
 Flea, Tick, and Heartworm Products Market | 2026-2036
Flea, Tick, and Heartworm Products Market Size, Share, and Industry Trends Forecast 2026-2036
Flea, Tick, and Heartworm Products Market Analysis
Veterinary clinics is bifurcating the Flea, Tick, and Heartworm Products landscape as pet owners migrate from over-the-counter retail toward clinically supervised parasite protocols. Zoetis anchors this shift through its prescription-dominant portfolio and direct veterinary channel control. Elanco leverages its R&D intensity in combination therapies to sustain premium positioning. Boehringer Ingelheim International GmbH dominates the oral medication segment with manufacturing scale that few competitors match.
Flea, tick, and heartworm products comprise parasiticide formulations—typically containing isoxazolines, macrocyclic lactones, or pyrethroids—delivered via topical, oral, or collar systems to prevent or eliminate ectoparasites and helminths in companion animals. These products function through systemic absorption or surface distribution, with efficacy thresholds measured in weeks of sustained protection against reinfestation. Oral medications command the fastest growth trajectory as pet owners prioritize convenience and reduced human contact with neurotoxic actives. Topical treatments retain margin concentration among price-sensitive segments despite regulatory pressure on residue profiles. Collars occupy a shrinking but defensible niche in multi-pet and shelter environments where cost-per-animal drives procurement decisions.
The EPA governs pesticide registration and label claims for topical and spray formulations in the United States, while the FDA Center for Veterinary Medicine asserts jurisdiction over orally administered parasiticides as animal drugs. This dual-track oversight elevates compliance costs and fragments product development timelines across delivery modes. The EU REACH framework and F-Gas Regulation constrain active ingredient sourcing for manufacturers distributing in Europe. Stakeholders must monitor evolving residue limits and prescription-status reclassifications that could abruptly reshape channel economics.
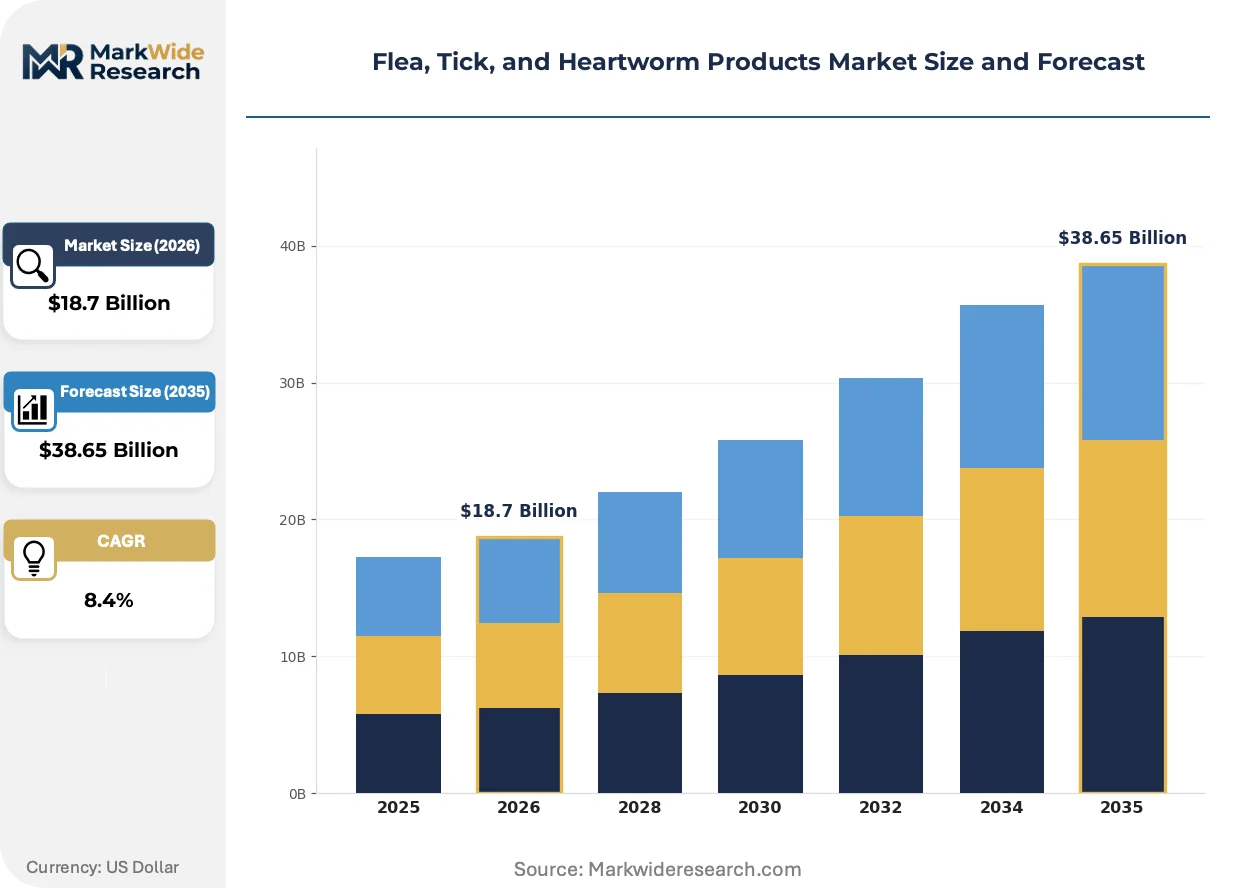
Market Dynamics
The veterinary clinic channel is consolidating purchasing power as pet owners abandon retail self-selection for supervised parasite protocols, compressing margin structures for manufacturers dependent on over-the-counter distribution.
Growth Catalysts
- EPA efficacy-labeling mandates:Reformulation requirements for topical treatments are accelerating R&D investment in next-generation actives with cleaner residue profiles.
- Preventive-care insurance penetration:Reimbursement frameworks in the United States are reducing out-of-pocket cost barriers for prescription-grade combination therapies.
- Isoxazoline chemistry platforms:Extended-duration oral formulations are capturing share from monthly dosing regimens through improved pet owner compliance.
Market Restraints
- Active ingredient concentration:Three suppliers control the majority of macrocyclic lactone precursor supply, creating vulnerability to agricultural chemical pricing cycles.
- FDA Center for Veterinary Medicine review timelines:New oral parasiticide approvals average 18-24 months, delaying product launches and compressing effective patent life.
- Neurotoxicity concerns:Adverse event reporting systems have flagged seizure risks in isoxazoline-class products, triggering label warnings that dampen uptake in seizure-prone breeds.
Strategic Opportunities
- Telemedicine-enabled prescription fulfillment:Virtual veterinary platforms are opening clinic-channel access for rural and underserved pet owner populations previously restricted to retail.
- EU F-Gas Regulation compliance pathways:Manufacturers investing in non-fluorinated solvent systems for topical formulations will capture preferential positioning in European distribution.
- Shelter and rescue procurement centralization:Multi-year municipal contracts for high-volume oral dosing are creating defensible volume anchors for scaled manufacturers.
Industry Challenges
- Dual-track regulatory navigation:Product portfolios spanning topical and oral delivery modes require simultaneous EPA pesticide and FDA animal drug expertise, fragmenting compliance teams.
- Integration of pharmacovigilance systems:Manufacturers must reconcile FDA adverse event databases with EPA incident reporting, creating data architecture complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flea, Tick, and Heartworm Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Collars, Sprays Delivery Mode: Prescription, Over-the-Counter, Vets Clinics, Pet Stores End User: Pet Owners, Veterinary Clinics, Animal Shelters, Groomers Application: Prevention, Treatment, Control, Combination Therapy |
| Companies Covered | Elanco, Ceva, Zoetis, Sergeant's Pet Care Products, Inc., The Hartz Mountain Corporation, Merck and Co., Inc., Virbac, Inc., Promika, LLC, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flea, Tick, and Heartworm Products Market Emerging Trajectories
Formulation chemistry and channel economics are diverging sharply as convenience-driven pet owners reject residue-based treatments while regulators tighten environmental safety thresholds.
Extended-release injectable depots containing moxidectin are supplanting monthly oral tablets in the working dog and breeding kennel segments, where handler compliance is operationally critical. Large-animal veterinarians with companion animal satellite practices are adopting these platforms fastest, compressing the addressable market for conventional monthly SKUs and forcing reformulation of entire product lines.
REACH framework amendments in Europe are restricting perfluorinated compound use in topical vehicle formulations, compelling manufacturers to validate alternative solvent systems. The regulatory pressure is most acute for spray and spot-on products, with several suppliers accelerating biodegradability testing to maintain CE marking eligibility.
Subscription-based auto-ship models through veterinary practice management software are displacing episodic clinic counter purchases. The shift is most visible in suburban United States markets with high dual-income household density, where convenience premiums outweigh price sensitivity and loyalty program lock-in reduces annual switching.
Flea, Tick, and Heartworm Products Market Segmentation
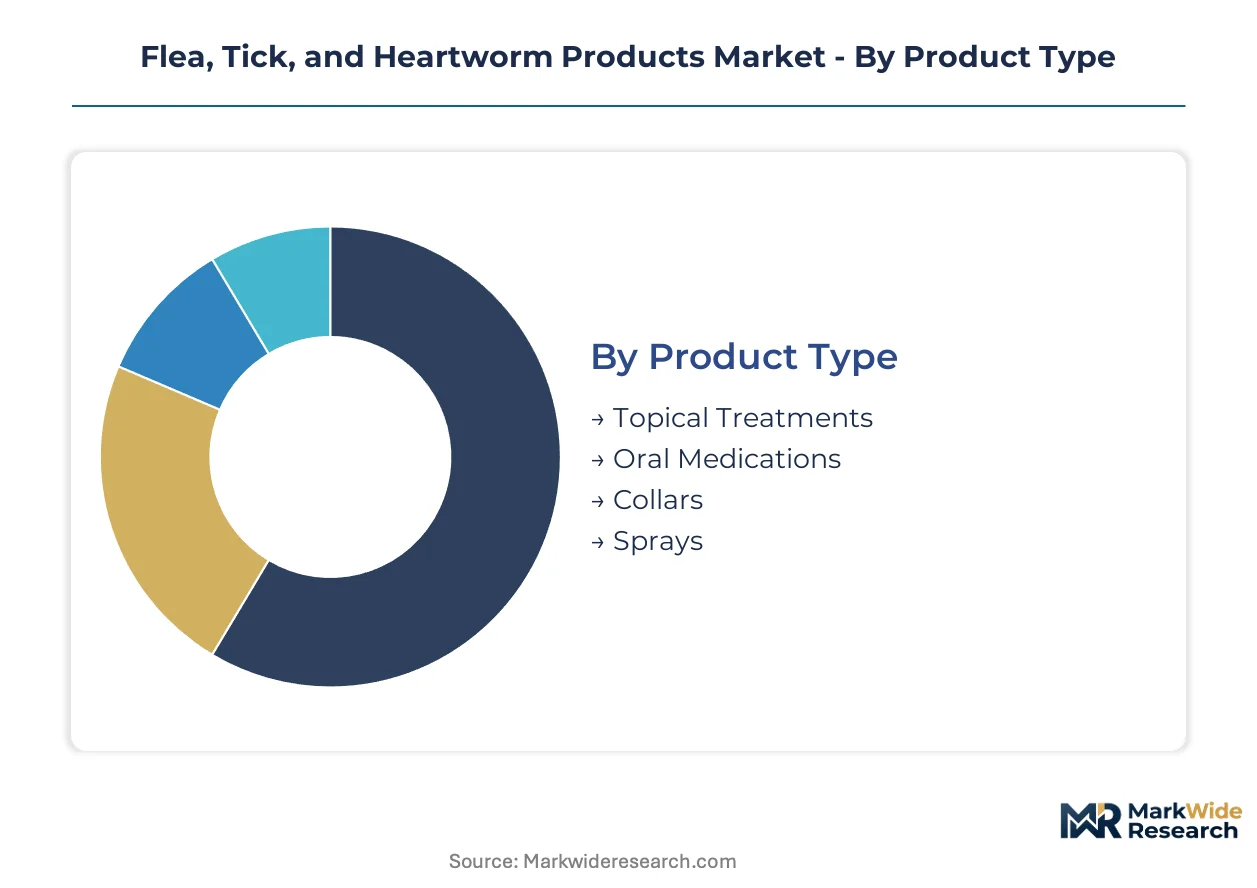
Parasiticide manufacturers face divergent margin pressures across product architectures, with convenience-driven pet owners abandoning residue-based formats while regulatory scrutiny intensifies on neurotoxic actives. Channel bifurcation between prescription veterinary protocols and retail self-medication creates distinct competitive arenas requiring separate formulation and compliance strategies.
Product Type:
Oral medications exert the strongest substitution pressure on legacy formats as pet owners reject topical residue exposure and handling complexity.
- Oral Medications:Isoxazoline and macrocyclic lactone tablets or chewables deliver systemic parasiticide distribution through gastrointestinal absorption. United States demand concentrates among insured pet owners seeking extended-duration protection with reduced human contact. FDA Center for Veterinary Medicine oversight elevates compliance costs but sustains premium pricing power through prescription exclusivity.
- Topical Treatments:Spot-on and pour-on formulations containing pyrethroids or permethrins distribute actives across the integumentary system. Price-sensitive segments in rural United States markets retain loyalty despite EPA-mandated reformulation requirements for cleaner residue profiles. Efficacy-labeling tightening compresses margin structures for manufacturers dependent on over-the-counter distribution.
- Collars:Polymer matrix devices releasing active compounds through contact diffusion serve multi-pet and shelter procurement where cost-per-animal dominates.
- Sprays:Aqueous or aerosol formulations provide immediate knockdown for acute infestations in grooming and kennel environments.
Topical treatments anchor the volume base while oral medications gain share at the steepest rate.
Delivery Mode:
Channel economics stratify sharply around supervision requirements and reimbursement eligibility.
- Vets Clinics:Professionally administered or dispensed products under veterinary supervision carry prescription status with insurance reimbursement pathways. United States suburban markets with high preventive-care insurance penetration sustain premium uptake through practice management software integration and auto-ship subscription models.
- Prescription:FDA-regulated oral parasiticides requiring veterinary authorization command the highest price tiers and strongest compliance-driven repurchase rates.
- Over-the-Counter:EPA-registered topical and collar products accessible without professional supervision compete on shelf price and brand recognition.
- Pet Stores:Retail self-selection environments concentrate price competition and promotional intensity for established active ingredient platforms.
Vets clinics capture margin concentration while telemedicine-enabled prescription fulfillment expands geographic reach fastest.
End User:
Procurement authority is centralizing toward institutional buyers with volume leverage and multi-year contract capacity.
- Veterinary Clinics:Clinical decision-makers drive prescription protocol adoption through diagnostic confirmation and treatment supervision. United States corporate practice chains consolidate purchasing power, compressing manufacturer margin structures in exchange for formulary placement guarantees.
- Pet Owners:Individual purchasers select between convenience premiums and price sensitivity based on household income and insurance status.
- Animal Shelters:Municipal and non-profit procurement operations prioritize cost-per-dose and handler safety in high-volume intake environments.
- Groomers:Service providers administer acute treatments during routine care appointments with limited diagnostic capability.
Veterinary clinics control premium positioning while animal shelters drive volume scaling through centralized procurement.
Application:
Clinical outcomes measurement is shifting from episodic treatment to sustained prevention metrics.
- Prevention:Prophylactic protocols administered before parasite exposure establish baseline protection through scheduled dosing regimens. United States insured pet populations sustain year-round compliance with monthly or extended-duration formulations.
- Combination Therapy:Multi-parasite coverage integrating flea, tick, and heartworm actives in single-dose administration reduces pet owner complexity. FDA review timelines for novel combinations average 18-24 months, delaying competitive entry.
- Treatment:Therapeutic intervention following confirmed infestation addresses acute parasitic burden with higher active concentration.
- Control:Population-level management in shelter and kennel environments suppresses environmental reservoir transmission.
Prevention commands the revenue base while combination therapy expands at the most rapid clip.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers supply veterinary clinics across Canada and Mexico through integrated North American distribution networks. European producers route oral parasiticide formulations through Rotterdam and Hamburg ports to Middle Eastern and Asian markets. Asian contract manufacturers concentrate active ingredient synthesis for global pharmaceutical companies.
United States
Veterinary clinic chains in Texas and Florida drive prescription protocol adoption through corporate formulary standardization. EPA efficacy-labeling mandates for topical treatments force reformulation investments among domestic manufacturers. Kansas City and Research Triangle Park host R&D operations where Zoetis and Elanco develop next-generation isoxazoline platforms.
Germany
REACH framework amendments constrain perfluorinated solvent use in topical vehicle formulations, compelling biodegradability validation. Bavaria-based Boehringer Ingelheim leverages manufacturing scale to supply oral medication segments across European Union markets. Frankfurt Rhine-Main logistics clusters expedite distribution to veterinary wholesalers in France and Benelux countries.
United Kingdom
Pet insurance penetration in Greater London and Southeast England sustains premium uptake for combination therapies through veterinary practice management systems. The Veterinary Medicines Directorate enforces pharmacovigilance reporting requirements that align with FDA adverse event databases. Cambridge life sciences corridor attracts parasiticide formulation research from multinational animal health companies.
Brazil
São Paulo and Rio de Janeiro metropolitan areas concentrate veterinary clinic expansion as middle-class pet ownership rises. ANVISA regulates animal drug registrations with review timelines that lag FDA Center for Veterinary Medicine standards. Minas Gerais agricultural chemical producers supply macrocyclic lactone precursors to regional formulation facilities.
Australia
TGA oversight of veterinary medicines maintains alignment with FDA and EMA standards, facilitating parallel registration strategies. Sydney and Melbourne veterinary corporate groups consolidate purchasing power through multi-year procurement contracts. Queensland and New South Wales shelter operations drive volume demand for cost-per-dose oral formulations in high-intake environments.
Flea, Tick, and Heartworm Products Market Vendor Landscape
Listed leaders compete with private specialists across prescription exclusivity and retail accessibility dimensions. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with FDA-regulated oral portfolios, mid-scale private manufacturers serving EPA-registered topical segments, and regional specialists capturing municipal shelter contracts. Dominant competitive moves include backward integration into active ingredient synthesis and telemedicine platform partnerships that expand clinic-channel geographic reach.
Among diversified animal health conglomerates, Zoetis and Elanco exemplify prescription-dominant archetypes with veterinary channel control, while Boehringer Ingelheim International GmbH anchors the oral medication segment through manufacturing scale. Virbac, Inc. and Ceva occupy positions within the mid-tier specialist category, with geographic origins reflecting French veterinary pharmaceutical heritage. Sergeant's Pet Care Products, Inc. and The Hartz Mountain Corporation represent private manufacturers concentrated in retail-accessible EPA-registered formulations.
| Leading Market Players |
|---|
| Elanco |
| Ceva |
| Zoetis |
| Sergeant's Pet Care Products, Inc. |
| The Hartz Mountain Corporation |
| Merck and Co., Inc. |
| Virbac, Inc. |
| Promika, LLC |
| Boehringer Ingelheim International GmbH |
| Others |
Supply Flow & Price Mechanics
Active ingredient synthesis capacity utilization in India and China directly determines cost floors for macrocyclic lactone precursors, concentrating pricing power among three agricultural chemical suppliers while compressing margins for formulation-dependent manufacturers. This scale concentration elevates price floors for oral parasiticides and amplifies volatility exposure when agricultural chemical pricing cycles shift.
Pricing Analysis
Next-generation isoxazoline oral formulations command 40-60% premiums over legacy monthly tablets, while prior-generation pyrethroid topicals face downward pressure from EPA-mandated reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates prescription-exclusive oral medications from over-the-counter topicals and shelter-procurement collars. Cost compression in the topical tier is intensifying because efficacy-labeling investments cannot be passed to price-sensitive rural buyers. Animal shelters exhibit highest price sensitivity due to cost-per-dose procurement mandates, while insured suburban pet owners show lowest sensitivity through reimbursement pathways.
Supply Chain Analysis
Strait of Malacca transit underwrites 70% of global isoxazoline active ingredient movement from Indian synthesis facilities to European formulation plants. Supply concentrates in India for macrocyclic lactone precursors, China for pyrethroid intermediates, and Germany for polymer matrix collar substrates. Raw material dependencies include agricultural chemical feedstocks, fluorinated solvent systems, and veterinary-grade polymer resins. Single-source vulnerability pervades the macrocyclic lactone precursor tier where three suppliers control majority capacity. Distribution runs through Rotterdam and Hamburg port clusters for European veterinary wholesalers, with integrated North American networks serving clinic chains from Kansas City distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isoxazoline chemistry platforms are disrupting legacy monthly dosing regimens, creating acquisition and partnership windows as FDA review timelines compress effective patent windows for first-movers.
For Market Incumbents: Shield prescription-channel exclusivity through backward integration into active ingredient synthesis, particularly for macrocyclic lactone precursors where supply concentration threatens margin stability. Deepen practice management software integration to lock in auto-ship subscription volumes before telemedicine platforms erode geographic control. The priority lever rests on captive supply of isoxazoline actives as agricultural chemical pricing cycles intensify. For New Entrants and Emerging Players: Telemedicine-enabled prescription fulfillment in rural United States markets represents the most penetrable white-space where corporate clinic chains have limited physical presence. Municipal shelter procurement centralization offers volume anchors with lower regulatory barriers than FDA oral parasiticide pathways. Target subscription-based auto-ship partnerships with independent veterinary platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors scaled manufacturers with FDA-approved oral portfolios and established pharmacovigilance infrastructure over topical-dependent private labels. Long-term viability hinges on isoxazoline patent cliff navigation and combination therapy pipeline depth. Watch FDA adverse event database trends for seizure-risk label expansion as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Active Ingredient Backward Integration | Captive supply of macrocyclic lactone precursors insulates margin structures from agricultural chemical pricing volatility. |
| Telemedicine Platform Partnership | Virtual veterinary authorization expands prescription-channel reach into rural markets previously restricted to retail. |
| Extended-Duration Formulation Launch | Three-month isoxazoline chewables capture compliance premiums from convenience-driven insured pet owners. |
| Non-Fluorinated Solvent Transition | REACH-compliant topical vehicles secure CE marking eligibility and European distribution continuity. |
| Shelter Procurement Contracting | Multi-year municipal agreements create defensible volume anchors with predictable offtake schedules. |
Methodological Framework
Cross-validation between regulatory filing analysis and veterinary practice management data anchors the qualitative findings on channel shift dynamics. Primary interviews with veterinary clinic procurement directors, animal shelter operations managers, EPA pesticide registration specialists, and pet insurance reimbursement officers combined with secondary validation from FDA Center for Veterinary Medicine submissions, EPA pesticide registration documents, state-level veterinary board records, and corporate animal health SEC filings. Bottom-up prescription volume modeling and top-down veterinary expenditure surveys triangulate market sizing.
Sensitivity analysis across regulatory approval timeline scenarios and agricultural chemical price volatility bands informs projection robustness. Segmentation dimensions modeled include product architecture, delivery mode channel classification, end-user procurement authority, and application protocol type, with regional regulatory cluster overlays. CAGRs derive from compounding annual prescription volume growth adjusted for insurance penetration curves and clinic channel consolidation rates. Forecast inputs incorporate isoxazoline patent expiration schedules and EPA reformulation compliance cost assumptions.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine review standards and EPA efficacy-labeling frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as isoxazoline adverse event reporting thresholds and REACH solvent restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Pet Toys Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Raw Pet Food Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Cat Mat Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Dog Biscuit Market
Pet Care Products
Dog Float Market
Pet Care Products
Cat Harness Market