
 US Automatic Content Recognition Market | 2026-2036
US Automatic Content Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
US Automatic Content Recognition Market Insights
California's technology corridor is tilting toward ACR infrastructure expansion as streaming penetration deepens. Roku Inc. leverages its proprietary Smart TV operating system to embed fingerprinting capabilities directly into household viewing hardware. Samsung Electronics America Inc. anchors its competitive stance through Tizen OS integration across millions of domestic television sets. Google LLC sustains audience measurement scale through Android TV and YouTube cross-platform data synthesis.
Automatic Content Recognition denotes computational systems that extract perceptual features from audio or video signals and match them against reference databases to identify content in real time, operating at millisecond latency thresholds essential for live broadcast synchronization. The technology serves advertisers seeking granular attribution and broadcasters requiring automated content compliance verification. Fingerprinting dominates deployment volumes due to its minimal preprocessing overhead and resistance to signal degradation, while watermarking commands premium positioning among studios demanding forensic-grade provenance tracking. Cloud-based deployment is accelerating fastest as broadcasters abandon capital-intensive on-premise server farms for elastic processing capacity.
The Federal Communications Commission governs broadcast spectrum allocation and cross-media ownership rules that determine ACR data collection boundaries, while the Federal Trade Commission scrutinizes consumer privacy disclosures under Section 5 unfair practice provisions. California's Consumer Privacy Act imposes additional consent-layer requirements on platforms capturing viewing behavior from state residents. Stakeholders must monitor emerging state-level biometric and behavioral privacy legislation that could fragment compliance obligations across jurisdictions.
Market Dynamics
The US Automatic Content Recognition Market is restructuring around cloud-native deployment architectures as broadcasters abandon on-premise infrastructure for elastic processing capacity. This shift compresses capital requirements while expanding real-time matching capabilities across streaming and linear television environments.
Growth Catalysts
- Streaming advertising attribution:Advertisers demand granular household-level measurement as connected TV inventory scales. ACR fingerprinting enables post-campaign verification without panel-based extrapolation.
- California Consumer Privacy Act compliance frameworks:Platforms investing in consent-layer infrastructure capture viewing data that competitors forfeit. First-movers build proprietary audience graphs.
- Live broadcast synchronization:Millisecond-latency content identification supports dynamic ad insertion during sports and news programming. Broadcasters deploy edge-computing nodes to reduce round-trip delays.
Market Restraints
- Reference database maintenance costs:Continuous ingestion of new content releases requires petabyte-scale storage expansion. Smaller vendors face margin compression against hyperscaler economies.
- Signal degradation in compressed streams:Aggressive video compression algorithms reduce fingerprinting accuracy. Watermarking alternatives impose encoding overhead that delays live distribution.
- FCC media ownership rule uncertainty:Pending revisions to cross-platform audience measurement standards create compliance planning paralysis. Platforms defer multi-year infrastructure commitments.
Strategic Opportunities
- Midwestern broadcast station consolidation:Regional station groups lack in-house ACR capabilities. Managed service providers capture long-term operational contracts with performance-based pricing.
- Biometric privacy legislation tailwinds:Illinois Biometric Information Privacy Act and emerging Texas equivalents create demand for privacy-preserving identification methods. Differential privacy techniques differentiate vendor offerings.
- Edge-AI and 5G broadcast convergence:Low-latency wireless distribution enables real-time ACR processing in stadium and venue environments. Sports leagues pilot personalized second-screen experiences.
Industry Challenges
- Cross-platform identity resolution:Fragmented device graphs across Smart TV OS, mobile, and desktop environments complicate household deduplication. Engineers with probabilistic matching expertise command premium compensation.
- Legacy cable headend integration:Quadrature amplitude modulation infrastructure lacks IP-native interfaces. Custom middleware development extends deployment timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automatic Content Recognition Market |
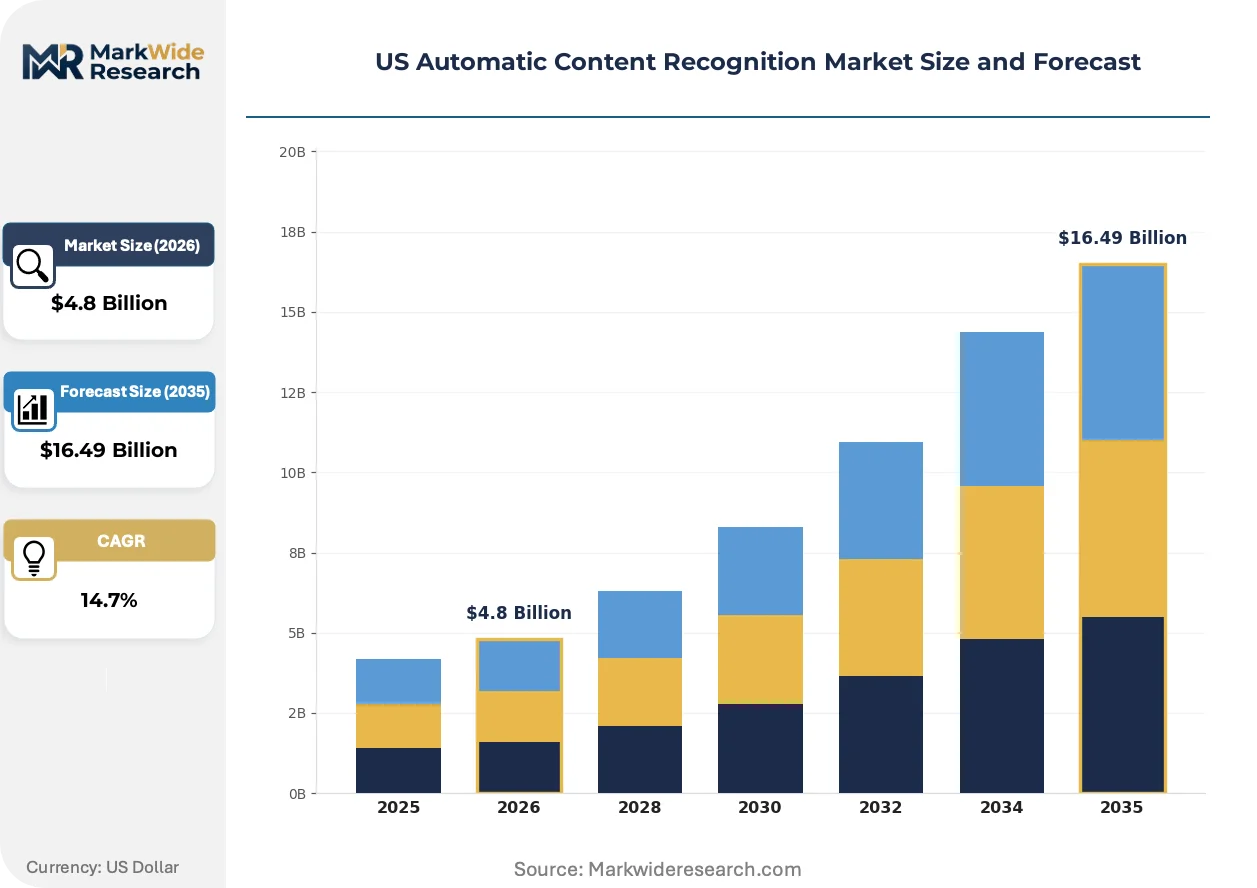
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.49 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprinting, Watermarking, Metadata Matching, Audio Recognition End User: Streaming Services, Broadcasters, Media Agencies, Advertisers Deployment: On-premise, Cloud-based, Hybrid, Mobile Application: Content Identification, Audience Measurement, Interactive Advertising, Media Monitoring |
| Companies Covered | Roku Inc., Samsung Electronics America Inc., Vizio Holding Corp., ACRCloud Technology Co., Ltd., Gracenote Inc., Google LLC, IBM Corporation, Audible Magic Corporation, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automatic Content Recognition Market Trends and Innovations
Cloud migration is compressing deployment timelines while expanding ACR accessibility to mid-market broadcasters previously excluded by capital constraints. Three convergent developments are reshaping competitive positioning.
Edge-based fingerprinting is hybridizing with centralized cloud matching to balance latency requirements against computational cost. Regional sports networks deploy local processing nodes for live game identification while offloading archival content matching to AWS and Azure. This architecture reduces per-match processing costs by eliminating redundant cross-country data transit.
The Federal Trade Commission's Section 5 enforcement against dark pattern interfaces is forcing disclosure redesigns across ACR-enabled platforms. Smart TV manufacturers must surface data collection practices during initial device setup rather than burying terms within multi-page agreements. California residents now encounter granular opt-in screens that segment viewing behavior collection from general device analytics.
Agency holding companies are consolidating ACR measurement contracts around fewer verification vendors. Independent media buyers lose negotiating leverage as procurement authority concentrates with WPP, Omnicom, and Publicis centralized data platforms. This concentration is most visible in upfront television negotiations where guaranteed audience delivery terms now specify ACR-verified impressions rather than traditional Nielsen guarantees.
US Automatic Content Recognition Market Segmentation
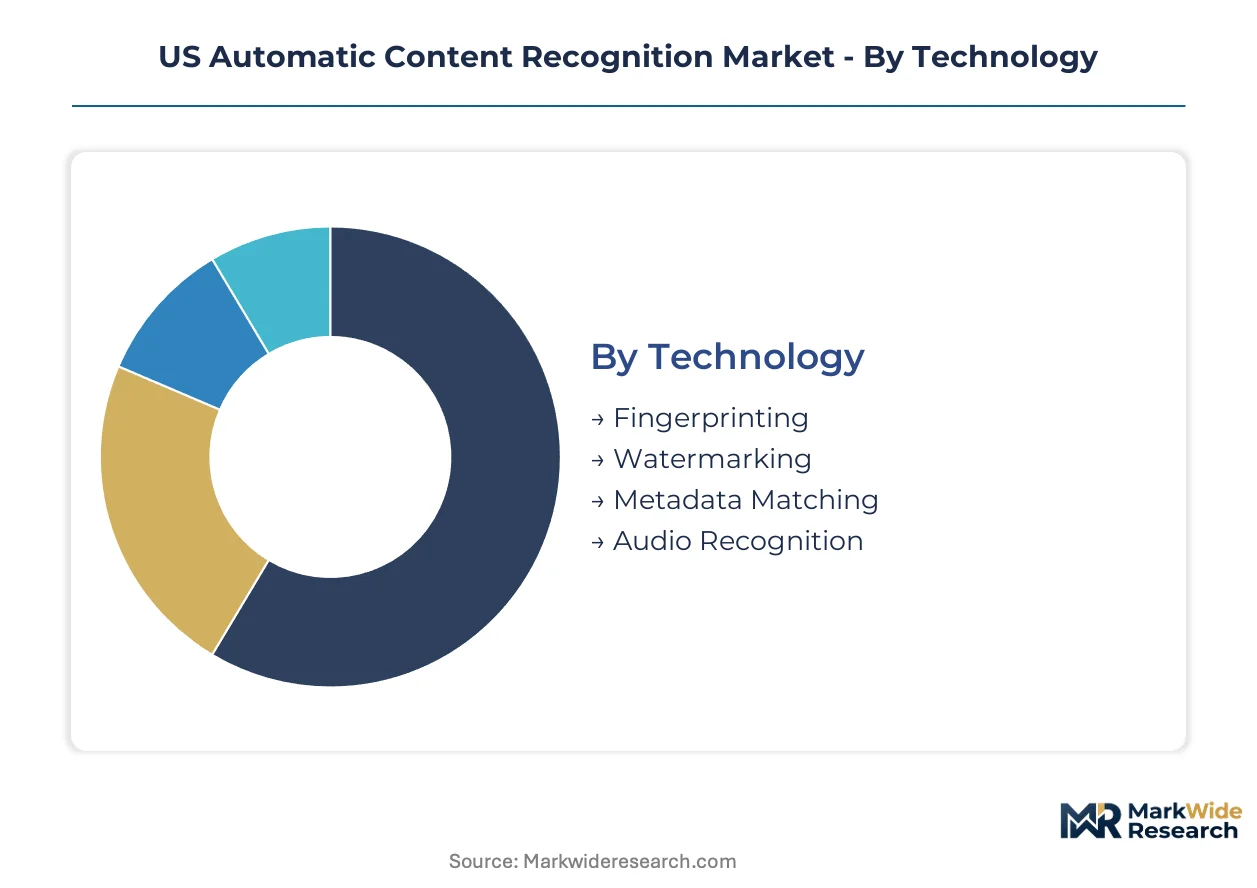
ACR segmentation reveals divergent technology maturities and deployment economics across the US television ecosystem. Streaming platforms and broadcasters select architectures based on latency tolerance, capital constraints, and FCC compliance exposure. Each dimension carries distinct vendor concentration patterns and margin structures.
Technology:
Mature extraction methods dominate transaction volumes while emerging approaches capture innovation investment.
- Fingerprinting:Perceptual hashing algorithms generate compact signatures from audio-visual streams without modifying source content. Broadcasters in Los Angeles and New York deploy fingerprinting for live sports ad insertion where encoding delays are unacceptable. The method's resistance to compression artifacts sustains its position across cable and satellite distribution.
- Watermarking:Imperceptible data embedding at the encoding stage enables forensic content provenance tracking. Major studios demand watermarking for premium release windows to combat piracy leakage through the supply chain. The technique commands higher unit economics due to encoder integration complexity and studio certification requirements.
- Metadata Matching:Electronic program guide alignment with content fingerprints provides contextual enrichment for audience analytics platforms.
- Audio Recognition:Spectral analysis of soundtracks identifies content when video signals are degraded or unavailable.
Fingerprinting retains volume leadership; watermarking holds the steepest expansion curve.
End User:
Customer type determines pricing power and contract duration across the revenue base.
- Streaming Services:Subscription and ad-supported platforms require real-time content identification to enable dynamic ad insertion and personalized recommendation engines. Netflix, Hulu, and Amazon Prime Video operate proprietary ACR stacks while smaller services license third-party identification APIs. California-based engineering teams concentrate development investment in cross-device identity resolution.
- Broadcasters:Local television stations and network affiliates leverage ACR for automated content compliance and audience measurement verification. Sinclair Broadcast Group and Nexstar Media Group pilot edge-based processing to reduce cloud egress costs during high-viewership events.
- Media Agencies:Omnicom and WPP holding companies consolidate measurement contracts around ACR-verified impression guarantees.
- Advertisers:Direct brand investment in ACR infrastructure remains concentrated among Fortune 500 consumer packaged goods marketers.
Streaming services command the largest deployment scale; broadcasters represent the most price-sensitive procurement segment.
Deployment:
Infrastructure location choices reflect latency requirements versus operational flexibility tradeoffs.
- Cloud-based:Elastic compute capacity from AWS, Google Cloud, and Microsoft Azure enables broadcasters to match processing resources against variable viewership patterns. Regional sports networks offload archival content matching to centralized data centers while maintaining local nodes for live programming. The model converts capital expenditure to operational spending with consumption-based metering.
- Hybrid:Split architectures process time-sensitive identification at edge locations while delegating reference database queries to cloud backends. NBCUniversal and CBS deploy hybrid configurations to balance millisecond-latency requirements against petabyte-scale storage economics.
- On-premise:Legacy broadcast facilities maintain captive server farms where regulatory data sovereignty concerns predominate.
- Mobile:Smartphone-embedded ACR enables second-screen synchronization and portable content identification applications.
Cloud-based deployment captures the majority of new contract value; hybrid architectures are climbing the fastest among multi-platform content distributors.
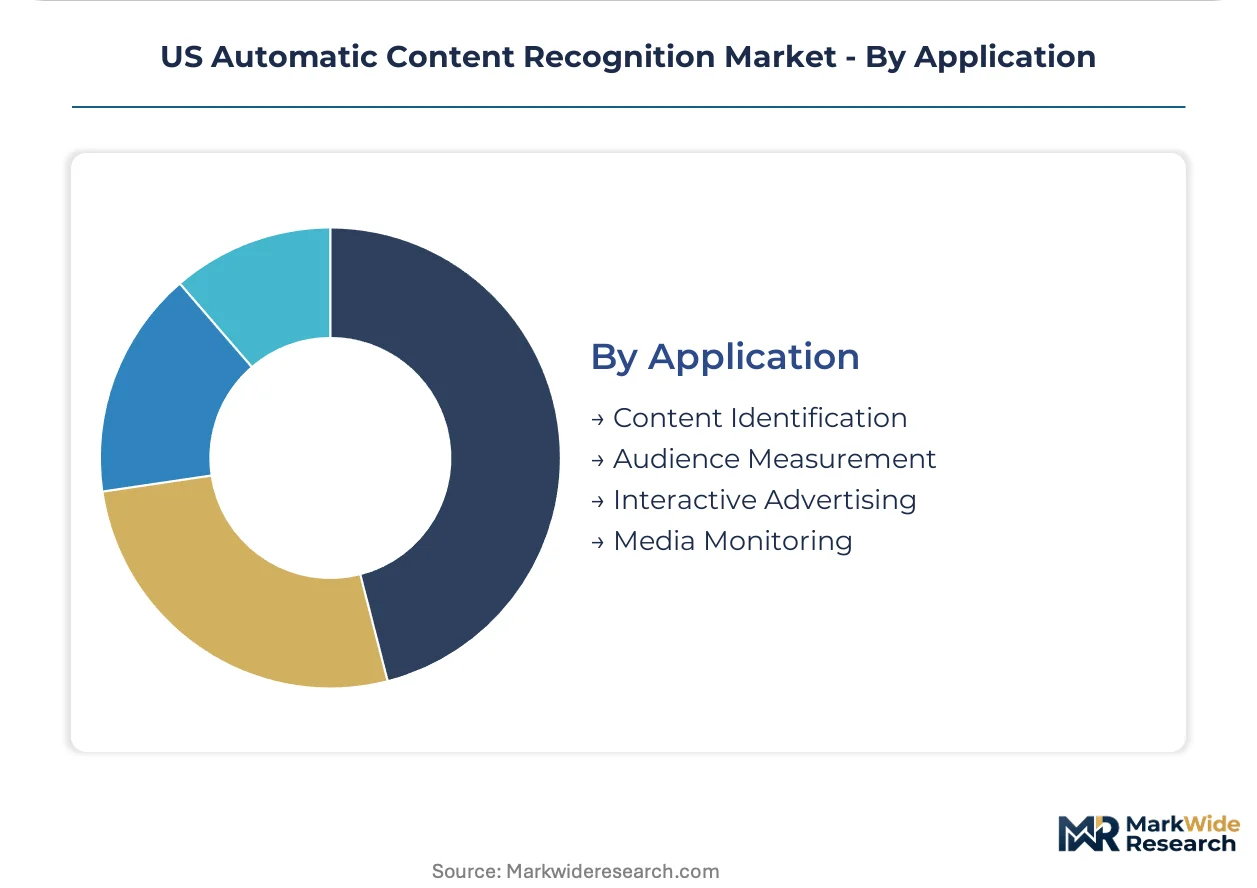
Application:
Use case specialization drives feature differentiation and integration depth requirements.
- Content Identification:Real-time matching against reference databases enables automated programming verification and copyright enforcement. YouTube's Content ID system processes user uploads against studio fingerprint libraries at scale. The application demands sub-second latency thresholds to support live broadcast workflows.
- Audience Measurement:Household-level viewing data aggregation replaces panel-based extrapolation with census-level impression counting. Nielsen and Comscore compete to displace traditional diary methods with ACR-derived metrics in upfront negotiations.
- Interactive Advertising:Second-screen engagement and personalized overlay insertion create incremental inventory for connected TV platforms.
- Media Monitoring:Brand safety verification and competitive intelligence gathering serve public relations and marketing analytics functions.
Content identification anchors the installed base; audience measurement is gaining share fastest as currency standardization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Communications Commission's spectrum allocation and media ownership frameworks anchor demand concentration in California and New York media corridors. State-level biometric privacy laws fragment compliance obligations across jurisdictions.
California
Silicon Valley engineering clusters and Los Angeles studio complexes drive ACR infrastructure investment. The California Consumer Privacy Act mandates granular consent layers for viewing behavior collection. San Francisco Bay Area technology developers embed fingerprinting capabilities directly into streaming hardware and smart television operating systems.
New York
Manhattan-based media agencies consolidate measurement contracts around ACR-verified impression guarantees. The state's biometric privacy legislation proposals create uncertainty for facial recognition-enabled content identification. Brooklyn and Queens broadcast facilities pilot hybrid cloud-edge architectures for live sports synchronization.
Texas
Dallas-Fort Worth regional sports networks deploy edge-computing nodes to reduce latency during high-viewership events. Emerging state privacy legislation mirrors Illinois biometric protections. Austin technology corridors attract ACR software development talent from California migration patterns.
Illinois
Chicago broadcast station groups lack in-house ACR capabilities and contract managed service providers. The Biometric Information Privacy Act creates demand for privacy-preserving identification methods. Regional advertising markets in the Midwest lag coastal deployment density but show accelerating adoption curves.
Washington
Seattle cloud infrastructure providers supply elastic processing capacity to national broadcasters. State consumer protection frameworks supplement federal FTC Section 5 enforcement. Pacific Northwest data centers host reference databases for fingerprint matching at petabyte scale.
US Automatic Content Recognition Market Competitive Landscape
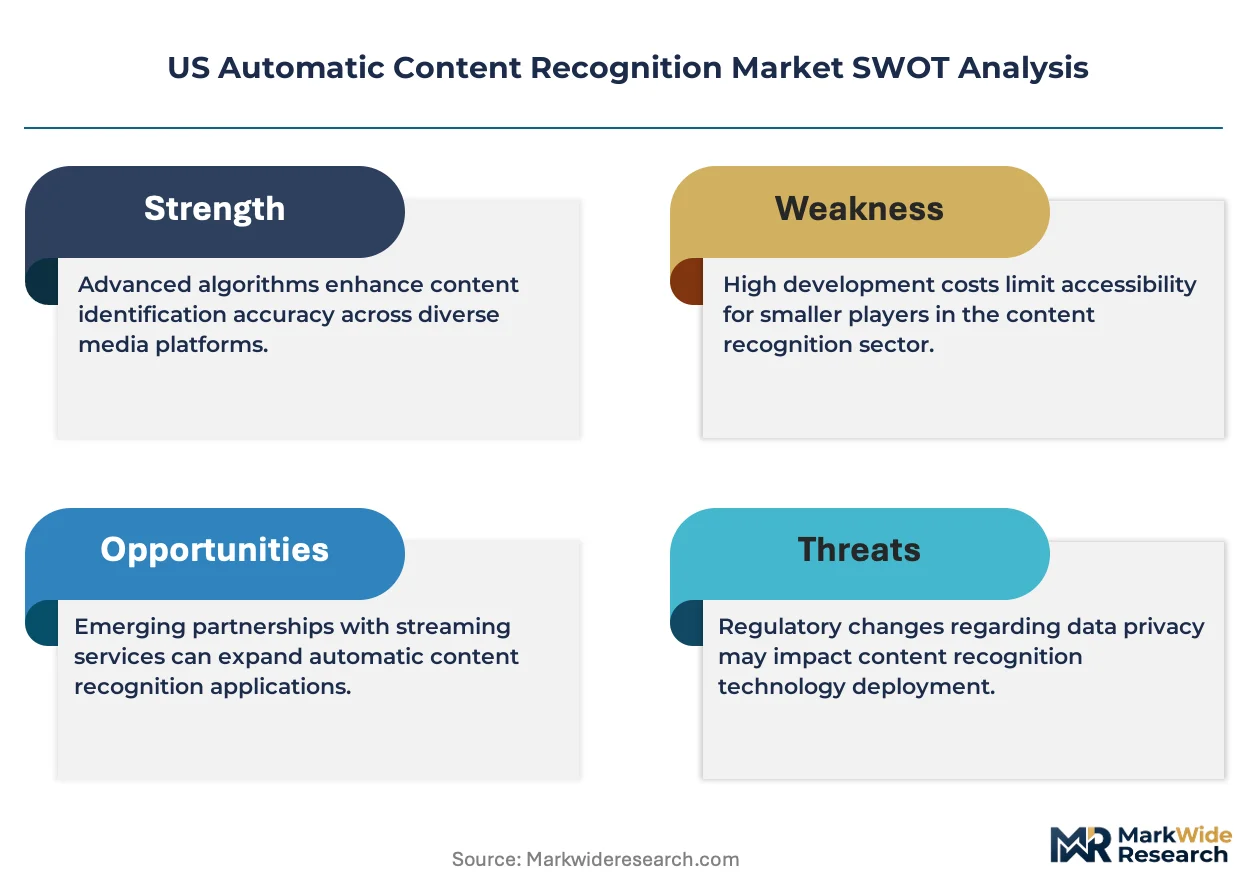
Capability concentration sits with one tier; scale advantage sits with another. The US Automatic Content Recognition Market structures around three distinct competitive archetypes: smart TV operating system vendors, cloud infrastructure providers, and specialized identification technology developers. Consolidation pressures favor platforms with captive device distribution. Strategic moves center on vertical integration into hardware-software stacks and exclusive data partnership arrangements with major studios.
Within the smart TV platform tier, Roku Inc., Samsung Electronics America Inc., and Google LLC occupy positions defined by operating system penetration and household data access. Roku exemplifies the streaming-native archetype through proprietary hardware-software integration. Samsung represents the consumer electronics incumbent leveraging manufacturing scale. Google anchors the cross-platform data synthesis position through Android TV and YouTube ecosystem convergence.
| Leading Market Players |
|---|
| Roku Inc. |
| Samsung Electronics America Inc. |
| Vizio Holding Corp. |
| ACRCloud Technology Co., Ltd. |
| Gracenote Inc. |
| Google LLC |
| IBM Corporation |
| Audible Magic Corporation |
| Microsoft Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taiwan Semiconductor Manufacturing Company for neural processing units concentrates pricing power among foundry operators and compresses margin flexibility across ACR hardware tiers. This chokepoint forces vendors to absorb silicon cost volatility through service-layer markups while reshaping procurement strategies toward multi-source qualification programs.
Pricing Analysis
Coastal California commands 15-20% premiums over Midwestern broadcast station deployments for equivalent ACR functionality. Pricing stratifies across premium watermarking certification, standard fingerprinting SaaS tiers, and economy API-per-call arrangements for mid-market streamers. Cost compression in the standard tier is intensifying because hyperscalers bundle identification services with cloud storage commitments. Local television affiliates exhibit highest price sensitivity; major streaming platforms leverage volume scale for customized enterprise licensing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for edge-computing hardware and reference database storage infrastructure. Taiwan, South Korea, and the United States anchor semiconductor supply for neural processing engines. Raw material dependencies include high-bandwidth memory modules, specialized image sensors, and rare-earth magnet components for server cooling systems. Distribution runs through direct OEM partnerships with smart TV manufacturers and managed service provider channels for broadcast station groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ACR infrastructure represents a service-attach opportunity where recurring cloud processing contracts and compliance monitoring subscriptions expand faster than one-time hardware licensing. Managed service revenue layers for regional broadcasters now outpace standalone software sales.
For Market Incumbents: Harden reference database exclusivity through exclusive content fingerprinting contracts with major studios. Expand edge-computing node deployment across secondary US markets to preempt managed service competitors. Vertical integration into smart TV operating systems remains critical as Roku and Samsung tighten hardware-software control. For New Entrants and Emerging Players: Establish a beachhead in Midwestern broadcast station consolidation where Sinclair and Nexstar affiliates lack in-house ACR engineering. Target Illinois and Ohio station groups with privacy-compliant managed service offerings. A go-to-market angle through differential privacy certification differentiates against coastal incumbents facing California Consumer Privacy Act complexity. For Investors and Strategic Acquirers: FCC media ownership rule revisions reshape the acquisition landscape by determining which platforms can monetize cross-station audience data at scale. Long-term viability favors vendors with captive device distribution and cloud infrastructure partnerships rather than pure-play identification technology developers. The signal to watch is state-level biometric privacy legislation passage rates as a demand catalyst for privacy-preserving methods.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | AWS and Azure consumption-based metering converts broadcaster capital expenditure to operational flexibility. |
| Edge-AI Hardware Integration | NVIDIA and Qualcomm neural processing units enable millisecond-latency fingerprinting at local broadcast nodes. |
| Privacy Certification Investment | California Consumer Privacy Act compliance frameworks differentiate vendors in consent-layer infrastructure. |
| Studio Data Partnership | Exclusive fingerprinting contracts with Warner Bros. Discovery and Paramount Global lock reference database content. |
| Regional Service Provider Acquisition | Midwestern broadcast station groups lack in-house ACR capabilities and represent recurring revenue capture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC rulemaking dockets, SEC 10-K filings from smart TV manufacturers, and cloud infrastructure capex disclosures. Primary interviews engaged platform engineering directors at streaming services, broadcast technology officers at regional station groups, and privacy compliance leads at advertising technology vendors. Secondary validation drew from Nielsen measurement methodology white papers, Consumer Privacy Act enforcement records, and patent filings for perceptual hashing algorithms. Bottom-up deployment counts triangulate against top-down advertising spend attribution estimates.
Forecast inputs span technology type segmentation, deployment model migration curves, and end-user procurement patterns across the projection horizon. The analytical framework models fingerprinting versus watermarking adoption, cloud versus hybrid infrastructure splits, and streaming service versus broadcaster demand profiles. CAGRs derive from elasticity-adjusted deployment trajectories and service pricing trend analysis. Industry-specific inputs include FCC media ownership rule revision probabilities and state-level biometric privacy legislation passage timelines.
Sensitivities concentrate around FCC cross-platform measurement standard delays and hyperscaler bundling strategies that compress standalone vendor pricing. Forecasts reflect assumptions regarding cloud migration velocity and studio content release window patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
North America Webtoons Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Music Rights Management Market
Digital Media
Social TV Market
Digital Media
Art App Market
Digital Media
ACGN Subculture Market
Digital Media
Wedding Photography Market
Digital Media
Manga Market
Digital Media
Video Wall Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Mobile Entertainment Market
Digital Media
Stock Music Software Market
Digital Media
Media Coding Service Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market