
 Drone Wedding Photography Market | 2026-2036
Drone Wedding Photography Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Wedding Photography Market Insights
China's Shenzhen manufacturing corridor is reconfiguring global supply chains for compact aerial imaging platforms, with DJI Innovations leveraging integrated gimbal-stabilized camera systems to sustain technology leadership. SKYKAM Ltd anchors premium service positioning across British heritage estates, while ProAerial Media LLC competes aggressively on FAA-certified operator networks throughout the southeastern United States. Shenzhen Pigeon Aerial Film and Television Co., Ltd. dominates Greater China's wedding cinematography segment through direct-to-consumer booking platforms.
Drone wedding photography deploys unmanned aerial vehicles equipped with stabilized high-resolution cameras to capture cinematic footage and still imagery of matrimonial events, typically operating at altitudes below 400 feet with 4K or higher resolution sensors and three-axis gimbal stabilization for broadcast-grade output. Multi-rotor platforms lead service deployment due to vertical takeoff precision and hover stability in confined venue airspace, while aerial cinematography commands premium pricing as couples prioritize cinematic highlight reels over static documentation. Ceremony coverage represents the most mature service tier with standardized deliverables, whereas post-production editing increasingly differentiates studios through color grading and soundtrack integration.
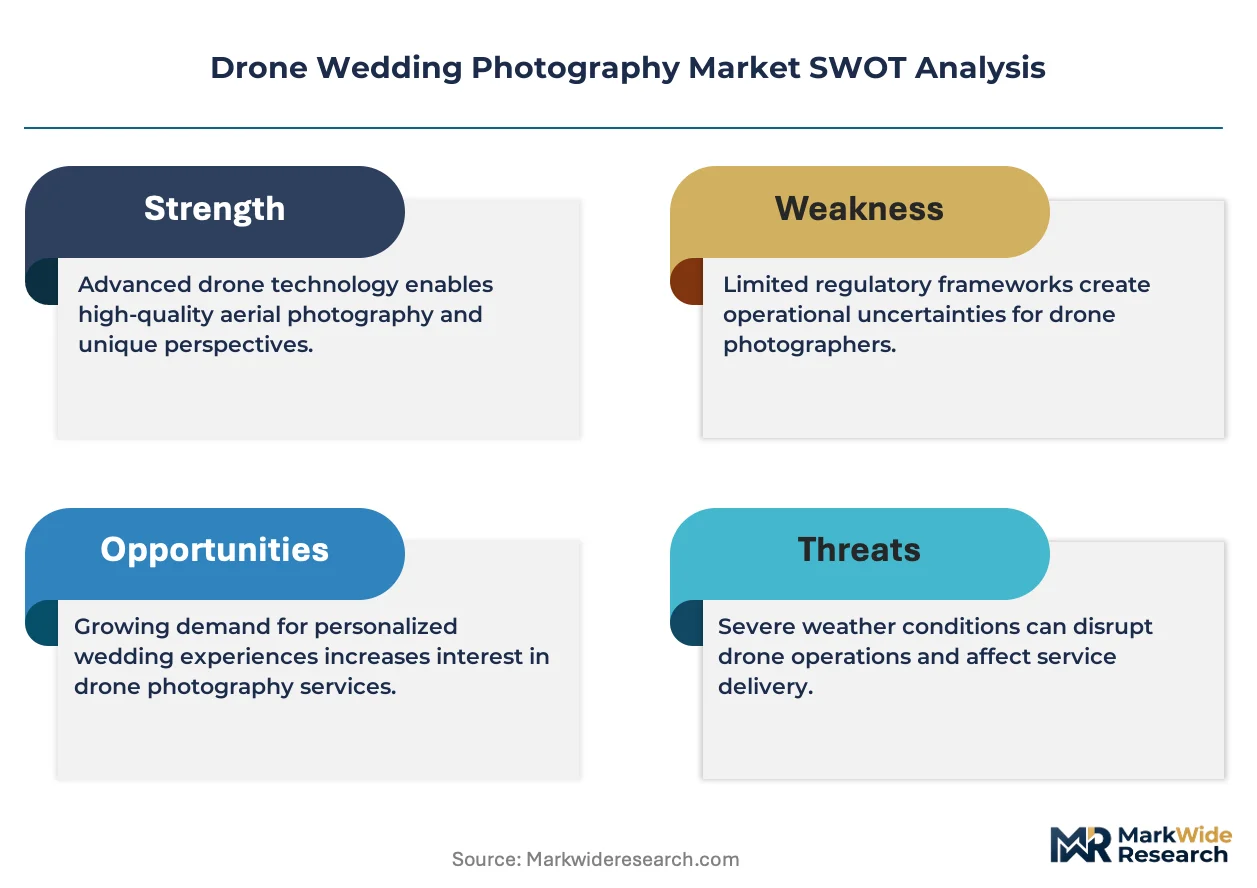
FAA Part 107 mandates commercial pilot certification and operational waivers for restricted airspace, directly constraining vendor eligibility and insurance underwriting across the United States. EASA's open and specific category frameworks under EU Regulation 2019/947 govern altitude limits, remote identification, and operator competency across European wedding destinations. India's Directorate General of Civil Aviation enforces No Permission-No Takeoff protocols and geo-fencing near heritage monuments, reshaping where aerial sequences can legally occur. Stakeholders must monitor evolving national drone frameworks, insurance liability evolution, and real-time airspace management integration as regulatory complexity becomes a primary competitive filter.
Market Dynamics
Regulatory certification mandates are fragmenting vendor eligibility across jurisdictions, elevating operator professionalism while compressing margins for uncertified providers who cannot access restricted airspace near heritage venues or metropolitan centers.
Growth Catalysts
- EASA Open Category Framework:Standardized altitude limits and remote identification requirements across European wedding destinations reduce compliance friction for cross-border operators.
- 4K Gimbal Stabilization:Three-axis mechanical stabilization systems deliver broadcast-grade footage without manned helicopter costs, expanding addressable demand from luxury tier to upper-middle market segments.
- India's Heritage Circuit:DGCA-approved drone zones near Rajasthan forts and Kerala backwaters create legally sanctioned content backdrops for cinematic pre-wedding sequences.
Market Restraints
- Li-ion Battery Supply Concentration:Cell production clusters in China's Guangdong province expose operators to raw material volatility and export control disruptions.
- FAA Part 107 Waivers:Night operation and altitude exemptions require 90-day federal review timelines, constraining last-minute booking fulfillment.
- Manned Aerial Cinematography:Helicopter operators in Dubai and Monaco compete on reliability in high-wind coastal conditions where multi-rotor platforms face operational limits.
Strategic Opportunities
- Southeast Asia's Resort Corridor:Vietnam's Da Nang and Thailand's Phuket lack established aerial cinematography vendors despite surging destination wedding volumes.
- AI-Assisted Editing Convergence:Automated color grading and soundtrack synchronization reduce post-production labor intensity for high-volume studios.
- Direct-to-Consumer Booking Platforms:Mobile-first reservation systems bypass traditional wedding planner intermediaries, capturing margin previously allocated to referral fees.
Industry Challenges
- FAA Remote Pilot Certification Pipeline:Practical test scheduling backlogs extend operator onboarding to 8-12 weeks, throttling fleet expansion timelines.
- Real-Time Airspace Management Integration:LAANC authorization systems require API compatibility investments that strain small-studio technical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Wedding Photography Market |
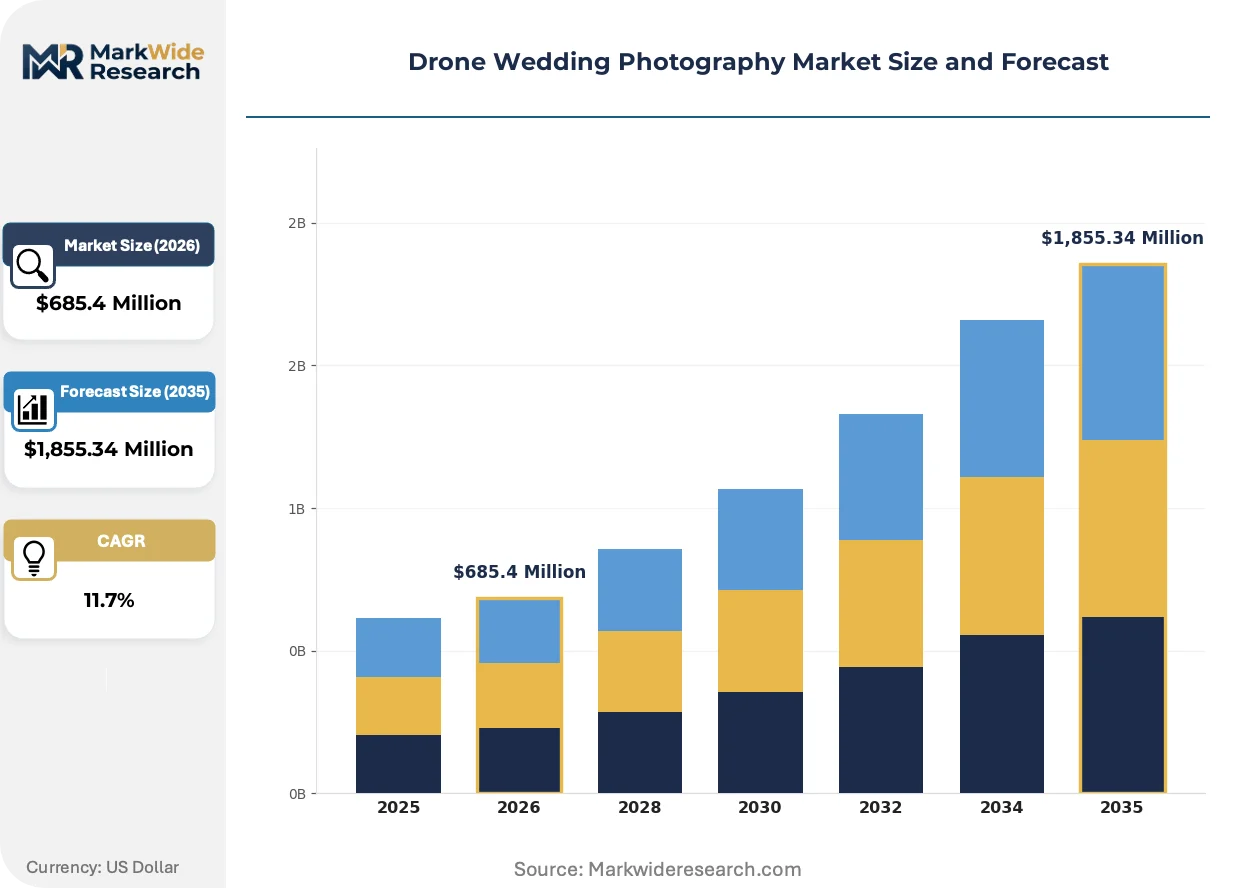
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drone Type: Fixed-Wing, Multi-Rotor, Hybrid, Single Rotor Service Type: Pre-Wedding Shoots, Ceremony Coverage, Reception Filming, Aerial Cinematography, Post-Production Editing End User: Professional Photographers, Event Planners, Wedding Venues, Couples, Media Companies Deployment Environment: Outdoor Gardens, Indoor Halls, Beach Locations, Heritage Sites, Rooftop Venues |
| Companies Covered | Airborne Visuals, SKYKAM Ltd, Phometo, The Wedding Photo Company, ProAerial Media LLC, Drone Pro Media, Shenzhen Pigeon Aerial Film and Television Co., Ltd., DJI Innovations, AirVuz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Wedding Photography Market Trends and Innovations
Autonomous flight pathing and real-time obstacle avoidance are compressing the skill threshold for cinematic capture, enabling boutique studios to compete with established aerial cinematography houses on output quality.
Dual-frequency RTK-GNSS positioning modules are delivering centimeter-level hover accuracy in GPS-denied environments such as canyon venues and dense urban canyons. Boutique operators in Santorini and Amalfi are adopting these systems to execute precision orbiting shots around cliffside chapels. Manual piloting expertise is rendering obsolete as automated waypoint execution standardizes complex maneuver reproducibility.
EU Regulation 2019/947 mandates remote identification broadcast for all aerial platforms above 250 grams, effective across member states. Wedding vendors must retrofit existing fleets with RID modules or face operational grounding, compressing equipment depreciation schedules. Italian and Greek operators are accelerating fleet refresh cycles to maintain compliance ahead of enforcement deadlines.
Couples are unbundling photography and videography procurement, contracting aerial specialists directly rather than through all-inclusive wedding planner packages. This channel disintermediation shifts price discovery to platform-based comparison tools and erodes traditional referral fee structures. Mumbai and Bangalore studios report the highest direct booking ratios, driven by digitally native clientele comfortable with vendor vetting through social media portfolios.
Drone Wedding Photography Market Segmentation
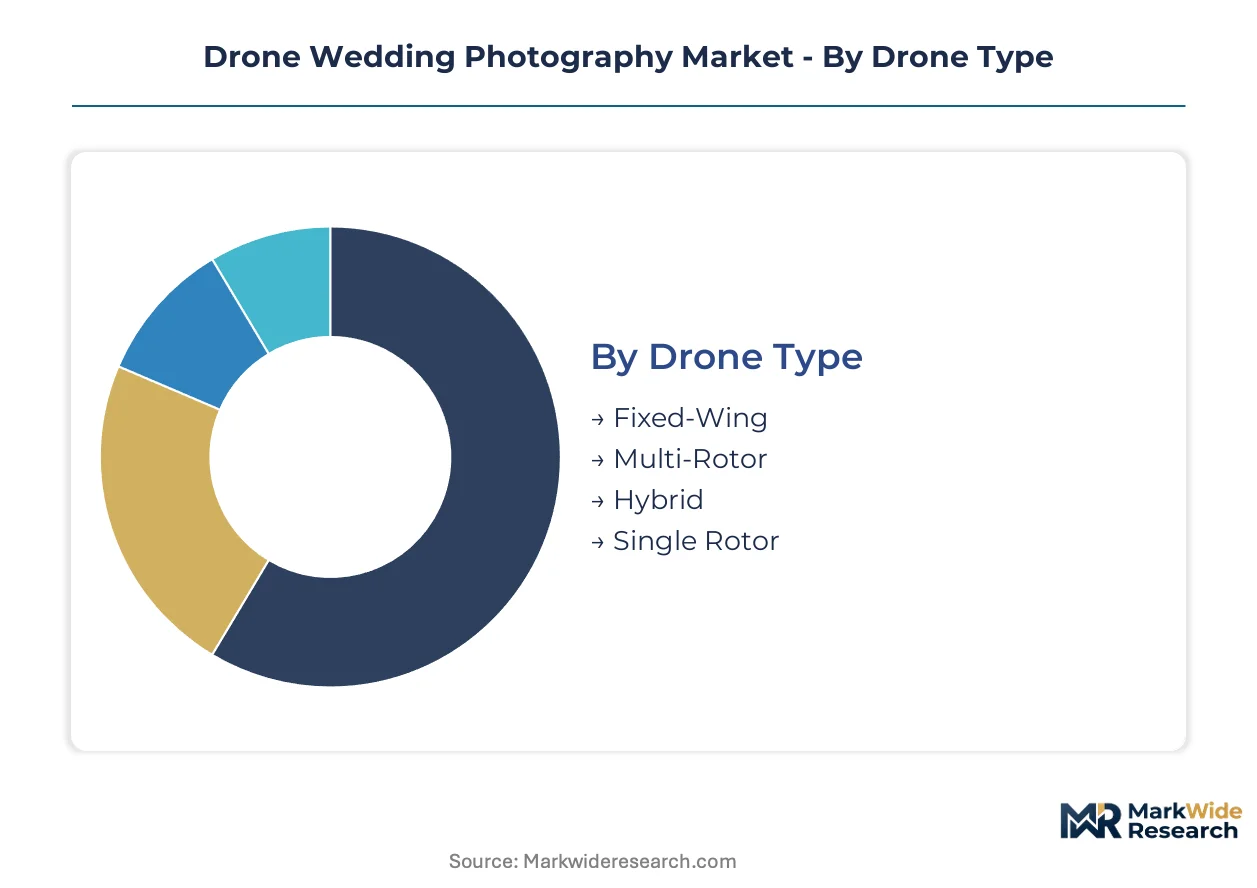
Drone wedding photography vendors configure equipment and service tiers around venue constraints, regulatory airspace, and couple budget bands. Segmentation clarity separates commodity operators from premium aerial cinematography houses competing on FAA Part 107 certification and EASA compliance credentials.
Drone Type:
Mature multi-rotor platforms dominate current fleet deployment while hybrid architectures emerge for extended endurance missions.
- Fixed-Wing:Extended flight endurance suits expansive rural estate coverage across Rajasthan forts and Scottish Highlands venues. Regulatory altitude waivers prove harder to secure for fixed-wing platforms near controlled airspace, limiting urban adoption.
- Multi-Rotor:Vertical takeoff precision and three-axis gimbal stabilization enable hover shots in confined Santorini cliffside chapels and Bali resort gardens. Mumbai studios deploy quadcopter arrays for cinematic orbiting sequences around heritage monuments where DGCA geo-fencing permits operation.
- Hybrid:VTOL transition capability merges endurance with precision, gaining traction among Dubai operators covering desert resort complexes.
- Single Rotor:Helicopter-style platforms persist in high-wind coastal conditions where multi-rotor stability degrades.
Multi-rotor retains volume leadership; hybrid configurations hold the steepest expansion curve.
Service Type:
Pricing stratifies across premium, standard, and economy levels based on deliverable complexity and post-production labor intensity.
- Pre-Wedding Shoots:Cinematic sequences at Kerala backwaters and Jaipur palaces command premium rates for DGCA-permitted aerial corridors. Couples book these sessions months ahead to secure heritage site filming windows.
- Ceremony Coverage:Standardized altitude protocols and repeatable flight paths compress margins as Bangalore studios compete on package bundling.
- Reception Filming:Low-light sensor requirements and FAA night waiver constraints elevate specialist pricing for evening drone coverage.
- Aerial Cinematography:Broadcast-grade 4K output with soundtrack integration differentiates premium vendors from commodity operators.
- Post-Production Editing:AI-assisted color grading and automated highlight reel generation reduce labor costs for high-volume studios in metropolitan India.
Ceremony coverage generates the highest transaction frequency; aerial cinematography delivers the steepest margin expansion.
End User:
Channel disintermediation shifts procurement authority from wedding planners to digitally native couples vetting portfolios through social platforms.
- Professional Photographers:Established studios subcontract certified drone operators to expand service menus without fleet capital expenditure.
- Event Planners:Traditional intermediaries face margin compression as direct-to-consumer booking platforms capture referral fee pools.
- Wedding Venues:British heritage estates and Santorini resorts negotiate preferred vendor arrangements with aerial specialists holding site-specific airspace clearances.
- Couples:Direct procurement concentrates among Bangalore and Mumbai clientele comfortable with platform-based vendor comparison.
- Media Companies:Broadcast and streaming productions contract aerial cinematography for destination wedding content libraries.
Couples drive the fastest channel shift; professional photographers maintain the largest aggregate contract volume.
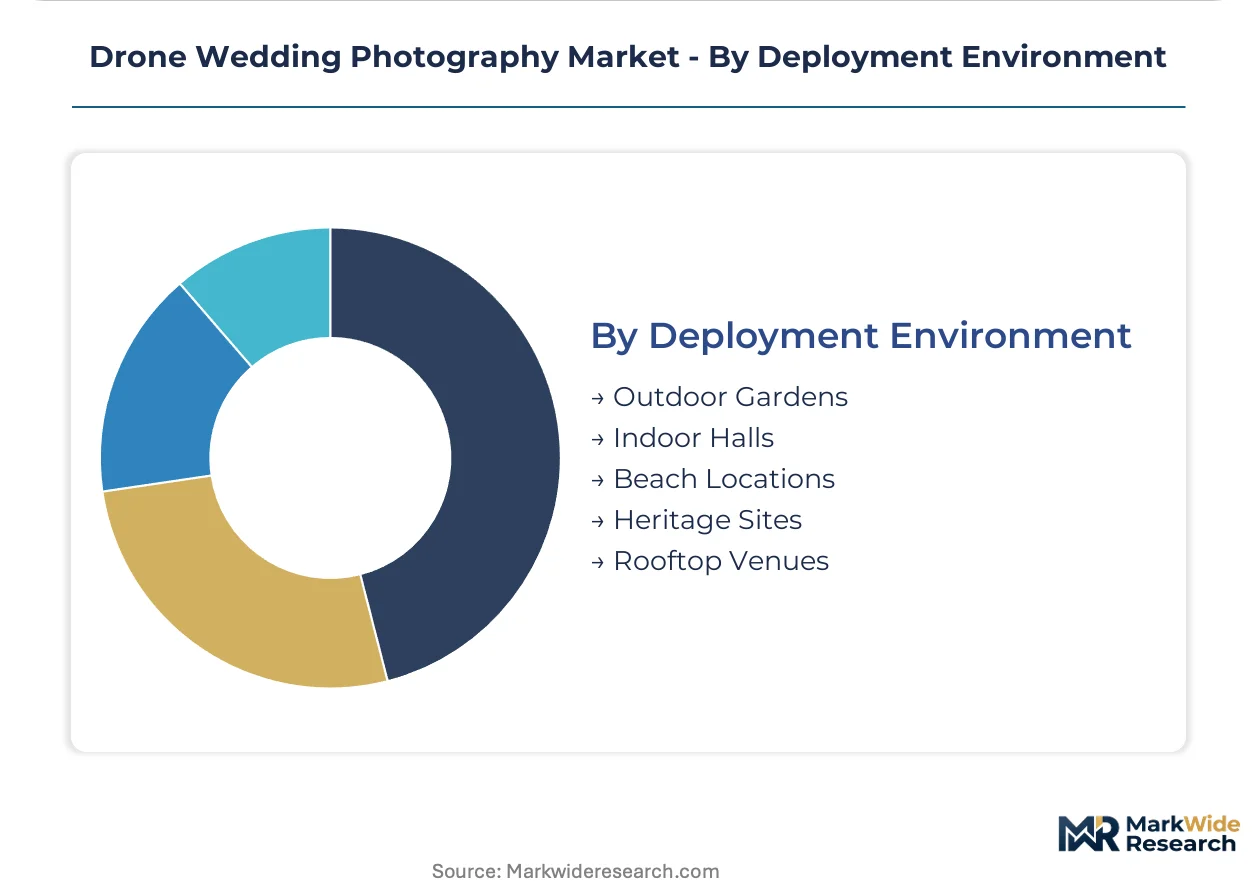
Deployment Environment:
Regulatory complexity varies sharply across venue categories, with heritage monuments and controlled airspace corridors imposing the strictest operational constraints.
- Outdoor Gardens:Unrestricted Class G airspace enables standard Part 107 operations across southeastern United States venues.
- Indoor Halls:GPS-denied environments demand visual line-of-sight piloting and obstacle avoidance systems for safe operation.
- Beach Locations:High-wind coastal conditions in Phuket and Da Nang favor single-rotor platforms over multi-rotor alternatives.
- Heritage Sites:DGCA No Permission-No Takeoff protocols and EASA specific category requirements govern filming at Rajasthan forts and Greek archaeological zones.
- Rooftop Venues:Dense urban canyons require LAANC authorization and remote identification compliance for metropolitan center operations.
Outdoor gardens sustain the highest flight hour volume; heritage sites command the steepest regulatory premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen manufacturing corridor anchors global aerial imaging platform supply, while destination wedding demand clusters around coastal resort infrastructure and heritage monument circuits across multiple continents.
United States
Destination wedding demand concentrates in Florida beach resorts and California wine country estates. FAA Part 107 mandates commercial pilot certification and LAANC authorization for controlled airspace operations. Atlanta and Miami studios compete aggressively for southeastern ceremony coverage where operator density remains highest.
China
Domestic wedding cinematography demand surges in Shanghai and Hangzhou metropolitan corridors. The country's national civil aviation regulator enforces real-name registration and flight zone restrictions near urban centers. Shenzhen's integrated manufacturing ecosystem supplies gimbal-stabilized platforms to domestic operators and export markets simultaneously.
India
Heritage fort pre-wedding sequences drive premium pricing in Rajasthan and Kerala backwater circuits. DGCA No Permission-No Takeoff protocols require advance clearance for monument-adjacent filming. Mumbai and Bangalore studios command the highest direct-to-consumer booking ratios among Asia-Pacific markets.
United Kingdom
British heritage estates and Scottish Highlands venues sustain premium aerial cinematography demand. The country's national aviation safety body governs altitude limits and remote identification requirements for commercial operators. London-based studios subcontract certified pilots to rural venues lacking local operator networks.
Italy
Santorini-style cliffside chapel sequences extend demand across Amalfi Coast and Tuscan vineyard venues. EASA open category frameworks standardize cross-border operator compliance for destination wedding vendors. Rome and Milan studios retrofit fleets with remote identification modules ahead of enforcement deadlines.
Drone Wedding Photography Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying gimbal systems and imaging sensors. The vendor base stratifies across three tiers: Shenzhen-based manufacturing conglomerates controlling hardware supply, regional aerial cinematography houses competing on certification credentials, and boutique operators differentiating through post-production editing capabilities. Dominant competitive moves include fleet refresh cycles to maintain regulatory compliance and direct-to-consumer platform development to capture referral fee pools.
Among Greater China-based manufacturers, Shenzhen Pigeon Aerial Film and Television Co., Ltd. occupies a position representing integrated production-to-service verticals, while DJI Innovations anchors the equipment supply tier. SKYKAM Ltd exemplifies the heritage estate specialist archetype in European markets. These three entities represent distinct competitive positioning vectors: hardware dominance, regional service integration, and premium venue specialization.
| Leading Market Players |
|---|
| Airborne Visuals |
| SKYKAM Ltd |
| Phometo |
| The Wedding Photo Company |
| ProAerial Media LLC |
| Drone Pro Media |
| Shenzhen Pigeon Aerial Film and Television Co., Ltd. |
| DJI Innovations |
| AirVuz |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen's gimbal-stabilized camera module production is compressing hardware margins while elevating pricing power for certified operators in restricted-airspace corridors. Utilization rates below 70% among component suppliers are forcing volume-discount tiering downstream, whereas FAA Part 107 certification scarcity lets compliant vendors command premium positioning in metropolitan markets.
Pricing Analysis
Volume-discount tiering structures dominate procurement between studios and fleet operators, with multi-shoot packages reducing per-event costs by 15-25% for high-frequency venues. Pricing stratifies across premium, standard, and economy tiers based on certification grade and post-production complexity. Cost compression in the economy tier is intensifying because uncertified operators undercut on price to access unrestricted Class G airspace. Event planners exhibit the highest price sensitivity, while couples booking direct prioritize portfolio quality over rate comparison.
Supply Chain Analysis
Extended payment terms from 30 to 90 days are becoming standard among Shenzhen component suppliers financing distributor inventory positions. Hardware production concentrates in China, Taiwan, and South Korea, with imaging sensors drawing from Japanese CMOS fabrication. Battery cell supply rests on Guangdong province capacity, exposing operators to lithium carbonate volatility. Distribution runs through authorized DJI dealer networks and direct OEM procurement for fleet-scale buyers. Single-source vulnerability in gimbal motor supply creates chokepoint risk for boutique studios refreshing equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified pilot scarcity is constraining fleet expansion timelines for studios seeking to capture premium heritage-venue contracts, creating asymmetric returns for operators who accelerate FAA Part 107 or EASA credentialing pipelines.
For Market Incumbents: Insulate margin position by securing exclusive preferred-vendor arrangements with British heritage estates and Santorini resorts before competitor certification catch-up. Accelerate backward integration into post-production editing suites to capture labor cost efficiencies from AI-assisted color grading. Defend against direct-to-consumer platform disintermediation by building proprietary booking portals that bypass wedding planner referral fees.
For New Entrants and Emerging Players: Vietnam's Da Nang and Thailand's Phuket resort corridors offer underpenetrated white-space where established vendor density remains minimal. Target DGCA-approved heritage zones in Rajasthan and Kerala where regulatory barriers filter out uncertified competition. Launch mobile-first portfolio platforms enabling couples to vet aerial cinematography samples before traditional planner consultation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among studios with annual preferred-vendor contracts at destination wedding venues rather than transactional per-event booking. Long-term viability hinges on regulatory compliance infrastructure that becomes more capital-intensive as EASA remote identification mandates expand. Monitor FAA Part 107 practical test scheduling backlogs as an inflection signal—persistent delays indicate sustained scarcity pricing power for certified operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Remote ID Retrofit Program | EASA Regulation 2019/947 mandates RID modules above 250 grams across member states. |
| Heritage Venue Preferred Vendor Agreement | DGCA-permitted zones at Rajasthan forts create legally defensible exclusivity positions. |
| Direct-to-Consumer Platform Launch | Mobile-first booking captures margin previously allocated to wedding planner referral pools. |
| AI-Assisted Post-Production Integration | Automated color grading reduces labor intensity for high-volume Mumbai and Bangalore studios. |
| Cross-Border Operator Certification | Dual FAA Part 107 and EASA credentials enable seamless service across US and European destinations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with certified drone operators, wedding venue procurement managers, and post-production studio heads; and secondary validation against FAA waiver databases, DGCA flight permission logs, and EASA regulatory filings. Bottom-up triangulation combined fleet deployment estimates from Shenzhen manufacturing channels with top-down addressable market sizing from destination wedding volume data across Bali, Santorini, and Rajasthan corridors.
Forecast inputs considered equipment refresh cycles, regulatory enforcement timelines, and platform adoption curves across the projection horizon. Segmentation dimensions modeled include drone architecture type, service tier complexity, end-user procurement channel, and deployment environment regulatory classification. CAGRs were derived from logistic diffusion curves fitted to certified operator growth rates and destination wedding booking patterns. Industry-specific inputs incorporated LAANC authorization system API integration costs and AI editing software penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in leisure travel recovery trajectories, lithium battery raw material costs, or cross-border regulatory harmonization progress would shift the trajectory. Forecasts reflect documented assumptions about certification pipeline throughput and heritage monument filming permission availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Digital Media Production Software Market
Digital Media
Mexico Webtoons Market
Digital Media
North America Webtoons Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Digital Content Creation Market
Digital Media
Middle East and Africa Animation Market
Digital Media
Online Art Market
Digital Media
United States Sports Betting Market
Digital Media
Media Coding Service Market
Digital Media
Video Production Market
Digital Media
Media and Entertainment Market
Digital Media
Social TV Market
Digital Media
Animation and VFX Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
LED Stadium Screens Market