
 APAC DOOH Market | 2026-2036
APAC DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
APAC DOOH Market Outlook
Transit authorities and municipal governments is collapsing the traditional split between retail media buyers and public infrastructure operators as the dominant procurement archetype in APAC DOOH. Focus Media Information Technology Co. Ltd. leverages its elevator screen density across Chinese urban centers to sustain premium inventory rates. JCDecaux Group anchors its competitive position through long-term concession agreements with airport authorities across the region. Plan B Media Public Company Limited dominates transit corridor deployments in Bangkok and Southeast Asian hub cities.
Digital out-of-home advertising encompasses networked electronic displays deployed in publicly accessible spaces, typically utilizing LED backlighting or direct-view LED matrices with brightness ratings exceeding 5,000 nits for daylight visibility, serving brand messaging and programmatic campaign delivery to audiences in transit and commerce environments. Screen displays and digital billboards lead installed base volume, though interactive kiosks capture expanding share in retail chain deployments where proximity marketing integration enables dwell-time monetization. Programmatic advertising technology is reshaping transaction mechanics, with real-time analytics becoming the margin pool differentiator as buyers demand impression verification and audience measurement parity with online channels.
China's MIIT enforces GB standards for electromagnetic compatibility and energy consumption that filter hardware suppliers from non-compliant manufacturers, while India's TRAI guidelines on advertising content and placement restrict certain display categories near educational institutions and highways. Japan's METI promotes smart city infrastructure standards that incorporate DOOH networks as data collection nodes, creating dual-revenue pressure on operators to satisfy both advertiser and municipal data needs. Stakeholders must weigh concession duration against technology refresh cycles as LED panel lifespans and software architectures diverge from typical municipal contract tenors.
Market Dynamics
China's dual carbon goals and MIIT energy efficiency mandates are compressing hardware procurement timelines while forcing operators to reconcile LED panel refresh cycles with municipal concession durations that often extend fifteen to twenty years.
Growth Catalysts
- Transit corridor densification:Municipal governments in Bangkok, Seoul, and Singapore are accelerating screen deployments in subway stations and airports, collapsing the traditional split between retail media buyers and public infrastructure operators.
- Programmatic advertising technology:Real-time analytics and impression verification capabilities are pulling advertising budgets from online channels into physical display networks as buyers demand audience measurement parity.
- GB standards enforcement:China's MIIT electromagnetic compatibility and energy consumption regulations are filtering hardware suppliers, creating procurement advantages for compliant domestic manufacturers.
Market Restraints
- LED panel lifespan divergence:Display hardware refresh cycles of seven to ten years clash with typical municipal contract tenors, stranding capital in obsolete technology.
- Inventory scarcity in tier-one cities:Screen density saturation in Shanghai, Beijing, and Shenzhen is compressing available slots and inflating rate cards beyond mid-market advertiser tolerance.
- Data sovereignty friction:Japan's METI smart city infrastructure standards incorporate DOOH networks as data collection nodes, creating dual-revenue pressure that complicates pure-play advertising business models.
Strategic Opportunities
- Elevator screen underpenetration:Secondary Chinese cities and Southeast Asian urban centers remain below saturation thresholds for captive-audience residential and commercial building displays.
- Proximity marketing integration:Interactive kiosk deployments in retail chain environments enable dwell-time monetization through beacon-triggered content and mobile handset synchronization.
- India's TRAI placement guidelines:Restrictions on highway and educational institution displays create regulatory-defined white space for compliant transit and commercial corridor operators.
Industry Challenges
- Software architecture obsolescence:Content management systems and programmatic platforms require continuous updates that outpace municipal procurement cycles, forcing operators to self-fund integration layers.
- Audience measurement standardization:Fragmented verification methodologies across Australia, South Korea, and Southeast Asia prevent cross-border campaign planning and rate normalization.
- Concession renegotiation complexity:Airport authorities and transit operators are extracting revenue-sharing terms that compress operator margins as contracts come up for renewal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC DOOH Market |
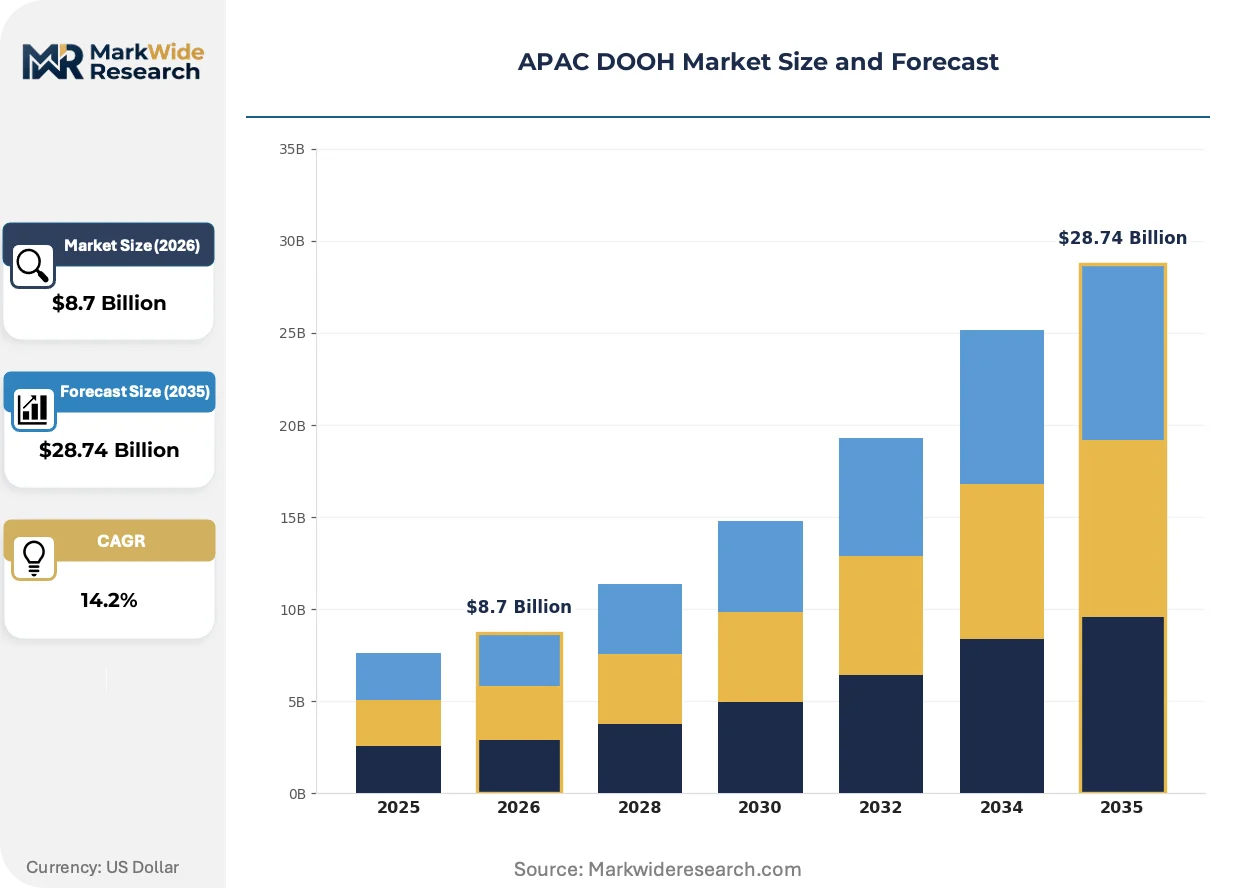
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Billboards, Screen Displays, Interactive Kiosks, LED Panels End User: Retail Chains, Transportation Hubs, Entertainment Venues, Corporate Offices Technology: Augmented Reality, Programmatic Advertising, Real-Time Analytics, Proximity Marketing Distribution Channel: Direct Sales, Online Platforms, Partnerships, Resellers |
| Companies Covered | Outfront Media Inc., Times Innovative Media Limited, JCDecaux Group, Plan B Media Public Company Limited, Asiaray Media Group Limited, Clear Channel Outdoor Holdings Inc., Focus Media Information Technology Co. Ltd., Broadsign International LLC, oOh!media Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC DOOH Market Strategic Shifts
Direct-view LED matrices with brightness ratings exceeding five thousand nits are displacing legacy backlighting systems while programmatic infrastructure is decomposing traditional insertion-order workflows across the region.
Micro-LED packaging technology is decomposing the cost-performance tradeoff that previously favored LCD alternatives in high-ambient-light environments. Airport authorities in Singapore and Hong Kong are specifying direct-view LED for all new terminal deployments. This shift is compressing maintenance budgets and extending operational lifespans in twenty-four-hour transit environments.
China's GB standards for electromagnetic compatibility are forcing hardware redesigns that eliminate non-compliant suppliers from state-backed procurement channels. Domestic manufacturers with certified product lines are capturing municipal contracts that previously sourced from Taiwanese and Korean competitors. The energy efficiency mandates are accelerating adoption of lower-wattage display modules in outdoor highway and plaza installations.
Media buyers are consolidating planning around impression-verified networks that offer audience measurement parity with digital channels. This behavioral shift is fragmenting demand across premium verified inventory and residual non-measured slots. The concentration is most visible in Australian and Japanese markets where agency holding companies have centralized DOOH investment desks.
APAC DOOH Market Segmentation
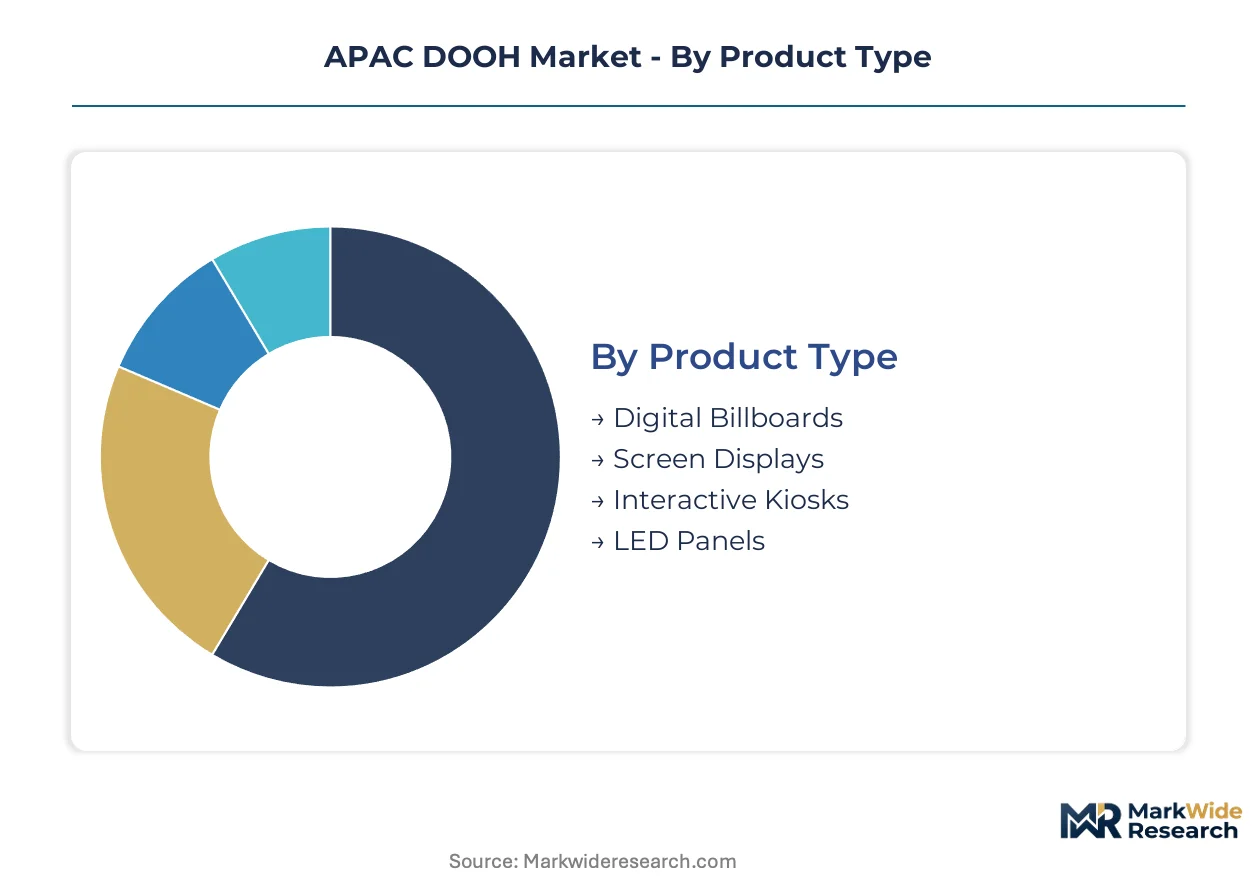
APAC DOOH procurement flows through distinct channel pathways that shape margin structures and installation velocity across product categories. Understanding how hardware specifications, end-use environments, and transaction mechanisms interlock reveals where operators can extract premium positioning versus commodity exposure.
Product Type:
Hardware procurement channels bifurcate between municipal concession holders sourcing through tender processes and retail operators purchasing via direct manufacturer relationships.
- Digital Billboards:Large-format LED matrices mounted on highway corridors and urban plazas, typically exceeding 10,000 nits brightness for daylight visibility. Shanghai and Beijing municipal tenders concentrate demand as tier-one cities exhaust permissible installation sites, compressing available inventory and elevating rate cards.
- Screen Displays:Networked LCD and LED panels deployed in elevator lobbies, commercial building common areas, and transit corridors. Focus Media Information Technology Co. Ltd. sustains premium positioning through density advantages across Chinese urban centers where captive-audience dwell times enable higher CPM realization.
- Interactive Kiosks:Touch-enabled displays with beacon integration for proximity-triggered content delivery. Retail chain deployments in Bangkok and Singapore shopping districts enable dwell-time monetization through mobile handset synchronization.
- LED Panels:Modular direct-view matrices specified for 24-hour transit environments. Singapore and Hong Kong airport authorities mandate these for all new terminal deployments, displacing legacy backlighting systems through superior longevity and reduced maintenance cycles.
Screen displays dominate installed base across APAC urban centers. LED panels are where expansion concentrates as transit authorities accelerate replacement cycles.
End User:
Customer concentration varies sharply by procurement sophistication and concession tenure, with public infrastructure operators wielding superior negotiating leverage versus private retail deployers.
- Transportation Hubs:Airports and subway stations where municipal authorities grant 15-20 year concessions. JCDecaux Group anchors competitive positioning through long-term agreements with airport authorities across the region, though renewal negotiations increasingly extract revenue-sharing terms that compress operator margins.
- Retail Chains:Department stores and shopping malls deploying proximity-enabled networks. Interactive kiosk integration enables beacon-triggered content and mobile synchronization, capturing expanding share as dwell-time monetization models mature.
- Entertainment Venues:Cinemas, stadiums, and concert halls utilizing large-format displays for pre-show advertising and wayfinding.
- Corporate Offices:Building lobbies and common areas where elevator screen networks capture professional audiences during peak commute windows.
Transportation hubs command the longest concession tenures. Retail chains are climbing the fastest as programmatic infrastructure enables impression-verified audience measurement.
Technology:
Technology adoption curves diverge by market maturity, with Australian and Japanese buyers consolidating around verified measurement while Southeast Asian operators prioritize hardware deployment over analytics integration.
- Programmatic Advertising:Real-time bidding infrastructure and impression verification capabilities. Media buyers in Australian and Japanese markets demand audience measurement parity with online channels, fragmenting demand toward premium verified inventory.
- Real-Time Analytics:Computer vision and mobile signal processing for audience counting and dwell-time measurement. Software architecture refresh cycles outpace municipal procurement timelines, forcing operators to self-fund integration layers.
- Proximity Marketing:Beacon-triggered content delivery and mobile handset synchronization.
- Augmented Reality:Overlay content integrating physical displays with smartphone cameras.
Programmatic advertising dominates technology investment. Real-time analytics is where margin differentiation concentrates as verification becomes table stakes for agency holding company budgets.
Distribution Channel:
Channel structure reflects the split between municipal tender processes requiring local compliance certification and retail deployments favoring speed-to-installation.
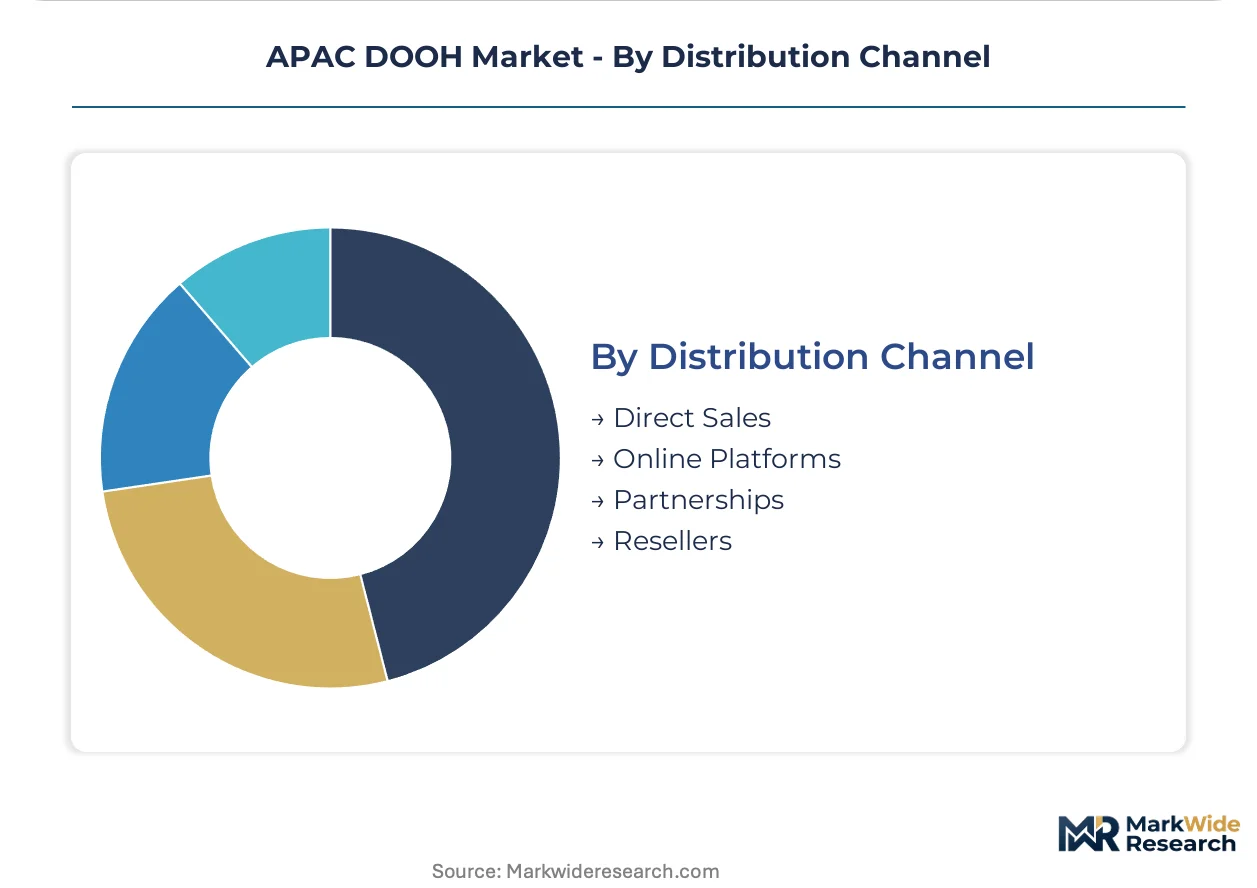
- Direct Sales:Manufacturer relationships with large-scale operators and concession holders. China's MIIT GB standards for electromagnetic compatibility filter hardware suppliers, creating procurement advantages for certified domestic manufacturers in state-backed channels.
- Partnerships:Technology alliances between display manufacturers and software platform providers. Transit corridor densification in Bangkok, Seoul, and Singapore accelerates as municipal governments collapse traditional splits between retail media buyers and public infrastructure operators.
- Resellers:Regional distributors serving mid-market retail and corporate deployments.
- Online Platforms:Digital procurement channels for standardized hardware configurations.
Direct sales dominate municipal and large-operator procurement. Partnerships are gaining share fastest as software-hardware integration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hong Kong-Zhuhai-Macau Bridge and Singapore's Changi Airport expansion anchor digital display procurement corridors across the region's transit infrastructure networks.
China
Elevator screen density in Shanghai and Beijing commercial towers sustains premium inventory rates for captive-audience networks. MIIT GB standards for electromagnetic compatibility and energy consumption filter hardware suppliers, advantaging certified domestic manufacturers in state-backed tenders. Shenzhen's LED module production clusters supply direct-view matrices displacing legacy backlighting across municipal subway deployments.
Japan
Tokyo's Yamanote Line stations and Narita International Terminal expansions drive transit corridor screen densification. METI smart city infrastructure standards incorporate DOOH networks as data collection nodes, creating dual-revenue pressure on operators. Osaka's Kansai International Airport concession renewals extract revenue-sharing terms that compress operator margins.
South Korea
Seoul Metro's digital transformation program accelerates LED panel replacement cycles in subway corridors. The national smart city initiative mandates display interoperability with municipal data networks. Incheon International Airport's Terminal 2 expansion specifies direct-view LED matrices exceeding five thousand nits brightness for twenty-four-hour operational environments.
Singapore
Changi Airport's Terminal 5 development anchors premium large-format display procurement for international transit advertising. The Land Transport Authority's concession frameworks favor operators with integrated programmatic capabilities. Marina Bay and Orchard Road retail clusters deploy proximity-enabled interactive kiosks for beacon-triggered mobile synchronization.
India
Mumbai Metro and Delhi Airport express corridors concentrate transit advertising inventory expansion. TRAI placement guidelines restrict highway and educational institution displays, creating regulatory-defined white space for compliant commercial corridor operators. Bangalore's tech campus clusters drive elevator screen network penetration in captive-audience office environments.
APAC DOOH Market Competitive Environment
Concentration sits with concession-based infrastructure operators and captive-audience network specialists competing across divergent procurement channels. The vendor base spans multinational outdoor advertising groups, domestic Chinese elevator media platforms, and Southeast Asian transit corridor specialists. Three archetypes dominate: long-term concession holders anchoring airport and subway authority relationships; density-driven residential and commercial building network operators; and programmatic technology providers enabling impression-verified audience measurement. Competitive moves center on concession renewal negotiations with revenue-sharing extraction and software-hardware integration partnerships collapsing traditional procurement splits.
Among the concession-holder archetype, JCDecaux Group and Clear Channel Outdoor Holdings Inc. occupy positions tied to long-term airport authority agreements across multiple jurisdictions. Focus Media Information Technology Co. Ltd. exemplifies the density-driven model through elevator screen saturation in Chinese urban centers. Plan B Media Public Company Limited represents transit corridor specialization in Bangkok and Southeast Asian hub cities.
| Leading Market Players |
|---|
| Outfront Media Inc. |
| Times Innovative Media Limited |
| JCDecaux Group |
| Plan B Media Public Company Limited |
| Asiaray Media Group Limited |
| Clear Channel Outdoor Holdings Inc. |
| Focus Media Information Technology Co. Ltd. |
| Broadsign International LLC |
| oOh!media Limited |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's LED module production clusters generate scale economies that compress unit costs for direct-view matrices while simultaneously elevating entry barriers for non-certified manufacturers locked out of state-backed procurement channels. This concentration dynamic propagates through municipal tender processes, where MIIT GB compliance filters create pricing power for domestic suppliers and force international competitors into residual retail channels at compressed margins.
Pricing Analysis
Volume-discount tiering structures dominate municipal procurement, with three-tier pricing separating premium verified inventory from standard programmatic slots and residual non-measured display capacity. Price differentiation hinges on certification grade under MIIT electromagnetic compatibility standards and volume scale of concession deployments, with tier-one cities commanding premium positioning due to inventory scarcity. Cost compression in standard-tier highway and plaza installations is intensifying because domestic manufacturers with certified product lines capture state-backed tenders previously sourced from Taiwanese and Korean competitors. Mid-market advertisers exhibit highest price sensitivity as rate cards in Shanghai and Beijing inflate beyond tolerance thresholds, while multinational agency holding companies demonstrate lowest sensitivity when purchasing impression-verified networks with audience measurement parity.
Supply Chain Analysis
Inventory lead times for direct-view LED matrices have compressed as Shenzhen and Dongguan production clusters absorb module assembly and final integration stages within consolidated manufacturing footprints. Raw material dependencies center on gallium nitride substrates, driver ICs, and aluminum heat-dissipation frames sourced from China, Taiwan, and South Korea. Single-source vulnerability concentrates in advanced LED chip fabrication, where patent-protected processes tether supply security to licensing arrangements with dominant semiconductor foundries. Distribution runs through direct manufacturer relationships with municipal concession holders and tier-one retail operators, while mid-market deployers access standardized hardware configurations via regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC DOOH represents an early-cycle expansion story as transit corridor densification across Bangkok, Seoul, and Singapore accelerates screen deployments beyond saturation thresholds in legacy tier-one cities. Programmatic infrastructure maturity is pulling advertising budgets from online channels into physical display networks, creating sustained tailwinds for impression-verified inventory.
For Market Incumbents: Compound density advantages in captive-audience environments through elevator screen network expansion in secondary Chinese cities and Southeast Asian urban centers. Deepen backward integration into LED module production to defend margin position against domestic Chinese manufacturers capturing state-backed tenders through MIIT certification compliance. Prioritize software-hardware integration partnerships that collapse traditional procurement splits between retail media buyers and public infrastructure operators. For New Entrants and Emerging Players: Lead with proximity marketing integration capabilities targeting retail chain deployments in Bangkok and Singapore shopping districts, where beacon-triggered content and mobile handset synchronization enable dwell-time monetization models with lower capital intensity than municipal concession bidding. India's TRAI placement guidelines restricting highway and educational institution displays create regulatory-defined white space for compliant transit and commercial corridor operators. Pursue technology alliance go-to-market angles with established software platform providers to bypass hardware certification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with integrated programmatic capabilities and long-term airport authority concession agreements, as media buyers consolidate planning around impression-verified networks. Long-term viability over a five-to-ten year window rests on reconciling LED panel refresh cycles with municipal contract tenors that often extend fifteen to twenty years. Target acquisition archetypes include density-driven residential and commercial building network specialists and programmatic technology providers enabling audience measurement parity. Monitor software architecture obsolescence risk as content management system refresh cycles outpace municipal procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal Negotiation | Airport authorities extract revenue-sharing terms that compress operator margins across Osaka and Singapore renewals. |
| MIIT Certification Investment | Domestic manufacturers with GB-compliant product lines capture municipal tenders filtering non-certified competitors. |
| Programmatic Platform Integration | Real-time bidding infrastructure enables impression verification that attracts agency holding company budgets. |
| Transit Corridor Densification | Municipal governments accelerate screen deployments in subway stations and airports across Seoul and Bangkok. |
| Proximity Marketing Deployment | Beacon-triggered interactive kiosks in Singapore retail clusters enable dwell-time monetization through mobile synchronization. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with transit authority procurement officers, airport concession managers, media buying directors at agency holding companies, LED display manufacturers, and programmatic technology platform executives. Secondary validation drew from MIIT GB standards documentation, TRAI placement guidelines, METI smart city infrastructure standards, municipal tender records, and customs trade data for LED module imports. Bottom-up unit economics modeling triangulated against top-down market sizing derived from concession tenure analysis and screen density calculations.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, end user environment, technology adoption tier, and distribution channel structure. CAGRs were derived from installation velocity projections, replacement cycle assumptions, and programmatic penetration curves calibrated against verified inventory growth in Australian and Japanese markets. Industry-specific forecast inputs include municipal concession renewal timelines, LED panel lifespan degradation curves, and software platform refresh cycle frequencies.
Forecasts assume regulatory continuity in China's MIIT enforcement regime, India's TRAI placement guidelines, and Japan's METI smart city standards; material policy shifts would require re-modeling supply-side certification requirements and demand-side inventory accessibility. Technology obsolescence risk, data sovereignty friction, and concession renegotiation complexity represent specific factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Digital Content Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
VFX Market
Digital Media
Video Content Management Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Media Coding Service Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Anime Derivatives Market
Digital Media
Anime Streaming Tool Market
Digital Media
Middle East Gaming Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Adult Entertainment Market
Digital Media
Europe Online Gambling Market
Digital Media
Digital Media Market
Digital Media
Digital Media Switchers Market