
 Europe Professional Audio Video (Proav) Market | 2026-2036
Europe Professional Audio Video (Proav) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Professional Audio Video (Proav) Market Foresight
IP-based signal transport is narrowing the gap between traditional AV infrastructure and IT network architectures across European installations. Barco NV leverages its command-and-control visualization heritage to dominate large-venue projection and LED walls. Crestron Electronics, Inc. anchors the integrated control systems segment with programmable automation platforms that unify lighting, climate, and AV. Sennheiser electronic GmbH & Co. KG specializes in wireless microphone ecosystems that address spectral congestion in dense urban broadcast environments.
Professional Audio Video encompasses engineered systems for sound reinforcement, visual display, signal routing, and content distribution in commercial and institutional settings, typically operating across frequency ranges from 20 Hz to 20 kHz for audio and resolutions from 1080p to 8K for video. These systems serve live events, broadcast origination, corporate communication, and educational delivery where consumer-grade equipment lacks reliability, scalability, or interoperability. Microphones and streaming technology capture expanding margin pools as remote production and hybrid participation become permanent fixtures in corporate and education workflows. Speakers and analog switchers represent mature categories where replacement cycles lengthen and price competition intensifies, though premium line arrays in sports venues sustain above-average profitability.
CE marking under the EU Radio Equipment Directive governs wireless microphone and streaming device market access, while the EU Green Deal's Ecodesign requirements compel manufacturers to reduce standby power and improve material recoverability in amplifiers and displays. REACH and RoHS constrain substance use in solder, cables, and housing plastics, adding compliance cost but also creating differentiation for vendors with certified supply chains. Stakeholders must monitor spectrum reallocation decisions by national regulators and the pending EU AI Act's potential classification of automated camera tracking and voice analytics systems.
Market Dynamics
IP-based signal transport is collapsing the traditional boundary between AV infrastructure and enterprise IT networks across European installations, forcing vendors to reengineer hardware for software-defined workflows and network-native interoperability.
Growth Catalysts
- Hybrid conferencing infrastructure:Corporate events and permanent meeting spaces in Germany, the United Kingdom, and France are driving accelerated procurement of integrated microphone arrays and camera systems. IT departments now control AV budgets that facilities managers once owned.
- EU Green Deal Ecodesign requirements:Mandates for reduced standby power and improved material recoverability in amplifiers and displays are pushing vendors toward energy-efficient Class-D architectures and recyclable aluminum enclosures. Certified supply chains command procurement preference.
- Broadcast modernization:Public service broadcasters across the continent are retiring SDI infrastructure in favor of IP-based production, creating replacement demand for routing switchers, multiviewers, and synchronized audio networks.
Market Restraints
- Semiconductor supply concentration:FPGA and DSP fabrication for professional audio processing concentrates in Taiwanese foundries, exposing European integrators to allocation risk and extended lead times for digital mixing consoles.
- Spectral congestion in UHF bands:National regulators in France, Germany, and the United Kingdom continue reallocating spectrum to mobile broadband, compressing available channels for wireless microphone systems and forcing costly hardware refreshes.
- Copper and rare earth price volatility:Magnet materials for speaker drivers and cable conductors face input cost swings that squeeze margin on mature product categories where pricing power has eroded.
Strategic Opportunities
- Smart venue retrofits in secondary cities:Municipal arenas and convention centers in Spain, Italy, and Poland lag London and Paris in installed base, offering white-space demand for line arrays and LED video walls as EU recovery funds flow to cultural infrastructure.
- Convergence of AV and building automation:Integration of lighting, climate, and AV control onto single programmable platforms creates attach-rate opportunities for sensors and analytics software in corporate headquarters.
- EU AI Act classification pathway:Automated camera tracking and voice analytics systems face pending regulatory clarity; vendors with pre-certified compliance documentation will capture early mover advantage in education and healthcare verticals.
Industry Challenges
- Network engineering skill scarcity:Traditional AV technicians lack certification in VLAN segmentation, PTP timing, and multicast routing required for ST 2110 deployments, forcing integrators to hire IT specialists or retrain existing staff.
- CE marking timeline compression:The EU Radio Equipment Directive's evolving testing protocols for wireless microphone and streaming devices extend product launch cycles, delaying revenue recognition against fixed R&D budgets.
- Legacy analog integration friction:Hybrid environments mixing Dante/AES67 networks with existing copper infrastructure demand custom gateway hardware and commissioning expertise that erodes project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Professional Audio Video (Proav) Market |
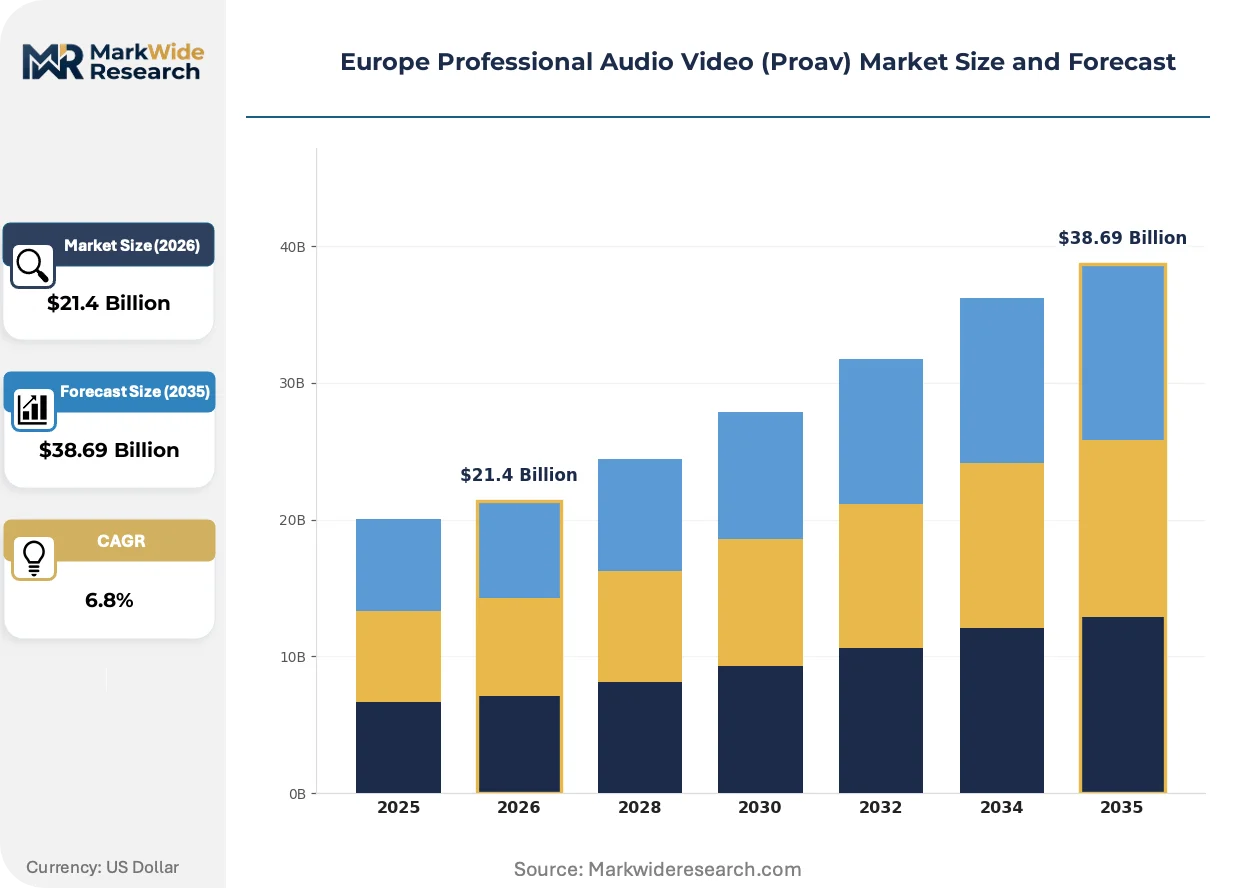
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Projectors, Speakers, Switchers Application: Corporate Events, Entertainment, Education, Houses of Worship Technology: Analog, Digital, Wireless, Streaming End User: Broadcasting, Hospitality, Retail, Sports Venues |
| Companies Covered | Barco NV, Crestron Electronics, Inc., Bosch Security Systems GmbH, Harman International Industries, Inc., Sony Corporation, Sennheiser electronic GmbH & Co. KG, Shure Incorporated, Panasonic Corporation, LG Electronics Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Professional Audio Video (Proav) Market Shifts & Advancements
Software-defined signal processing is decoupling hardware from functionality across European installations, enabling subscription-based feature licensing and remote fleet management that restructures vendor-customer relationships.
Dante audio networking from Audinate is rendering obsolete traditional point-to-point analog and digital snake systems in live sound and broadcast environments. Regional system integrators in Germany and the Netherlands are specifying Dante-native endpoints on 80% of new corporate and education projects. The shift compresses installation labor and cable costs while locking venues into ecosystem-dependent upgrade paths.
REACH and RoHS substance restrictions are constraining solder alloys, cable jacketing compounds, and housing plastics used in European-market products. Manufacturers with certified supply chains are capturing procurement preference from public sector buyers, while smaller vendors face compliance cost barriers. Amplifier and loudspeaker categories see the most intense material substitution pressure as enclosure mass and thermal management requirements conflict with restricted substance lists.
Enterprise IT departments are consolidating AV procurement under centralized network security governance, displacing the decentralized facilities-led purchasing that dominated pre-2020. Financial services and pharmaceutical headquarters in Frankfurt and Basel are requiring ST 2110 compliance and encrypted control protocols as table stakes. This pattern concentrates demand among vendors with enterprise-grade cybersecurity documentation and dedicated channel partner programs.
Europe Professional Audio Video (Proav) Market Segmentation
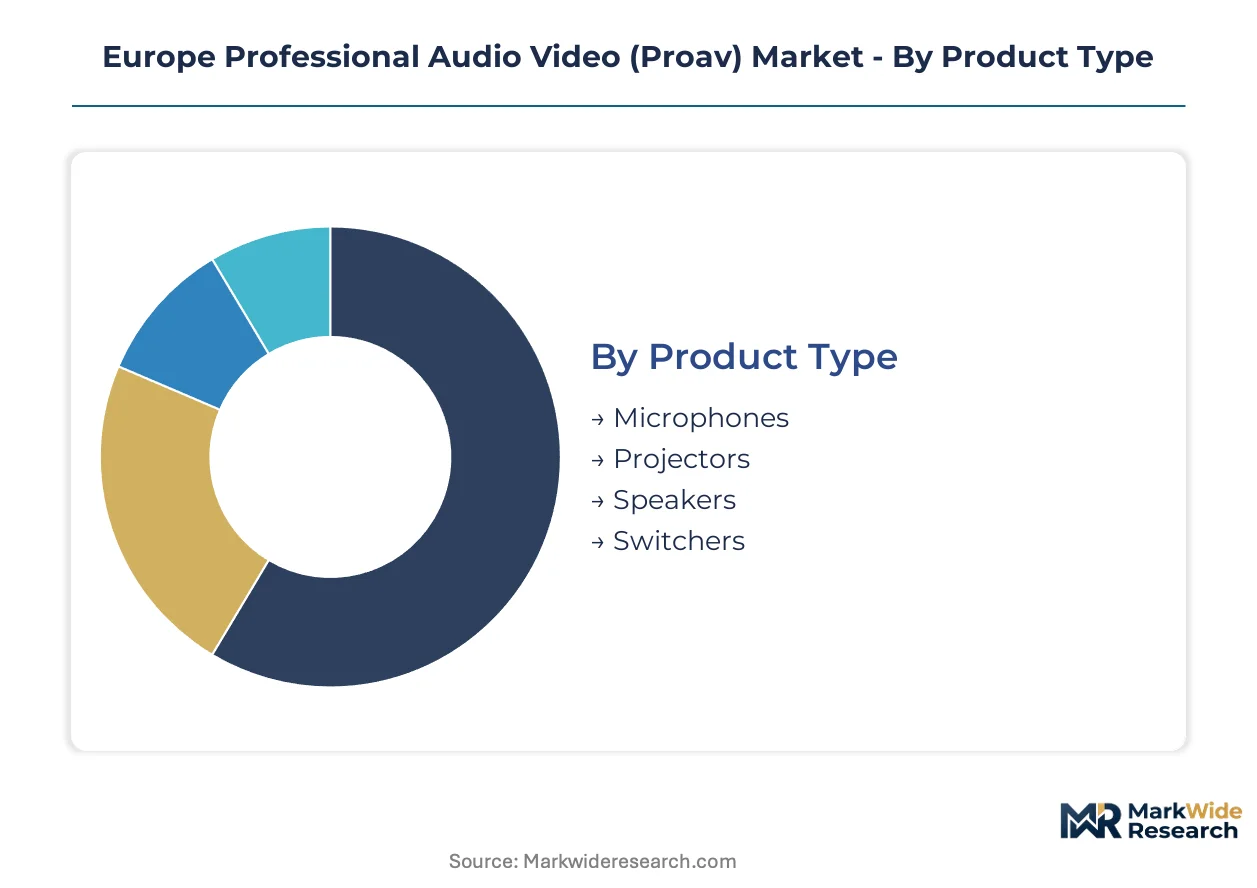
Segmentation reveals how procurement authority, technical requirements, and compliance obligations diverge across European ProAV installations. Each dimension exposes distinct margin structures and vendor specialization patterns that shape competitive positioning.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with networked systems demanding ongoing firmware support and on-site calibration that traditional analog equipment never required.
- Microphones:Wireless microphone systems incorporate spectral scanning and frequency agility to navigate UHF band reallocation by regulators in Germany, France, and the United Kingdom. Demand concentrates in corporate headquarters and broadcast studios where spectral congestion forces hardware refreshes and IT departments now manage procurement budgets previously controlled by facilities teams.
- Projectors:Laser phosphor and LED projection technologies deliver 20,000-hour maintenance-free operation for large-venue installations. Museums, command centers, and corporate briefing rooms in London, Paris, and Frankfurt absorb the premium tier where Barco NV holds established relationships.
- Speakers:Line array systems for sports venues and touring applications face copper and rare earth magnet cost volatility.
- Switchers:IP-based routing infrastructure replaces SDI matrices in broadcast modernization programs.
Microphones hold the largest share; momentum sits with switchers as IP conversion accelerates.
Application:
Cost tier stratification separates permanent installation budgets from rental and staging expenditure, with ownership models diverging sharply across use cases.
- Corporate Events:Hybrid conferencing infrastructure demands integrated microphone arrays, auto-tracking cameras, and room automation platforms. Germany, the United Kingdom, and France drive procurement volume as IT departments consolidate AV spending under network security governance with ST 2110 compliance as mandatory specification.
- Entertainment:Touring productions and fixed theatrical installations specify Dante-native audio networks and programmable LED video walls. Secondary cities in Spain, Italy, and Poland present white-space opportunity as EU recovery funds flow to cultural infrastructure upgrades.
- Education:Lecture capture and remote participation systems face pending EU AI Act classification for automated camera tracking.
- Houses of Worship:Volunteer-operated installations prioritize intuitive control interfaces over technical sophistication.
Corporate Events commands the largest installed base; Education is expanding most quickly as hybrid learning becomes permanent fixture.
Technology:
Volume concentration favors network-native architectures as European integrators retire legacy copper infrastructure at accelerating pace.
- Digital:Dante audio networking from Audinate renders point-to-point analog snakes obsolete across German and Dutch corporate and education projects. Regional system integrators specify Dante-native endpoints on the majority of new installations, compressing labor costs while creating ecosystem-dependent upgrade paths.
- Wireless:UHF wireless microphone systems face spectral compression from mobile broadband allocation decisions by national regulators. CE marking under the EU Radio Equipment Directive extends testing timelines and compliance costs.
- Analog:Mature installed base in legacy venues requires gateway hardware for hybrid network integration.
- Streaming:Remote production workflows and hybrid participation drive encoder and decoder procurement for broadcast and corporate verticals.
Digital holds the largest share; streaming gains share fastest as remote production becomes standard practice.
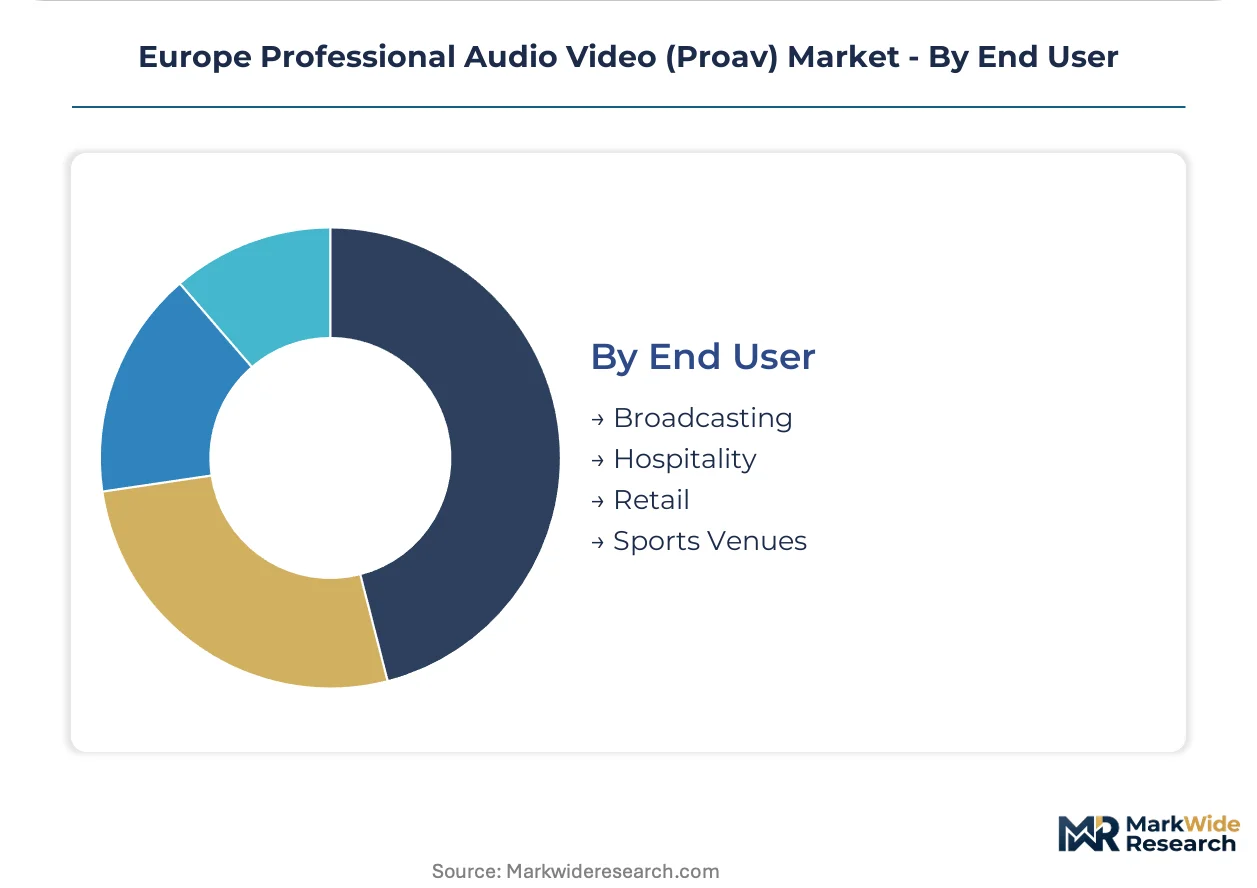
End User:
Customer type determines specification authority, with broadcasting and sports venues maintaining engineering teams while hospitality and retail delegate to integrators.
- Broadcasting:Public service broadcasters across Europe retire SDI infrastructure for IP-based production, creating replacement demand for routing switchers, multiviewers, and PTP-synchronized audio networks. The EU Green Deal's Ecodesign requirements compel energy-efficient amplifier selection.
- Sports Venues:Premium line arrays and LED video walls sustain above-average profitability despite long replacement cycles. Municipal arenas in secondary cities lag London and Paris in installed base, offering retrofit opportunity.
- Hospitality:Hotel conference centers specify integrated control platforms unifying lighting, climate, and AV.
- Retail:Digital signage and background music systems prioritize cost efficiency over technical sophistication.
Broadcasting holds the largest share; sports venues present the steepest expansion trajectory as EU recovery funds reach cultural infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ProAV equipment flows into corporate headquarters and broadcast facilities across France, the United Kingdom, and the Netherlands, establishing a north-south trade corridor that concentrates procurement budgets in the continent's economic core.
Germany
Broadcast modernization and smart venue retrofits absorb capital expenditure in Berlin and Munich. The EU Green Deal's Ecodesign Directive compels energy-efficient amplifier selection in public sector tenders. Frankfurt's financial services headquarters mandate ST 2110 compliance and encrypted control protocols for corporate conferencing infrastructure.
United Kingdom
Hybrid conferencing infrastructure drives procurement of integrated microphone arrays and auto-tracking cameras in London corporate headquarters. Ofcom's spectrum reallocation decisions compress UHF channels for wireless microphone systems. Manchester and Birmingham municipal arenas lag London in LED video wall installed base, offering retrofit opportunity.
France
Public service broadcasters retire SDI infrastructure for IP-based production, creating replacement demand for routing switchers and PTP-synchronized audio networks. ANSM and CNIL oversight extends to automated camera tracking systems in education and healthcare. Paris command centers and museums sustain premium-tier projection demand where established vendor relationships dominate.
Netherlands
Regional system integrators specify Dante-native endpoints on the majority of new corporate and education projects in Amsterdam and Rotterdam. REACH and RoHS substance restrictions constrain cable jacketing compounds and housing plastics in Dutch-market products. Eindhoven's technology corridor anchors semiconductor fabrication for professional audio processing components.
Poland
Municipal arenas and convention centers in Warsaw and Krakow lag Western European capitals in installed base, offering white-space demand for line arrays and LED video walls. EU recovery funds flow to cultural infrastructure upgrades in secondary cities. Local integrators face network engineering skill scarcity for VLAN segmentation and multicast routing deployments.
Europe Professional Audio Video (Proav) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven manufacturers anchor the mid-market and premium-tier vendors capture broadcast and command-center verticals. The vendor base separates into three strategic archetypes: integrated control platform providers, wireless audio ecosystem specialists, and visualization hardware manufacturers. M&A activity concentrates on IP-based signal processing capabilities, while geographic expansion targets secondary cities in Southern and Eastern Europe.
Among Belgium-based visualization specialists, Barco NV occupies a position exemplifying large-venue projection and LED wall heritage. Crestron Electronics, Inc. represents the integrated control systems archetype with programmable automation platforms. Sennheiser electronic GmbH & Co. KG anchors the wireless microphone ecosystem tier, addressing spectral congestion in dense urban broadcast environments. These three entities illustrate how vendor specialization patterns align with procurement authority shifts from facilities managers to IT departments.
| Leading Market Players |
|---|
| Barco NV |
| Crestron Electronics, Inc. |
| Bosch Security Systems GmbH |
| Harman International Industries, Inc. |
| Sony Corporation |
| Sennheiser electronic GmbH & Co. KG |
| Shure Incorporated |
| Panasonic Corporation |
| LG Electronics Inc. |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp freight corridor channels amplifier enclosures and DSP modules from Taiwanese foundries through Dutch distribution hubs, with container rate volatility feeding directly into procurement cost spreads between certified and uncertified vendor tiers across German and French corporate installations.
Pricing Analysis
Next-generation IP-native endpoints command 40-60% premiums over legacy analog equivalents, while prior-generation SDI switchers face accelerating price erosion as broadcasters retire copper infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates ST 2110-compliant systems with encrypted control protocols from basic Dante-native configurations and residual analog inventory. Pricing pressure stems from semiconductor allocation constraints that extend lead times for FPGA-based digital mixing consoles. Public sector buyers in Germany and France exhibit lowest price sensitivity due to Ecodesign Directive compliance mandates, while hospitality integrators in Southern Europe prioritize cost efficiency over certification tier.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for Taiwanese FPGA and DSP suppliers serving European OEMs, compressing working capital for mid-tier integrators. Manufacturing concentrates in Taiwan for semiconductor fabrication, China for magnet materials and cable assemblies, and Germany for precision amplifier enclosures. Raw material dependencies include neodymium for speaker drivers, copper for cable conductors, and aluminum for thermal management housings. Single-source vulnerability concentrates in Taiwanese foundry capacity for professional audio processing chips. Distribution runs through authorized dealer networks in Germany and the Netherlands, with direct-to-integrator procurement gaining share in broadcast verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's ProAV market sits in early-cycle expansion as IP-based signal transport displaces legacy copper infrastructure across broadcast and corporate verticals, with EU recovery funds accelerating smart venue retrofits in secondary cities.
For Market Incumbents: Harden ecosystem lock-in by deepening Dante-native endpoint penetration in German and Dutch corporate accounts before AES67 interoperability standards erode proprietary advantages. Acquire certified supply chain capabilities to defend margin position against REACH and RoHS compliance cost barriers that disproportionately burden smaller competitors. Prioritize firmware subscription models that convert one-time hardware revenue into recurring service income.
For New Entrants and Emerging Players: Pursue white-space demand in Polish and Italian municipal arenas where EU recovery funds flow but incumbent relationships remain underdeveloped. Target education verticals facing pending EU AI Act classification for automated camera tracking, where pre-certified compliance documentation commands procurement preference. Lead with network engineering training bundles that address VLAN segmentation skill scarcity among regional integrators.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underoptimized ProAV divisions lacking IP-native product portfolios. Long-term viability favors vendors with software-defined architectures and enterprise cybersecurity documentation as IT departments consolidate procurement authority. Monitor spectrum reallocation decisions by Ofcom, BNetzA, and ANFR as inflection indicators for wireless microphone refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| IP-Native Product Migration | ST 2110 compliance captures procurement budgets shifting from facilities to IT departments. |
| Supply Chain Certification Investment | REACH and RoHS certified supply chains command preference in German public sector tenders. |
| Subscription-Based Feature Licensing | Software-defined signal processing enables recurring revenue from firmware updates. |
| Secondary City Geographic Expansion | EU recovery funds flow to cultural infrastructure in Spain, Italy, and Poland arenas. |
| EU AI Act Pre-Certification | Automated camera tracking compliance documentation secures education and healthcare verticals. |
Research Methodology
Cross-validation between primary interviews with system integrators, broadcast engineers, and corporate IT procurement officers and secondary validation through customs trade data, EU Ecodesign Directive filings, and semiconductor import records anchors the qualitative findings. Bottom-up triangulation from project-level procurement data and top-down reconciliation against vendor shipment disclosures ensures dimensional consistency across product type, application, technology, and end user segments.
Calibration against historical replacement cycles and technology adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include signal transport architecture, compliance certification tier, procurement authority type, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand functions incorporating hybrid conferencing penetration rates and broadcast infrastructure retirement schedules.
Sensitivities concentrate around semiconductor allocation timelines, spectrum reallocation decisions by national regulators, and EU AI Act implementation clarity. Forecasts reflect documented assumptions regarding technology substitution rates and procurement authority migration patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Media and Entertainment Market
Digital Media
Online Movie Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Digital Content Market
Digital Media
United Kingdom Webtoons Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Global Transport Media Market
Digital Media
Media Gateway Market
Digital Media
Anime Market
Digital Media
Europe Online Gambling Market
Digital Media
ACGN Subculture Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Playout Solutions Market
Digital Media
Digital Video Content Market
Digital Media
Digital Media Production Software Market
Digital Media
Global Music Video Production Market