
 Web Service Cloud Market | 2026-2036
Web Service Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Web Service Cloud Market Analysis
Healthcare and life sciences is recalibrating its cloud procurement priorities, shifting from cost-driven public deployments toward HIPAA-compliant hybrid architectures. Amazon Web Services (AWS) leverages its GovCloud regions to anchor federal and healthcare contracts with dedicated compliance boundaries. Microsoft Azure competes through deep enterprise integration, sustaining advantage in organizations already running Windows Server and Office 365 workloads. Google Cloud Platform differentiates on data analytics and AI infrastructure, specializing in genomics and pharmaceutical research pipelines.
Web Service Cloud denotes on-demand delivery of computing resources, storage, databases, networking, and software over the internet through standardized APIs with service-level agreements guaranteeing uptime, latency, and throughput thresholds. The architecture eliminates capital expenditure on physical infrastructure while enabling elastic scaling from hundreds to millions of concurrent users across distributed data centers. Public cloud deployments lead in absolute revenue volume, though hybrid cloud represents the fastest-growing structural segment as enterprises retain sensitive workloads on-premises while bursting transactional loads to external infrastructure. SaaS captures the largest margin pool due to recurring subscription economics and low customer acquisition costs at scale, while IaaS remains the foundational layer where hyperscalers invest most heavily in capital-intensive data center expansion.
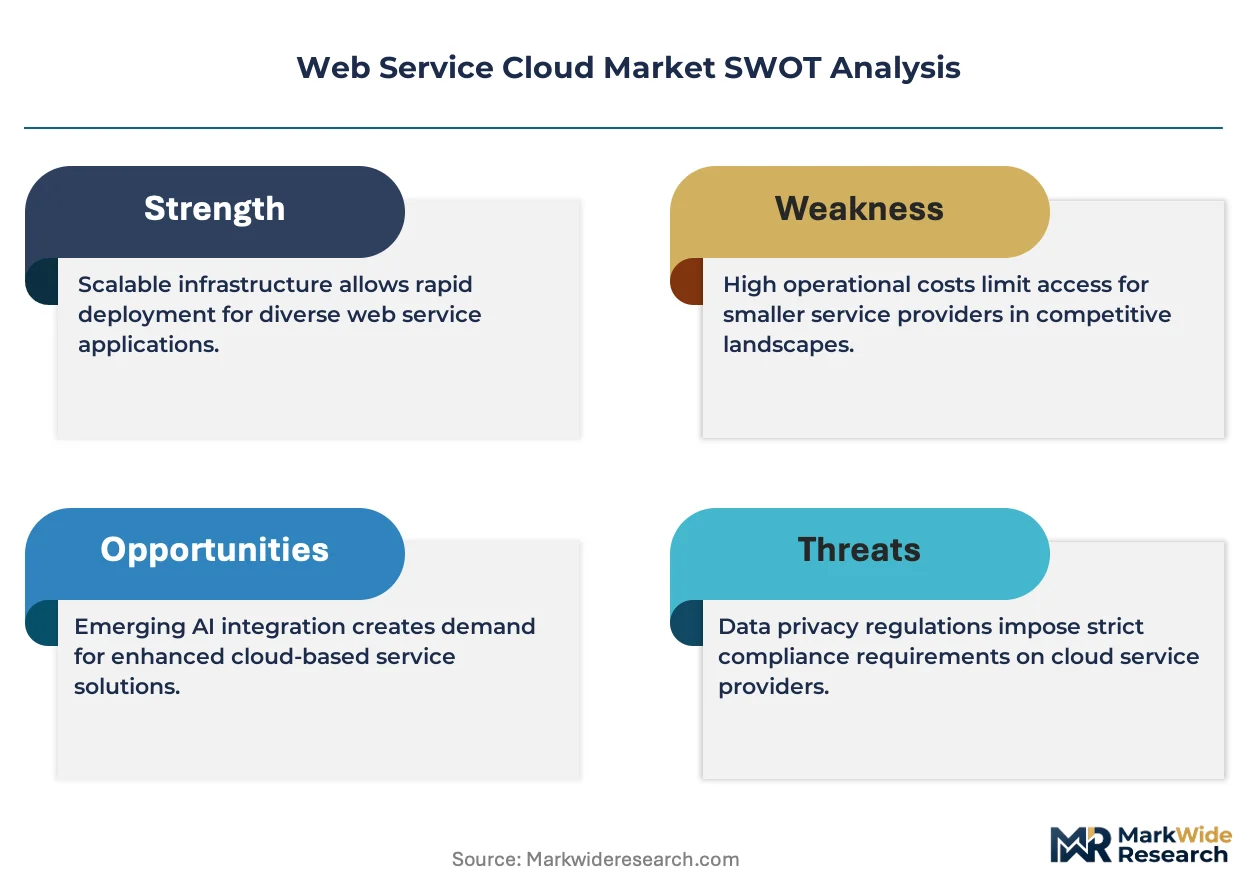
FDA 21 CFR Part 11, HIPAA, and the EU AI Act collectively shape product standards and market access, forcing providers to implement audit trails, encryption-at-rest mandates, and algorithmic transparency documentation before serving regulated industries. The SEC's cybersecurity disclosure rules for publicly traded firms further tighten procurement due diligence, redirecting enterprise buyers toward vendors with third-party SOC 2 Type II and ISO 27001 certifications. Stakeholders must monitor evolving cross-border data localization requirements and assess whether their current provider footprint satisfies emerging sovereignty constraints before committing to multi-year infrastructure contracts.
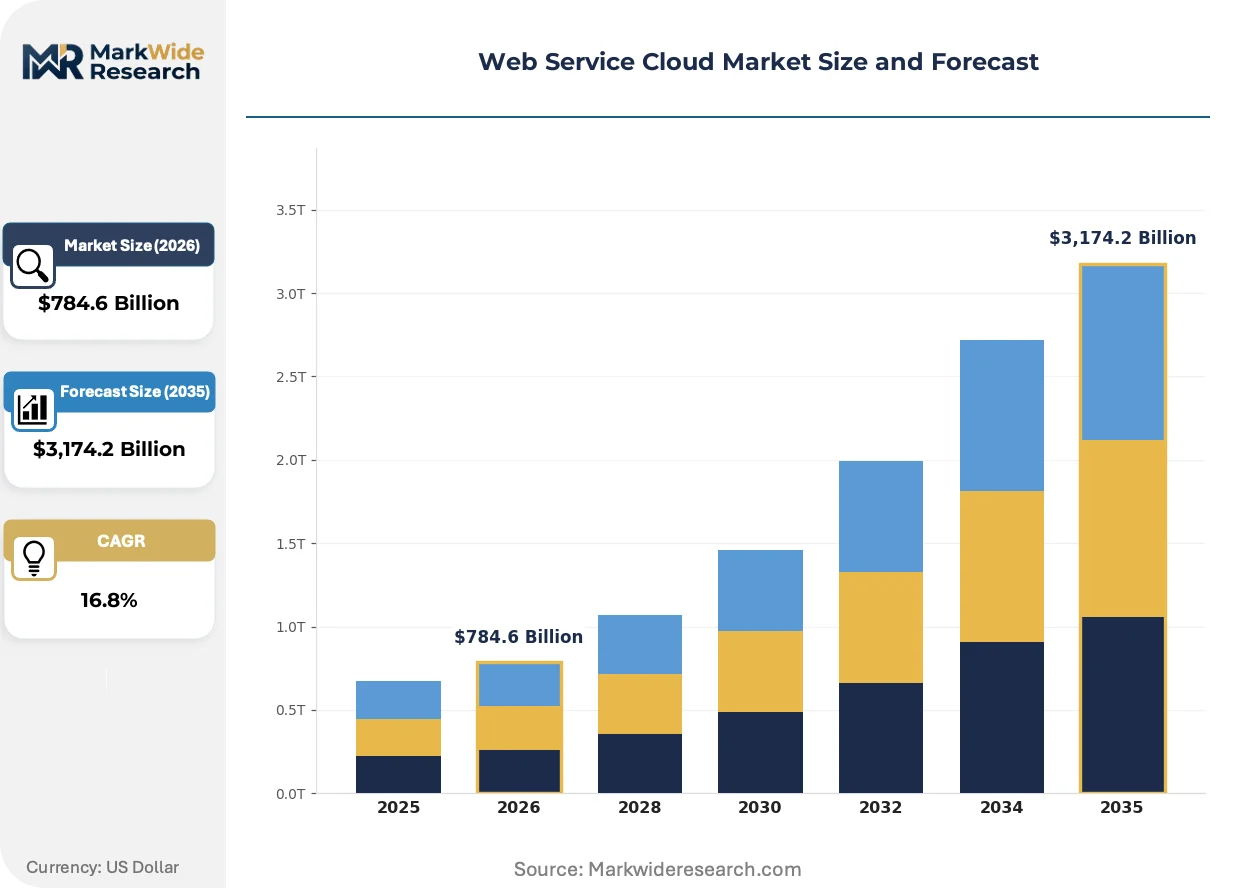
Market Dynamics
Enterprise data gravity is shifting toward sovereign infrastructure as cross-border data localization mandates harden procurement criteria. Financial services and healthcare buyers now disqualify providers lacking certified in-region data centers before contract negotiation begins.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises must complete algorithmic transparency documentation by 2026, accelerating migration to audited cloud environments with built-in governance tooling.
- Automotive edge computing:German OEMs require sub-10ms latency for autonomous vehicle telemetry, driving private cloud deployments at manufacturing plants.
- Genomics pipeline expansion:Pharmaceutical research organizations are scaling computational biology workloads that exceed on-premises capacity, creating sustained demand for burst-capable hybrid architectures.
Market Restraints
- Energy input volatility:Data center power purchase agreements face renegotiation as European electricity markets experience price instability, compressing hyperscaler margins in Frankfurt and Amsterdam clusters.
- Semiconductor equipment concentration:Advanced networking chip fabrication concentrates in Taiwan, creating single-source vulnerability for 400G+ interconnect hardware essential to AI training clusters.
- Substitution by sovereign alternatives:National cloud initiatives in France, Germany, and Italy are capturing sensitive public-sector workloads that would otherwise flow to commercial hyperscalers.
Strategic Opportunities
- India's data localization regime:The country's central bank mandates in-country storage for payment data, creating greenfield infrastructure demand as domestic providers scale to meet enterprise requirements.
- Convergence of confidential computing and Kubernetes:Hardware-based enclaves combined with container orchestration enable multi-tenant AI training without data exposure, opening regulated pharmaceutical collaborations.
- Brazilian healthcare digitization:ANVISA's electronic medical record mandates are driving first-time cloud adoption among regional hospital networks previously reliant on paper systems.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Platform engineering teams capable of managing workload portability across AWS, Azure, and GCP command premium compensation, constraining mid-market enterprise migration velocity.
- SOC 2 Type II certification timelines:Healthcare SaaS vendors face 12-18 month audit cycles before qualifying for hospital procurement shortlists, delaying revenue recognition.
- Legacy mainframe integration complexity:Financial institutions running COBOL-based core banking systems require specialized middleware to connect transaction processing to modern API gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web Service Cloud Market |
| Market Size in 2026 | $784.6 Billion |
| Market Size in 2035 | $3,174.2 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: Enterprise, Startups, Government, Educational Institutions Technology: Microservices, Serverless, API Management, Containers |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform, Oracle Cloud Infrastructure, Alibaba Cloud, IBM Cloud, DigitalOcean, Rackspace, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web Service Cloud Market Emerging Trajectories
Workload portability and infrastructure abstraction are eroding provider stickiness as enterprises architect for supplier diversification. Standardized container formats and declarative infrastructure APIs are commoditizing underlying compute resources.
Confidential computing hardware is absorbing sensitive AI training workloads previously restricted to air-gapped environments. Pharmaceutical companies are deploying AMD SEV-SNP and Intel TDX-enabled instances for multi-party drug discovery without raw data exposure. This encryption-at-runtime capability is absorbing the compliance overhead that previously forced research consortia into expensive private infrastructure builds.
GDPR Article 44 transfer mechanism rulings are forcing structural separation of European and US data estates. The Schrems II precedent invalidated Privacy Shield, compelling providers to establish operationally independent EU legal entities with segregated engineering teams. Healthcare and financial services buyers in Germany, France, and the Netherlands are now mandating contractual guarantees against US government data access requests.
Consumption-based pricing is displacing reserved instance commitments as the dominant procurement model for variable workloads. Retail and media companies with seasonal traffic patterns are negotiating pay-per-query data warehouse contracts and serverless container billing. This shift is most pronounced in the United States, where CFOs prioritize OpS flexibility over multi-year depreciation schedules amid interest rate volatility.
Web Service Cloud Market Segmentation
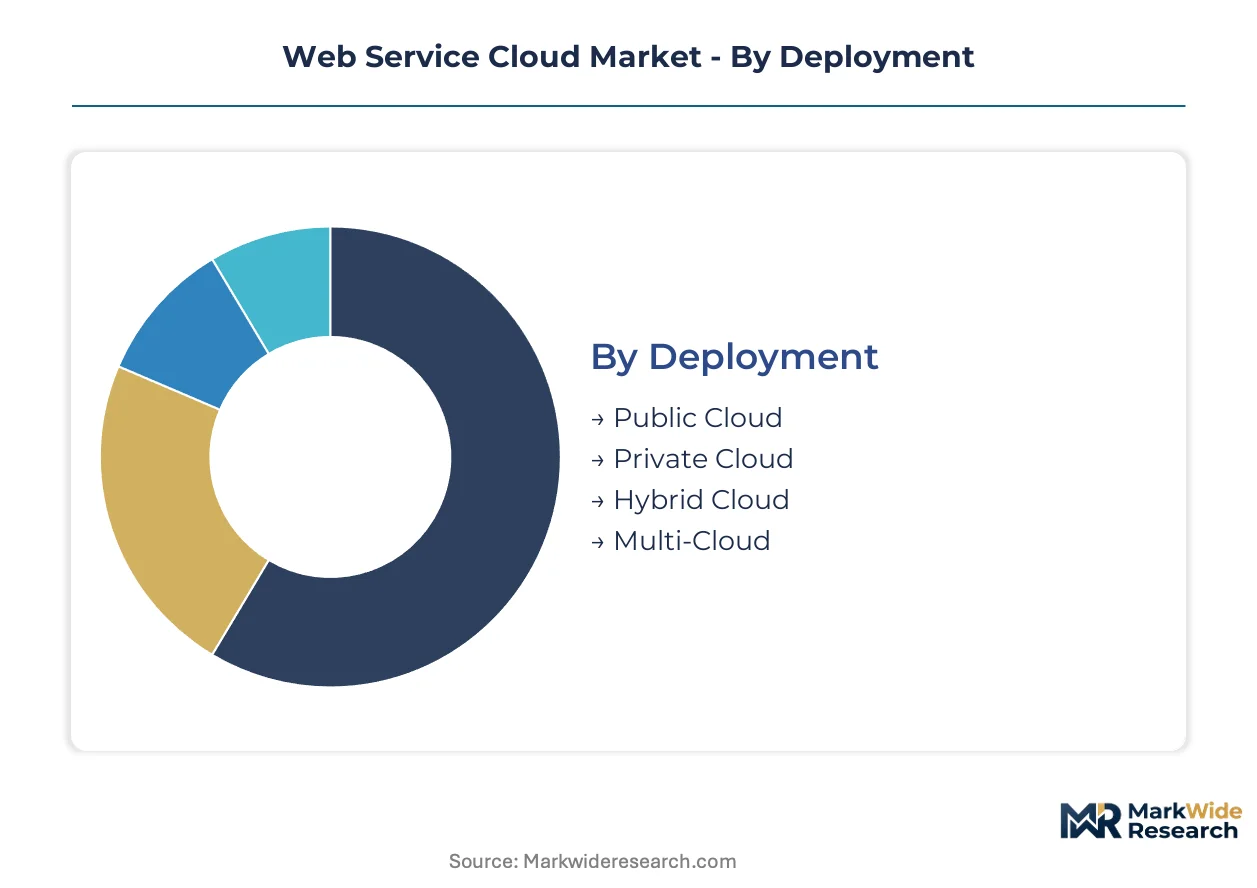
Web Service Cloud segmentation reveals how procurement criteria diverge across compliance regimes, workload sensitivity, and operational maturity. Deployment architecture and service abstraction layers determine capital efficiency, regulatory eligibility, and vendor lock-in exposure for buyers.
Deployment:
Upgrade cycles in cloud infrastructure accelerate as enterprises replace first-generation lift-and-shift migrations with architecturally native deployments optimized for cost and sovereignty.
- Public Cloud:Shared infrastructure pools deliver elastic compute and storage through standardized APIs with usage-based billing. Demand concentrates in US retail and media sectors where CFOs prioritize OpS flexibility over depreciation schedules amid interest rate volatility.
- Private Cloud:Dedicated single-tenant environments provide isolated compute, storage, and networking resources within enterprise-controlled facilities or hosted cages. German automotive and industrial engineering sectors drive adoption for data residency under GDPR and EU AI Act mandates.
- Hybrid Cloud:Orchestrated workload portability across on-premises and external infrastructure with unified management planes. Burst-capable architectures absorb pharmaceutical genomics pipelines exceeding on-premises capacity.
- Multi-Cloud:Deliberate distribution of workloads across two or more hyperscaler environments to mitigate vendor concentration risk. Platform engineering scarcity constrains mid-market enterprise adoption velocity.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Hybrid Cloud.
Service Type:
Margin structures diverge sharply across abstraction layers, with higher-level services capturing recurring subscription economics while infrastructure layers require heavy capital reinvestment.
- IaaS:Foundational compute, storage, and networking resources delivered as virtualized primitives. Hyperscalers invest most heavily here in Frankfurt, Amsterdam, and Singapore data center expansion.
- PaaS:Managed runtime environments, databases, and middleware eliminating operational overhead for application teams. Enterprise buyers in financial services favor PaaS for SOC 2 Type II certification coverage.
- SaaS:Complete application functionality delivered through web browsers and mobile clients with zero infrastructure management. Healthcare SaaS vendors face 12-18 month audit cycles before hospital procurement qualification.
- DaaS:Cloud-hosted virtual desktops and application streaming replacing traditional VDI deployments. ANVISA's electronic medical record mandates in Brazil drive first-time adoption among regional hospital networks.
Revenue concentration sits with SaaS; steepest expansion trajectory belongs to PaaS as enterprises containerize legacy workloads.
End User:
Procurement sophistication varies dramatically across buyer categories, with compliance documentation and security attestation requirements scaling with organizational maturity and regulatory exposure.
- Enterprise:Large organizations with dedicated cloud centers of excellence negotiating enterprise discount programs and dedicated support tiers. SEC cybersecurity disclosure rules tighten procurement due diligence toward SOC 2 Type II and ISO 27001 certifications.
- Startups:Venture-backed and bootstrapped companies prioritizing speed-to-market over architectural optimization, often defaulting to whichever provider offers the most generous credits program.
- Government:Federal, state, and municipal agencies requiring FedRAMP, IL-5, or equivalent sovereign certifications. AWS GovCloud regions anchor federal contracts with dedicated compliance boundaries.
- Educational Institutions:Universities and research consortia leveraging educational pricing and grant-funded infrastructure for computational research and administrative systems.
Contract value concentrates in Enterprise; Government represents the most restrictive certification pathway.
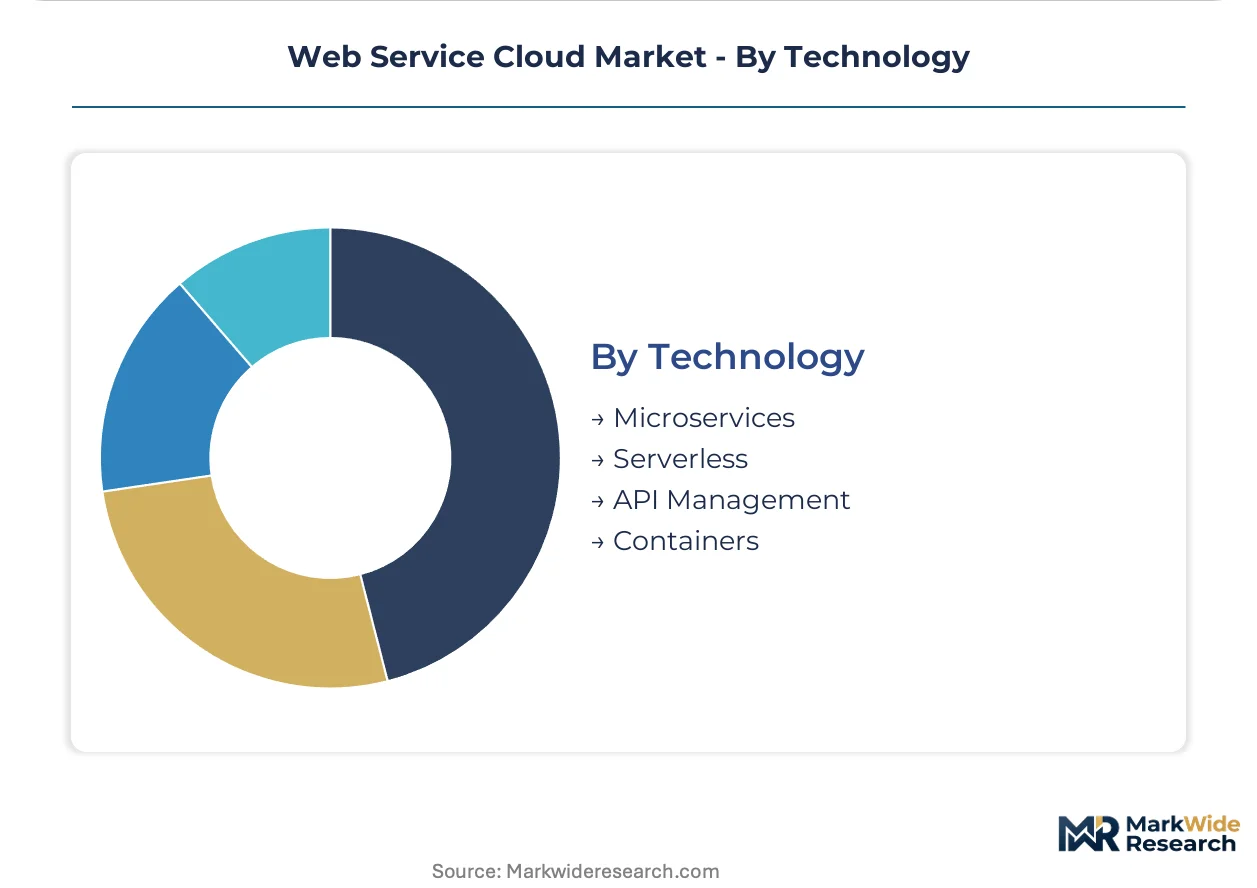
Technology:
Architectural paradigms determine portability, operational complexity, and the feasibility of multi-cloud strategies for workload diversification.
- Microservices:Decomposed application architectures enabling independent deployment and scaling of bounded contexts. Financial institutions require specialized middleware to connect COBOL-based core systems to modern API gateways.
- Serverless:Function-as-a-service execution models with automatic scaling and per-invocation billing. Retail companies with seasonal traffic patterns negotiate pay-per-query data warehouse contracts.
- API Management:Governance, security, and monetization layers for internal and external service interfaces. GDPR Article 44 transfer mechanism rulings force structural separation of European and US API estates.
- Containers:Standardized application packaging with Kubernetes orchestration enabling workload portability across provider environments. Confidential computing hardware absorbs sensitive AI training previously restricted to air-gapped environments.
Adoption maturity concentrates in Containers; Serverless gains share fastest among variable workload profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure production concentrates in hyperscale data center clusters across the United States, Germany, and China, while consumption patterns fragment across sovereign compliance zones and latency-sensitive edge locations. European demand outpaces local supply capacity, forcing German automotive OEMs to build private cloud installations at manufacturing plants. Indian payment data localization mandates are drawing greenfield infrastructure investment from domestic providers scaling to meet enterprise requirements.
United States
Retail and media companies with seasonal traffic patterns drive consumption-based procurement models prioritizing OpS flexibility over multi-year depreciation schedules. SEC cybersecurity disclosure rules tighten procurement due diligence toward SOC 2 Type II and ISO 27001 certifications. AWS GovCloud regions anchor federal and healthcare contracts with dedicated compliance boundaries in Northern Virginia and Oregon clusters.
Germany
Automotive and industrial engineering sectors demand sub-10ms latency for autonomous vehicle telemetry, driving private cloud deployments at manufacturing plants. EU AI Act compliance deadlines and GDPR data residency mandates disqualify providers lacking certified in-region data centers before contract negotiation begins. Frankfurt and Berlin clusters face power purchase agreement renegotiation as European electricity markets experience price instability.
India
RBI mandates in-country storage for payment data, creating greenfield infrastructure demand as domestic providers scale to meet enterprise requirements. The central bank's data localization regime forces structural separation of Indian and foreign data estates for financial services workloads. Mumbai and Bangalore clusters absorb venture-backed startup consumption prioritizing speed-to-market over architectural optimization.
China
MIIT cloud service licensing requirements and data security regulations channel sensitive workloads toward domestic hyperscalers with in-country legal entities. Dual carbon goals pressure data center operators toward renewable energy procurement in Yangtze River Delta and Pearl River Delta clusters. Zhejiang and Jiangsu provinces concentrate manufacturing edge computing for industrial IoT telemetry processing.
Brazil
ANVISA electronic medical record mandates drive first-time cloud adoption among regional hospital networks previously reliant on paper systems. The national pharmaceutical regulator's digitization requirements create demand for HIPAA-compliant hybrid architectures in São Paulo and Rio de Janeiro clinical networks. Domestic providers capture public-sector workloads through certified government cloud frameworks.
Web Service Cloud Market Vendor Landscape
Top-tier vendors anchor the hyperscale infrastructure tier, while regional specialists and sovereign cloud alternatives occupy differentiated positions below. The market structure reflects a consolidated upper tier with three dominant global platforms, fragmented mid-market offerings, and emerging national champions capturing sensitive public-sector workloads. Strategic archetypes include full-stack hyperscalers with compliance-specialized regions, vertical-integrated enterprise integrators, and sovereign infrastructure operators with government equity backing. Competitive dynamics center on geographic expansion through certified region launches and confidential computing hardware deployment for regulated AI workloads.
Within the full-stack hyperscaler tier, Amazon Web Services (AWS), Microsoft Azure, and Google Cloud Platform represent the dominant infrastructure platforms. AWS exemplifies the compliance-specialized archetype through GovCloud region architecture. Microsoft Azure occupies a position within enterprise-integrated environments running Windows Server and Office 365 workloads. Google Cloud Platform sits within the data analytics specialization vector for genomics and pharmaceutical research pipelines. Oracle Cloud Infrastructure and IBM Cloud represent enterprise integrators with legacy database and middleware integration capabilities. Alibaba Cloud anchors the China-domestic and Asia-Pacific expansion pattern.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud Platform |
| Oracle Cloud Infrastructure |
| Alibaba Cloud |
| IBM Cloud |
| DigitalOcean |
| Rackspace |
| ServiceNow |
| Others |
Supply Flow & Price Mechanics
European electricity price benchmarks cascade through data center power purchase agreements, compressing hyperscaler margins in Frankfurt and Amsterdam clusters while forcing tiered pricing stratification across compute-intensive workloads. This input cost volatility feeds directly into regional cloud procurement premiums, with German automotive OEMs absorbing latency-sensitive private cloud deployments at manufacturing plants.
Pricing Analysis
Margin tightening in IaaS tiers reflects energy input volatility and semiconductor equipment concentration, with hyperscalers renegotiating power agreements in European clusters. Three-tier pricing structure across premium compliance-grade, standard enterprise, and economy developer tiers separates buyers by certification requirements and data residency guarantees. Cost-down pressure on burst-capable hybrid architectures accelerates as pharmaceutical genomics pipelines exceed on-premises capacity. Startups default to economy tiers with generous credit programs, while financial services enterprises absorb premium pricing for SOC 2 Type II and ISO 27001 coverage.
Supply Chain Analysis
Hardware refresh cycles and decommissioned server refurbishment flow through secondary markets in Singapore and Hong Kong, extending asset lifecycles for mid-market colocation providers. Advanced networking chip fabrication concentrates in Taiwan, with 400G+ interconnect hardware for AI training clusters drawing from single-source vulnerability. Memory module and storage component dependencies rest on South Korean and Chinese manufacturing bases. Tariff exposure on semiconductor equipment threatens hyperscaler expansion timelines. Distribution runs through direct enterprise sales teams with dedicated solution architects, supplemented by channel partners serving mid-market workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container orchestration and serverless execution models are displacing first-generation lift-and-shift architectures, forcing infrastructure providers to reprice around workload abstraction rather than raw compute units.
For Market Incumbents: Anchor compliance-specialized region launches in Germany, France, and India to capture sovereign cloud demand driven by GDPR, EU AI Act, and RBI data localization mandates. Defend against national cloud initiatives in France, Germany, and Italy by embedding confidential computing hardware for multi-tenant AI training without data exposure. Prioritize certification investment in FedRAMP and IL-5 pathways to maintain government contract eligibility. For New Entrants and Emerging Players: Launch via vertical-integrated managed service partnerships targeting Brazilian healthcare digitization under ANVISA electronic medical record mandates, where regional hospital networks seek first-time cloud adoption. Exploit platform engineering scarcity in mid-market enterprises by offering pre-architected multi-cloud portability solutions. Target India's greenfield payment data infrastructure as domestic providers scale to meet RBI requirements. For Investors and Strategic Acquirers: The window for entry favors confidential computing hardware specialists and sovereign cloud operators with government equity backing. Long-term viability hinges on regulatory compliance automation tooling rather than raw infrastructure scale. Watch for EU AI Act enforcement actions against providers lacking algorithmic transparency documentation as an inflection signal for compliance-grade premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Deployment | AMD SEV-SNP and Intel TDX instances absorb pharmaceutical AI workloads from air-gapped environments. |
| Sovereign Region Expansion | Certified EU data centers with segregated engineering teams satisfy Schrems II transfer mechanism rulings. |
| Serverless Platform Integration | Pay-per-query billing models capture retail and media companies with seasonal traffic volatility. |
| Healthcare Compliance Specialization | HIPAA and FDA 21 CFR Part 11 tooling anchors hospital procurement shortlists for SaaS vendors. |
| Multi-Cloud Orchestration Acquisition | Kubernetes-native portability solutions address mid-market enterprise migration constraints. |
Methodological Framework
Document review covered hyperscaler capex disclosures, SEC cybersecurity filings, and EU regulatory guidance, complemented by interviews with CTOs, platform engineers, IT procurement officers, and healthcare compliance leads. Secondary validation drew from hyperscaler infrastructure expansion announcements, GPO contract databases, and hospital procurement records. Bottom-up workload sizing and top-down market aggregation were triangulated against primary field input.
Historical capacity deployment patterns were cross-referenced against panel input from data center operators and enterprise migration timelines. Segmentation dimensions modeled include deployment architecture, service abstraction layer, organization size, vertical industry, and regional compliance regime. CAGRs were derived from capacity expansion trajectories and consumption-based pricing adoption curves across the analysis window. AI training cluster demand and sovereign data localization mandates served as industry-specific forecast inputs.
Regulatory enforcement delays, energy market volatility, and semiconductor supply disruption are the dominant revision risks to projection assumptions. Practitioners should monitor EU AI Act compliance deadlines, power purchase agreement renegotiations in European clusters, and Taiwan Strait logistics indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Cloud API Market
Cloud Computing
Cloud IDE Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
North America Cloud Microservices Platform Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Government Cloud Market
Cloud Computing
Cloudifier Market
Cloud Computing
Cloud Continuum Market