
 Cloud IDE Market | 2026-2036
Cloud IDE Market Size, Share, and Industry Trends Forecast 2026-2036
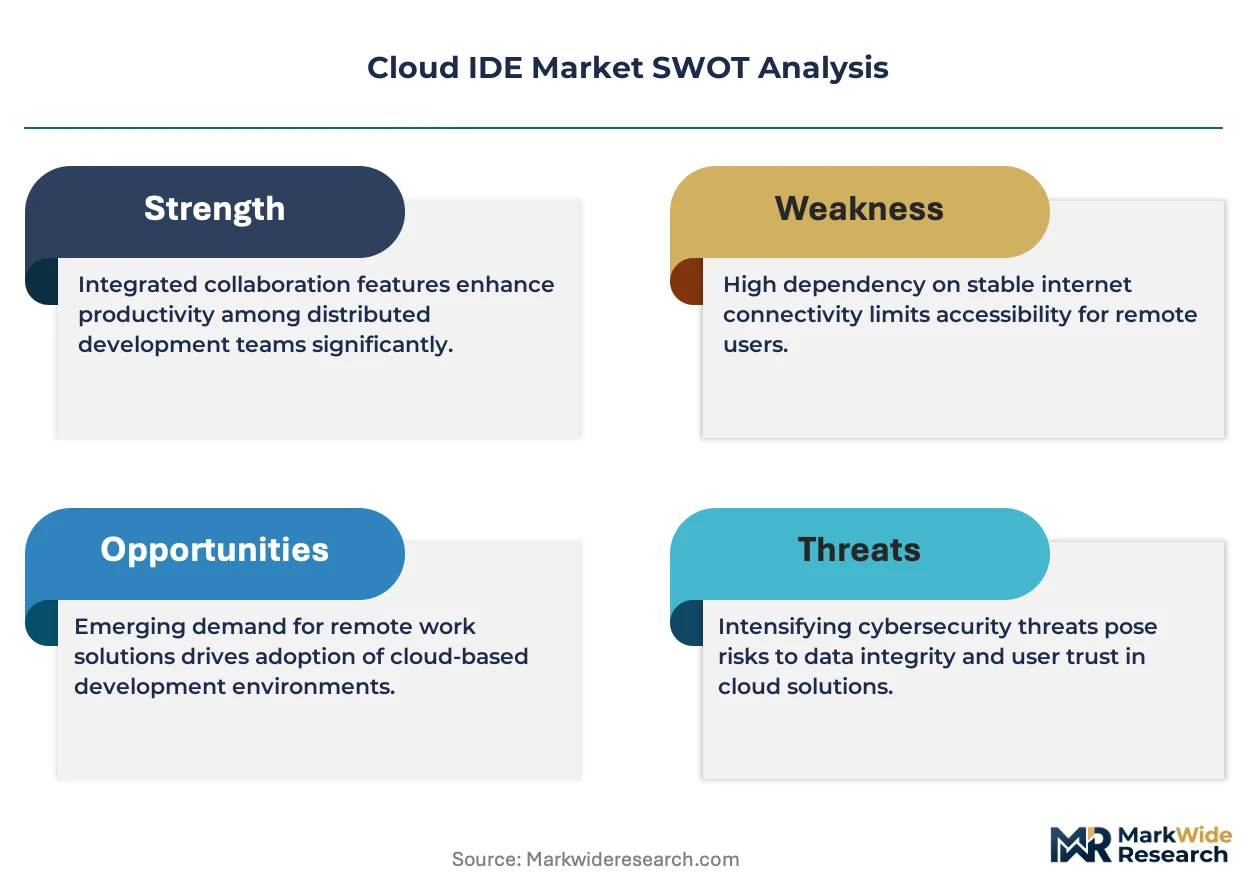
Cloud IDE Market Analysis
Enterprise procurement of cloud development environments is unwinding the historical dominance of individual developer licenses. GitHub Codespaces leverages Microsoft Azure infrastructure to anchor corporate accounts with seamless repository integration. AWS Cloud9 sustains its position among AWS-native organizations through deep service mesh connectivity. Replit competes aggressively for educational institutions and early-stage startup segments with freemium onboarding pathways.
A cloud integrated development environment delivers browser-accessible coding, debugging, and deployment capabilities through containerized workspace orchestration, typically provisioning compute instances with 2-16 vCPU cores and 4-64 GB RAM per developer session. Public cloud deployment models lead current infrastructure spend while hybrid cloud configurations capture the fastest growth as regulated industries partition sensitive codebases between tenant-controlled and provider-managed resources. Among service types, code collaboration modules command the strongest margin pools because real-time pair programming and AI-assisted review workflows lock enterprise teams into platform ecosystems.
The EU AI Act, GDPR, and ISO 27001 frameworks impose stringent audit trail and data residency requirements on development tools processing proprietary source code. The US SEC and HIPAA extend comparable governance pressure across financial services and healthcare software supply chains. Stakeholders must evaluate whether their chosen cloud IDE vendor maintains certifications spanning every jurisdiction where their development teams operate.
Market Dynamics
Enterprise procurement of cloud development environments is consolidating around centralized, auditable platforms as financial services and automotive firms abandon individual developer licenses under regulatory pressure from the EU AI Act and GDPR compliance mandates.
Growth Catalysts
- EU AI Act enforcement:Article 52 requirements for traceable AI development pipelines push financial institutions toward cloud IDEs with built-in audit logging and model lineage tracking.
- Container orchestration maturation:Kubernetes-native workspace provisioning enables automotive software teams in Germany to spin up standardized development environments for embedded systems validation.
- Remote engineering team distribution:Post-pandemic talent dispersion across Eastern European tech hubs drives demand for browser-accessible coding infrastructure with centralized security policy enforcement.
Market Restraints
- Cloud egress cost volatility:Data transfer fees from hyperscale providers create unpredictable operating expenditure for teams running large artifact repositories and container registries.
- Single-region infrastructure concentration:Dependence on Frankfurt and Dublin availability zones exposes European enterprises to localized service disruptions and data residency complications.
- Air-gapped development requirements:Defense contractors and classified program offices cannot adopt public cloud IDEs, limiting addressable market in national security verticals.
Strategic Opportunities
- ISO 27001-certified sovereign cloud partnerships:German automotive suppliers seek workspace platforms hosted on T-Systems or SAP infrastructure to satisfy procurement security questionnaires.
- Edge-IDE convergence:Integration between cloud development environments and edge deployment targets enables industrial automation engineers to prototype PLC code against live factory hardware.
- CSRD disclosure automation:Real-time carbon footprint tracking of compute-intensive build pipelines appeals to sustainability officers preparing scope 3 emissions reports.
Industry Challenges
- Multi-cloud credential federation:Engineering teams struggle to maintain consistent identity and access management across AWS, Azure, and GCP-hosted development workspaces without privilege sprawl.
- Legacy mainframe integration:Financial institutions running COBOL cores face friction connecting modern cloud IDEs to z/OS build systems and proprietary source control formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud IDE Market |
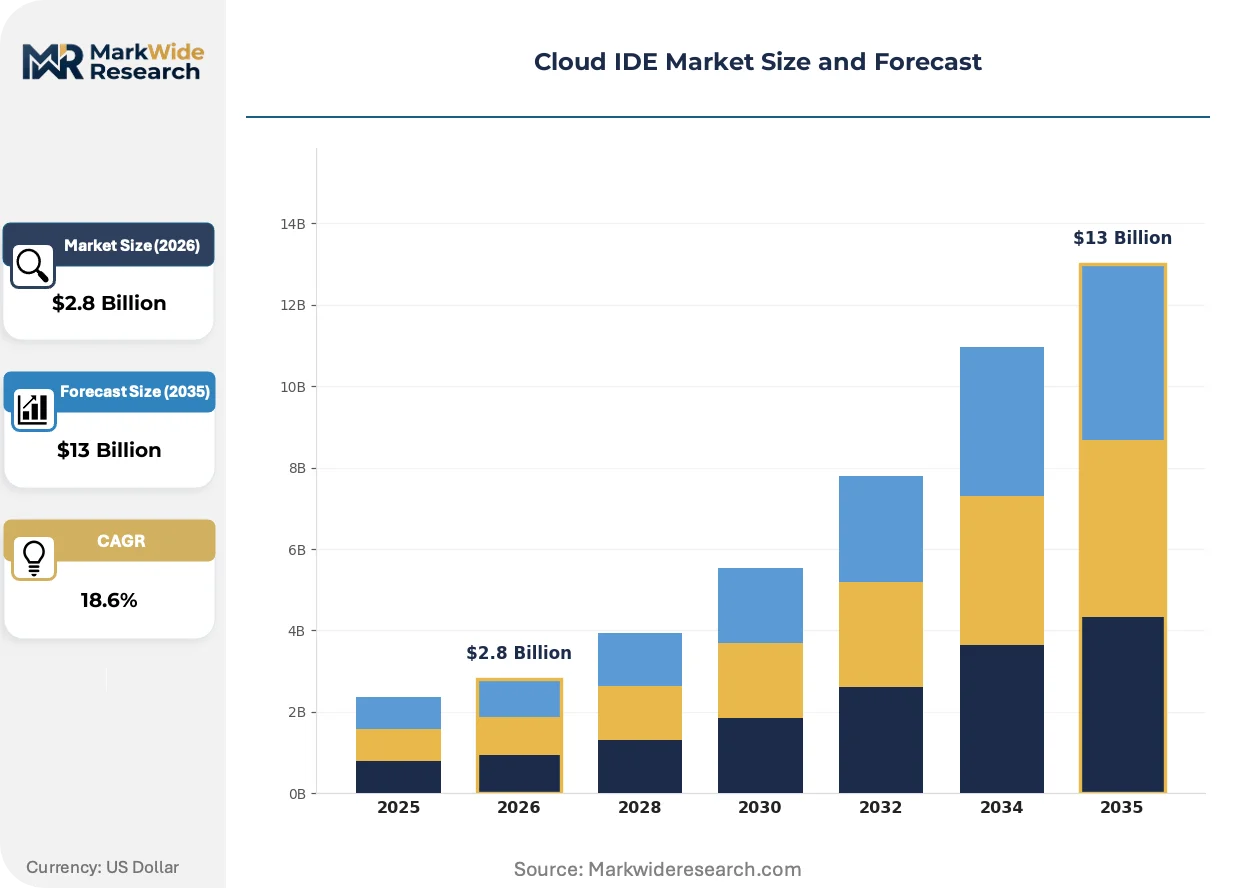
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Integrated Development Environment, Code Collaboration, Version Control, Debugging Tools End User: Enterprise, Startups, Educational Institutions, Freelancers Technology: Web-Based, Mobile IDE, Desktop Client, API Integration |
| Companies Covered | GitHub Codespaces, AWS Cloud9, Gitpod, IntelliJ IDEA Cloud Edition, Google Cloud Workstations, Microsoft Visual Studio Codespaces, JetBrains Space, Replit, Codeanywhere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud IDE Market Emerging Trajectories
Agentic AI coding assistants are compressing traditional software development lifecycles by automating boilerplate generation, test scaffolding, and documentation maintenance within integrated cloud environments.
Large language model-powered pair programming is displacing conventional code review workflows as GitHub Copilot and comparable tools embed directly into browser-based IDEs. Financial services developers in London and Singapore now expect real-time suggestion engines as standard workspace features. This capability compression is collapsing the distinction between authoring and review phases, forcing platform vendors to differentiate on model fine-tuning quality rather than basic autocomplete functionality.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for high-risk AI systems before deployment. Development teams building credit scoring or medical diagnostic models must now maintain immutable training data provenance and model versioning records. German automotive firms and Dutch health tech startups are retrofitting cloud IDE pipelines with automated compliance checkpoints to satisfy notified body audit requirements.
Consumption-based pricing for compute-intensive development tasks is fragmenting traditional seat-license models as organizations unbundle IDE access from build-minutes and GPU-accelerated testing. Early-stage biotechnology companies in Cambridge and Basel now negotiate separate contracts for coding workspace access versus molecular simulation workloads. This unbundling creates procurement complexity but enables precise cost allocation across research and engineering cost centers.
Cloud IDE Market Segmentation
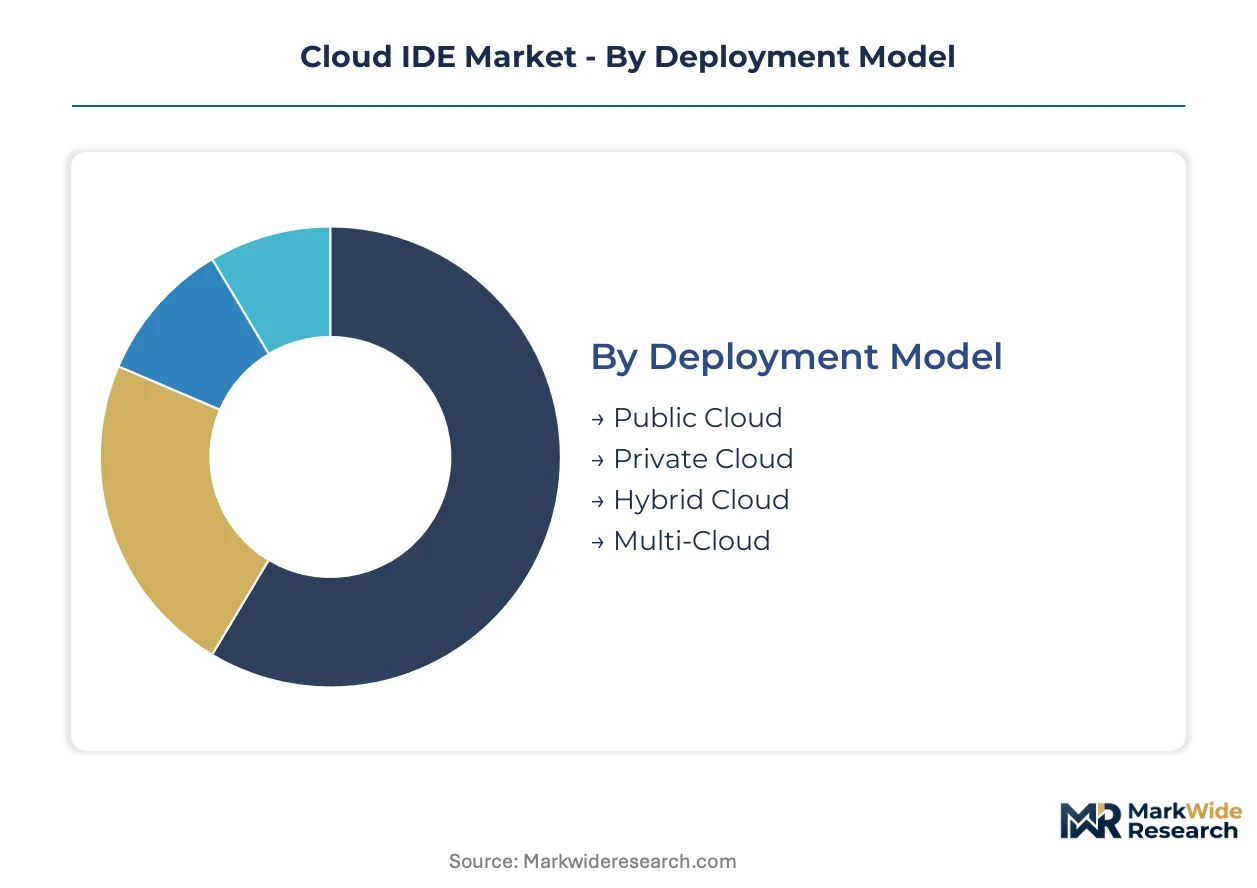
Cloud IDE procurement patterns diverge sharply across deployment models, service tiers, and user constituencies. Understanding these fault lines reveals where vendor substitution pressure concentrates and which segments command sustainable pricing power.
Deployment Model:
Public cloud configurations face the most intense substitution threat from hybrid alternatives as regulated industries partition sensitive workloads.
- Public Cloud:Fully managed infrastructure provisioned over shared hyperscale resources with elastic compute scaling. Financial services developers in London and Singapore dominate consumption here, though EU AI Act audit requirements are pushing some workloads toward sovereign alternatives.
- Hybrid Cloud:Split architecture partitioning proprietary source code on tenant-controlled infrastructure while delegating compute-intensive build pipelines to provider-managed resources. German automotive suppliers and Dutch health tech firms are retrofitting pipelines with automated compliance checkpoints to satisfy notified body audit requirements.
- Private Cloud:Single-tenant deployments on dedicated infrastructure with full data residency guarantees. Defense contractors and classified program offices require these configurations, though air-gapped development requirements limit addressable market expansion.
- Multi-Cloud:Orchestration layers spanning AWS, Azure, and GCP with unified credential federation. Engineering teams struggle to maintain consistent identity and access management without privilege sprawl.
Public cloud anchors the volume base while hybrid cloud gains share at the steepest rate.
Service Type:
Margin structures concentrate in collaboration modules where real-time pair programming creates sticky platform ecosystems.
- Code Collaboration:Real-time editing, AI-assisted review workflows, and synchronous pair programming environments. These modules command the strongest margin pools because they lock enterprise teams into integrated platform ecosystems with high switching costs.
- Integrated Development Environment:Browser-accessible coding, debugging, and deployment through containerized workspace orchestration. Demand concentrates among individual developers and small teams seeking standardized environments without local toolchain maintenance.
- Version Control:Git-native repository management with branch protection, merge queue automation, and immutable audit trails. EU AI Act Article 52 requirements for traceable development pipelines elevate these capabilities to procurement-critical status.
- Debugging Tools:Remote breakpoint configuration, log streaming, and performance profiling within containerized sessions. Biotechnology companies in Cambridge and Basel negotiate separate contracts for these compute-intensive capabilities versus basic workspace access.
Integrated development environments anchor the volume base while code collaboration expands most quickly.
End User:
Procurement authority is shifting from individual developers toward centralized IT governance as enterprise security questionnaires harden.
- Enterprise:Centralized procurement of cloud development environments with standardized security policy enforcement. Financial services and automotive firms are abandoning individual developer licenses under regulatory pressure from GDPR and the EU AI Act.
- Startups:Freemium onboarding pathways with consumption-based scaling as headcount grows. Early-stage companies prioritize rapid environment provisioning over compliance certification depth.
- Educational Institutions:Curriculum-integrated platforms with bulk licensing and pedagogical toolchains. Replit competes aggressively for this segment with simplified onboarding and classroom management features.
- Freelancers:Individual subscriptions with pay-as-you-go compute for sporadic project work. Price sensitivity here is acute, limiting vendor margin capture.
Enterprise accounts anchor the volume base while educational institutions climb the fastest as coding curriculum expands across secondary and tertiary systems.
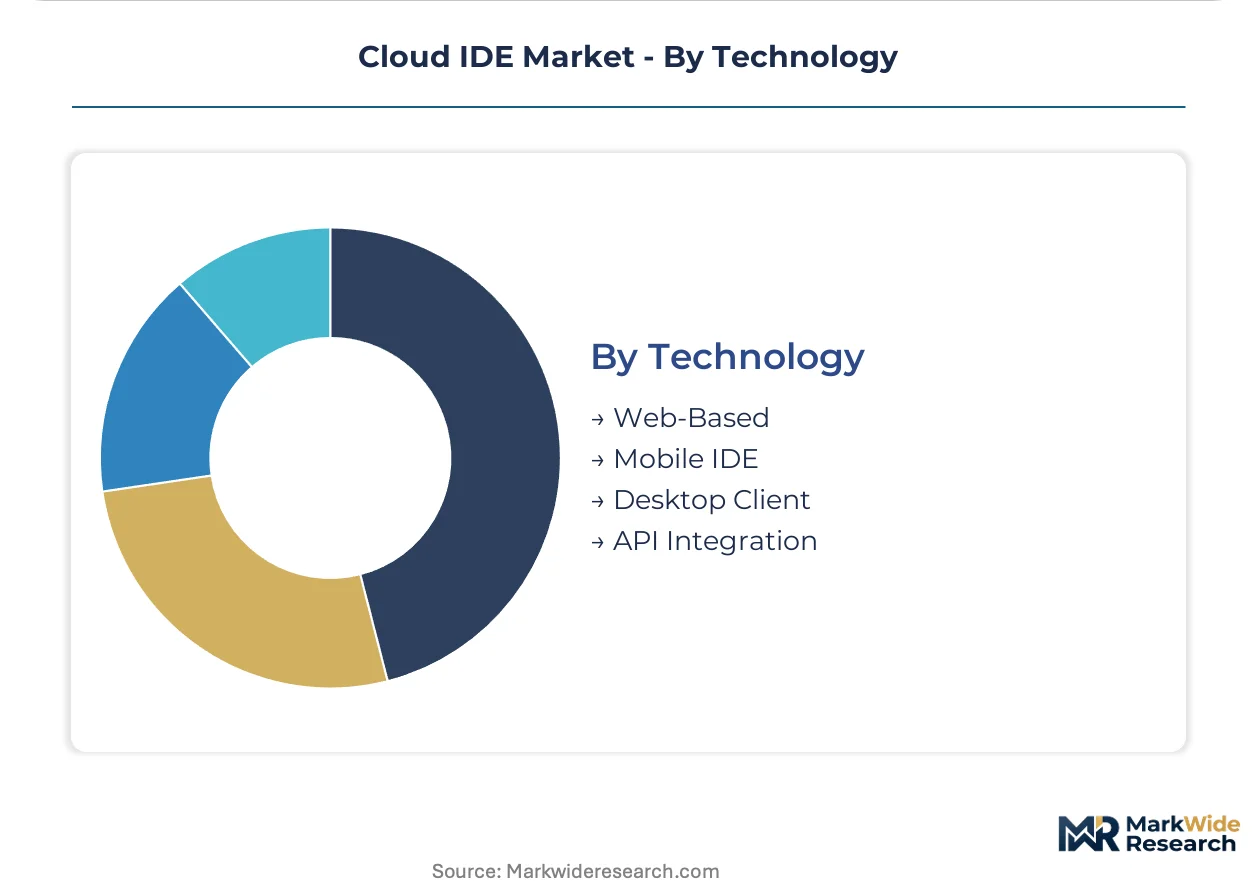
Technology:
Access modality determines integration depth with existing developer workflows and CI/CD pipeline architecture.
- Web-Based:Browser-native coding environments requiring zero local installation with automatic updates. Post-pandemic talent dispersion across Eastern European tech hubs drives demand for this accessibility profile.
- API Integration:Headless workspace orchestration through REST and GraphQL endpoints for custom toolchain embedding. Platform engineering teams at scale-ups favor this modality for embedding IDE capabilities into internal developer portals.
- Desktop Client:Electron-based or native applications with local caching for offline productivity. Legacy mainframe integration scenarios in financial services sometimes require these bridges to z/OS build systems.
- Mobile IDE:Touch-optimized interfaces for tablet-based code review and emergency hotfixes. Adoption remains niche given screen real estate constraints for complex debugging tasks.
Web-based delivery anchors the volume base while API integration shows the steepest expansion trajectory as platform engineering matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of cloud development environments concentrates among financial services clusters in London, automotive engineering hubs in Stuttgart and Munich, and emerging fintech centers in Singapore and Bangalore. Regulatory pressure from the EU AI Act and GDPR compliance mandates is reshaping vendor selection criteria across these buyer archetypes.
United States
Financial services developers in Manhattan and San Francisco dominate consumption of public cloud IDE infrastructure. SEC disclosure requirements and HIPAA compliance frameworks push healthcare software teams toward centralized, auditable development environments. The Boston biotechnology corridor drives demand for GPU-accelerated workspace provisioning for computational biology pipelines.
Germany
Automotive software engineering clusters in Stuttgart, Munich, and Wolfsburg consume premium workspace configurations for embedded systems validation. The EU AI Act Article 52 mandates traceable AI development pipelines, forcing suppliers to retrofit cloud IDE deployments with automated compliance checkpoints. T-Systems and SAP sovereign cloud partnerships satisfy procurement security questionnaires from tier-one automotive suppliers.
United Kingdom
London fintech developers and insurance technology teams anchor enterprise seat volume. Financial Conduct Authority operational resilience requirements intersect with GDPR data residency rules, pushing regulated firms toward hybrid cloud configurations. The Cambridge biotechnology ecosystem negotiates consumption-based pricing for compute-intensive molecular simulation workloads separate from basic workspace access.
India
Bangalore and Hyderabad technology campuses drive educational institution procurement alongside startup ecosystem adoption. Remote engineering talent dispersion across Pune and Chennai tech hubs creates demand for browser-accessible coding infrastructure with centralized security policy enforcement. The country's software services export sector prioritizes rapid environment provisioning over deep compliance certification.
Singapore
Wealth management technology teams and regional headquarters of multinational banks concentrate demand for real-time pair programming capabilities. The Monetary Authority of Singapore's technology risk management guidelines align with EU AI Act traceability expectations for algorithmic trading systems. Marina Bay financial district procurement favors platforms with seamless API integration into internal developer portals.
Cloud IDE Market Vendor Landscape
Player mix skews toward hyperscale cloud providers with integrated development environment offerings and specialized workspace-as-a-service vendors. Market structure consolidates around three strategic tiers: infrastructure-anchored platforms with deep service mesh connectivity, collaboration-centric suites emphasizing real-time editing workflows, and education-focused freemium providers. Dominant competitive moves include strategic partnerships with sovereign cloud operators and portfolio diversification into edge-IDE convergence capabilities.
Within the infrastructure-anchored tier, GitHub Codespaces and AWS Cloud9 exemplify platform ecosystems that lock enterprise teams through repository integration and service mesh depth. Replit occupies a distinct position targeting educational institutions and early-stage startups with simplified onboarding pathways. These three anchors represent the archetype spectrum from enterprise compliance depth to accessible freemium scaling.
| Leading Market Players |
|---|
| GitHub Codespaces |
| AWS Cloud9 |
| Gitpod |
| IntelliJ IDEA Cloud Edition |
| Google Cloud Workstations |
| Microsoft Visual Studio Codespaces |
| JetBrains Space |
| Replit |
| Codeanywhere |
| Others |
Supply Flow & Price Mechanics
ISO 27001 certification gates vendor qualification and price differentiation simultaneously, as German automotive suppliers and Dutch health tech firms will not onboard uncertified platforms regardless of cost position. This compliance threshold stratifies the vendor base into auditable premium tiers versus commodity workspace providers.
Pricing Analysis
Consumption-based contracts with hyperscale compute indexation dominate enterprise procurement, with pricing stratifying across premium, standard, and economy tiers based on compliance certification depth and data residency guarantees. Price differentiation rests on ISO 27001 audit scope and sovereign cloud partnership status. Cost compression in the standard tier is intensifying because educational institutions and startups negotiate freemium conversion rates aggressively. Freelancers exhibit acute price sensitivity while financial services procurement teams prioritize audit trail completeness over unit cost.
Supply Chain Analysis
Just-in-time workspace provisioning prevails among agile development teams, though German automotive suppliers maintain strategic stockpiles of containerized environment templates for embedded systems validation. Compute infrastructure concentrates in the United States, Germany, and Singapore, with raw material dependencies spanning hyperscale server hardware, GPU accelerators, and low-latency networking equipment. Single-region infrastructure concentration in Frankfurt and Dublin availability zones exposes European enterprises to localized service disruptions. Distribution runs through direct enterprise sales and self-service digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement cycles for cloud development environments track capital expenditure recovery patterns in financial services and automotive sectors, with normalization contingent on interest rate stabilization.
For Market Incumbents: Secure ISO 27001 certification expansions into T-Systems and SAP sovereign cloud partnerships before competitors capture German automotive procurement windows. Defend against hybrid cloud substitution by deepening service mesh connectivity with AWS-native organizations. Prioritize edge-IDE convergence capabilities for industrial automation engineers prototyping against live factory hardware.
For New Entrants and Emerging Players: Lead with API-first workspace orchestration targeting platform engineering teams at scale-ups embedding IDE capabilities into internal developer portals. Capture white-space in biotechnology companies negotiating separate contracts for compute-intensive molecular simulation workloads. Penetrate Eastern European tech hubs through browser-accessible infrastructure with centralized security policy enforcement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across code collaboration modules as AI-assisted review workflows reduce marginal compute costs per developer. Long-term viability favors platforms with sticky enterprise ecosystems locked through real-time pair programming capabilities. Monitor EU AI Act enforcement intensity across German automotive suppliers as inflection indicator for compliance-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | T-Systems certification unlocks tier-one German automotive supplier procurement pipelines. |
| Edge-IDE Convergence | Live factory hardware integration captures industrial automation engineering workflows. |
| Agentic AI Integration | Automated compliance checkpoints satisfy EU AI Act Article 52 audit requirements. |
| Consumption-Based Pricing Unbundling | Separate GPU-accelerated contracts enable precise cost allocation across research cost centers. |
| Educational Institution Freemium Scaling | Curriculum integration builds developer preference lock-in before enterprise procurement decisions. |
Methodological Framework
The analysis maps public cloud, hybrid cloud, private cloud, and multi-cloud deployment configurations, each validated through platform engineering directors, IT procurement officers, compliance auditors, and hyperscaler solution architects. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory filings, and cloud infrastructure spend databases. Bottom-up developer seat estimates triangulated against top-down enterprise IT budget allocations.
Consistency checks validated volume and value outputs against hyperscaler revenue segment disclosures and third-party cloud spend analytics across the projection horizon. Segmentation dimensions modeled include deployment model, service type, end-user category, and access technology, with regional adoption patterns as cross-cutting dimension. CAGRs derived from regression analysis of historical seat growth correlated with regulatory enforcement timelines and remote work policy normalization.
Underlying assumptions cover sustained EU AI Act enforcement intensity, hyperscale compute pricing stability, and enterprise security questionnaire standardization, with deviation risk concentrated in sovereign cloud procurement acceleration and air-gapped development requirement expansions. Revision becomes warranted when multi-cloud credential federation complexity crosses implementation abandonment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Web Service Cloud Market