
 Global Digital Intelligence Platform Market | 2026-2036
Global Digital Intelligence Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Intelligence Platform Market Foresight
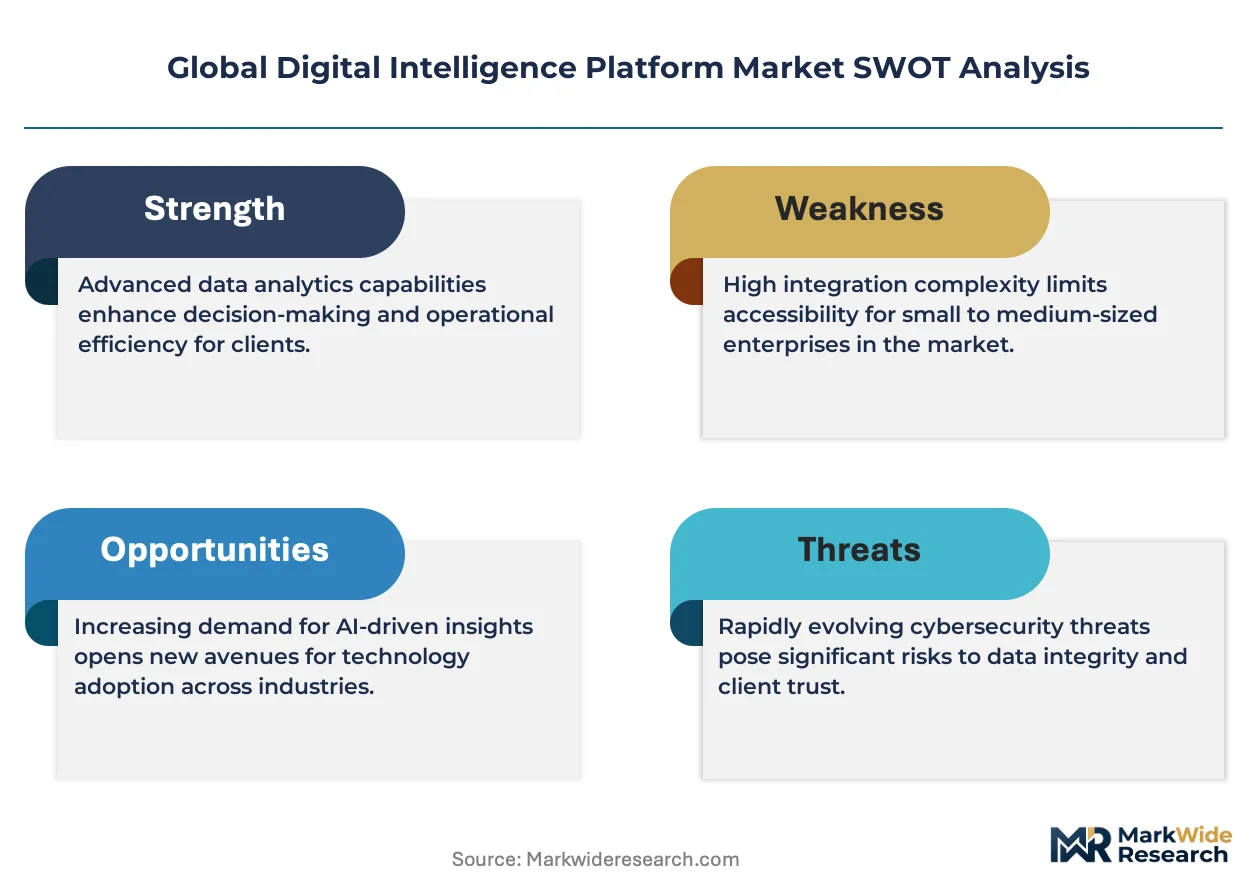
Data engineering talent scarcity is bifurcating the competitive landscape between vendors with captive AI/ML workforces and those dependent on contractor pipelines. IBM leverages its deep bench of quantum and AI researchers to sustain platform differentiation in enterprise analytics. Google anchors its digital intelligence stack within cloud-native infrastructure, competing directly with Microsoft, which extends Azure-based analytics through tight Office 365 integration. Oracle differentiates via database-to-intelligence pipelines that control enterprise data gravity.
A digital intelligence platform integrates data ingestion, processing, analytics, and visualization layers to transform raw operational signals into actionable business insights through machine learning inference and real-time dashboarding. These systems serve commercial and industrial users by automating pattern detection across transactional, behavioral, and sensor data streams. Cloud-based deployment models are capturing the fastest expansion as enterprises abandon on-premises infrastructure maintenance, while customer experience management solutions command premium pricing due to direct revenue linkage. Analytics platforms remain the largest solution type by installed base, though fraud detection applications within financial services are accelerating disproportionately.
The EU AI Act imposes risk-tiered compliance obligations on automated analytics deployed in European member states, forcing platform vendors to embed audit trails and human-in-the-loop controls. The U.S. SEC and FDA are separately tightening algorithmic transparency requirements for financial forecasting and clinical decision-support tools, narrowing market access for non-compliant providers. Japan's METI is promoting data-free flow with trust principles that ease cross-border analytics deployment. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmentation of product roadmaps and compliance architectures.
Market Dynamics
Real-time inference pipelines are compressing decision latency from hours to milliseconds, forcing platform vendors to rearchitect around edge-native compute and stream-processing fabrics rather than batch-oriented warehouses.
Growth Catalysts
- EU AI Act mandates:Automated decision-making systems in European member states now require embedded audit trails and human-in-the-loop controls, creating compliance-driven procurement cycles for certified platforms.
- Financial services fraud detection:Real-time transaction monitoring across payment networks is pulling investment into sub-100-millisecond inference engines with behavioral biometrics integration.
- Cloud-native infrastructure abandonment:Enterprises in the United States, Germany, and India are retiring on-premises data centers, accelerating subscription revenue for hosted analytics stacks.
Market Restraints
- GPU cluster cost volatility:Training and inference workloads depend on concentrated semiconductor fabrication in Taiwan, exposing platform operators to supply shocks and pricing spikes.
- Cross-border data friction:Divergent national data-localization regimes fragment unified analytics architectures, forcing redundant infrastructure deployment.
- Quantum-resistant cryptography transition:Migration timelines for post-quantum encryption standards remain undefined, freezing long-term security roadmaps for sensitive data processing.
Strategic Opportunities
- Brazilian enterprise modernization:Mid-market manufacturers in São Paulo and Rio de Janeiro lack captive data-science teams, creating white space for managed analytics services with Portuguese-language interfaces.
- Clinical decision-support convergence:FDA algorithmic transparency requirements for diagnostic tools are opening validated pathways for healthcare-specific platform modules.
- Edge-to-cloud orchestration:5G network slicing combined with containerized microservices enables distributed inference models that reduce backhaul costs for industrial sensor deployments.
Industry Challenges
- MLOps engineering scarcity:Pipeline automation, model versioning, and drift monitoring require specialized talent that commands premium compensation, constraining vendor scaling velocity.
- Legacy ERP integration complexity:SAP and Oracle database environments resist standard API connectivity, demanding custom connector development that extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Intelligence Platform Market |
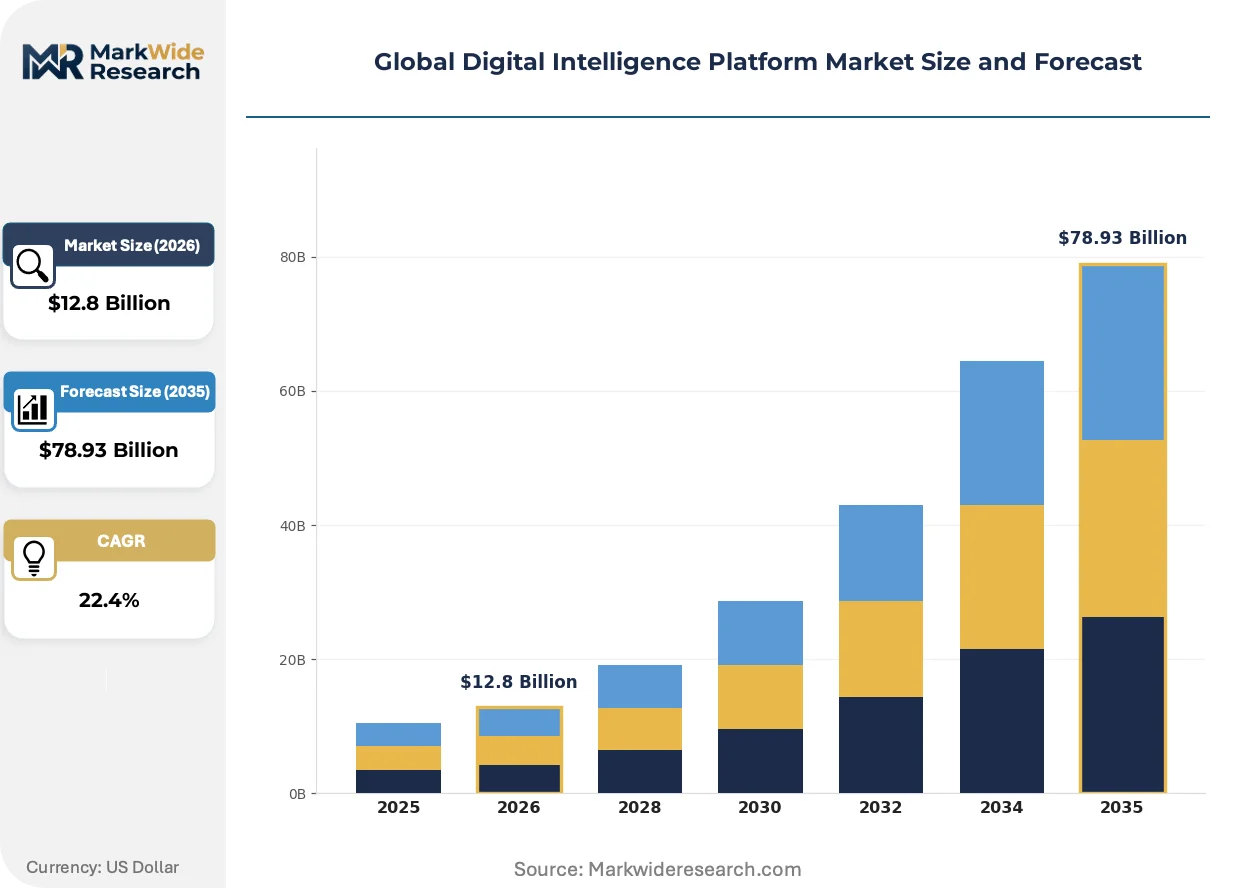
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $78.93 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Analytics Platform, Business Intelligence, Data Visualization, Performance Management, Customer Experience Management Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Software as a Service, Edge Computing Application Area: Marketing Optimization, Fraud Detection, Supply Chain Analysis, Product Development, Risk Management End User Industry: Telecom Operators, Financial Services, Manufacturing Enterprises, Government Agencies, Technology Providers |
| Companies Covered | IBM, Adobe Systems, SAS Institute, Google, Microsoft, Oracle, Optimizely, Mixpanel, New Relic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Intelligence Platform Market Shifts & Advancements
Foundation-model architectures are commoditizing natural-language interfaces, compressing differentiation toward proprietary data moats and vertical-specific fine-tuning capabilities.
Retrieval-augmented generation is displacing standalone business-intelligence dashboards by embedding contextual data queries directly into operational workflows. Financial services risk teams in New York and London are deploying these interfaces to interrogate transaction patterns conversationally rather than through static SQL reports. The shift is compressing analyst training cycles and collapsing the boundary between data consumers and technical specialists.
Japan's METI data-free flow with trust principles is easing cross-border analytics deployment for multinational enterprises operating across Tokyo, Singapore, and Sydney. The framework reduces legal review overhead for shared inference models while maintaining consent-chain documentation. Healthcare and automotive manufacturers are piloting federated learning architectures under these guidelines to train on distributed datasets without centralization.
Buyers in the United States and Germany are unbundling implementation services from platform subscriptions, demanding itemized Statements of Work for data-migration and change-management phases. Systems integrators are capturing margin that vendors previously folded into annual contracts, forcing platform providers to certify external implementation partners. The disaggregation is most visible in manufacturing verticals where shop-floor connectivity requires specialized OT/IT convergence expertise.
Global Digital Intelligence Platform Market Segmentation
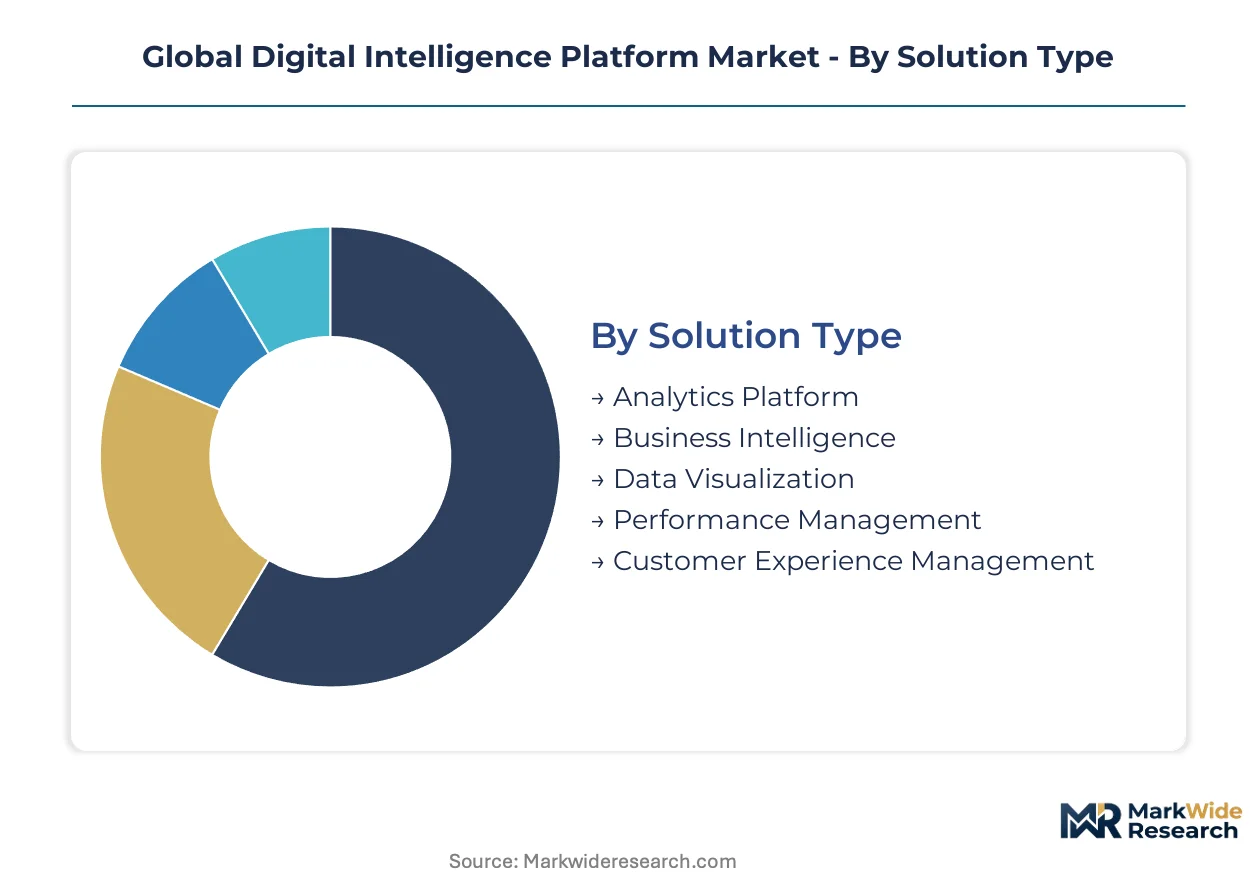
Platform architecture choices determine where vendors extract margin and where buyers face switching costs. Deployment models and solution types structure competitive positioning, while application areas and end-user industries shape feature roadmaps and compliance requirements.
Solution Type:
Margin pools concentrate in vertically integrated modules that bundle inference engines with industry-specific compliance tooling.
- Analytics Platform:Core engines ingest structured and unstructured data streams for pattern recognition and predictive modeling. Financial services firms in the United States and Germany deploy these systems for real-time transaction scoring, driven by SEC algorithmic transparency mandates.
- Customer Experience Management:Unified interfaces orchestrate behavioral data across touchpoints to personalize engagement at scale. Telecom operators in Japan and India prioritize these modules for churn reduction, with METI data-free flow principles easing cross-border deployment.
- Business Intelligence:Dashboard-centric tools aggregate historical performance metrics for executive reporting.
- Data Visualization:Interactive rendering layers translate complex datasets into explorable graphical formats.
- Performance Management:Goal-tracking systems align operational KPIs with strategic objectives through automated alerting.
Analytics Platform holds installed capacity. Customer Experience Management is rotating up the share rankings.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises builds from operational-expense cloud subscriptions.
- Cloud-Based:Fully managed infrastructure eliminates data center maintenance while enabling elastic compute scaling for training workloads. Enterprises in Brazil and India are migrating aggressively, abandoning owned hardware to redirect capital toward model development.
- Software as a Service:Pre-configured analytics stacks accelerate time-to-insight through standardized connectors and automated updates. Mid-market manufacturers in São Paulo lack captive engineering teams, creating demand for Portuguese-language managed services.
- On-Premises:Self-hosted deployments retain physical control over sensitive data assets.
- Hybrid Cloud:Split architectures keep regulated data local while bursting compute to public infrastructure.
- Edge Computing:Distributed inference nodes process sensor streams at the network periphery to minimize latency.
Cloud-Based commands the steepest expansion trajectory. Edge Computing is climbing the fastest among infrastructure categories.
Application Area:
Volume concentration tracks regulatory intensity, with compliance-driven procurement cycling through financial and healthcare verticals.
- Fraud Detection:Sub-100-millisecond inference engines monitor payment flows against behavioral biometric baselines. EU AI Act human-in-the-loop requirements are forcing platform upgrades across member states, creating certified procurement windows.
- Risk Management:Stress-testing and scenario-modeling modules quantify exposure across credit, operational, and market dimensions. Basel III implementation deadlines in Germany and France are expanding validation budgets for explainable analytics.
- Marketing Optimization:Campaign orchestration tools attribute revenue to channel spend through multi-touch algorithms.
- Supply Chain Analysis:Demand-forecasting and inventory-optimization engines reduce working capital requirements.
- Product Development:Voice-of-customer analytics and usage-pattern mining accelerate feature prioritization.
Fraud Detection holds installed capacity. Risk Management is gaining share fastest as regulatory frameworks tighten.
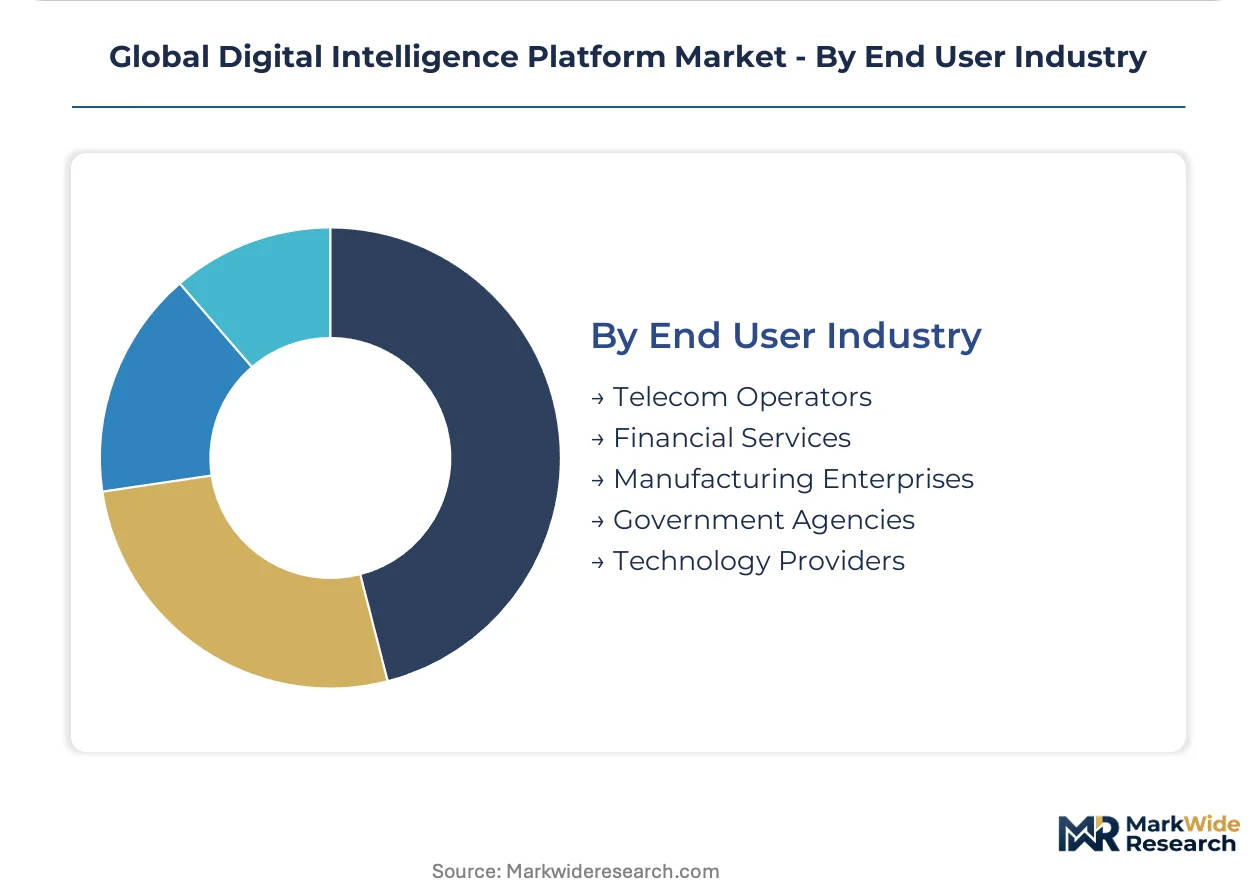
End User Industry:
Customer type maturity separates early adopters with captive data-science teams from laggards dependent on external implementation partners.
- Financial Services:Banks, insurers, and payment networks deploy real-time analytics for transaction monitoring, credit scoring, and regulatory reporting. FDA algorithmic transparency requirements for clinical decision-support tools are opening adjacent pathways for healthcare-specific modules.
- Telecom Operators:Network equipment providers and mobile carriers optimize infrastructure utilization through predictive maintenance and subscriber analytics. 5G network slicing in Japan and South Korea enables distributed inference models that reduce backhaul costs.
- Manufacturing Enterprises:Industrial firms apply sensor analytics to quality control and predictive maintenance.
- Government Agencies:Public sector deployments emphasize fraud detection in procurement and benefit administration.
- Technology Providers:Cloud and software vendors embed intelligence layers into their own product offerings.
Financial Services holds installed capacity. Telecom Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC anchors demand concentration in the United States, where financial services firms drive real-time analytics procurement. EU AI Act mandates are cycling compliance upgrades across European banking infrastructure. Japan's METI framework is easing cross-border deployment for Asia-Pacific operators.
United States
Financial services fraud detection and SEC algorithmic transparency requirements dominate enterprise procurement in New York and Chicago. The SEC mandates explainable audit trails for automated forecasting tools, narrowing vendor qualification. Boston and San Francisco clusters host dense concentrations of cloud-native platform deployments for healthcare and technology verticals.
Germany
Basel III implementation deadlines are expanding risk management validation budgets across Frankfurt and Munich banking centers. The EU AI Act imposes human-in-the-loop controls on automated credit scoring, forcing platform architecture upgrades. Industrial manufacturers in Baden-Württemberg are deploying edge-to-cloud orchestration for predictive maintenance on sensor networks.
Japan
Telecom operators in Tokyo and Osaka are prioritizing customer experience management modules for subscriber churn reduction. METI data-free flow with trust principles reduces legal overhead for federated learning pilots across Kanto and Kansai regions. Automotive manufacturers in Nagoya are piloting distributed inference models under these cross-border guidelines.
India
Mid-market enterprises in Mumbai and Bangalore are abandoning on-premises data centers for cloud-native analytics stacks. RBI guidelines on digital lending transparency are accelerating explainable AI procurement for fintech credit scoring. Hyderabad and Pune technology corridors are absorbing managed analytics services as captive data science teams remain scarce.
Brazil
Manufacturers in São Paulo and Rio de Janeiro lack internal engineering capacity, creating white space for Portuguese-language managed analytics. ANVISA data localization requirements for healthcare analytics are shaping platform deployment architectures. Industrial sensor deployments in Minas Gerais are driving edge computing adoption for reduced backhaul costs.
Global Digital Intelligence Platform Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying around cloud-native infrastructure and vertical-specific compliance tooling. The upper tier commands premium pricing through bundled inference engines and regulatory certification, while specialists compete on implementation velocity and domain expertise. Two strategic archetypes dominate: hyperscale cloud providers extending analytics through infrastructure integration, and database incumbents leveraging data gravity for platform stickiness. Competitive moves center on M&A for MLOps talent acquisition and strategic partnerships to bridge legacy ERP connectivity gaps.
Within the integrated leader tier, IBM and Oracle exemplify divergent approaches to enterprise platform positioning. IBM represents the captive research archetype, sustaining differentiation through deep benches of quantum and AI specialists. Oracle occupies the data gravity position, anchoring intelligence layers within database-to-analytics pipelines that control enterprise information flows. Microsoft and Google, as cloud-native hyperscalers, sit within the infrastructure-extension archetype, competing through tight productivity suite integration and elastic compute scaling respectively.
| Leading Market Players |
|---|
| IBM |
| Adobe Systems |
| SAS Institute |
| Microsoft |
| Oracle |
| Optimizely |
| Mixpanel |
| New Relic |
| Others |
Supply & Pricing Matrix
GPU cluster utilization rates above 80 percent in Taiwan and South Korea concentrate inference-capacity ownership among hyperscale cloud providers, compressing margin pools for mid-tier platform vendors and establishing subscription price floors tied to semiconductor access costs.
Pricing Analysis
Annual contract values in the United States run 40-60 percent above equivalent deployments in Brazil and India, reflecting differential labor costs for implementation services and compliance certification overhead. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade platforms with embedded audit trails from mid-market SaaS offerings and open-source-based deployments. Cost compression in the economy tier is intensifying because Brazilian manufacturers demand Portuguese-language interfaces without captive engineering premiums. Mid-market manufacturers in São Paulo and Rio de Janeiro exhibit highest price sensitivity; financial services firms in New York and Frankfurt demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Lead times for NVIDIA H100 and equivalent AI accelerators stretch 26-40 weeks, forcing platform vendors to pre-commit capacity 6-9 months ahead of customer deployment schedules. Taiwan, South Korea, and the United States anchor global supply of advanced semiconductors, with packaging and testing concentrated in Malaysia and Vietnam. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized cooling substrates. Single-source vulnerability around TSMC's 4nm and 5nm fabrication nodes exposes operators to geopolitical disruption. Distribution runs through direct hyperscaler marketplaces, systems integrator channels, and certified implementation partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in digital intelligence markets hinge on data gravity and inference-latency arbitrage, with API interoperability standards and cross-cloud model portability emerging as decisive ecosystem battlegrounds.
For Market Incumbents: Consolidate MLOps engineering talent through targeted acquisition of pipeline-automation specialists in Hyderabad and Berlin, defending against hyperscaler encroachment into on-premises edge deployments. Deepen backward integration into semiconductor capacity reservations to secure inference-hardware allocation priority. Embed EU AI Act certification documentation as a standard platform module to accelerate procurement cycles in Frankfurt and Paris.
For New Entrants and Emerging Players: Anchor in Brazilian mid-market manufacturing verticals where captive data-science teams remain scarce and Portuguese-language managed services command premium pricing. Target São Paulo industrial sensor deployments with edge-native inference offerings that reduce backhaul costs versus cloud-heavy incumbents. Pursue ANVISA healthcare analytics certification as a differentiated entry pathway against generalized platform providers.
For Investors and Strategic Acquirers: Specialist compliance-tooling vendors with embedded EU AI Act audit-trail capabilities represent priority acquisition targets, given regulatory cycling across European banking infrastructure. Long-term viability rests on model-portability architectures that reduce customer switching costs and sustain recurring revenue across multi-cloud deployments. Monitor FDA algorithmic transparency guideline finalization as an inflection signal for healthcare-specific platform module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding inference engines within SAP and Oracle database pipelines captures enterprise data gravity in Frankfurt and Chicago. |
| Acquisition of Specialist Firm | MLOps automation vendors with drift-monitoring capabilities address engineering scarcity constraining vendor scaling velocity. |
| Strategic Partnership | Systems integrator certification programs recapture implementation margin lost to unbundled procurement in German manufacturing. |
| Geographic Expansion | Portuguese-language managed services target São Paulo mid-market manufacturers lacking captive engineering teams. |
| Product Launch | Federated learning modules under METI data-free flow principles enable cross-border deployment for Tokyo healthcare operators. |
Research Methodology
The analysis maps analytics platforms, customer experience management modules, and fraud detection applications, each validated through platform engineering directors, enterprise IT procurement officers, and regulatory compliance leads at financial services firms. Primary interviews with CTOs, data science team leads, and systems integrator partners combined with secondary validation against SEC algorithmic transparency filings, EU AI Act implementation guidance, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulated against top-down market sizing across cloud-native, SaaS, and on-premises infrastructure categories.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment model, solution type, application area, and end-user industry vertical. CAGRs derived from regression analysis of historical adoption curves and forward-looking regulatory implementation timelines. Forecast inputs incorporated RBI digital lending transparency mandates, Basel III validation budget expansion, and METI cross-border data flow adoption rates.
Decision-makers should treat outputs as directional under assumptions of sustained GPU supply normalization and stable regulatory enforcement timelines; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding EU AI Act compliance adoption and cloud migration velocity in target geographies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Network Analytics Market
Analytics
Network Analytics Services Market
Analytics
Social Business Intelligence Market
Analytics
Global Data Analysis Software Market
Analytics
Europe Supply Chain Analytics Market
Analytics
India Big Data Technology and Service Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Content Analytics Market
Analytics
Product Analytics Market
Analytics
Global Sales Performance Management Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Israel ICT Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Connected Device Analytics Market
Analytics
Data Mining Tools Market
Analytics
Video Analytics Market