
 Europe Supply Chain Analytics Market | 2026-2036
Europe Supply Chain Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Supply Chain Analytics Market Intelligence
Multi-sourced data integration across tiered supplier networks is broadening the addressable scope for analytics vendors in Europe. SAP SE leverages deep ERP connectivity to anchor its position in manufacturing-centric deployments. Oracle Corporation sustains competitive pressure through cloud-native supply chain suites tailored to continental compliance requirements. IBM Corporation differentiates via AI-infused risk modeling capabilities that resonate with pharmaceutical and automotive buyers navigating ESG traceability mandates.
Supply chain analytics encompasses the systematic application of statistical modeling, machine learning algorithms, and network optimization techniques to procurement, inventory, and logistics data streams, typically processing terabyte-scale operational datasets to generate predictive insights on lead times, demand variability, and supplier performance. Its primary commercial purpose is to reduce working capital trapped in inventory buffers while maintaining service-level commitments across multi-echelon distribution networks. Software solutions command the dominant share of value capture given recurring subscription economics and embedded AI feature upgrades, while cloud deployment architectures are expanding fastest as hyperscaler infrastructure penetrates mid-market enterprises seeking elasticity without on-premises capital burden. Demand forecasting applications attract disproportionate R&D investment because accuracy improvements cascade directly into inventory carrying cost reductions and obsolescence risk mitigation.
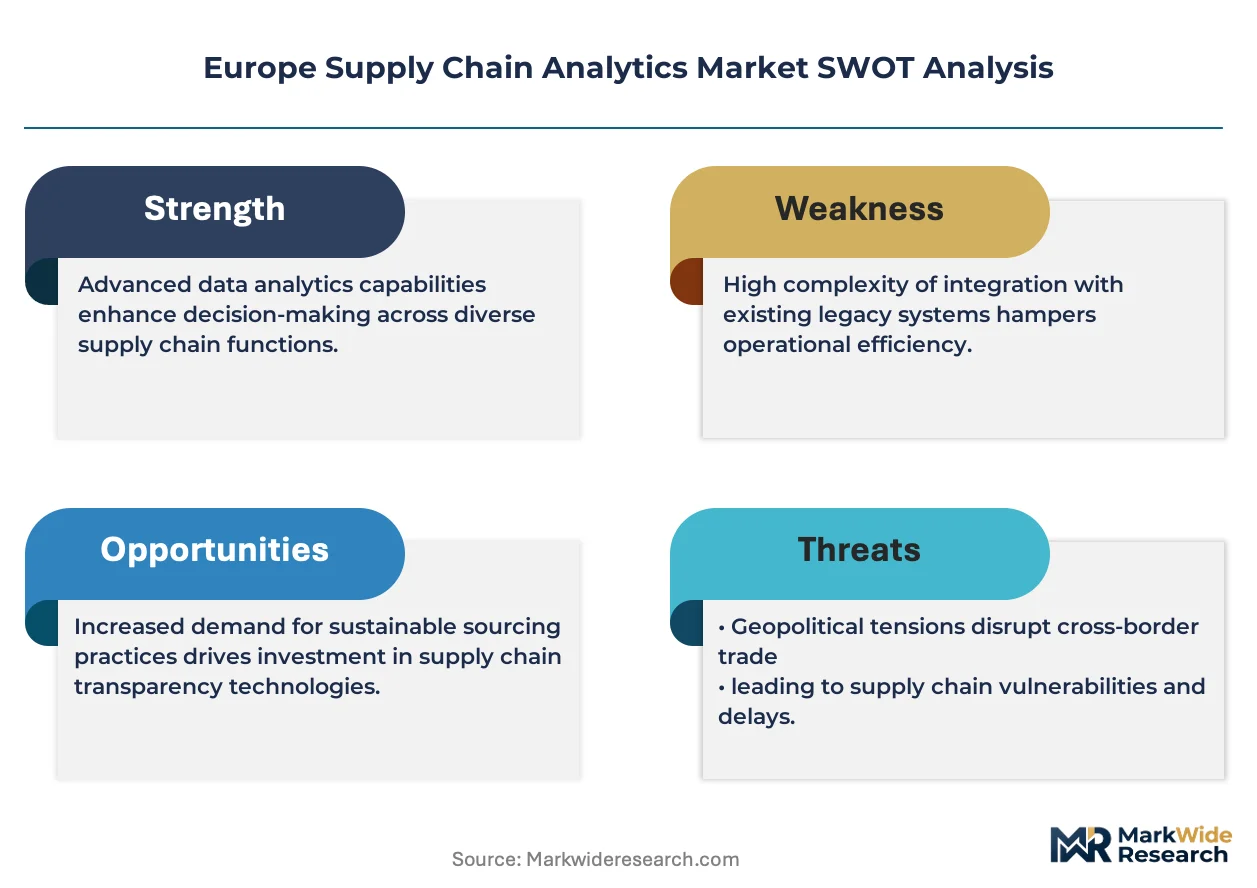
The EU AI Act imposes risk-classification requirements on automated decision systems used in supply chain planning, compelling vendors to embed explainability modules and human oversight protocols into algorithmic forecasting tools. ECHA's REACH framework extends chemical traceability obligations upstream, forcing analytics platforms to integrate substance-level genealogy tracking across multi-tier supplier networks. Stakeholders must weigh the capital efficiency of cloud migration against emerging data sovereignty requirements under GDPR and the proposed EU Data Act as they architect next-generation analytics infrastructure.
Market Dynamics
The EU AI Act's risk-classification framework for automated decision systems is forcing predictive logistics vendors to rebuild algorithmic architectures around explainability mandates and human-in-the-loop protocols.
Growth Catalysts
- ECHA REACH substance tracking:Chemical traceability obligations upstream through multi-tier supplier networks expand the functional scope required of analytics platforms.
- German automotive predictive logistics:OEMs and tier-1 suppliers are deploying machine learning models for demand-signal propagation across just-in-sequence assembly lines.
- Netherlands distribution hub concentration:Rotterdam and Venlo logistics clusters generate dense data volumes that reward real-time network optimization investments.
Market Restraints
- GDPR data sovereignty friction:Cross-border data flows for cloud-native analytics face jurisdictional fragmentation that complicates multi-country deployments.
- Legacy ERP integration debt:Mid-market manufacturers carry decades of on-premises system customization that resists API-based connectivity.
- Specialized talent scarcity:The intersection of supply chain operations research and machine learning engineering remains thinly staffed across continental Europe.
Strategic Opportunities
- France pharmaceutical cold chain:Temperature-sensitive biologics distribution creates demand for IoT-integrated risk modeling with EMA compliance documentation.
- EU CSRD scope expansion:Mandatory ESG disclosure requirements for large enterprises pull Scope 3 emissions analytics into procurement technology stacks.
- Digital twin convergence:Physics-based simulation married to operational data streams enables scenario planning for network disruption response.
Industry Challenges
- Algorithmic audit readiness:The EU AI Act's conformity assessment timelines compress vendor development cycles for high-risk supply chain applications.
- Multi-source data harmonization:Tier-2 and tier-3 supplier data arrives in incompatible formats that resist automated ingestion pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Supply Chain Analytics Market |
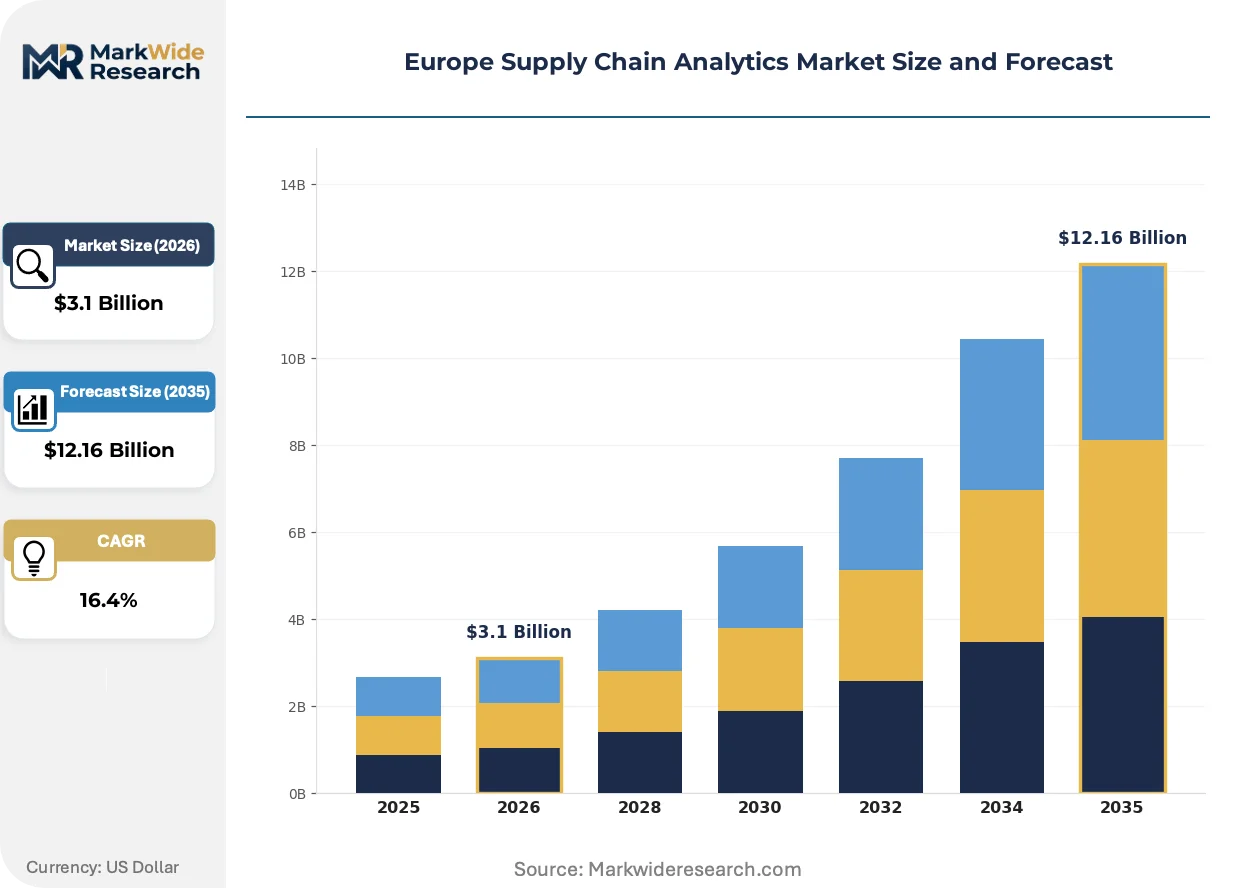
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Software, Consulting Services, Data Analytics, Integration Services End User: Manufacturers, Retailers, Logistics Providers, Wholesalers Deployment: Cloud, On-Premises, Hybrid, Edge Computing Application: Demand Forecasting, Inventory Management, Supplier Collaboration, Risk Management |
| Companies Covered | SAP SE, Oracle Corporation, IBM Corporation, Accenture PLC, SAS Institute Inc., Manhattan Associates, Inc., Genpact Limited, Kinaxis Inc., A.P. Moller - Maersk A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Supply Chain Analytics Market Strategic Shifts & Innovations
Generative AI architectures are penetrating demand forecasting workflows, compressing model development cycles while raising new questions about output reliability in production planning environments.
Federated learning protocols enable predictive model training across supplier networks without centralizing proprietary operational data. Automotive and pharmaceutical buyers in Germany and Belgium are piloting these architectures to satisfy GDPR constraints while improving forecast accuracy. This approach is rewriting competitive dynamics for cloud analytics vendors by reducing data migration friction that previously favored incumbents with deep ERP integration.
The EU AI Act's implementation timeline imposes conformity assessment requirements on high-risk automated decision systems used in supply chain planning. Vendors must embed explainability modules and human oversight mechanisms into algorithmic forecasting tools. Pharmaceutical manufacturers navigating EMA pharmacovigilance obligations face the steepest compliance burden, driving early procurement of audit-ready platforms.
Buyers are unbundling software procurement from implementation services, separating analytics platform licensing from systems integration contracts. Mid-market distributors in the Netherlands and France are driving this shift, preferring specialized boutique consultants over vendor-delivered professional services. This pattern concentrates pricing pressure on bundled offerings while opening margin opportunities for pure-play analytics vendors with robust API documentation.
Europe Supply Chain Analytics Market Segmentation
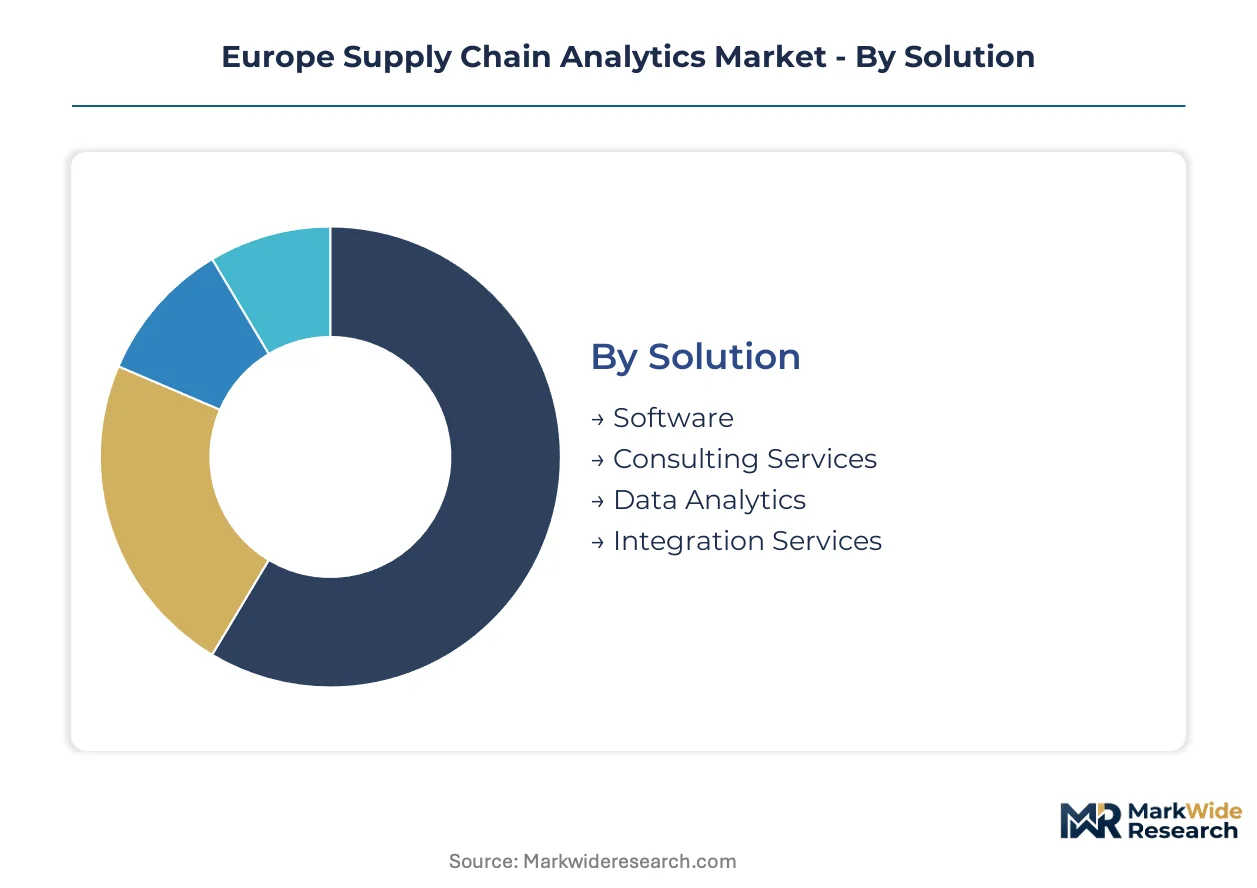
Supply chain analytics procurement patterns across Europe diverge sharply by solution type, deployment architecture, and end-user sophistication. Regulatory exposure under the EU AI Act and ECHA REACH creates tiered compliance burdens that reshape vendor selection criteria and implementation timelines.
Solution:
Software platforms face the steepest conformity assessment requirements under the EU AI Act's high-risk system classification, while consulting and integration services navigate lighter procedural obligations.
- Software:Subscription-based platforms embed machine learning modules for demand-signal processing and inventory optimization. German automotive OEMs and Dutch distribution hubs drive concentrated procurement of cloud-native suites with embedded explainability protocols mandated by algorithmic audit timelines.
- Consulting Services:Boutique advisory practices guide mid-market manufacturers through legacy ERP modernization and GDPR-compliant data architecture design. France and Belgium exhibit dense demand for specialized implementation support as enterprises unbundle software licensing from professional services.
- Data Analytics:Standalone analytical engines process terabyte-scale operational datasets for network optimization. Pharmaceutical cold chain operators in France prioritize IoT-integrated risk modeling with EMA documentation capabilities.
- Integration Services:API connectivity specialists bridge decades of on-premises ERP customization with modern cloud infrastructure. Mid-market manufacturers across the Netherlands and Germany confront the deepest integration debt.
Software sits at the top of the volume ranking, with Data Analytics climbing the fastest.
End User:
Cost-tier stratification separates enterprise-grade deployments from mid-market implementations, with compliance spending concentrated among the largest buyers.
- Manufacturers:Discrete and process manufacturers deploy predictive logistics platforms across just-in-sequence assembly lines. German automotive tier-1 suppliers generate dense demand for federated learning architectures that satisfy GDPR constraints while improving forecast accuracy.
- Retailers:Omnichannel distributors invest in real-time inventory positioning across store networks and fulfillment centers. Netherlands-based logistics clusters reward network optimization investments with measurable working capital reductions.
- Logistics Providers:Third-party operators leverage digital twin simulations for scenario planning around port congestion and modal disruptions. Rotterdam hub operators pilot physics-based operational modeling married to live data streams.
- Wholesalers:Bulk distributors focus on supplier collaboration tools and demand forecasting modules with shorter implementation horizons. French pharmaceutical wholesalers prioritize temperature-sensitive biologics tracking with EMA compliance integration.
Manufacturers command the largest addressable spend, with Logistics Providers expanding most quickly.
Deployment:
Application maturity varies by architecture, with edge-native solutions still navigating standardization gaps while cloud and hybrid models accumulate operational track records.
- Cloud:Hyperscaler-hosted analytics suites deliver elasticity without capital burden. Mid-market enterprises across France and the Netherlands accelerate migration despite GDPR data sovereignty friction complicating cross-border flows.
- On-Premises:Captive infrastructure persists where chemical traceability under ECHA REACH demands localized data retention. German automotive manufacturers maintain hybrid estates for sensitive supplier performance data.
- Hybrid:Split architectures partition sensitive forecasting workloads on-premises while pushing computational intensity to cloud instances. Pharmaceutical manufacturers navigating EMA pharmacovigilance obligations favor this model for audit readiness.
- Edge Computing:Distributed processing nodes enable real-time decisioning at warehouse and production line level. Belgian automotive plants pilot edge-native demand-signal propagation with reduced latency.
Cloud deployments hold the dominant volume position, with Hybrid architectures gaining share fastest.
Application:
Customer type stratification separates transactional procurement tools from strategic planning systems, with risk management attracting premium pricing for ESG traceability integration.
- Demand Forecasting:Algorithmic models predict lead times and demand variability across multi-echelon networks. Accuracy improvements cascade directly into inventory carrying cost reductions, attracting disproportionate R&D investment from software vendors.
- Inventory Management:Multi-echelon optimization reduces working capital trapped in buffer stock while maintaining service-level commitments. Retailers in the Netherlands concentrate procurement of real-time positioning tools.
- Supplier Collaboration:Tiered data sharing platforms extend visibility upstream through multi-tier supplier networks. ECHA REACH substance tracking obligations expand functional scope requirements for chemical manufacturers.
- Risk Management:AI-infused modeling capabilities address network disruption response and ESG traceability mandates. Pharmaceutical and automotive buyers in Germany prioritize audit-ready platforms with embedded explainability modules.
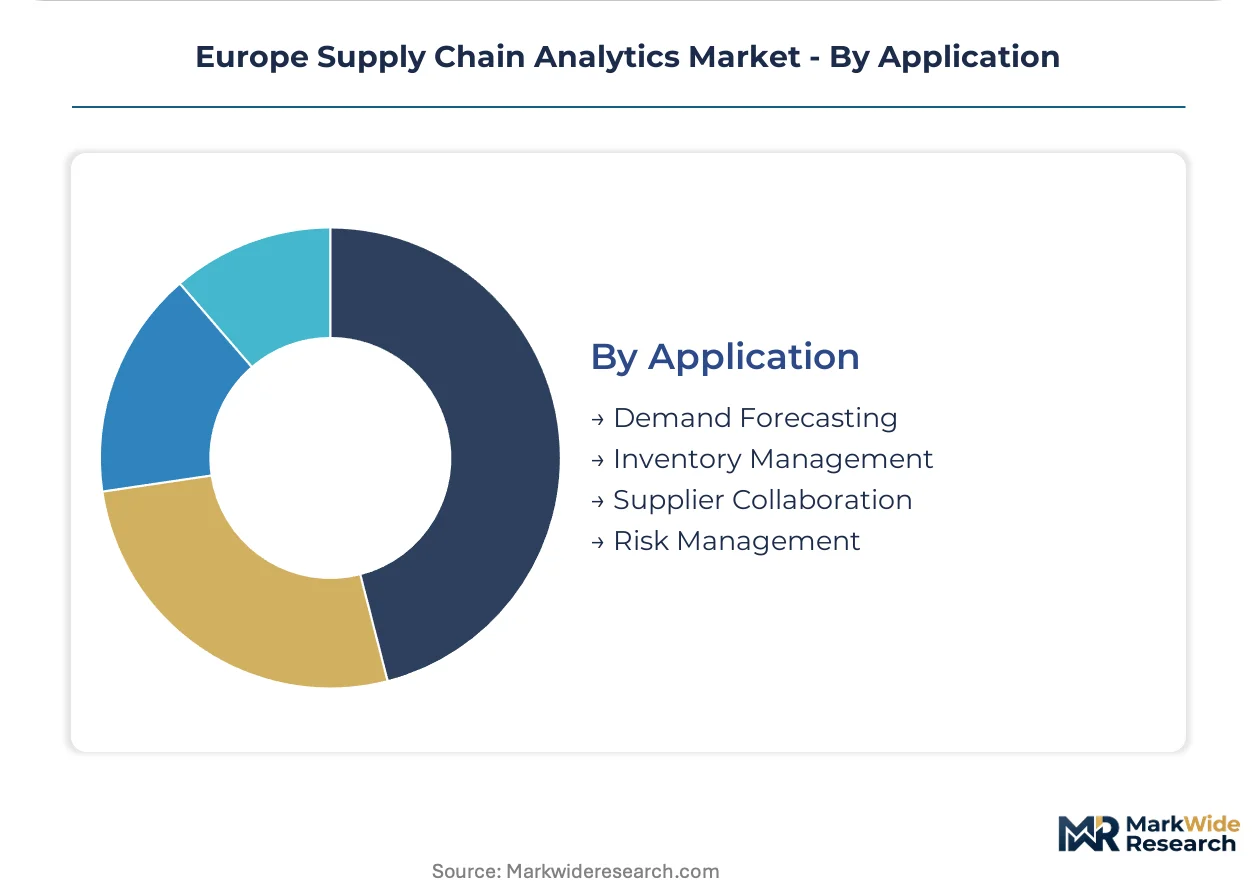
Demand Forecasting leads by installed base, with Risk Management showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's logistics corridor anchors European supply chain analytics demand. German automotive clusters and French pharmaceutical hubs generate concentrated procurement of predictive platforms. Regulatory fragmentation under GDPR and the EU AI Act reshapes cross-border deployment architectures.
Germany
Automotive OEMs and tier-1 suppliers deploy machine learning models for just-in-sequence assembly synchronization. The EU AI Act's high-risk system classification compels vendors to embed explainability modules into algorithmic forecasting tools. Stuttgart and Munich manufacturing clusters drive dense demand for federated learning architectures that satisfy GDPR constraints.
France
Pharmaceutical cold chain operators invest in IoT-integrated risk modeling for temperature-sensitive biologics distribution. EMA pharmacovigilance obligations steepen compliance burdens for automated decision systems. Île-de-France and Lyon logistics hubs concentrate procurement of audit-ready platforms with embedded human oversight protocols.
Netherlands
Rotterdam and Venlo distribution clusters generate terabyte-scale operational datasets that reward real-time network optimization investments. The proposed EU Data Act intensifies data sovereignty scrutiny for cross-border cloud analytics flows. Mid-market distributors here unbundle software procurement from implementation services, preferring specialized boutique consultants.
United Kingdom
Post-Brexit customs complexity drives demand for multi-tier supplier visibility platforms. The UK Information Commissioner's Office enforces GDPR-equivalent data protection standards that complicate continental data sharing. London financial services and Midlands manufacturing clusters pilot hybrid deployment architectures partitioning sensitive workloads on-premises.
Belgium
Pharmaceutical manufacturers in the Flanders region navigate EMA and EU AI Act dual compliance obligations. Brussels-based logistics providers leverage digital twin simulations for scenario planning around port congestion. Antwerp's chemical processing corridor demands substance-level genealogy tracking under ECHA REACH upstream traceability mandates.
Europe Supply Chain Analytics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-native specialization and API-first architectures. The vendor landscape stratifies across three maturity tiers: legacy ERP-integrated incumbents, hyperscaler-aligned challengers, and boutique analytics specialists. Dominant competitive moves include portfolio diversification into ESG traceability modules and strategic partnerships with industrial IoT platform vendors.
Within the ERP-anchored tier, SAP SE and Oracle Corporation exemplify incumbents leveraging deep manufacturing connectivity to defend installed base positions. IBM Corporation occupies a distinct position in AI-infused risk modeling, resonating with pharmaceutical and automotive buyers navigating ESG disclosure mandates. These three anchors represent contrasting strategic postures: embedded workflow integration, cloud-native compliance suites, and explainable AI governance tooling.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Accenture PLC |
| SAS Institute Inc. |
| Manhattan Associates, Inc. |
| Genpact Limited |
| Kinaxis Inc. |
| A.P. Moller - Maersk A/S |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through subscription pricing tiers for supply chain analytics platforms, with hyperscaler compute fees compressing margins for mid-market SaaS vendors serving Dutch distribution hubs and German automotive clusters. This input-cost pass-through intensifies as GDPR data sovereignty requirements force regional data center localization, elevating delivery costs for cross-border deployments.
Pricing Analysis
Input-cost pass-through from hyperscaler infrastructure fees shapes SaaS subscription tiers across the European market. Price differentiation rests on explainability module depth mandated by EU AI Act compliance tiers and federated learning architecture availability for GDPR-constrained automotive buyers. Pricing pressure stems from boutique consulting unbundling, which strips implementation margins from bundled vendor offerings. Mid-market wholesalers exhibit highest price sensitivity due to shorter implementation horizons, while pharmaceutical manufacturers navigating EMA pharmacovigilance obligations show lowest sensitivity for audit-ready platforms.
Supply Chain Analysis
CE marking and ISO 27001 certification gating restrict vendor qualification for EU AI Act high-risk system deployments, filtering platform providers serving German automotive OEMs and French pharmaceutical cold chain operators. Software development concentrates in Ireland, Germany, and the Netherlands, with cloud infrastructure sourcing from hyperscaler regions in Frankfurt, Amsterdam, and Dublin. Supply chain risk centers on single-source vulnerability for specialized machine learning engineering talent across continental Europe. Distribution runs through direct enterprise sales supplemented by boutique systems integrators in France and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European supply chain analytics procurement has shifted toward premium specifications as EU AI Act compliance deadlines harden demand for embedded explainability and human-in-the-loop protocols.
For Market Incumbents: Hedge against boutique consulting unbundling by deepening API documentation and partner certification programs that capture implementation value without direct service delivery. Acquire specialized federated learning capabilities to defend against hyperscaler-aligned challengers penetrating GDPR-sensitive German automotive accounts. Prioritize ESG traceability module development as EU CSRD scope expansion pulls Scope 3 emissions analytics into mandatory procurement stacks. For New Entrants and Emerging Players: API-first documentation and self-service onboarding platforms open routes into mid-market Dutch distributors that have rejected vendor-delivered professional services. Target Belgian pharmaceutical manufacturers navigating dual EMA and EU AI Act compliance obligations with audit-ready risk management modules. Pursue vertical specialization in temperature-sensitive biologics tracking for French cold chain operators seeking EMA-integrated IoT solutions. For Investors and Strategic Acquirers: Consolidation pressure builds where boutique analytics specialists accumulate federated learning expertise and pharmaceutical compliance track records that larger platforms lack. The five-to-ten-year viability window favors vendors with embedded explainability architectures and established EMA documentation workflows. Watch for inflection where EU AI Act conformity assessment deadlines trigger accelerated replacement cycles for non-compliant legacy forecasting tools.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures capture mid-market distributors unbundling software from implementation services in the Netherlands. |
| Acquisition of Specialist Firm | Federated learning boutiques add GDPR-compliant model training capabilities for German automotive tier-1 suppliers. |
| Product Launch | ESG traceability modules address EU CSRD Scope 3 emissions disclosure mandates pulling analytics into procurement stacks. |
| Strategic Partnership | Industrial IoT platform alliances enable real-time cold chain monitoring for French pharmaceutical biologics distribution. |
| Geographic Expansion | Rotterdam and Venlo hub presence captures dense data volumes rewarding network optimization investments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with supply chain analytics vendors, automotive procurement officers, pharmaceutical logistics directors, and cloud infrastructure specialists with secondary validation against SEC filings, EU regulatory databases, hyperscaler capex disclosures, and trade association reports. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from ERP vendor disclosed install bases and cloud migration patterns.
Comparable historical periods anchored growth trajectory assumptions across the projection horizon, with segmentation modeling spanning deployment architecture, end-user sophistication tier, application functional scope, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated baseline estimates, incorporating EU AI Act implementation timelines and ECHA REACH substance tracking expansion as industry-specific demand drivers.
The model assumes a particular technology adoption path; alternative pathways for generative AI demand forecasting would alter the outlook if output reliability concerns delay production deployment. Forecasts reflect documented assumptions about regulatory enforcement intensity and cloud migration elasticity. A model refresh is warranted upon material change in EU AI Act conformity assessment timelines or hyperscaler data sovereignty localization requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Event Stream Processing Market
Analytics
Mobile Analytics Market
Analytics
Weather Data Services Market
Analytics
TV Analytics Solutions Market
Analytics
Manufacturing Analytics Market
Analytics
Global Enterprise Performance Management Market
Analytics
Prescriptive Analytics Market
Analytics
Europe Operational Intelligence Market
Analytics
Global Customer Analytics Market
Analytics
Global Analytics Software Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Business Analytics Market
Analytics
Crowd Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Sentiment Analytics Market
Analytics
US Video Analytics Market