
 Women's Watch Market | 2026-2036
Women's Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Watch Market Analytics
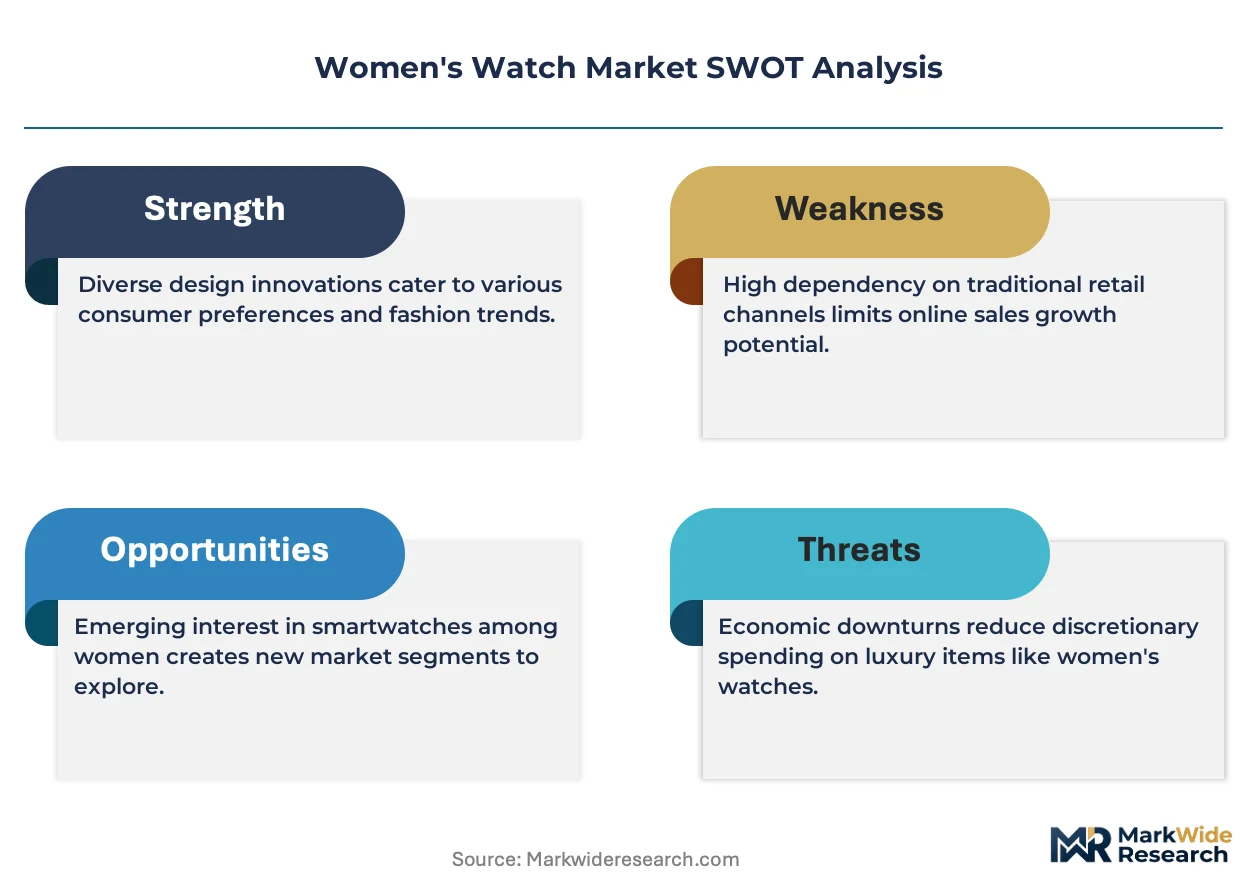
Smart connectivity integration is tilting how women's watches deliver biometric tracking and mobile payment functionality beyond traditional timekeeping. Rolex leverages its vertically integrated manufacturing to sustain exceptional quality control across precious metal cases and in-house calibers. Cartier anchors its position through jewelry-house heritage, while Audemars Piguet differentiates via complex movement expertise in the high-complications segment.
A women's watch is a precision-engineered timekeeping instrument designed for female wrist proportions, typically featuring case diameters between 26mm and 38mm, with movements ranging from quartz oscillators to manually wound mechanical calibers, serving both functional horology and personal adornment purposes. The luxury price tier commands the dominant margin pool, sustained by scarcity marketing and authorized dealer network control. Smart watches represent the fastest-expanding product type, though analog mechanical pieces retain collector-driven resilience in the dress and casual style categories.
Swissmedic governs medical-device claims for heart-rate and blood-oxygen sensors embedded in smart watch models, while REACH and RoHS constrain heavy-metal content and chemical safety in European-sold units. The EU AI Act will soon classify algorithmic health recommendations from wearable software, reshaping firmware development obligations. Stakeholders must weigh whether to pursue medical-grade certification for sensor arrays or remain in the lifestyle-accessory tier as regulatory boundaries harden.
Market Dynamics
Smart sensor integration is digitizing how women's watches deliver biometric functionality, forcing traditional Swiss houses to reconfigure R&D roadmaps around health-data compliance while Asian contract manufacturers capture volume in connected modules.
Growth Catalysts
- EU AI Act classification:Algorithmic health recommendations from wearable firmware face new regulatory categories, creating first-mover advantage for firms pursuing medical-grade certification pathways.
- Luxury gifting among professional women:Corporate milestone celebrations and self-purchase occasions expand addressable demand beyond traditional gift-giving calendar constraints.
- China tier-one city concentration:Domestic brands and Swiss houses compete for share in Shanghai, Beijing, and Shenzhen, where disposable income density supports premium price points.
Market Restraints
- Precious metal input volatility:Gold and platinum price swings compress margin predictability for mechanical caliber producers dependent on case and bracelet materials.
- Swiss movement supply concentration:ETA and Sellita dominate ebauche supply, creating bottleneck risk for independent brands without in-house manufacturing.
- Nickel release limits under REACH:European import compliance requires material reformulation or alternative alloys, raising certification costs for non-EU manufacturers.
Strategic Opportunities
- India metro expansion:Mumbai, Delhi, and Bangalore present underpenetrated demand for mid-luxury mechanical pieces as professional female workforce participation rises.
- Medical-grade sensor convergence:Integration of photoplethysmography and electrocardiography arrays enables differentiation beyond lifestyle tracking.
- Direct-to-consumer channel innovation:Brand-owned e-commerce and appointment-only boutiques bypass wholesale margin compression in traditional authorized dealer networks.
Industry Challenges
- Horological movement engineering talent scarcity:Master watchmaker training programs face demographic gaps, constraining capacity expansion for complications production.
- Swissmedic certification timelines:Medical-device claims for heart-rate and blood-oxygen sensors require extended validation cycles, delaying product launches.
- Legacy inventory obsolescence:Analog quartz inventory loses velocity as smart connectivity becomes baseline expectation in entry and mid-tier segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Watch Market |
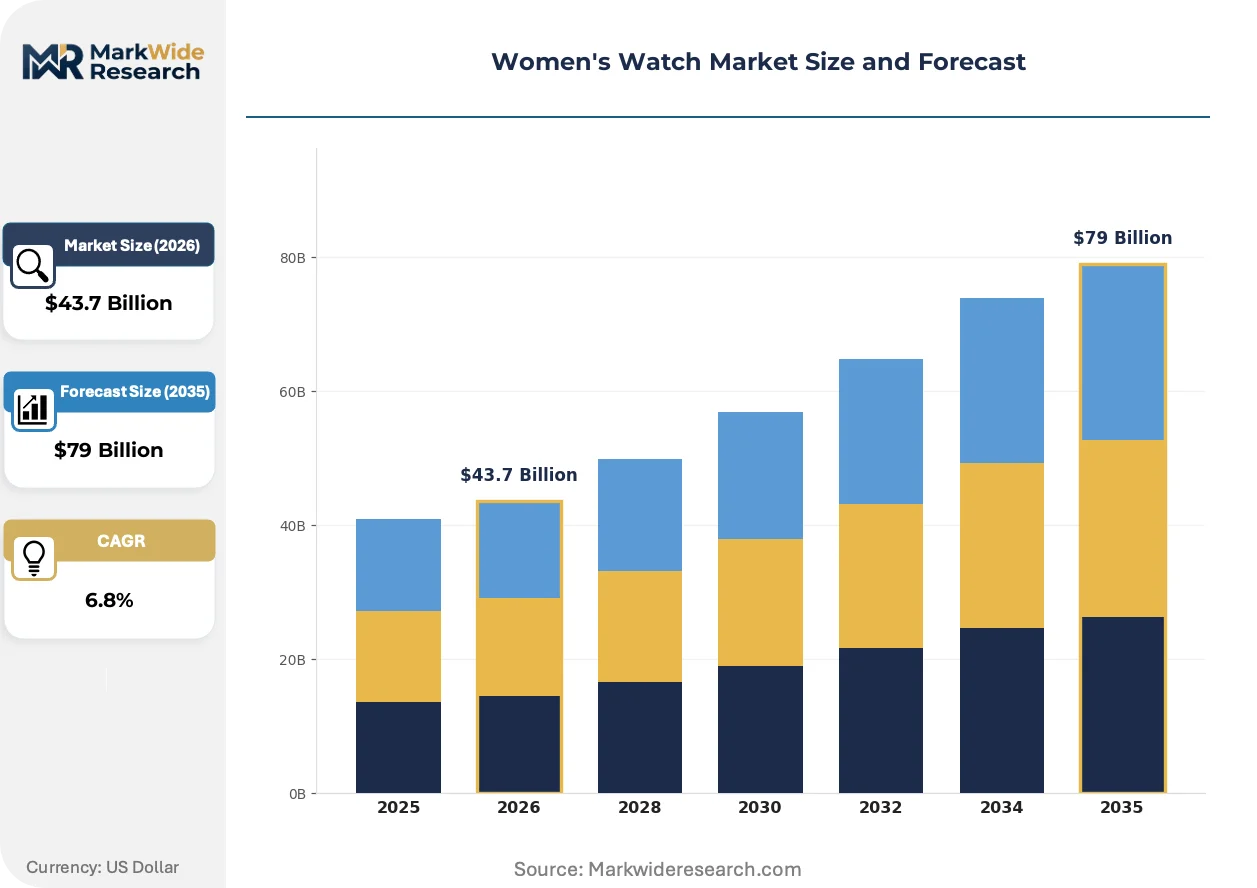
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Smart Material: Stainless Steel, Leather, Ceramic, Plastic Style: Casual, Dress, Sports, Fashion Price Tier: Luxury, Mid-range, Budget, Premium |
| Companies Covered | Patek Philippe, Breitling, Cartier, Hublot, Longines, Rolex, Tag Heuer, Jaeger-LeCoultre, Audemars Piguet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Watch Market Evolving Landscape
Biometric sensor miniaturization and algorithmic health coaching are compressing the boundary between timepiece and medical device, requiring firmware architectures that satisfy both CE marking and lifestyle aesthetics.
Miniaturized photoplethysmography arrays are digitizing continuous heart-rate and blood-oxygen monitoring in 38mm case formats previously reserved for quartz movements. Premium smart watch buyers in North American and European urban centers now expect clinical-grade accuracy from wrist-worn sensors. This capability compression is forcing analog houses to partner with semiconductor foundries or cede the health-data layer entirely.
REACH and RoHS constraints on heavy-metal content are tightening material substitution requirements for European-sold units, particularly affecting case alloys and battery chemistries in smart models. Manufacturers must maintain dual supply chains: compliant alloys for EU markets and cost-optimized alternatives elsewhere. High-volume producers with Shenzhen and Dongguan assembly footprints face the steepest reformulation costs.
Certification-driven preference shifts are reshaping how professional women evaluate purchase decisions, with medical-grade sensor validation displacing brand heritage as the primary selection criterion in the 35-50 age cohort. Authorized dealer networks in Germany and Switzerland report elongated consideration cycles as buyers compare FDA-cleared and CE-marked feature sets. This diligence pattern is most pronounced among healthcare and finance sector professionals.
Women's Watch Market Segmentation
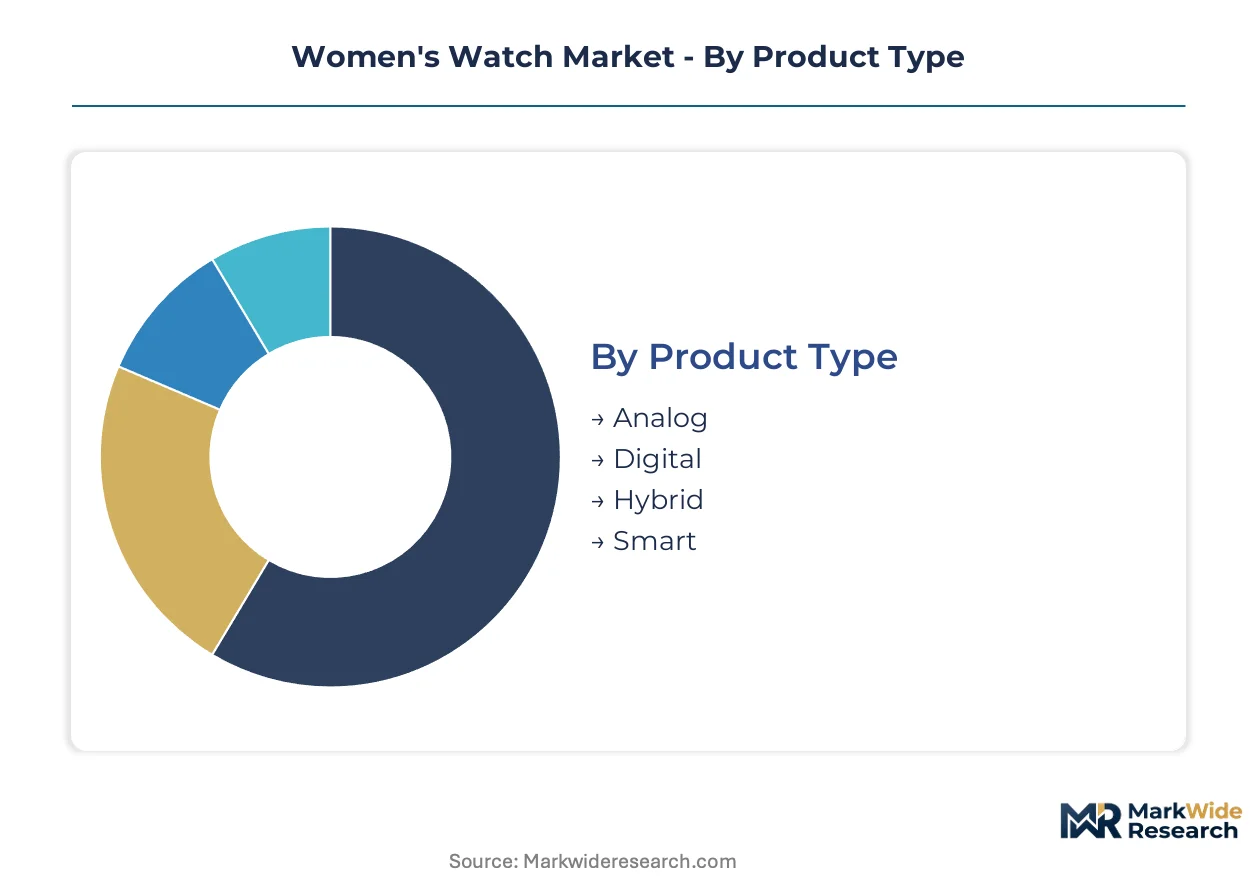
Segmentation in the women's watch market reveals how purchasing decisions split across functional utility, aesthetic positioning, and technical sophistication. Distinct buyer cohorts prioritize sensor capability, jewelry heritage, or price accessibility, forcing brands to architect parallel product architectures rather than unified portfolios.
Product Type:
Functional architecture determines how timekeeping interfaces with digital ecosystems and wearer expectations around connectivity.
- Analog:Mechanical and quartz movements power traditional three-hand and complications configurations. Collector demand concentrates in Swiss and Japanese manufacturing clusters, where in-house caliber production sustains margin premiums against contract ebauche alternatives.
- Smart:Biometric sensors, touchscreens, and wireless connectivity transform the wrist into a health-data node. Shenzhen-based contract manufacturers capture assembly volume as FDA and Swissmedic certification timelines extend development cycles for brands pursuing medical-grade claims.
- Digital:LCD and LED displays deliver precision timekeeping without mechanical complexity. Cost-optimized production in Dongguan serves price-sensitive markets where battery longevity outweighs connectivity demands.
- Hybrid:Analog hands overlay smart notification and activity-tracking functions. This bridging format attracts transition buyers in European urban centers reluctant to abandon mechanical aesthetics for full digitization.
Analog commands the established base. The steepest expansion runs through Smart.
Material:
Surface composition shapes weight perception, skin compatibility, and regulatory compliance burden across export markets.
- Stainless Steel:Austenitic grades dominate case and bracelet production, though REACH nickel release limits force 316L specification upgrades for European entry. Medical-grade 904L variants command price premiums in Swiss luxury manufacturing.
- Leather:Calfskin and exotic hides from French and Italian tanneries supply dress watch straps. Chrome-free tanning processes gain share as ECHA scrutiny intensifies on hexavalent chromium residues.
- Ceramic:Zirconium oxide and alumina compounds deliver scratch resistance and hypoallergenic properties. Sintering complexity limits production to high-volume Swiss and Japanese facilities with captive ceramic pressing capabilities.
- Plastic:Polycarbonate and resin formulations serve entry-tier digital and children's segments. RoHS constraints on phthalate plasticizers require reformulation for EU market access.
Stainless steel anchors volume manufacturing. Ceramic gains share fastest in premium positioning.
Style:
Wearer context—professional, athletic, or ceremonial—drives case proportion, water resistance, and dial ornamentation choices.
- Dress:Ultra-thin profiles, precious metal cases, and minimal complications suit formal occasions. Geneva and Bienne workshops concentrate hand-finishing capacity for this margin-intensive category.
- Sports:Enhanced water resistance, screw-down crowns, and luminous indices support active use. Diver and chronograph specifications from ISO 6425 and ISO 764 shape technical compliance requirements.
- Casual:Versatile proportions and interchangeable straps accommodate daily rotation. This flexible positioning absorbs the largest unit volume across mid-tier retail channels.
- Fashion:Trend-responsive designs with seasonal colorways and collaborator branding. Fast-turn production cycles in Guangzhou and Milan respond to runway and celebrity endorsement velocity.
Casual styling captures the broadest installed base. Sports configuration expands most quickly through fitness-tracking integration.
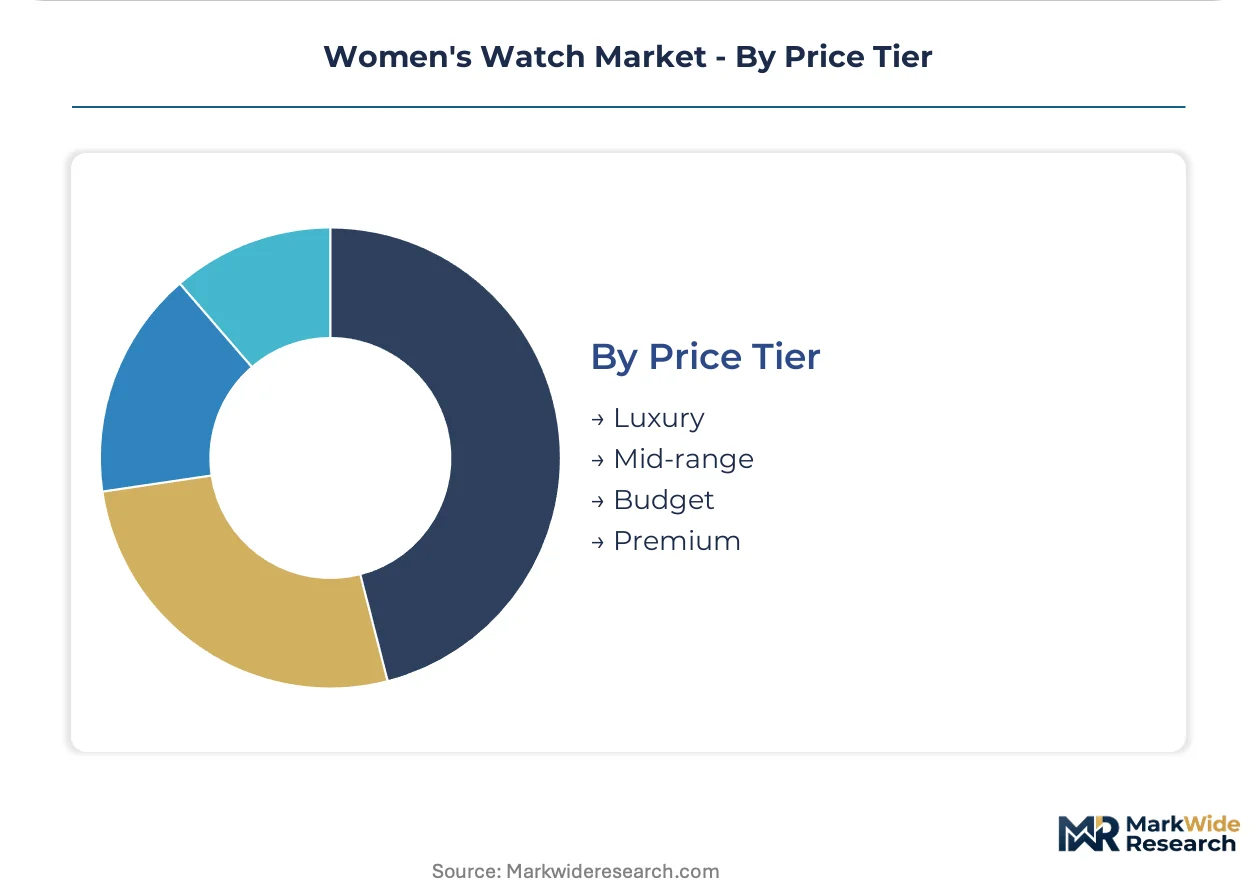
Price Tier:
Payment thresholds separate buyers by purchase occasion—self-reward, gift, or heirloom investment—and determine channel economics.
- Luxury:Five-figure price floors sustained by scarcity marketing, authorized dealer allocation control, and in-house movement manufacturing. Swiss cantonal production concentrates supply for this tier.
- Premium:Accessible prestige positioning with ETA or Sellita movements and brand heritage marketing. German and Japanese manufacturers compete aggressively here against entry-level Swiss houses.
- Mid-range:Fashion brand licensing and private-label assembly dominate. Shenzhen contract manufacturers supply quartz and basic smart functionality at compressed margins.
- Budget:Mass retail and e-commerce direct distribution with minimal service infrastructure. Battery replacement and strap swaps constitute the primary aftermarket touchpoint.
Luxury tier concentrates profit pool density. Mid-range volume scales fastest through emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate Swiss finished goods against Chinese component assembly and American consumer absorption. Germany and France regulate nickel release and algorithmic health claims through REACH and the EU AI Act. Japan and India present distinct demand profiles shaped by professional workforce expansion and heritage collector markets.
Switzerland
Geneva and Bienne workshops anchor mechanical caliber production for luxury tier export. Swissmedic governs medical-device claims for heart-rate sensors in smart watch variants. The Jura Arc concentrates hand-finishing capacity for complications manufacturing serving Asian and Middle Eastern buyers.
China
Shanghai, Beijing, and Shenzhen absorb premium Swiss imports while domestic brands capture mid-tier volume. MIIT standards and GB certification requirements shape smart watch firmware development. Dongguan and Shenzhen assembly clusters produce connected modules for European and North American brands.
Germany
Professional women in Frankfurt and Munich drive demand for mid-luxury mechanical pieces with medical-grade sensor integration. REACH nickel release limits enforce 316L stainless steel specifications for imported cases. Glashütte workshops preserve complications expertise amid talent scarcity pressures.
United States
FDA-cleared sensor validation influences purchase decisions among healthcare and finance professionals in New York and California. FCC wireless certification requirements extend development timelines for connected models. Miami and Los Angeles concentrate authorized dealer networks for luxury Swiss distribution.
India
Mumbai, Delhi, and Bangalore present underpenetrated demand as professional female workforce participation rises. BIS quality standards and DGFT import duties structure market access for foreign manufacturers. Domestic assembly partnerships in Gujarat and Tamil Nadu reduce landed costs for mid-range quartz and hybrid models.
Women's Watch Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated Swiss manufacturers and Asian contract assemblers serving connected segments. Three archetypes dominate: heritage maisons with captive movement production, jewelry houses leveraging gem-setting expertise, and technology-forward specialists pursuing medical-device certification. Competitive moves center on direct-to-consumer channel expansion and sensor array partnerships with semiconductor foundries.
Within the heritage tier, Patek Philippe and Audemars Piguet exemplify complications-focused positioning anchored in Geneva and Le Brassus manufacturing. Cartier represents the jewelry-house archetype, while Rolex occupies a position defined by in-house caliber production and authorized dealer network control. Tag Heuer sits within the accessible-luxury segment bridging Swiss manufacturing with connected functionality development.
| Leading Market Players |
|---|
| Patek Philippe |
| Breitling |
| Cartier |
| Hublot |
| Longines |
| Rolex |
| Tag Heuer |
| Jaeger-LeCoultre |
| Audemars Piguet |
| Others |
Value Network & Pricing Analysis
REACH nickel release limits determine both stainless steel alloy specifications across European entry tiers and the geographic distribution of compliant forging capacity. This regulatory chokepoint widens price spreads between EU-certified and non-certified material streams while compressing margins for Asian contract manufacturers lacking dual-alloy supply chains.
Pricing Analysis
Prior-generation analog quartz movements trade at steep discounts to current-generation smart sensor arrays and emerging next-generation photoplethysmography-ECG convergence modules. Three-tier pricing structure across premium, standard, and economy levels separates Swiss in-house caliber pieces from ETA-powered mid-market offerings and Shenzhen-assembled digital units. Pricing pressure stems from smart connectivity becoming baseline expectation in entry and mid-tier segments. Budget-tier buyers exhibit highest price sensitivity, while luxury mechanical collectors demonstrate inelastic demand for Geneva-finished complications.
Supply Chain Analysis
Export control restrictions on advanced semiconductor lithography constrain photoplethysmography chip sourcing for medical-grade sensor arrays. Component flows center on Switzerland for mechanical movements, China for smart module assembly, and Japan for ceramic case compounds. Raw material dependencies span gold and platinum for luxury cases, lithium-ion cells for smart power systems, and zirconium oxide for premium ceramic finishing. Single-source vulnerability concentrates in ETA and Sellita ebauche supply for independent brands. Distribution runs through authorized dealer networks for luxury tiers and brand-owned e-commerce for direct-to-consumer bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The women's watch market sits in a cyclical upswing driven by professional female workforce expansion and self-purchase occasion normalization post-pandemic calendar distortions.
For Market Incumbents: Pre-empt smart sensor commoditization by accelerating Swissmedic medical-grade certification timelines before EU AI Act algorithmic health claim classifications harden regulatory moats. Secure captive ceramic pressing capacity or sintering partnerships to offset REACH-driven stainless steel reformulation costs. Vertical integration into photoplethysmography firmware development reduces dependency on semiconductor foundry allocation cycles. For New Entrants and Emerging Players: Build out India metro distribution before Swiss and Japanese heritage houses establish authorized dealer footholds in Mumbai, Delhi, and Bangalore. Target mid-luxury hybrid formats bridging analog aesthetics with FDA-cleared biometric functionality. Partner with Gujarat and Tamil Nadu domestic assembly facilities to circumvent DGFT import duty compression on landed quartz and connected modules. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with in-house caliber production and medical-device certification pipelines. Five-to-ten year viability hinges on sensor convergence capabilities rather than jewelry heritage alone. Watch for Swissmedic clearance velocity as inflection signal distinguishing lifestyle accessory valuations from medical-device premium multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Sensor Certification | Swissmedic and FDA pathways differentiate premium smart offerings from commodity fitness trackers. |
| Direct-to-Consumer Channel Launch | Brand-owned e-commerce bypasses authorized dealer margin compression in tier-one Chinese cities. |
| Ceramic Case Manufacturing Scale-Up | Captive zirconium oxide pressing insulates against REACH nickel limit compliance cost inflation. |
| India Metro Distribution Expansion | Mumbai and Delhi professional workforce growth supports mid-luxury mechanical penetration before saturation. |
| Heritage Complications Pipeline Investment | Geneva and Le Brassus hand-finishing capacity scarcity sustains collector-driven price inelasticity. |
Research Methodology
Desk research of trade customs records, Swiss export statistics, and MIIT smart device certification databases preceded structured interviews with watch brand product directors, authorized dealer network managers, Shenzhen contract manufacturing executives, and ceramic component procurement leads. Primary fieldwork combined with secondary validation from ETA supply bulletins and REACH compliance filings. Bottom-up unit shipment modeling triangulated against top-down luxury goods spending surveys.
Assumptions held fixed include Swiss franc exchange rate stability and current REACH nickel release thresholds; variables stress-tested spanned gold price volatility, China tier-one city disposable income growth, and FDA clearance timeline extensions. Segmentation dimensions encompassed product type, material composition, price tier, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to smart sensor penetration data and mechanical collector market depth indicators.
Stress conditions across precious metal input costs, EU AI Act implementation pacing, and India import duty schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Swiss manufacturing capacity constraints and Chinese domestic brand competitive intensity. Material shifts in Swissmedic medical-device classification thresholds or REACH alloy specification tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Battery for Children Smart Watch Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Smart Band Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market