
 Portable Kayaks Market | 2026-2036
Portable Kayaks Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Kayaks Market Outlook
ISO 6185 certification for inflatable craft is collapsing the barrier between hobby-grade and expedition-ready products, forcing manufacturers to elevate testing protocols. Oru Kayak Inc. leverages origami-inspired engineering to dominate the foldable segment with rigid-hull performance in a collapsible format. Sea Eagle Boats Inc. sustains broad market presence through deep catalog breadth across inflatable fishing and tandem configurations. Gumotex Group anchors European production with Czech-based manufacturing and welded-seam expertise in Hypalon construction.
Portable kayaks are compact, human-powered watercraft engineered for disassembly, deflation, or folding to transport dimensions under 120 centimeters, typically employing drop-stitch PVC, polyethylene, or coated fabric laminates to achieve hull rigidity without trailer dependency. Their primary purpose is to democratize water access for urban consumers and travelers lacking dedicated storage or vehicle rack systems. Inflatable kayaks command the largest volume pool due to sub-$800 entry pricing and rental fleet penetration, while foldable kayaks capture premium margins through performance parity with hard-shell designs. Fishing-oriented configurations within the use-case taxonomy are expanding fastest as rod holders, pedal-drive compatibility, and stability beams convert kayak anglers from dock or boat traditions.
The US Coast Guard flotation standard and EPA REACH-compliant material mandates in Europe are reshaping material selection, with PVC phthalate restrictions accelerating Hypalon and thermoplastic polyurethane migration in export-bound product lines. The EU's F-Gas Regulation indirectly pressures inflatable manufacturing by limiting certain industrial blowing agents, while Australia's ACCC product safety enforcement on buoyancy labeling affects import compliance costs. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and decide whether to regionalize material sourcing or absorb cross-border certification overhead.
Market Dynamics
Drop-stitch PVC technology is collapsing the performance gap between inflatable and rigid-hull kayaks, forcing traditional polyethylene manufacturers to defend their premium positioning through weight reduction and modularity investments.
Growth Catalysts
- ISO 6185 Certification:The inflatable craft safety standard is elevating consumer trust in expedition-grade products, opening rental fleet procurement to higher-specification models across Germany and Australia.
- Fishing Enthusiast Demand:Rod holder integration and pedal-drive compatibility are converting dock-based anglers to kayak platforms, particularly in waterfront-accessible US metropolitan areas.
- Urban Storage Constraints:Apartment dwellers in dense European cities are adopting foldable and inflatable formats as hard-shell ownership becomes impractical without dedicated vehicle racks.
Market Restraints
- Petrochemical Input Volatility:PVC resin and thermoplastic polyurethane pricing swings compress margin predictability for manufacturers dependent on Asian polymer supply chains.
- Welded Seam Skill Concentration:Czech and German facilities retain disproportionate expertise in Hypalon construction, creating geographic supply bottlenecks for export-bound production.
- EPA REACH Compliance Overhead:Phthalate restrictions in US and European markets force material reformulation, extending product development cycles and certification costs.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Early compliance with emerging state-level recycling mandates in California and New York positions manufacturers for preferred supplier status in institutional procurement.
- Thermoplastic Polyurethane Convergence:Welding advances combining TPU with drop-stitch cores enable lighter hulls without sacrificing puncture resistance, targeting the premium touring segment.
- Direct-to-Consumer Channel Expansion:Subscription-based rental-to-own models are penetrating Australian coastal cities where seasonal usage patterns discourage outright purchase.
Industry Challenges
- ISO 6185 Testing Timeline:Certification protocols for multi-chamber inflatable designs require 14-18 month validation cycles, delaying product launches and freezing inventory commitments.
- Cross-Border Material Sourcing Friction:EU F-Gas Regulation restrictions on industrial blowing agents force manufacturers to regionalize supply chains or absorb import compliance overhead.
- Integration Complexity with Legacy Rack Systems:Foldable kayak dimensions often conflict with established vehicle rack geometries, requiring aftermarket adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Kayaks Market |
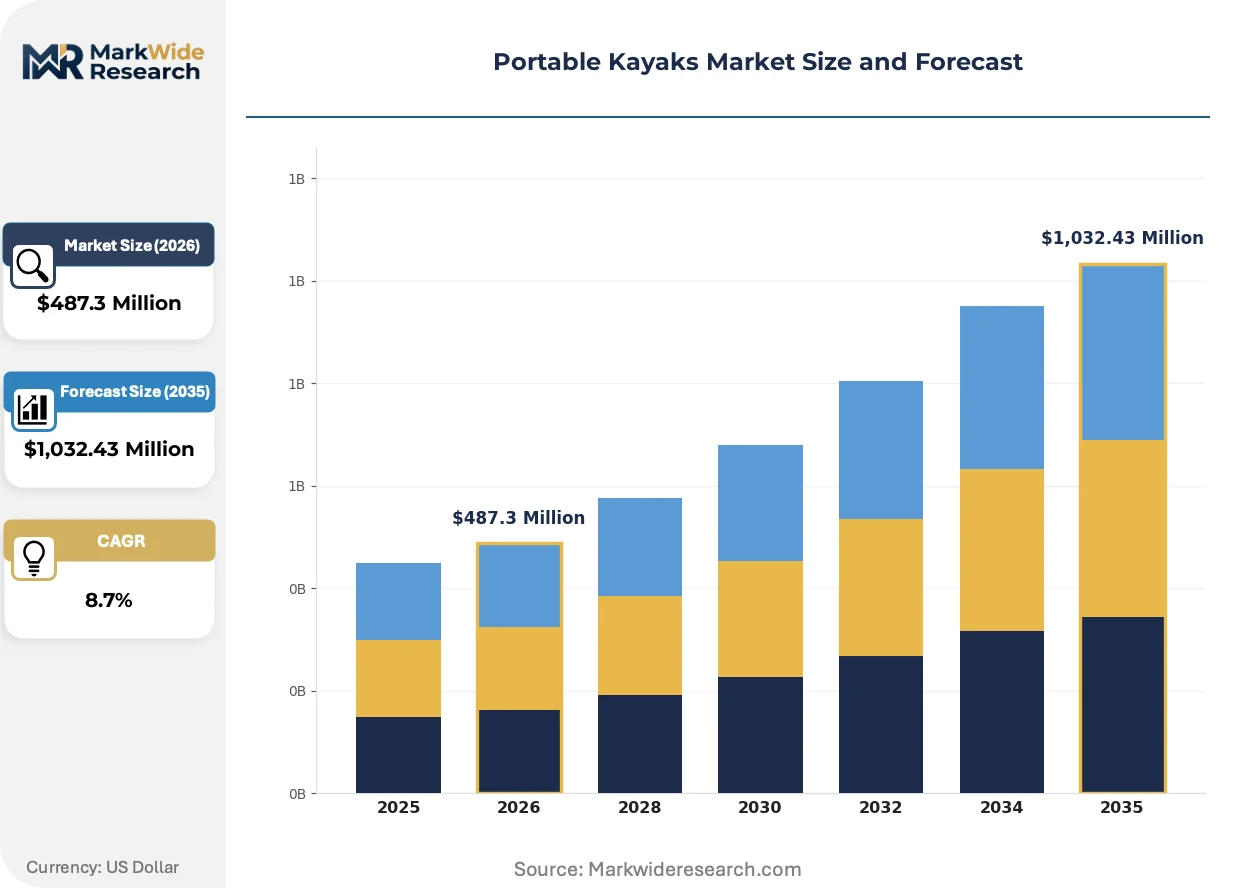
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Kayaks, Foldable Kayaks, Sit-On-Top Kayaks, Tandem Kayaks Material: Polyethylene, PVC, Hypalon, Inflatable Fabrics Use Case: Recreational Paddling, Fishing, Touring, Whitewater Customer Type: Occasional Users, Expedition Kayakers, Fishing Enthusiasts, Rental Services |
| Companies Covered | AIRE Inc., Aqua Marina, Oru Kayak Inc., Sea Eagle Boats Inc., Gumotex Group, TRAK Outdoors Ltd., Pelican International Inc., Nova Craft Canoe, Point 65 Sweden AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Kayaks Market Strategic Shifts
Material science breakthroughs and regulatory pressure on chemical composition are converging to redefine durability benchmarks and distribution economics across the portable watercraft sector.
Welded thermoplastic polyurethane construction is supplanting glued PVC seams in mid-tier and premium inflatable kayaks. Fishing-focused buyers in the United States and Australia are adopting TPU-hulled models at accelerating rates due to superior UV resistance and repairability. This material migration is compressing the traditional three-tier quality hierarchy into a two-tier structure separating disposable rental fleet units from durable consumer ownership models.
EU F-Gas Regulation limitations on hydrofluorocarbon blowing agents are reshaping inflatable manufacturing processes across Czech, German, and French production facilities. The industrial consequence is accelerated investment in mechanical expansion and nitrogen-based foaming alternatives for drop-stitch core production. Export-bound product lines destined for Australian and US markets are experiencing the most pronounced material reformulation costs, with manufacturers absorbing certification overhead rather than regionalizing supply chains.
Urban consumers are fragmenting purchase decisions across seasonal rental trial and eventual ownership, compressing traditional retail channel dominance. Specialty outdoor retailers in German and Australian markets are responding with experiential showroom formats featuring on-water demonstration access. This behavioral shift is most visible in waterfront-adjacent metropolitan areas where storage constraints and transit logistics previously suppressed category penetration.
Portable Kayaks Market Segmentation
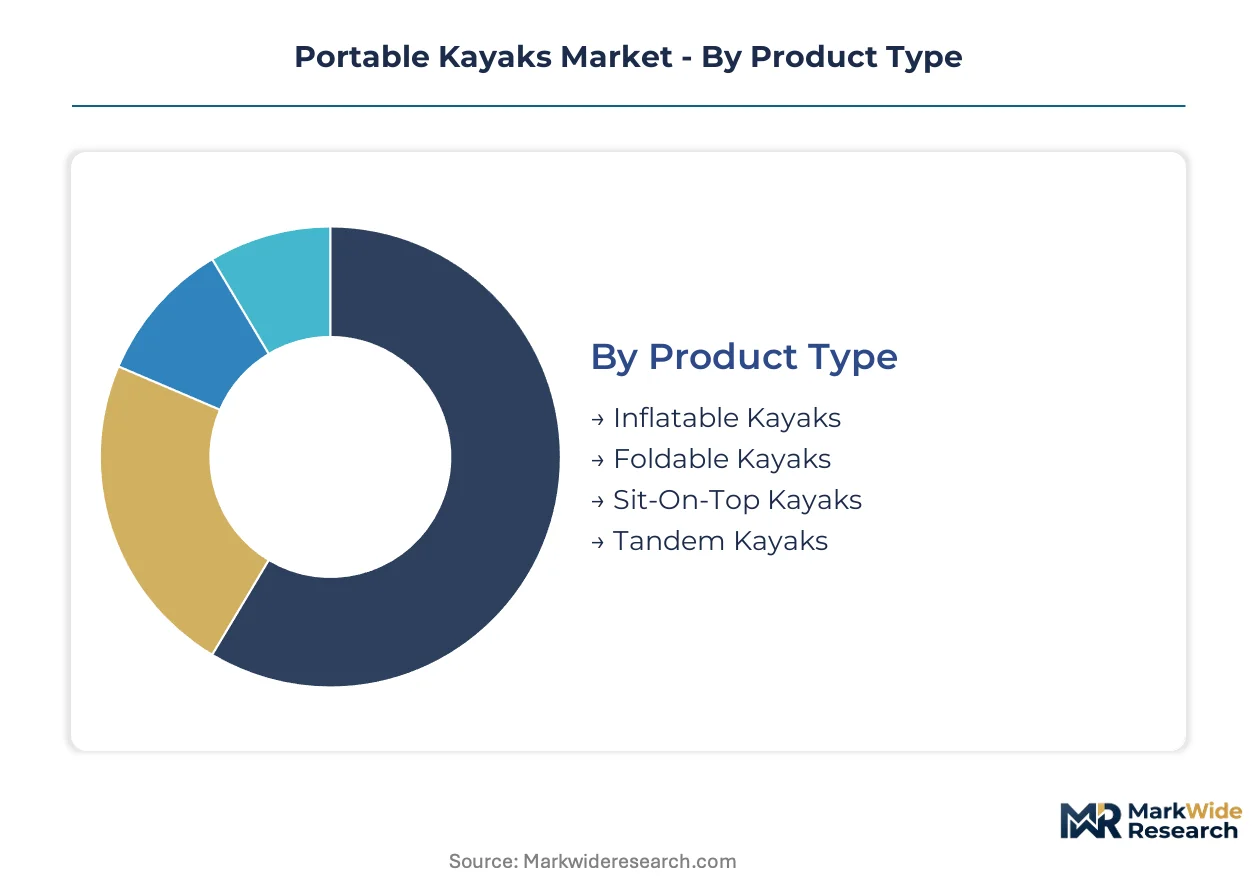
Portable kayak segmentation reveals how substitution pressures reshape competitive boundaries across product formats. Material chemistry and use-case specialization now determine which configurations defend margin against hard-shell alternatives and which segments face commoditization.
Product Type:
Inflatable kayaks face the most acute substitution threat from rigid-hull competitors as drop-stitch technology narrows the performance gap.
- Inflatable Kayaks:Drop-stitch PVC construction achieves hull rigidity comparable to polyethylene at sub-$800 price points. Demand concentrates in United States rental fleets and German urban markets where storage constraints dominate purchase decisions. EPA REACH phthalate restrictions are accelerating material migration toward thermoplastic polyurethane in export-bound product lines.
- Foldable Kayaks:Origami-inspired engineering delivers rigid-hull performance in collapsible formats under 120 centimeters. Premium positioning targets expedition kayakers in Australia and waterfront-adjacent United States metropolitan areas where vehicle rack conflicts suppress hard-shell adoption. Oru Kayak dominates this segment through patented folding geometry.
- Sit-On-Top Kayaks:Self-bailing hull design favors warm-climate recreational use and fishing applications.
- Tandem Kayaks:Two-person configurations serve rental services and family recreational segments.
Inflatable kayaks retain volume leadership; foldable kayaks hold the steepest expansion curve.
Material:
Cost tier stratification determines which materials defend position in premium versus disposable segments.
- Polyethylene:Rotomolded construction dominates hard-shell portable formats through impact resistance and repairability. United States manufacturing clusters in the Southeast retain scale advantages for domestic distribution, though weight penalties limit true portability compared to inflatable alternatives.
- PVC:Calendered vinyl with polyester reinforcement remains the cost baseline for rental fleet procurement. EU F-Gas Regulation restrictions on industrial blowing agents are forcing Czech and German manufacturers toward mechanical expansion processes, extending production cycles.
- Hypalon:Chlorosulfonated polyethylene construction delivers superior UV and chemical resistance for expedition-grade applications.
- Inflatable Fabrics:Coated fabric laminates enable ultralight packraft formats for backcountry access.
Polyethylene anchors premium durability positioning; thermoplastic polyurethane variants gain share fastest in mid-tier migration.
Use Case:
Application-specific feature integration determines margin capture across recreational and professional user bases.
- Fishing:Rod holder integration, pedal-drive compatibility, and stability beams convert dock-based anglers to kayak platforms. Demand concentrates in United States Gulf Coast and Australian coastal cities where waterfront access infrastructure supports launch convenience. Configuration complexity extends development cycles.
- Recreational Paddling:Entry-level sit-inside and sit-on-top formats target occasional users seeking lake and slow-river access. German and Australian specialty retailers are deploying experiential showroom formats with on-water demonstration to overcome purchase hesitation.
- Touring:Long-distance hull efficiency and cargo capacity target expedition kayakers.
- Whitewater:Reinforced construction and self-rescue features address technical river running.
Recreational paddling retains volume leadership; fishing configurations hold the steepest expansion curve.
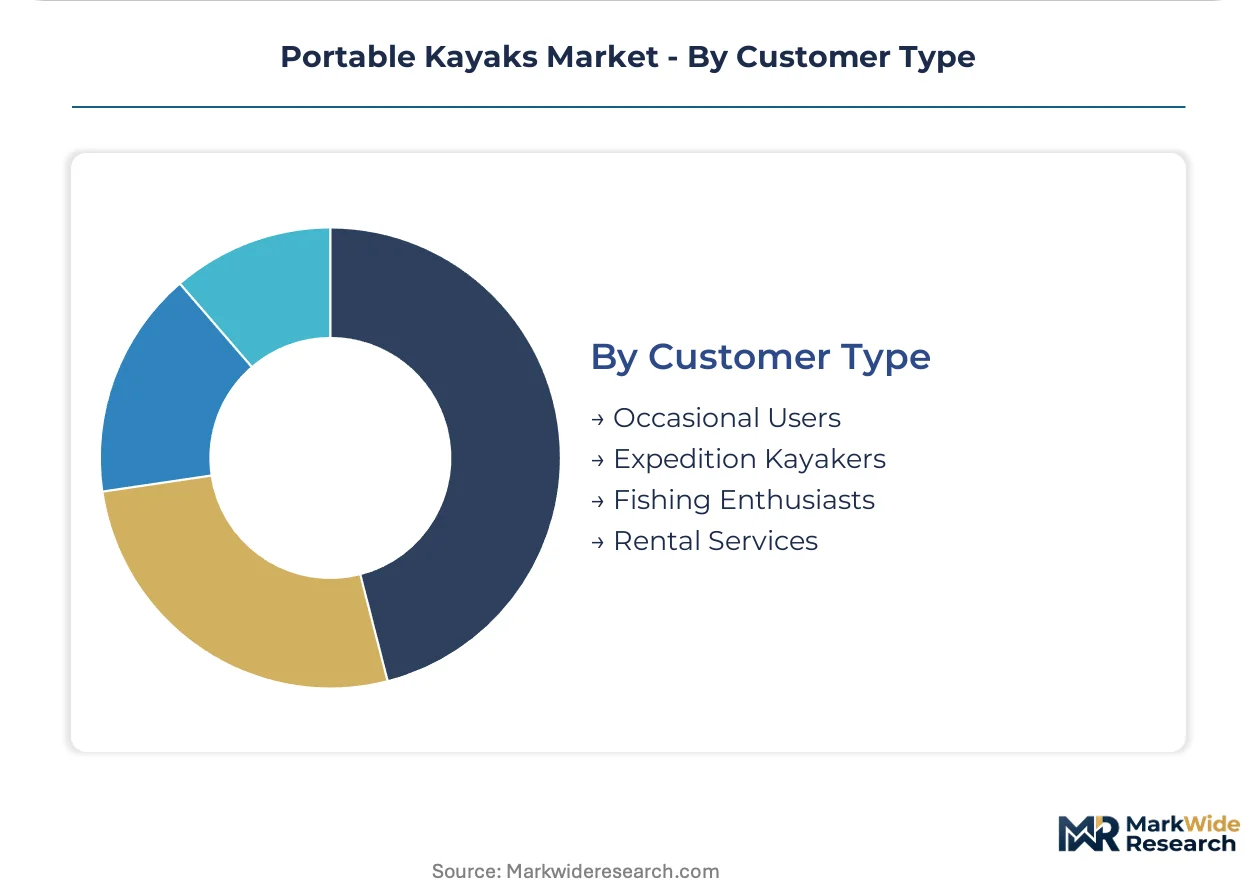
Customer Type:
Volume concentration versus margin extraction varies sharply across ownership frequency and institutional procurement.
- Rental Services:Fleet procurement prioritizes durability-to-cost ratios and rapid turnaround maintenance. Australian coastal cities and United States lake districts are adopting subscription-based rental-to-own models that compress traditional retail channel dominance.
- Fishing Enthusiasts:Technical feature requirements and brand loyalty support premium pricing. This segment drives fastest adoption of pedal-drive and motor-mount compatible configurations in United States and Australian markets.
- Occasional Users:Price-sensitive entry segment with high churn to secondary markets.
- Expedition Kayakers:Performance demands favor foldable and high-specification inflatable formats.
Rental services retain volume leadership; fishing enthusiasts hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives for outdoor recreation infrastructure and waterfront access programs are reshaping demand geography across developed economies. National regulators are embedding product safety standards into procurement criteria for public rental fleets. Manufacturing clusters concentrate where polymer processing expertise intersects with marine industry heritage.
United States
EPA REACH-compliant material mandates and Coast Guard flotation standards are elevating certification requirements for import-bound product lines. State-level extended producer responsibility frameworks in California and New York are forcing material sourcing regionalization. Manufacturing concentrates in Southeast rotomolding clusters serving domestic distribution networks.
Germany
EU F-Gas Regulation restrictions on industrial blowing agents are extending production cycles for drop-stitch core manufacturing. ISO 6185 certification protocols are opening rental fleet procurement to higher-specification inflatable models. Czech-German welded-seam expertise clusters anchor European Hypalon construction capacity.
Australia
ACCC product safety enforcement on buoyancy labeling is inflating import compliance costs for Asian-manufactured inventory. Waterfront access infrastructure investments in coastal metropolitan areas are converting dock-based anglers to kayak platforms. Subscription-based rental-to-own models are penetrating Sydney and Melbourne seasonal markets.
United Kingdom
CE marking requirements under EU MDR-aligned frameworks are persisting in post-Brexit regulatory alignment. Urban storage constraints in Greater London are accelerating foldable format adoption among apartment dwellers. Specialty outdoor retailers are deploying experiential showroom formats with on-water demonstration access.
Canada
Health Canada product safety standards are converging with US Coast Guard protocols for cross-border inventory harmonization. Provincial park infrastructure investments in Ontario and British Columbia are expanding launch site accessibility. Rotomolded polyethylene manufacturing in Quebec serves North American distribution networks.
Portable Kayaks Market Competitive Environment
Player mix skews toward specialized fabricators with material science capabilities rather than diversified marine conglomerates. Market structure fragments across inflatable, foldable, and rotomolded format specialists with limited cross-format integration. Three archetypes dominate: drop-stitch PVC engineers, origami-inspired folding mechanics, and welded-seam Hypalon craftsmen. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into fishing-specific configurations.
Within the foldable format tier, Oru Kayak Inc. and TRAK Outdoors Ltd. exemplify engineering-led positioning through patented collapsible geometries. Among inflatable specialists, Sea Eagle Boats Inc. and Gumotex Group occupy positions spanning rental fleet procurement and expedition-grade construction. AIRE Inc. anchors the premium whitewater segment with reinforced fabrication expertise.
| Leading Market Players |
|---|
| AIRE Inc. |
| Aqua Marina |
| Oru Kayak Inc. |
| Sea Eagle Boats Inc. |
| Gumotex Group |
| TRAK Outdoors Ltd. |
| Pelican International Inc. |
| Nova Craft Canoe |
| Point 65 Sweden AB |
| Others |
Value Chain & Pricing Dynamics
Rotomolded polyethylene capacity utilization in Southeast United States manufacturing clusters anchors cost floors across hard-shell formats, while Asian drop-stitch PVC production at scale compresses inflatable entry pricing and fragments margin pools between geographic supply bases.
Pricing Analysis
Certification level creates the primary spread between disposable rental fleet units and expedition-grade consumer ownership models. Three-tier pricing structure across premium ISO 6185-certified, standard welded-seam, and economy glued-PVC tiers segments buyer archetypes. Pricing pressure stems from petrochemical input volatility in Asian polymer supply chains. Rental services exhibit highest price sensitivity; expedition kayakers absorb premium positioning for foldable formats.
Supply Chain Analysis
Welded-seam skill concentration in Czech and German facilities creates chokepoint vulnerability for Hypalon construction capacity. Manufacturing draws from China for drop-stitch PVC cores, Southeast United States for rotomolded polyethylene, and Czech-German clusters for expedition-grade welding. Single-source vulnerability concentrates in Asian polymer feedstock supply. Distribution runs through specialty outdoor retailers, direct-to-consumer channels, and institutional rental fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where ISO 6185 certification timelines and EPA REACH compliance overhead create switching costs that lock in incumbent positioning against unqualified entrants.
For Market Incumbents: Shield market position by deepening backward integration into drop-stitch core manufacturing to offset Asian polymer price volatility. Accelerate ISO 6185 certification pipelines to capture rental fleet procurement upgrading from economy tiers. Incumbent leverage rests on welded-seam expertise concentration that emerging competitors cannot replicate without 14-18 month validation cycles.
For New Entrants and Emerging Players: Subscription-based rental-to-own service gaps in Australian coastal cities offer white-space penetration where seasonal usage patterns suppress outright purchase. Target fishing enthusiast configurations with pedal-drive compatibility as the most penetrable premium segment. Go-to-market angle should emphasize direct-to-consumer demonstration partnerships with waterfront-access retailers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material science specialists with thermoplastic polyurethane welding capabilities over assembly-only operations. Long-term viability hinges on compliance infrastructure amortization across multi-regulatory environments. Acquisition target archetype: Czech-German welded-seam fabricators with established EPA REACH export protocols. Signal to monitor: state-level extended producer responsibility framework adoption in California and New York as inflection indicator for preferred supplier status.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 6185 Certification Investment | Fourteen-month validation cycles lock in rental fleet procurement preference against uncertified competitors. |
| Backward Integration into TPU Welding | Captive supply of thermoplastic polyurethane seams reduces dependency on Czech-German skill concentration. |
| Direct-to-Consumer Rental Partnerships | Subscription models in Sydney and Melbourne capture seasonal users without traditional retail overhead. |
| Fishing Configuration Specialization | Pedal-drive compatibility converts dock-based anglers in United States Gulf Coast metropolitan areas. |
| EPR Framework Early Compliance | California and New York recycling mandates position manufacturers for institutional procurement preference. |
Study Parameters
The analysis maps inflatable, foldable, and rotomolded portable kayak sub-sectors, each validated through product engineering leads, rental fleet procurement managers, specialty outdoor retail buyers, and polymer supply specialists. Primary interview intelligence combined with secondary validation from United States Coast Guard flotation standard filings, EPA REACH compliance databases, EU F-Gas Regulation implementation records, and Australian ACCC product safety enforcement notices. Bottom-up unit economics triangulated against top-down category spend estimates.
Forecast consistency was verified against external benchmarks including customs trade data for PVC resin and thermoplastic polyurethane imports, specialty outdoor retailer inventory turnover disclosures, and waterfront infrastructure investment tracking from municipal recreation authorities. Segmentation modeling spanned product format, material chemistry, use case specialization, and customer ownership frequency across the projection horizon. CAGRs derived from demand elasticity analysis against price point clustering and substitution coefficient estimates between inflatable and rigid-hull alternatives.
Forecasts assume regulatory continuity in United States EPA REACH enforcement, EU F-Gas Regulation restrictions, and Australian ACCC buoyancy labeling mandates; material policy shifts would require re-modeling. Specific risk factors include petrochemical input volatility, ISO 6185 certification timeline extensions, and state-level extended producer responsibility framework acceleration. Practitioners should keep alternative scenarios live as polymer supply chain reconfiguration and welded-seam automation advances evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Kids Scooter Market