
 Global Swimming Pool Market | 2026-2036
Global Swimming Pool Market Size, Share, and Industry Trends Forecast 2026-2036
Global Swimming Pool Market Outlook
REACH compliance is shifting material specifications for pool liners and filtration housings across European supply chains. Pentair plc leverages its captive distribution network to sustain margin capture in North American replacement parts. Latham Group, Inc. anchors fiberglass shell production with automated molding capabilities that reduce labor dependency. Fluidra S.A. competes across the full equipment stack from pumps to LED lighting systems.
A swimming pool is a watertight structure engineered for aquatic recreation, therapy, or competitive training, typically constructed with reinforced concrete, vinyl membranes, or fiberglass composites and integrated with hydraulic circulation, filtration, and chemical treatment systems. Its primary commercial purpose centers on delivering sanitized, thermally regulated water volumes for residential leisure, hospitality amenities, or athletic facilities. Inground pools dominate value capture given their permanence and higher ancillary equipment attachment rates, while swim spas represent the fastest-expanding product type as urban households prioritize compact hydrotherapy installations. Fiberglass shells command premium positioning due to factory-controlled gelcoat finishes and reduced site-cure variability versus poured concrete.
The EPA regulates disinfection byproduct thresholds in public pool water chemistry across the United States, while the EU F-Gas Regulation constrains refrigerant choices for pool heat pumps in Europe, and Australia's Standards Australia AS 1926 series mandates barrier and fencing specifications for residential installations. These frameworks collectively elevate compliance costs for market entrants while creating specification advantages for pre-certified equipment suppliers. Stakeholders must monitor evolving refrigerant phase-down schedules and regional water-efficiency mandates to align product roadmaps with enforceable standards.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant phase-downs across European pool heating systems, compressing supply chains toward low-GWP heat pump architectures while elevating compliance costs for incumbent equipment suppliers.
Growth Catalysts
- Resort amenity expansion:Hospitality operators in Dubai and Southeast Asia are commissioning aquatic facilities as competitive differentiators, driving fiberglass shell and integrated filtration system procurement.
- REACH material compliance:European liner and filtration housing specifications are pivoting toward certified polymer formulations, creating specification lock-in for pre-qualified suppliers.
- Urban swim spa penetration:Compact hydrotherapy installations are capturing terrace and basement spaces in dense metropolitan housing across Australia and Spain.
Market Restraints
- Concrete curing labor dependency:Poured concrete construction faces skilled trowel-finisher shortages in North American and Australian markets, elongating project timelines.
- Refrigerant supply concentration:Low-GWP heat pump compressors depend on limited Asian component foundries, exposing European installers to allocation risk.
- Vinyl liner replacement cycles:Seven-to-ten-year membrane refresh intervals create recurring customer acquisition costs for service-oriented distributors.
Strategic Opportunities
- Smart chemistry monitoring:IoT-enabled pH and ORP sensors are penetrating residential installations in the United States, enabling subscription-based water management services.
- Passive solar thermal integration:Glazed collector systems paired with heat pumps qualify for IRA tax credits in California and Florida markets.
- Modular above-ground retrofit:Prefabricated steel-wall packages are accessing rental housing and temporary hospitality installations across Spain.
Industry Challenges
- Certification timeline compression:EPA disinfection byproduct testing protocols and EU F-Gas equipment certification are extending new product introduction cycles by eight to fourteen months.
- Legacy controller integration:Proprietary automation buses from 1990s-era installations resist interoperability with cloud-connected variable-speed pump drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Swimming Pool Market |
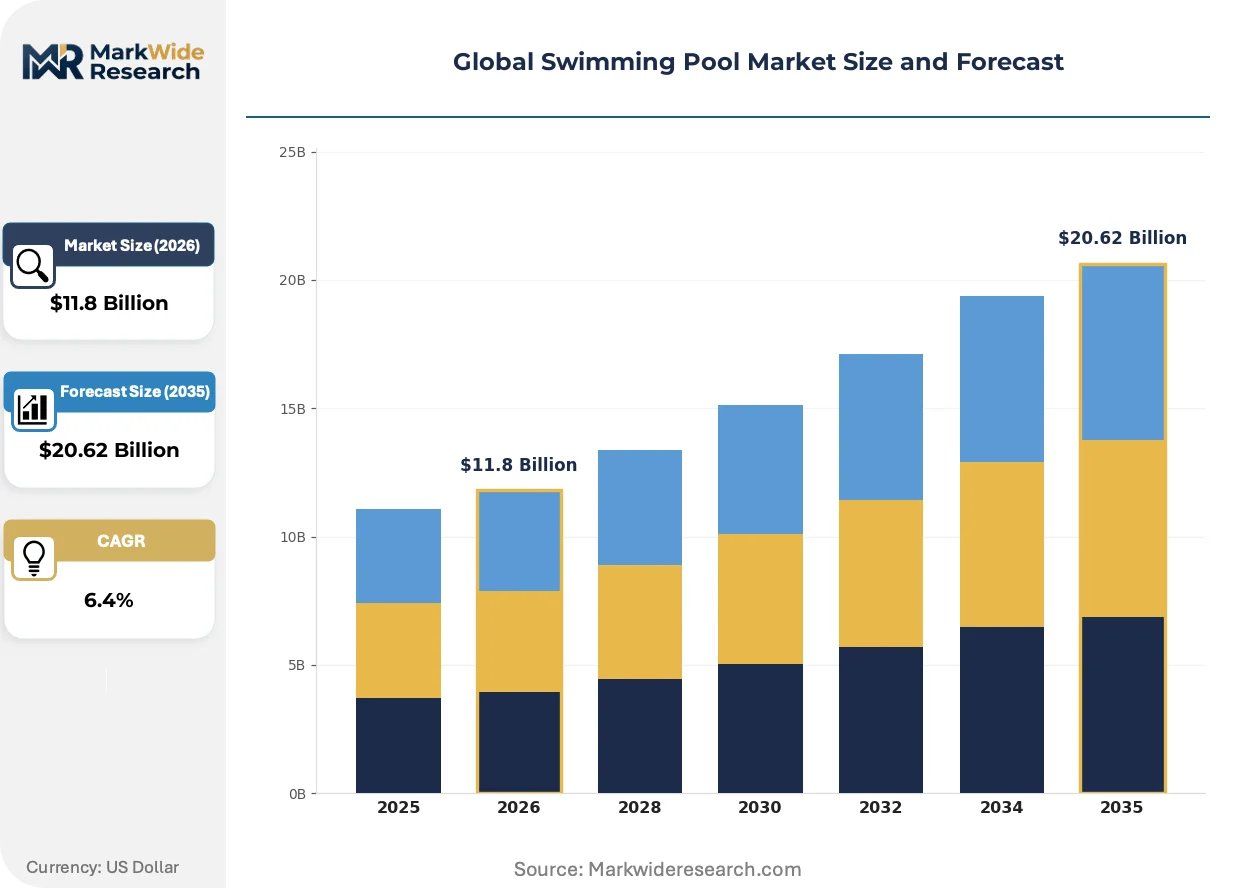
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inground Pools, Above Ground Pools, Spas, Swim Spas Material: Vinyl, Fiberglass, Concrete, Steel Installation Type: DIY, Professional, Modular, Permanent End User: Residential, Commercial, Hotels, Water Parks |
| Companies Covered | Fluidra S.A., Zodiac Pool Solutions, Latham Group, Inc., Paramount Aquatics, Waterco Limited, Pentair plc, Maytronics Ltd., Jacuzzi Group, Hayward Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Swimming Pool Market Strategic Shifts
Equipment electrification and refrigerant chemistry are restructuring competitive advantage in pool thermal management, while digital water chemistry is shifting maintenance economics from reactive service calls to predictive intervention models.
Variable-speed permanent magnet motors are overtaking single-speed induction drives in circulation pump specifications. Commercial aquatic centers in Florida and Texas are specifying these units to meet utility demand-response incentives. The technology is overtaking legacy fixed-speed inventory in distributor warehouses, compressing margin structures for mid-tier pump assemblers still dependent on induction platforms.
REACH substance restrictions are prohibiting certain phthalate plasticizers in European vinyl liner production. Compounders in Germany and Italy are reformulating with bio-based alternatives at 15-30% cost premiums. The regulation is accelerating specification divergence between European and North American liner supply chains, fragmenting economies of scale for multinational membrane producers.
After-sales service unbundling is disrupting traditional equipment-warranty bundling in Australian residential markets. Homeowners are purchasing filtration and heating hardware through e-commerce channels, then sourcing installation and seasonal opening services through independent platforms. This pattern is compressing brand loyalty for incumbent full-stack suppliers while elevating price transparency for commodity pump and heater SKUs.
Global Swimming Pool Market Segmentation
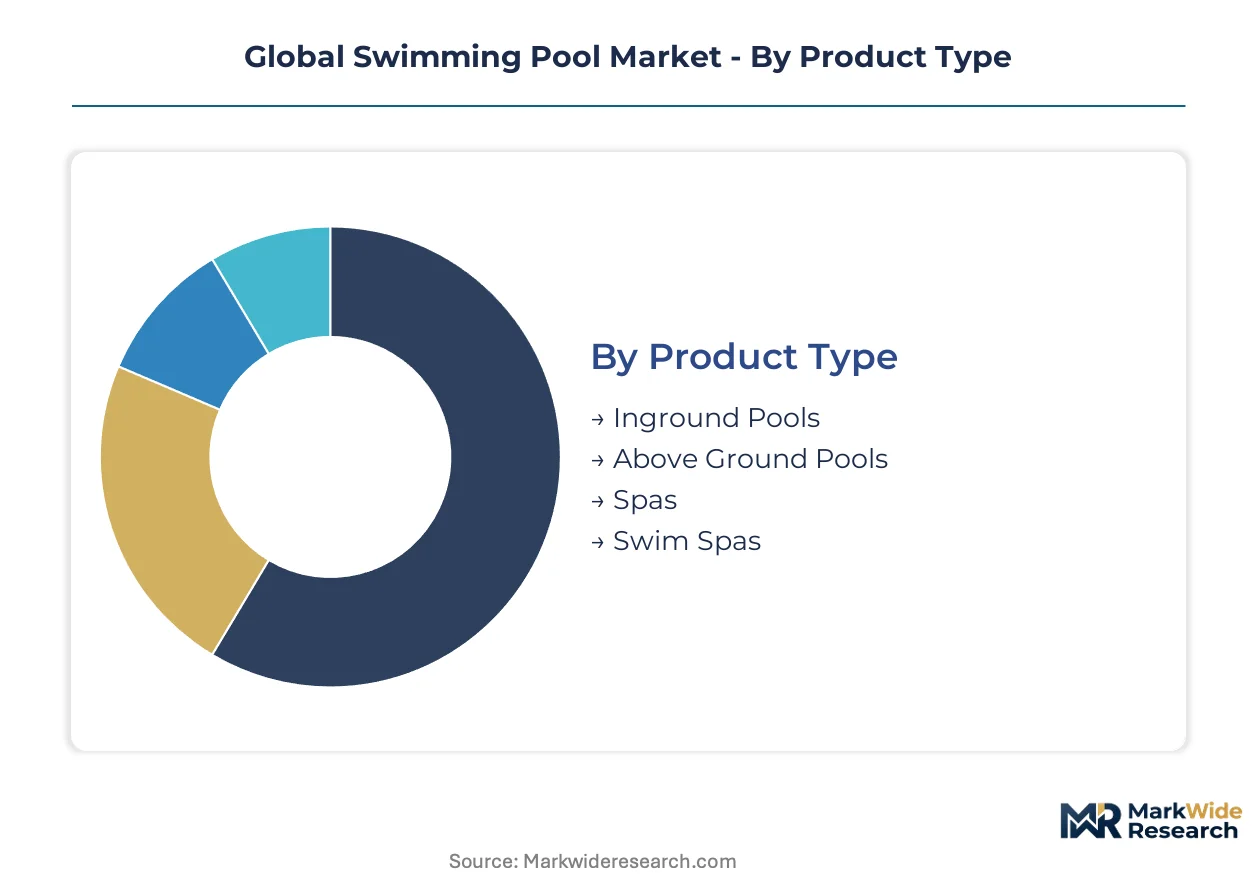
Swimming pool procurement patterns diverge sharply across construction permanence, material chemistry, and buyer sophistication. Segment boundaries determine equipment attachment rates, service contract value, and regulatory exposure for suppliers.
Product Type:
Buyers differentiate by available footprint, soil conditions, and intended use duration rather than upfront cost alone.
- Inground Pools:Reinforced concrete or fiberglass shells installed below grade deliver permanent aquatic infrastructure with integrated circulation and heating systems. Demand concentrates in suburban United States and Australian markets where property values justify five-figure capital commitments and municipalities permit permanent excavation.
- Swim Spas:Compact self-contained vessels combine counter-current swimming with hydrotherapy seating in footprints under 25 square meters. Terrace installations in dense Spanish and Australian metropolitan housing are climbing the fastest as urban households prioritize wellness amenities without pool permits.
- Above Ground Pools:Prefabricated steel or resin wall systems with vinyl liners offer seasonal deployment and relocation flexibility.
- Spas:Standalone heated vessels emphasize hydrotherapy jets and seating ergonomics over swimming function.
Volume sits with inground installations; growth tilts toward swim spas.
Material:
Material selection governs installation timeline, surface finish durability, and chemical compatibility with regional water hardness.
- Fiberglass:Factory-molded gelcoat shells arrive site-ready with controlled surface finishes and 25-year structural warranties. Luxury resort developments in Dubai and Southeast Asia specify fiberglass for accelerated construction schedules and reduced site-cure variability versus poured alternatives.
- Concrete:Steel-reinforced shotcrete or gunite construction permits custom dimensions and integrated features like vanishing edges. Skilled trowel-finisher shortages in North America and Australia are elongating project timelines and compressing margins for specialty contractors.
- Vinyl:Flexible PVC membranes stretched over steel or polymer wall frames offer lower first cost with 7-10 year replacement cycles.
- Steel:Corrugated metal wall panels provide structural rigidity for above-ground and semi-inground configurations.
Fiberglass commands premium positioning; vinyl maintains volume leadership in replacement-sensitive segments.
Installation Type:
Buyer technical confidence and permit complexity determine whether procurement flows through certified contractors or direct-to-consumer channels.
- Professional:Licensed contractors manage excavation, structural work, and equipment integration with warranty backing. Commercial aquatic centers and hospitality operators in the United States and Spain mandate professional installation to satisfy insurer and regulator requirements.
- Modular:Prefabricated panel systems with standardized connection interfaces enable rapid assembly without wet trades. Temporary hospitality installations across Spain and rental housing retrofits are expanding most quickly as landlords seek removable amenities.
- DIY:Consumer-assembled above-ground packages with simplified plumbing connections.
- Permanent:Fixed foundations with integrated hardscaping and structural integration.
Professional installation dominates value capture; modular approaches are gaining share fastest in transient-use applications.
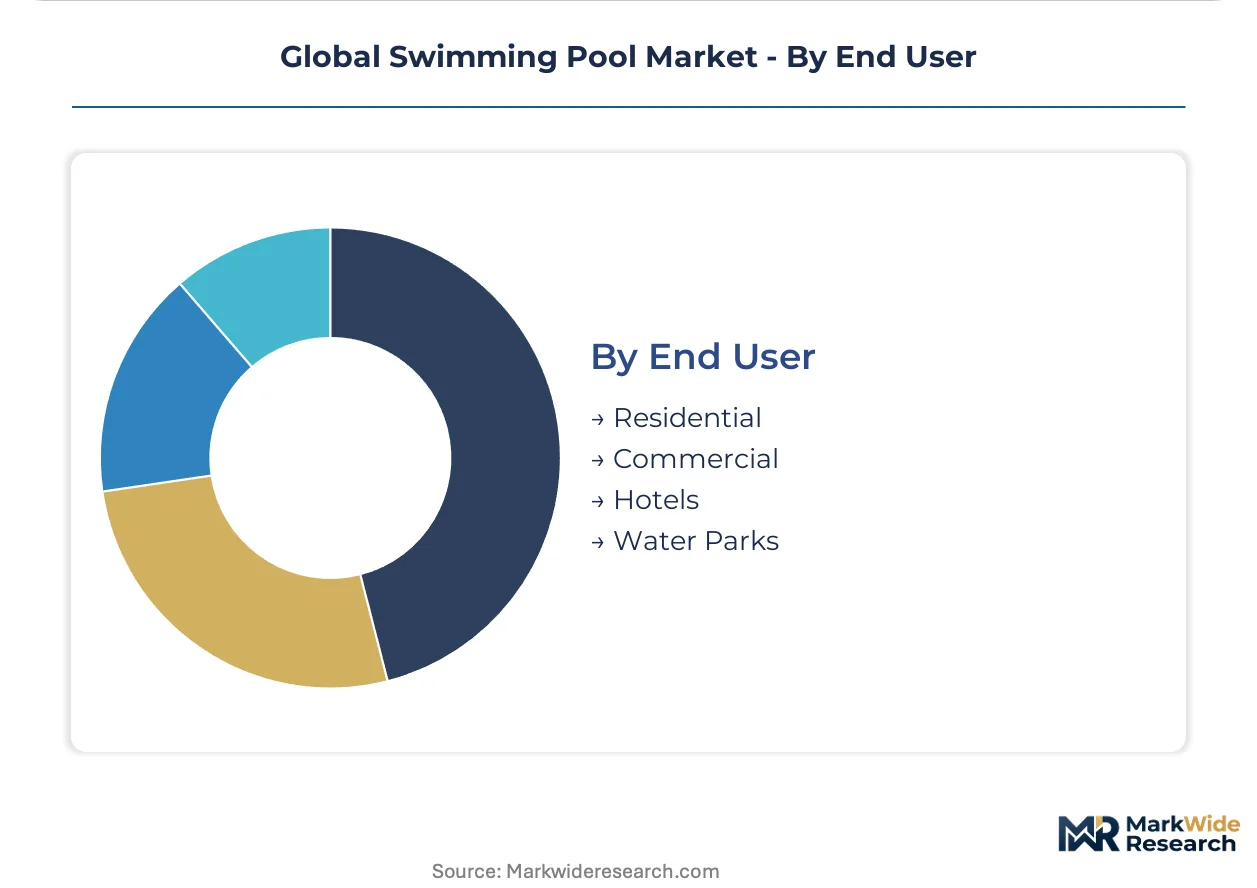
End User:
Revenue concentration and maintenance contract attach rates vary dramatically across ownership structures and utilization intensity.
- Residential:Single-family homeowners prioritize aesthetic integration and year-round usability. Suburban United States markets drive fiberglass and concrete inground specifications with automated chemistry monitoring and variable-speed pump upgrades.
- Hotels:Luxury hospitality operators in Dubai and Southeast Asia commission aquatic facilities as competitive differentiators, specifying integrated filtration, LED lighting, and heat pump systems with 24/7 operational redundancy.
- Commercial:Fitness centers and municipal facilities emphasizing lane swimming and programmed aquatic therapy.
- Water Parks:High-throughput entertainment venues with specialized wave generation and sanitation protocols.
Residential ownership anchors installed base; hotel operators drive equipment specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's hurricane recovery zones and California's drought-mitigation districts concentrate fiberglass shell demand through accelerated depreciation schedules for hospitality rebuilds. The Inflation Reduction Act channels heat pump subsidies toward pool thermal systems in sunbelt counties.
United States
Suburban homeowners in Texas and Arizona commission inground installations with variable-speed pump retrofits. The EPA enforces disinfection byproduct thresholds under the Safe Drinking Water Act for public aquatic facilities. Florida's resort corridor from Miami to Orlando drives fiberglass procurement for hurricane-resistant reconstruction timelines.
Australia
Metropolitan households in Sydney and Melbourne prioritize compact swim spas for terrace wellness installations. Standards Australia mandates AS 1926 barrier and fencing specifications for residential pool permits. Queensland's Gold Coast hospitality cluster specifies integrated filtration systems for year-round operational redundancy.
Spain
Coastal villa owners in Costa del Sol and Balearic Islands specify concrete infinity-edge designs. The EU F-Gas Regulation constrains refrigerant selections for pool heat pump replacements. Barcelona's modular installation specialists serve rental housing retrofits with removable steel-wall packages.
United Arab Emirates
Luxury hospitality operators in Dubai commission aquatic amenities as competitive differentiators for resort positioning. MOHAP enforces construction safety protocols for commercial aquatic facility permits. Abu Dhabi's Saadiyat Island development cluster sources factory-molded fiberglass shells for accelerated construction schedules.
Germany
Hotel operators in Bavaria and Baden-Württemberg upgrade thermal systems to low-GWP heat pump architectures. ECHA administers REACH substance restrictions prohibiting specific phthalate plasticizers in vinyl liner compounds. The Cologne-Düsseldorf industrial corridor hosts compounders reformulating bio-based polymer alternatives at certified production scales.
Global Swimming Pool Market Competitive Environment
North American producers anchor the premium equipment tier; European specialists hold regulatory-compliant material segments. The vendor base stratifies across full-stack system integrators, component fabricators, and regional installation networks. Three archetypes dominate: captive distribution operators, automated molding specialists, and IoT-enabled chemistry monitoring platforms. Consolidation pressures favor backward integration into polymer compounding and geographic expansion through distributor acquisitions.
Among publicly traded equipment suppliers, Fluidra S.A., Latham Group, Inc., and Pentair plc exemplify divergent scale strategies. Fluidra occupies a position spanning pumps through LED lighting integration. Latham Group anchors fiberglass production with factory-controlled gelcoat capabilities. Pentair represents captive distribution architecture sustaining replacement parts margin capture. These three structures illustrate how competitive positioning fragments across equipment depth, material specialization, and channel control vectors.
| Leading Market Players |
|---|
| Fluidra S.A. |
| Zodiac Pool Solutions |
| Latham Group, Inc. |
| Paramount Aquatics |
| Waterco Limited |
| Pentair plc |
| Maytronics Ltd. |
| Jacuzzi Group |
| Hayward Industries |
| Others |
Value Chain & Pricing Dynamics
Polymer resin indices and gelcoat chemical feedstock benchmarks cascade through fiberglass shell manufacturing into three distinct procurement tiers. Buyers in Dubai's resort corridor absorb premium markups for expedited factory-direct delivery, while Australian distributors negotiate volume rebates against standard lead-time schedules.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency replacement orders from planned seasonal procurement. Premium-mid-economy pricing differentiation tracks gelcoat finish grade and factory warranty duration, with certified low-GWP heat pump bundles commanding tier-one positioning. Cost compression in vinyl liner segments intensifies as bio-based compounders in Germany and Italy pass REACH compliance premiums downstream. Residential DIY assemblers exhibit highest price elasticity, whereas hospitality operators in Southeast Asia prioritize operational redundancy over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese permanent-magnet motor foundries supplying variable-speed pump manufacturers. Factory-molded fiberglass shells draw from gelcoat resin compounders in Germany, Italy, and Spain, while low-GWP compressor assemblies rest on South Korean and Japanese component specialists. Tariff exposure runs through Chinese steel-wall panel exports serving Spanish modular installers. Distribution runs through captive dealer networks for replacement parts and direct-to-consumer platforms for seasonal above-ground packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into polymer compounding to secure REACH-compliant formulations and compress input cost volatility.
For Market Incumbents: Deepen captive distribution control over replacement parts to defend margin capture against e-commerce price transparency. Secure dedicated capacity at certified bio-based compounders in the Cologne-Düsseldorf corridor before allocation constraints tighten. Incumbents must also lock in Taiwanese motor foundry partnerships before low-GWP heat pump demand accelerates compressor competition. For New Entrants and Emerging Players: Modular installation specialists in Spain's rental housing retrofit segment represent the most penetrable white-space target. Entrants should partner with independent service platforms in Australian metropolitan markets to bypass incumbent warranty bundling. A direct-to-consumer chemistry monitoring subscription model offers the clearest go-to-market angle for IoT-enabled sensor startups. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated fiberglass molding specialists with factory-controlled gelcoat capabilities in North American sunbelt counties. Long-term viability hinges on equipment electrification tailwinds and refrigerant chemistry transitions over the coming decade. Watch EPA refrigerant phase-down announcements and EU F-Gas allocation schedules as inflection indicators for heat pump equipment valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant bio-based formulations lock in European liner supply contracts against regulatory fragmentation. |
| Heat Pump Technology Licensing | Low-GWP architectures transfer to Southeast Asian resort developers facing EU F-Gas export constraints. |
| IoT Chemistry Monitoring Platform Launch | Subscription revenue streams displace reactive service calls in United States residential installations. |
| Captive Distribution Network Expansion | Dealer acquisitions in Texas and Arizona secure replacement parts margin capture against price transparency. |
| Modular Installation Joint Venture | Steel-wall panel partnerships with Spanish rental housing landlords access transient-use demand growth. |
Study Parameters
Document review covered SEC 10-K filings from publicly traded equipment suppliers, EU F-Gas regulatory databases, and REACH substance restriction notices, complemented by interviews with plant managers at fiberglass molding facilities, procurement leads at Dubai hospitality developers, and aftermarket service heads at Australian distributor networks. Secondary validation drew from customs trade data, EPA enforcement records, and Standards Australia certification registries. Bottom-up volume estimates triangulated against top-down expenditure flows across residential, hospitality, and commercial end-use segments.
Historical shipment patterns cross-referenced against panel input from equipment procurement officers and EPC contractors active in Southeast Asian resort developments. The analytical framework segmented across product type, material chemistry, installation mode, and end-use intensity throughout the forecast period. CAGRs were derived from regression against macroeconomic indicators and regulatory enforcement schedules. Industry-specific inputs included heat pump adoption curves tied to IRA subsidy eligibility and swim spa penetration rates in dense metropolitan housing.
Caveats apply where refrigerant phase-down acceleration, hurricane reconstruction timelines in Florida, or drought-mitigation policy shifts in California could materially shift the outlook. Forecasts reflect documented assumptions about compliance cost pass-through and distributor inventory cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Artificial Turf Market