

Swimming Pool Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool Accessories Market Insights
The capital-intensity divergence between integrated manufacturers and assembly-focused distributors is redrawing competitive boundaries in pool accessories. Fluidra leverages its European manufacturing footprint to sustain margin control across heating and filtration systems. Pentair anchors North American demand through specialized automation and smart-pool technologies.
Swimming pool accessories encompass the mechanical, electrical, and chemical ancillary products that maintain water quality, regulate temperature, secure physical safety, and extend seasonal usability of contained aquatic installations; these items typically incorporate UV-stabilized polymers, 316-grade stainless hardware, and salt-chlorine compatible electronics rated for continuous outdoor exposure. Cleaning equipment commands the largest revenue pool among product types due to recurring replacement cycles and robotization upgrades, while lighting systems represent the fastest-expanding segment as LED retrofits and color-changing installations displace legacy incandescent fixtures. Residential pools generate the dominant application volume, though hotels and resorts concentrate margin-rich demand for integrated automation and aesthetic water features.
EPA Energy Star requirements and CPSC entrapment-prevention standards shape product design and liability exposure for manufacturers serving the United States market. State-level regulations in California Title 24 and Florida building codes further constrain pump efficiency and barrier specifications. Stakeholders must monitor evolving municipal water-use restrictions and electrification incentives as these policies increasingly determine which accessory categories qualify for permitted installation.
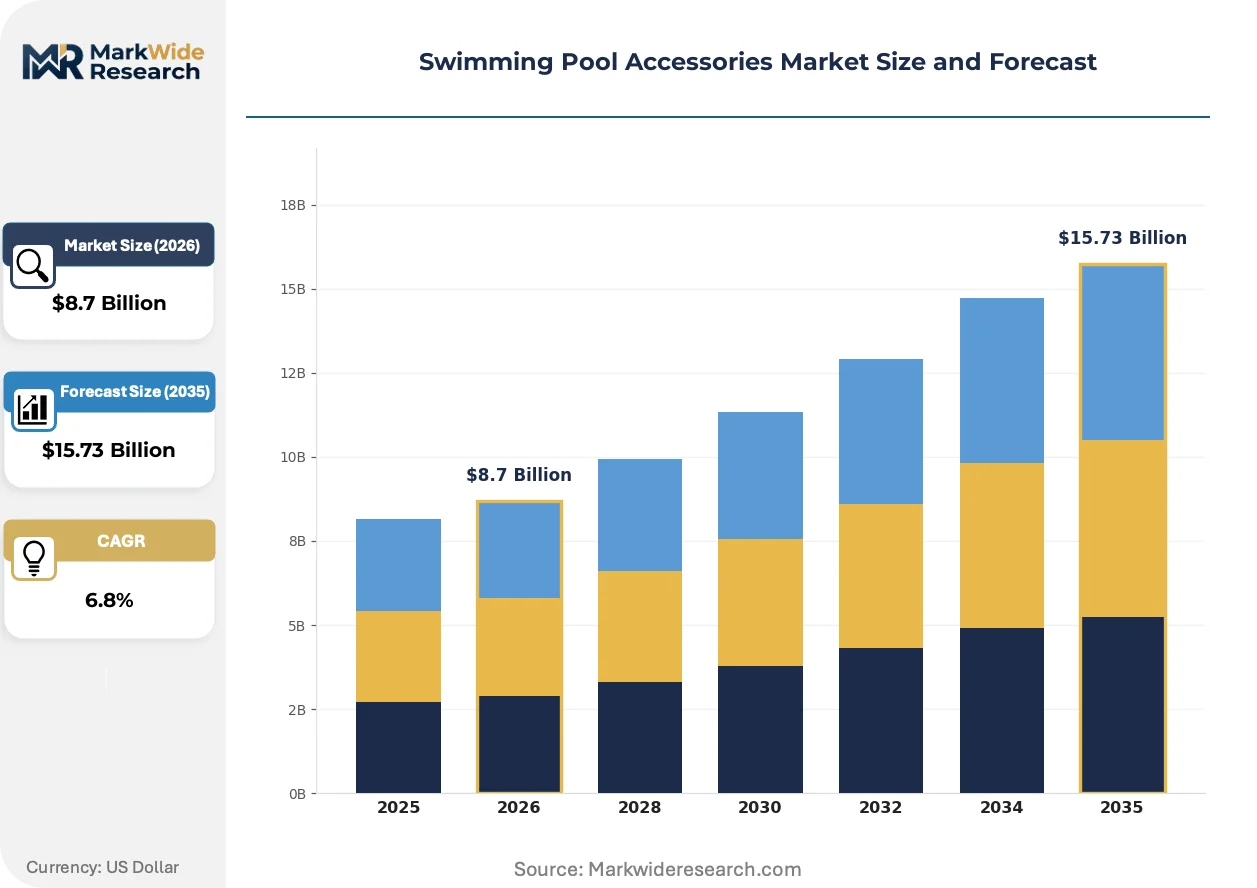
Market Dynamics
Residential pool owners are accelerating purchases of robotic cleaning systems and smart-pool controllers, compressing replacement cycles for legacy suction-side equipment and rewiring distributor inventory priorities toward connected automation SKUs.
Growth Catalysts
- EPA Energy Star pump mandates:Federal efficiency standards for pool pumps are forcing equipment upgrades across existing residential installations, creating pull-through demand for compatible filtration and control accessories.
- Sun Belt climate concentration:Arizona, Texas, and Florida pool ownership rates sustain replacement part velocity and shorten purchasing cycles for seasonal preparation goods.
- Salt-chlorine generator compatibility:Corrosion-resistant 316-grade stainless hardware and titanium-cell electronics are expanding addressable market for coastal and saltwater pool conversions.
Market Restraints
- UV-stabilized polymer input costs:Specialized polyethylene and ABS resin prices fluctuate with petrochemical feedstock volatility, squeezing margin on injection-molded skimmers and ladder components.
- Chinese component concentration:Pump motors, electronic control boards, and LED drivers cluster in Guangdong and Zhejiang manufacturing zones, exposing supply continuity to port congestion and tariff exposure.
- Seasonal demand compression:Northern latitude pool seasons constrain revenue recognition to 4-5 month windows, forcing working capital intensity for inventory build and off-season discounting.
Strategic Opportunities
- Electrification incentives:The US Inflation Reduction Act heat pump tax credits are accelerating residential heater retrofits, opening bundled sales channels for compatible automation and monitoring accessories.
- Commercial hospitality automation:Hotels and resorts are consolidating vendor relationships for integrated water-feature and lighting control systems, favoring full-suite suppliers over component specialists.
- Subscription-based chemical monitoring:IoT-enabled water quality sensors paired with automatic reordering platforms are displacing traditional retail chemical purchasing in suburban California and Florida markets.
Industry Challenges
- IP-67 enclosure certification timelines:Third-party validation for continuous outdoor electronics exposure extends product launch schedules by 8-14 months, delaying revenue capture across heating and lighting segments.
- Legacy automation integration:Retrofit compatibility with 1990s-era pneumatic and basic digital control systems requires redundant engineering resources, fragmenting R&D allocation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool Accessories Market Trends and Innovations
Connected pool equipment is compressing the traditional service-technician relationship, shifting diagnostic and maintenance authority toward homeowner-controlled mobile applications and cloud-based manufacturer support portals.
Robotic cleaners with LiDAR mapping and machine-learning debris detection are displacing pressure-side and suction-side automatic pool cleaners across premium residential installations. Sun Belt pool service companies are standardizing fleet purchases around these units. The technology is compressing labor hours per service visit and enabling route-density optimization for regional operators.
California Title 24 building efficiency standards are mandating variable-speed pump installations and restricting single-speed equipment in new construction and major renovations. Manufacturers are reconfiguring distribution inventories toward multi-speed and smart-controlled SKUs. The regulation is accelerating obsolescence of legacy pump inventories in Western US wholesale channels.
Commercial buyers are unbundling after-sales service contracts from initial equipment procurement, selecting specialized regional service firms over manufacturer-captive technicians. Hotels and municipal facilities are driving this fragmentation. The pattern is most pronounced in Florida and Arizona where third-party pool service density supports competitive technician labor markets.
Swimming Pool Accessories Market Segmentation
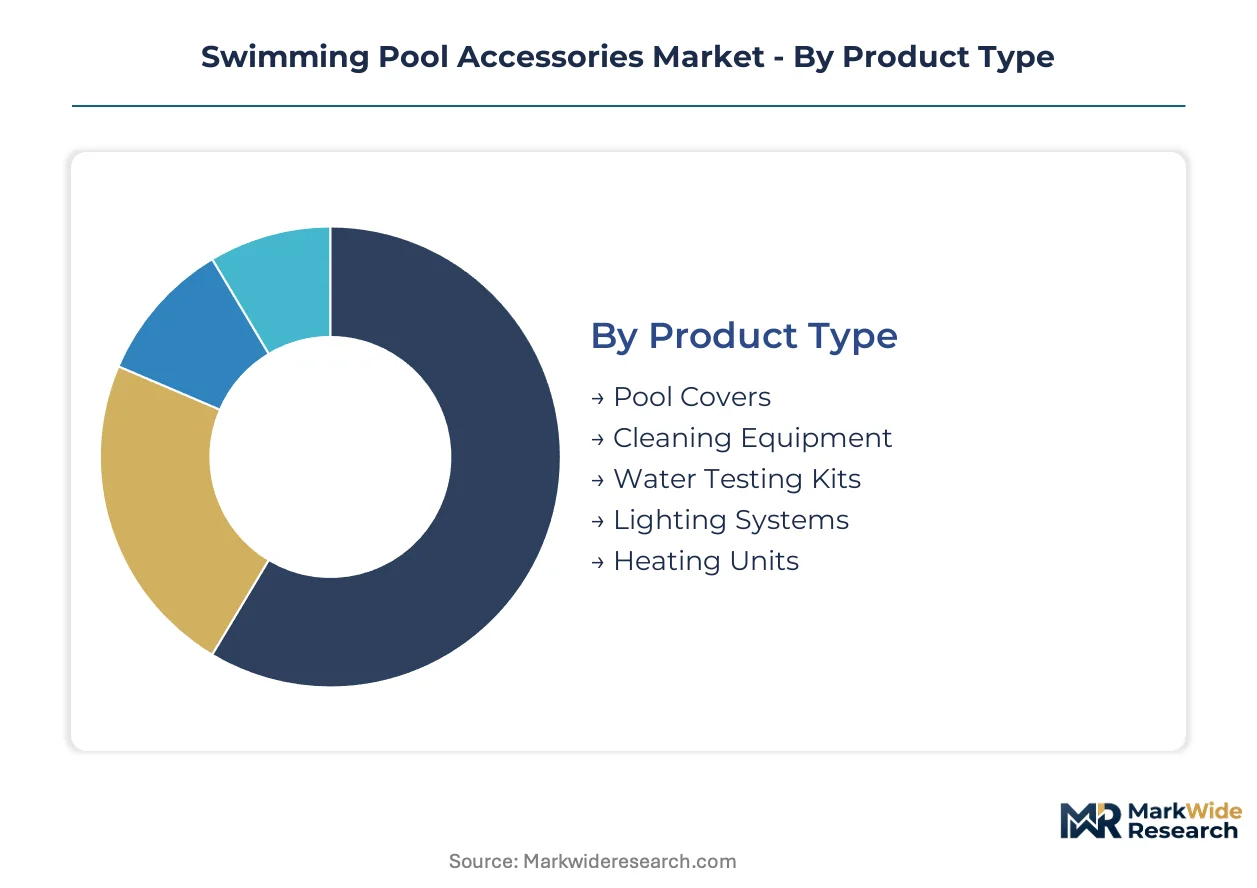
Accessory segmentation in swimming pools tracks divergent replacement cycles and margin profiles. Product type determines raw material exposure to petrochemical volatility, while installation type governs compatibility requirements and customer lifetime value.
Product Type:
Cleaning equipment faces the most acute substitution pressure as robotic systems displace legacy suction-side and pressure-side alternatives.
- Cleaning Equipment:Robotic cleaners with LiDAR mapping and machine-learning debris detection command premium positioning. Sun Belt pool service companies in Florida and Arizona are standardizing fleet purchases around these units, compressing labor hours per service visit.
- Lighting Systems:LED retrofits and color-changing installations displace legacy incandescent fixtures across residential and hospitality segments. California Title 24 efficiency standards accelerate obsolescence of single-color halogen units in Western US wholesale channels.
- Pool Covers:UV-stabilized polyethylene and mesh safety barriers serve seasonal protection and evaporation control needs.
- Water Testing Kits:Digital sensors paired with smartphone applications are displacing traditional chemical reagent strips in suburban markets.
- Heating Units:Heat pump configurations eligible for IRA tax credits are gaining share against legacy gas-fired equipment.
Cleaning equipment retains volume leadership; lighting systems hold the steepest expansion curve.
Application:
Cost tier stratification separates high-volume residential replacement parts from margin-rich integrated automation packages.
- Residential Pools:Single-family homeowners generate dominant unit volume through seasonal preparation purchases and mid-cycle upgrades. EPA Energy Star pump mandates are forcing equipment upgrades across existing installations, creating pull-through demand for compatible filtration accessories.
- Hotels & Resorts:Commercial hospitality buyers concentrate demand for aesthetic water features and unified lighting control systems. Properties in Florida and Arizona are unbundling after-sales service contracts from initial procurement, selecting specialized regional service firms.
- Commercial Pools:Municipal and institutional facilities prioritize durability certifications and extended warranty terms.
- Sports Facilities:Competition-grade venues require precision temperature control and chemical automation for regulatory compliance.
- Recreational Centers:Community pools balance budget constraints against safety barrier and entrapment-prevention mandates.
Residential pools anchor unit volume; hotels and resorts concentrate margin expansion.
Installation Type:
Supply concentration for inground components clusters around specialized excavation and plumbing contractors.
- Inground Pools:Permanent concrete and fiberglass installations require 316-grade stainless hardware and salt-chlorine compatible electronics. Coastal conversions in Florida and California are expanding addressable market for corrosion-resistant accessories.
- Above Ground Pools:Seasonal assembly products face compressed purchasing windows and working capital intensity for inventory build.
- Portable Pools:Temporary inflatable and frame structures serve rental property and trial ownership segments.
- Permanent Pools:Fixed installations with integrated automation command the longest customer lifetime value profiles.
Inground pools retain equipment value concentration; above ground pools face the shortest replacement cycles.
Distribution Channel:
Customer type fragmentation separates professional installer procurement from direct consumer purchasing.
- Pool Supply Wholesalers:Regional distributors maintain inventory depth for contractor-grade equipment and emergency replacement parts. California and Florida building codes are reshaling pump and barrier specifications, forcing distributor SKU reconfiguration.
- Online Stores:E-commerce platforms capture consumer-direct sales for standardized accessories and subscription chemical replenishment. IoT-enabled water quality sensors paired with automatic reordering platforms are displacing traditional retail chemical purchasing.
- Specialty Retailers:Local pool stores provide installation support and warranty claim handling for complex automation systems.
- Home Improvement Chains:Big-box retailers concentrate seasonal merchandise and entry-level cleaning equipment.
Pool supply wholesalers retain contractor loyalty; online stores are gaining share fastest in chemical and consumable categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in swimming pool accessories tilt heavily toward manufacturing concentration in East Asian electronics clusters and polymer processing zones, while North American and European markets absorb finished systems through wholesale distribution networks.
United States
Sun Belt states sustain the highest pool ownership density globally, with Arizona, Texas, and Florida driving replacement part velocity. EPA Energy Star pump mandates and CPSC entrapment-prevention standards reshape product specifications and liability exposure. Southern California and South Florida host the densest concentrations of pool service companies and specialty retailers.
China
Guangdong and Zhejiang provinces manufacture pump motors, electronic control boards, and LED driver assemblies for export markets. Port congestion and tariff exposure create supply continuity risks for North American and European importers. The Yangtze River Delta clusters injection-molded polymer components and titanium-cell electronics for salt-chlorine systems.
Germany
Central European demand concentrates in residential heating and filtration upgrades, with variable-speed pump retrofits accelerating under EU F-Gas Regulation and energy efficiency directives. Bavaria and Baden-Württemberg host specialized automation integrators serving commercial hospitality clients across the Alpine and Mediterranean leisure corridors.
Australia
Queensland and New South Wales sustain year-round pool usage, compressing seasonal demand patterns seen in Northern Hemisphere markets. The country's national building code mandates barrier specifications and entrapment prevention that exceed baseline ISO standards. Perth and Melbourne distributors stock corrosion-resistant hardware for coastal saltwater pool conversions.
Brazil
São Paulo and Rio de Janeiro metropolitan areas concentrate residential pool construction despite compressed purchasing power relative to North American benchmarks. Import dependency for electronic automation systems creates working capital intensity for regional distributors. The country's national consumer protection regulator enforces warranty and safety labeling requirements on imported equipment.
Swimming Pool Accessories Market Competitive Landscape
Concentration sits with integrated European manufacturers and North American automation specialists that control heating, filtration, and smart-control technology stacks. The vendor base spans three tiers: full-suite system integrators with captive manufacturing, component specialists focused on single product categories, and private-label assemblers serving mass-market retail channels. Strategic moves center on backward integration into polymer processing and electronics manufacturing to defend margin against petrochemical volatility, alongside geographic expansion through distribution partnerships in emerging Sun Belt markets.
Within the integrated manufacturing tier, Fluidra and Pentair exemplify divergent geographic anchoring strategies. Fluidra leverages its European manufacturing footprint across heating and filtration systems. Pentair anchors North American demand through specialized automation technologies. Among robotics-focused specialists, Maytronics occupies a position representing the machine-learning and LiDAR mapping segment that is compressing labor hours for pool service operators.
| Leading Market Players |
|---|
| Fluidra |
| Hayward Industries |
| Pentair |
| Maytronics |
| Intex Recreation |
| Waterco |
| Emaux Water Technology |
| Leslie's |
| Pool Corporation |
| Others |
Pricing and Supply Chain Analysis
Robotic cleaner adoption replacing suction-side equipment is redrawing procurement geography toward Guangdong electronics clusters while compressing margin pools for legacy component distributors across North American wholesale channels. This substitution dynamic simultaneously elevates pricing power for integrated automation manufacturers and erodes price realization for single-category component suppliers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in pool automation systems. Price differentiation rests on UL certification tier and after-sales service bundling, with premium robotic units commanding substantial markups over basic suction-side alternatives. Cost compression in economy-tier injection-molded components is intensifying because of petrochemical feedstock volatility. Residential direct consumers exhibit highest price sensitivity, while commercial hospitality buyers demonstrate lowest sensitivity due to total-cost-of-ownership framing.
Supply Chain Analysis
China and Taiwan anchor pump motor and electronic control board production for global pool equipment markets. Manufacturing draws from specialized polyethylene resin, 316-grade stainless steel, and titanium-cell electronics as critical inputs. Single-source vulnerability concentrates in Guangdong province port corridors, exposing North American importers to congestion-related disruption. Distribution runs through regional pool supply wholesalers that maintain contractor-grade inventory depth for emergency replacement scenarios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated commercial hospitality procurement teams that unbundle service contracts from equipment purchases, fragmenting vendor relationships and compressing supplier margin capture.
For Market Incumbents: Fortify position through backward integration into UV-stabilized polymer processing and captive electronics manufacturing to defend margin against petrochemical volatility. Invest in IP-67 enclosure certification capacity to accelerate product launch timelines threatened by extended third-party validation cycles. Prioritize channel control through exclusive distribution partnerships with Sun Belt pool service companies standardizing fleet purchases.
For New Entrants and Emerging Players: Lead with subscription-based chemical monitoring platforms paired with IoT-enabled water quality sensors, targeting suburban California and Florida residential markets where automatic reordering displaces traditional retail purchasing. Pursue white-space opportunity in corrosion-resistant hardware for coastal saltwater pool conversions. Deploy direct-to-consumer e-commerce go-to-market angles to bypass established wholesale distributor relationships.
For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated automation specialists with captive manufacturing footprints. Long-term viability centers on suppliers controlling heating, filtration, and smart-control technology stacks through the projection horizon. Target acquisition archetypes include robotics-focused specialists with machine-learning debris detection capabilities. Monitor EPA Energy Star pump mandate enforcement intensity as inflection indicator for replacement cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Processing | Captive supply of UV-stabilized resins insulates margin against Guangdong petrochemical price volatility. |
| IP-67 Certification Capacity Expansion | In-house validation for outdoor electronics exposure compresses product launch schedules by 8-14 months. |
| Subscription Platform Development | IoT-enabled water quality sensors with automatic reordering displace traditional retail chemical purchasing in California. |
| Commercial Hospitality Consolidation | Unified vendor relationships for integrated water-feature systems capture margin-rich demand from hotels and resorts. |
| Corrosion-Resistant Hardware Specialization | 316-grade stainless and titanium-cell electronics address expanding coastal saltwater pool conversion demand. |
Research Methodology
Desk research of regulatory filings, customs trade databases, and industry association technical standards preceded structured interviews with pool service company operators, wholesale distribution procurement managers, commercial hospitality facilities directors, and residential pool builder contractors. Primary fieldwork combined with secondary validation against EPA Energy Star certification records, CPSC entrapment-prevention compliance databases, and state-level building code repositories. Bottom-up unit economics triangulated against top-down market sizing across product type, application, installation type, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in segment-level modeling. Segmentation dimensions include product type, application tier, installation permanence, and geographic climate zone. CAGRs were derived through trend extrapolation of replacement cycle compression and regulatory upgrade mandates. Industry-specific forecast inputs incorporate salt-chlorine generator conversion rates and variable-speed pump retrofit velocity under Title 24 and EPA efficiency standards.
The analysis sits within stated boundaries; outcomes outside sustained Sun Belt construction activity and continued electrification incentive availability would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and petrochemical feedstock stability. Specific risks that could revise projections include tariff escalation on Chinese electronic components and municipal water-use restriction expansion. Recalibration cycles align with material shifts in federal efficiency mandate implementation and coastal corrosion-resistant hardware demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.