
 Australia Kids Scooter Market | 2026-2036
Australia Kids Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Kids Scooter Market Intelligence
The ACCC's mandatory safety standard for wheeled recreational devices is broadening the cost-of-entry calculus for new market entrants. Micro Scooters Australia leverages its domestic assembly footprint to navigate compliance thresholds with lower friction. Razor Australia sustains brand recognition through specialty store partnerships that control shelf positioning. Globber differentiates via adjustable-height platforms that extend product life across multiple age brackets.
Australia kids scooters are human-propelled or motor-assisted personal mobility devices designed for riders aged three to fourteen, typically constructed from aluminum alloy tubing with polyurethane or rubber wheel compounds, and intended to develop balance, coordination, and independent travel capabilities in controlled environments. Kick scooters occupy the volume core of the product type dimension, while electric scooters capture accelerating interest among the 9-12 Years and Teenagers age brackets where parental willingness to spend on powered alternatives has expanded. Aluminum dominates the material mix due to its strength-to-weight ratio, though composite frames are gaining traction in premium positioning where durability justifies higher unit economics.
The ACCC enforces mandatory safety standards under the Australian Consumer Law, while Standards Australia publishes AS/NZS 8124 specifications that govern mechanical and physical properties of wheeled toys sold domestically. TGA oversight intersects where injury reporting triggers product recall pathways that reshape manufacturer liability exposure. Stakeholders must monitor pending revisions to maximum speed thresholds for electric variants and the evolving interplay between online retail compliance obligations and direct-to-consumer import channels.
Market Dynamics
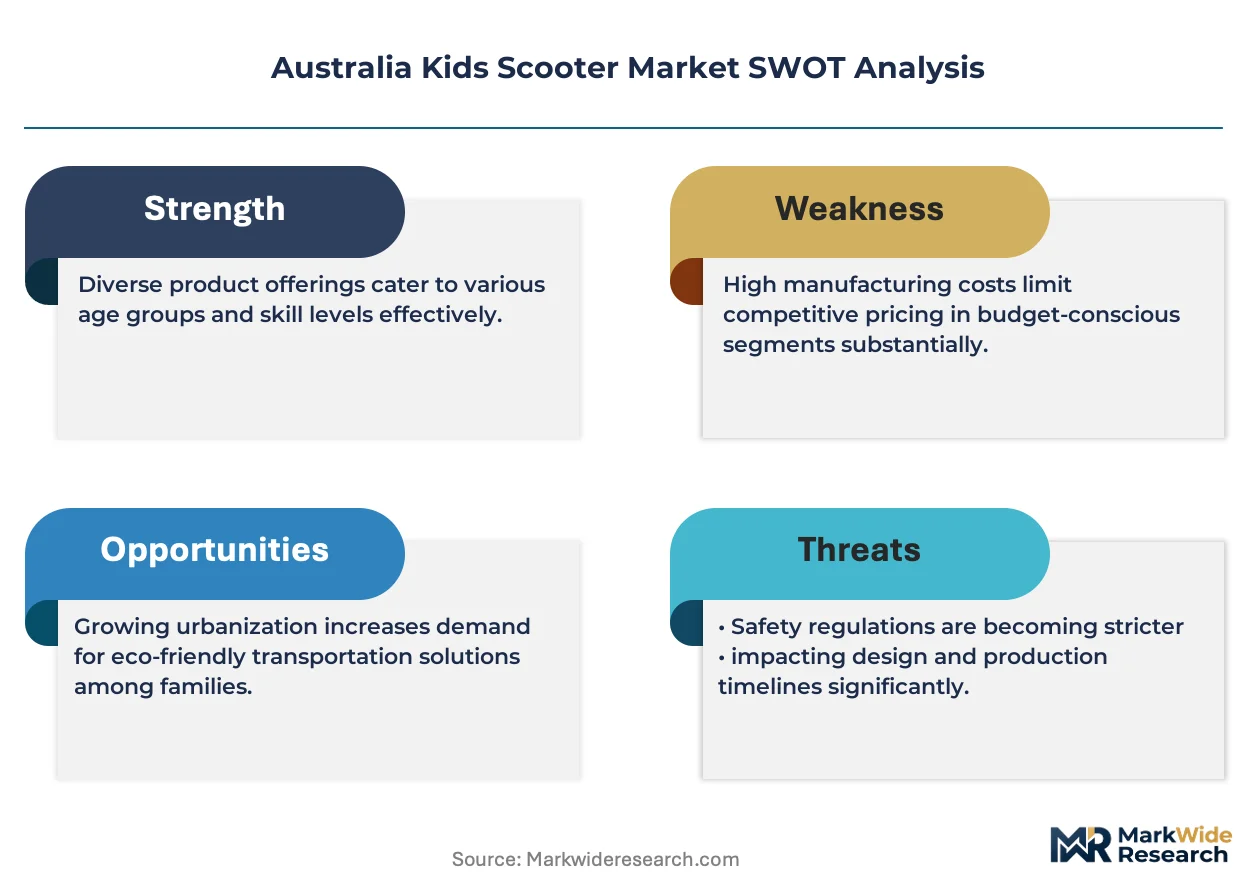
The ACCC's mandatory safety standard for wheeled recreational devices is compressing import timelines and forcing domestic assembly investments among distributors seeking sustained shelf access in Australian retail channels.
Growth Catalysts
- AS/NZS 8124 alignment:Early learning centers in Victoria and New South Wales now mandate certified equipment procurement, creating institutional demand pull for compliant suppliers.
- Urban infrastructure density:Melbourne and Sydney's expanding dedicated scooter paths reduce parental safety concerns and enable independent child mobility in controlled environments.
- Polyurethane wheel compounds:Advances in abrasion-resistant formulations extend product lifecycles and justify premium positioning in replacement cycles.
Market Restraints
- Aluminum alloy price volatility:Input cost swings for frame tubing compress margin buffers for mid-tier positioning strategies.
- Import concentration risk:Reliance on Asian manufacturing clusters exposes distributors to shipping rate fluctuations and extended lead times.
- Maximum speed thresholds:Pending ACCC revisions to electric variant limits create inventory obsolescence risk for non-compliant stock.
Strategic Opportunities
- Queensland and Western Australia penetration:Household scooter ownership rates lag Victoria and New South Wales by substantial margins, offering geographic expansion runway.
- Direct-to-consumer import channels:Online retail compliance obligations remain inconsistently enforced, creating temporary arbitrage windows for agile entrants.
- Adjustable-height platform convergence:Modular frame designs that span 3-14 year age brackets reduce family replacement frequency and build brand loyalty.
Industry Challenges
- Product safety certification timelines:TGA injury reporting pathways trigger recall protocols that reshape manufacturer liability exposure and insurance costs.
- Skill gaps in compliance navigation:Importers lack specialized expertise in evolving online retail compliance obligations versus traditional wholesale channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Kids Scooter Market |
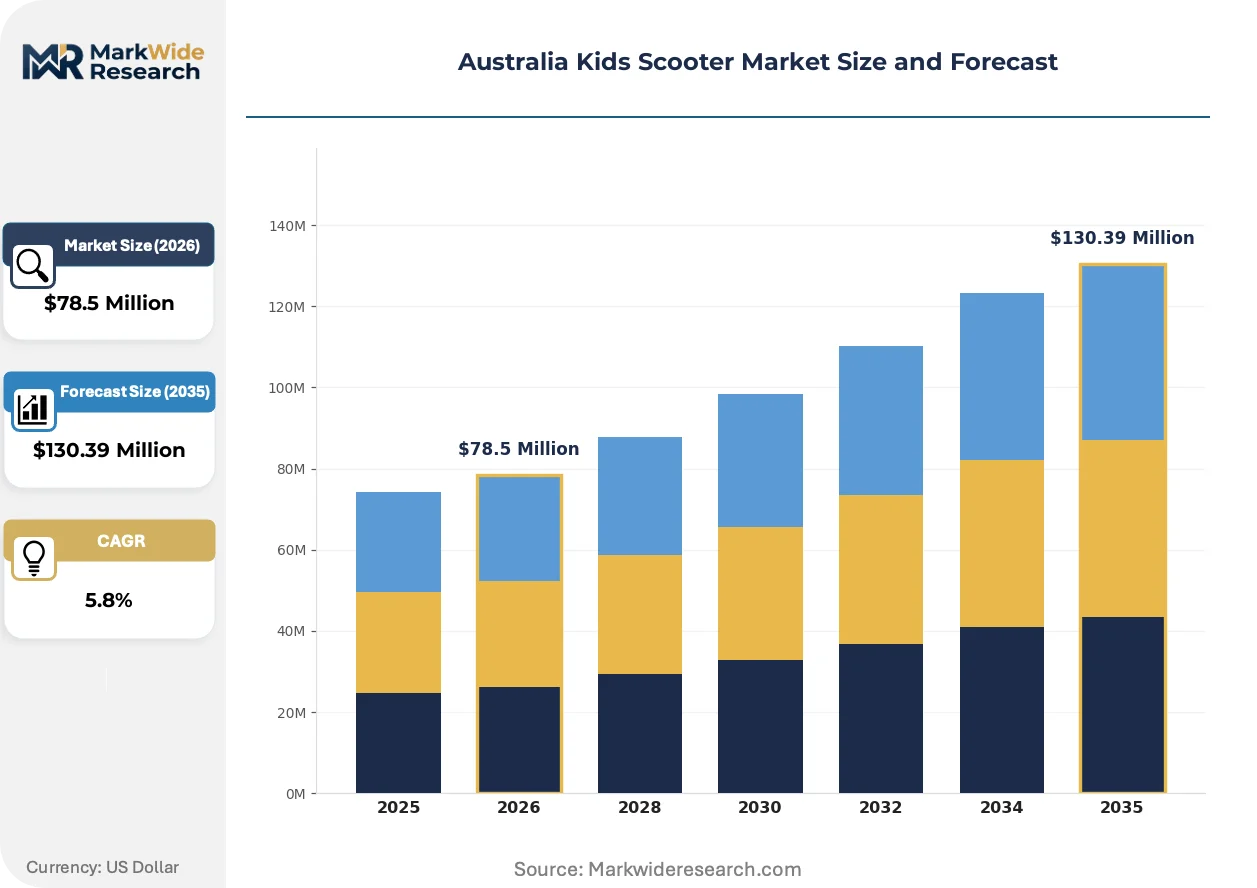
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $130.39 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kick Scooters, Electric Scooters, Foldable Scooters, Off-Road Scooters Material: Aluminum, Plastic, Steel, Composite Age Group: 3-5 Years, 6-8 Years, 9-12 Years, Teenagers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Sporting Goods Stores |
| Companies Covered | Micro Scooters Australia, Globber, Razor Australia, Fuzion Scooter, Radio Flyer, The Vault Pro Scooters, Swifty Scooters, Pacific Cycle, Segway, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Kids Scooter Market Strategic Shifts & Innovations
Product longevity engineering and regulatory compliance automation are reshaping competitive differentiation in Australia's kids scooter market. Manufacturers now prioritize adaptive designs and domestic certification capabilities over pure cost minimization.
Composite frame materials are expanding into premium positioning segments where durability justifies higher unit economics. Parents of 9-12 year riders demonstrate accelerating willingness to spend on powered alternatives with extended service intervals. This material shift is expanding into territory previously dominated by aluminum alloy tubing, compressing traditional price-performance hierarchies.
The ACCC's mandatory safety standard revision process is tightening mechanical property testing requirements for wheeled toys sold domestically. Importers face expanded documentation burdens and third-party verification costs. Electric variants targeting the Teenagers bracket bear the heaviest compliance load, prompting some distributors to delay powered product launches until thresholds stabilize.
Specialty store partnerships are displacing mass-market wholesale as the dominant channel for brand-controlled shelf positioning. Parents increasingly seek in-person fitting and safety guidance, particularly for first-time purchases in the 3-5 Years bracket. This channel rotation is most visible in Sydney and Melbourne, where dedicated scooter retailers concentrate in high-footfall urban corridors.
Australia Kids Scooter Market Segmentation
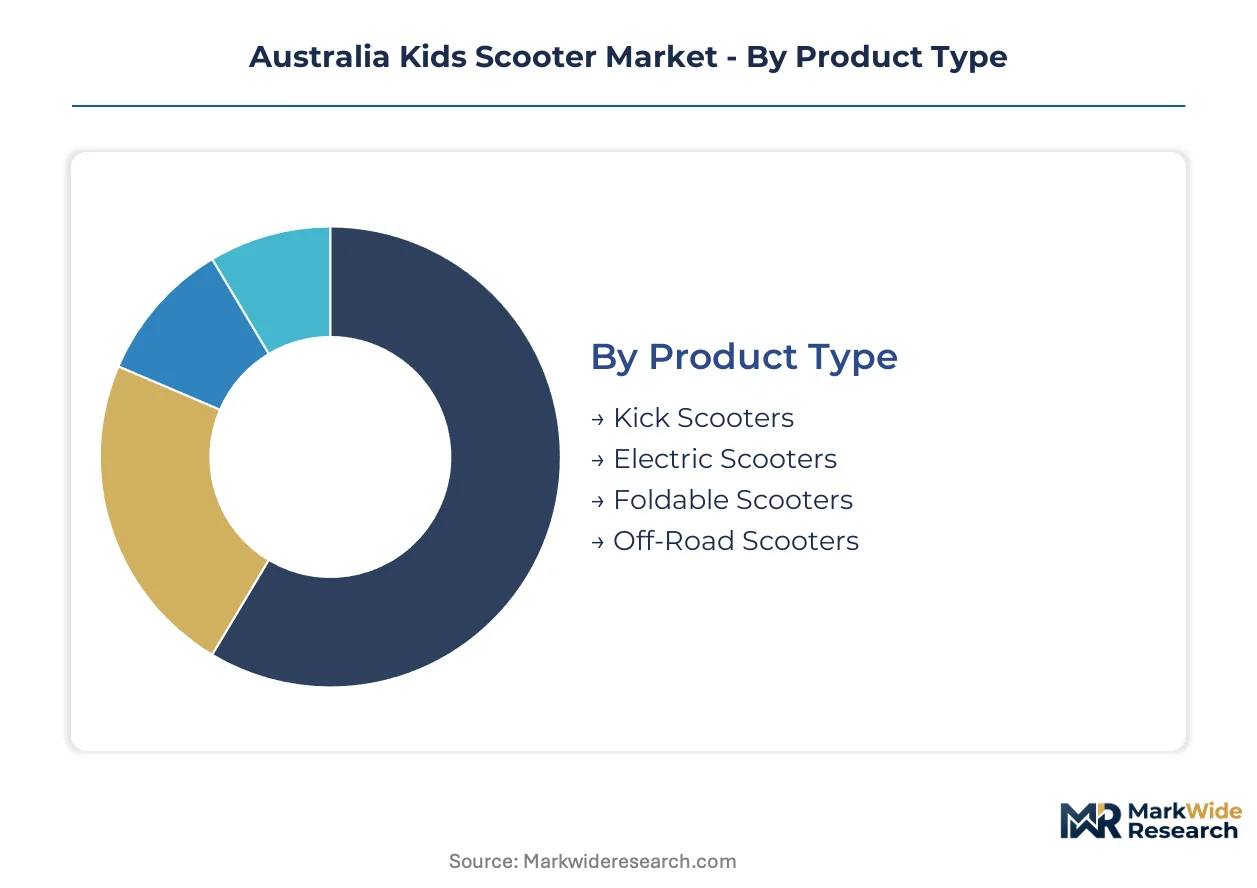
Segmentation in Australia's kids scooter market reflects divergent parental priorities across safety certification, urban mobility constraints, and age-appropriate feature sets. Suppliers configure product portfolios to capture replacement cycles that accelerate through childhood development stages and infrastructure access variations across Australian states.
Product Type:
Standardization dominates at entry price points while customization concentrates in premium tiers where adjustable geometry and power assistance justify higher unit economics.
- Kick Scooters:Human-propelled platforms with aluminum alloy tubing and polyurethane wheel compounds form the volume core of Australian retail. Demand concentrates in New South Wales and Victoria where Melbourne and Sydney's dedicated scooter paths enable independent child mobility in controlled environments, though AS/NZS 8124 certification requirements compress margin buffers for non-compliant imports.
- Electric Scooters:Motor-assisted variants with lithium-ion powertrains and regenerative braking systems capture accelerating interest among the 9-12 Years and Teenagers brackets. Parental willingness to spend on powered alternatives has expanded in urban corridors where infrastructure density reduces safety concerns, pending ACCC revisions to maximum speed thresholds create inventory risk for distributors holding non-compliant stock.
- Foldable Scooters:Collapsible frame designs with quick-release mechanisms address storage constraints in high-density Australian households.
- Off-Road Scooters:Reinforced suspension systems and pneumatic tire configurations target recreational use in Queensland and Western Australia where trail access exceeds dedicated urban infrastructure.
Leading the category by volume: Kick Scooters. Expanding most quickly: Electric Scooters.
Material:
Cost tier stratification aligns with durability expectations and replacement frequency across family budget segments.
- Aluminum:Aluminum alloy tubing dominates frame construction due to strength-to-weight ratios that enable child maneuverability without structural compromise. Victoria and New South Wales procurement mandates from early learning centers institutionalize demand for certified aluminum platforms, though input price volatility compresses margin buffers for mid-tier positioning strategies.
- Composite:Carbon fiber and glass-reinforced polymer formulations expand into premium positioning where extended service intervals justify higher unit economics. Parents of 9-12 year riders demonstrate accelerating willingness to spend on durability advantages that span multiple age brackets, compressing traditional price-performance hierarchies previously dominated by metal alternatives.
- Plastic:Polypropylene and ABS constructions serve entry-level price points in mass retail channels.
- Steel:Chromoly tubing persists in budget positioning where weight penalties are acceptable trade-offs for cost minimization.
Capturing highest volume: Aluminum. Gaining share fastest: Composite.
Age Group:
Application requirements shift from balance development to independent mobility as rider capabilities mature.
- 3-5 Years:Three-wheel platforms with low deck heights and lean-to-steer mechanisms dominate first-time purchases. Specialty store partnerships in Sydney and Melbourne concentrate demand where in-person fitting and safety guidance influence parental selection, AS/NZS 8124 mechanical property testing requirements impose documentation burdens on importers serving this bracket.
- 9-12 Years:Two-wheel configurations with adjustable handlebar stems and higher weight ratings capture replacement demand. Queensland and Western Australia penetration lags Victoria and New South Wales by substantial margins, offering geographic expansion runway for suppliers configuring products to this developmental stage.
- 6-8 Years:Transitional designs bridge stability features and performance capabilities.
- Teenagers:Adult-scaled platforms with enhanced load capacity and electric powertrain compatibility target extended use cycles.
Generating highest unit volume: 3-5 Years. Steepest expansion trajectory: 9-12 Years.
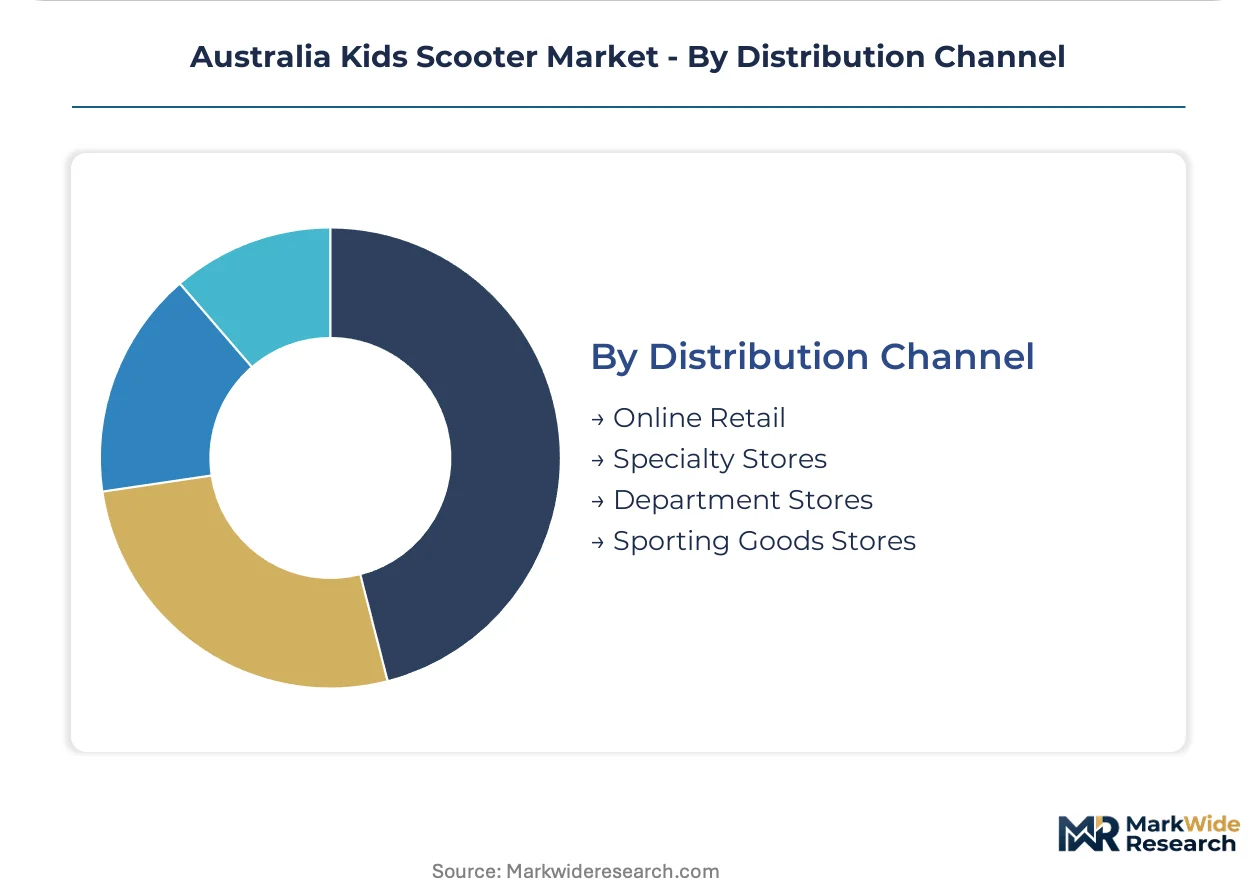
Distribution Channel:
Customer type and purchase occasion determine channel selection between transactional efficiency and consultative service.
- Specialty Stores:Dedicated scooter retailers in high-footfall Sydney and Melbourne corridors displace mass-market wholesale for brand-controlled shelf positioning. Parents increasingly seek in-person fitting and safety guidance, particularly for first-time purchases in the 3-5 Years bracket where improper sizing elevates injury risk.
- Online Retail:Direct-to-consumer platforms capture replacement purchases where prior product experience reduces consultation needs. Compliance obligations remain inconsistently enforced across import channels, creating temporary arbitrage windows for agile entrants navigating ACCC documentation requirements.
- Department Stores:Mass retail footprints serve convenience-driven purchases in suburban catchments.
- Sporting Goods Stores:Athletic positioning aligns with performance-oriented segments in the 9-12 Years and Teenagers brackets.
Highest transaction volume: Specialty Stores. Climbing the fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household scooter ownership concentrates in New South Wales and Victoria, where urban density and dedicated infrastructure create favorable conditions for child mobility products. Queensland and Western Australia present substantial penetration gaps relative to these southeastern states. Geographic expansion strategies now target underpenetrated markets where trail access and suburban layouts demand differentiated product configurations.
New South Wales
Sydney's expanding network of dedicated scooter paths reduces parental safety concerns and enables independent child mobility in controlled environments. Early learning centers across the state now mandate AS/NZS 8124 certified equipment procurement under revised procurement guidelines. Specialty retailers concentrate in high-footfall urban corridors where in-person fitting services drive first-time purchases in the 3-5 Years bracket.
Victoria
Melbourne's infrastructure investments in active transport corridors support higher household penetration rates than any other Australian metro. The ACCC's mandatory safety standard enforcement creates compliance cost advantages for domestic assemblers over direct importers. Inner-north and eastern suburban clusters generate disproportionate demand for premium adjustable-height platforms that span multiple age brackets.
Queensland
Recreational trail access exceeds dedicated urban scooter infrastructure, shifting demand toward reinforced suspension and pneumatic tire configurations. State-level procurement policies for early learning centers lag Victoria and New South Wales by approximately 18-24 months in certification mandate adoption. Brisbane and Gold Coast retail corridors show emerging specialty store penetration as distributors test geographic expansion hypotheses.
Western Australia
Household ownership rates trail the national average by substantial margins, creating runway for suppliers configuring products to local conditions. Perth's dispersed suburban fabric limits pure urban mobility use cases and elevates multi-terrain product relevance. Direct-to-consumer import channels face inconsistent enforcement of online retail compliance obligations, creating temporary market access windows.
South Australia
Adelaide's compact urban form supports scooter mobility despite lower absolute infrastructure investment than Sydney or Melbourne. State education department pilot programs for scooter-based physical activity are expanding procurement volumes for certified equipment. Metropolitan retail coverage remains thinner than eastern states, with sporting goods stores capturing channel share absent dedicated scooter specialists.
Australia Kids Scooter Market Key Industry Players
Australian domestic assemblers anchor one tier; European and North American specialists hold premium positioning through brand recognition and adjustable-geometry patents. The vendor base spans three concentration levels: integrated distributors with domestic assembly footprints, import-dependent wholesalers serving mass retail, and direct-to-consumer specialists exploiting compliance enforcement gaps. Two strategic archetypes dominate: compliance-integrated players leveraging TGA pathway familiarity, and brand licensors relying on parent-company R&D pipelines. Competitive moves concentrate on specialty store partnership exclusivity and modular platform development that extends replacement cycles.
Within the domestic assembly tier, Micro Scooters Australia leverages local certification capabilities to navigate ACCC thresholds with reduced friction. Razor Australia occupies a position sustained through specialty store shelf positioning and heritage brand recognition among parents. Globber exemplifies the European adjustable-height specialist archetype, with modular frame designs that compress family replacement frequency across the 3-14 year developmental span.
| Leading Market Players |
|---|
| Micro Scooters Australia |
| Globber |
| Razor Australia |
| Fuzion Scooter |
| Radio Flyer |
| The Vault Pro Scooters |
| Swifty Scooters |
| Pacific Cycle |
| Segway |
| Others |
Cost & Logistics Intelligence
Early learning center procurement programs in Victoria and New South Wales anchor pricing power for certified suppliers, compressing margin buffers for import-dependent competitors while rewarding domestic assemblers with compliance cost advantages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade stratification, with AS/NZS 8124 alignment commanding measurable premiums over uncertified alternatives.
Pricing Analysis
Short lead-time premiums dominate pricing for specialty store channels serving first-time 3-5 year purchases, while spot inventory discounts accelerate in direct-to-consumer import channels with extended delivery windows. Price differentiation centers on certification tier and brand heritage, with Micro Scooters Australia and Razor Australia capturing loyalty premiums versus mass-market alternatives. Cost compression in mid-tier aluminum frames is intensifying because of alloy price volatility, making early learning centers the least price-sensitive segment due to procurement mandate rigidity, while suburban mass-market buyers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-specialty-retail channels handle demand from high-footfall Sydney and Melbourne corridors, while online platforms serve replacement purchases with lower consultation requirements. Manufacturing concentrates in China, Vietnam, and Taiwan for frame tubing and wheel assembly, with lithium-ion cells for electric variants drawing from South Korean and Japanese suppliers. Aluminum alloy and polyurethane compound dependencies expose distributors to commodity swings, with single-source vulnerability in certified component supply creating inventory risk. Distribution runs through importer-distributor networks with domestic assembly footprints navigating ACCC thresholds with reduced friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into domestic certification capabilities separates sustainable competitors from import-dependent wholesalers facing compliance cost escalation.
For Market Incumbents: Extend specialty store partnership exclusivity in Sydney and Melbourne to lock out emerging entrants, while deepening in-house production of adjustable-height platforms that compress family replacement frequency. Regulatory shift toward tighter ACCC speed thresholds for electric variants threatens inventory obsolescence for distributors without agile certification pipelines. For New Entrants and Emerging Players: Launch via direct-to-consumer online channels exploiting inconsistent enforcement of import compliance obligations, targeting Queensland and Western Australia where household penetration lags southeastern states by substantial margins. Geographic white-space in Brisbane and Gold Coast retail corridors offers testable expansion hypotheses before specialty store investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic assemblers with TGA pathway familiarity in Victoria, where compliance cost advantages compound over import-dependent competitors. Long-term viability over a multi-year window hinges on certification automation capabilities and modular platform R&D pipelines. Watch pending ACCC electric variant threshold revisions as inflection indicator for powered segment inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Footprint Expansion | ACCC compliance cost advantages compound against import-dependent wholesalers facing documentation burdens. |
| Adjustable-Height Platform R&D | Modular frame designs spanning 3-14 years reduce replacement frequency and build brand loyalty. |
| Specialty Store Partnership Exclusivity | In-person fitting services in Sydney and Melbourne corridors capture first-time 3-5 year purchases. |
| Direct-to-Consumer Channel Launch | Online retail compliance gaps create temporary arbitrage windows for agile entrants. |
| Queensland and Western Australia Expansion | Underpenetrated markets offer geographic runway with trail-access product configurations. |
Research Approach
Company filings, customs trade records, and early learning center procurement databases formed the secondary backbone, supplemented by primary interviews with scooter brand managers, specialty retailer owners, ACCC compliance officers, and aluminum alloy procurement leads at frame manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, age group, and distribution channel dimensions.
Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation modeling covering kick versus electric propulsion, aluminum versus composite materials, developmental age brackets, and channel structure. CAGRs derived from weighted average of replacement cycle frequencies, infrastructure investment trajectories, and certification adoption curves, with electric variant regulatory thresholds and polyurethane compound innovation timelines as key forecast inputs.
ACCC speed threshold revisions, aluminum alloy price volatility, and shipping rate fluctuations are the dominant revision risks requiring scenario modeling. Forecasts reflect documented assumptions about procurement mandate adoption timelines and infrastructure completion schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Global Sailing Dinghy Masts Market