
 AR & VR Headset Market | 2026-2036
AR & VR Headset Market Size, Share, and Industry Trends Forecast 2026-2036
AR & VR Headset Market Insights
CE marking under the EU MDR is reorganizing which manufacturers can sell clinical-grade headsets into European healthcare systems. Meta leverages its Quest ecosystem to sustain dominance in consumer standalone devices. Sony Group Corporation anchors its position in tethered VR through PlayStation console integration. Apple Inc. differentiates via custom silicon and spatial computing interfaces that command premium positioning.
AR and VR headsets are wearable display systems combining near-eye optics, motion sensors, and spatial audio processors to overlay or replace visual reality, with field-of-view specifications typically ranging from 90 to 110 degrees and refresh rates exceeding 90 Hz to minimize motion sickness. Their primary commercial purpose spans immersive entertainment, workforce simulation, and clinical intervention. Standalone headsets lead volume shipments as wireless convenience displaces PC-tethered configurations. Gaming remains the largest application segment, though enterprise training commands superior margin pools due to customized content and service attach rates. OLED technology dominates premium tiers while LCD panels occupy mass-market price bands.
FDA clearance pathways in the United States govern therapeutic claims for VR-based pain management and psychiatric intervention, while the EU AI Act imposes conformity requirements on biometric inference capabilities. FCC radio equipment authorization and ETSI spectrum harmonization in Europe shape wireless connectivity standards and cross-border market access. Stakeholders must monitor how FDA software-as-medical-device guidance and EU cybersecurity certification for connected wearables will redefine compliance costs and competitive moats.
Market Dynamics
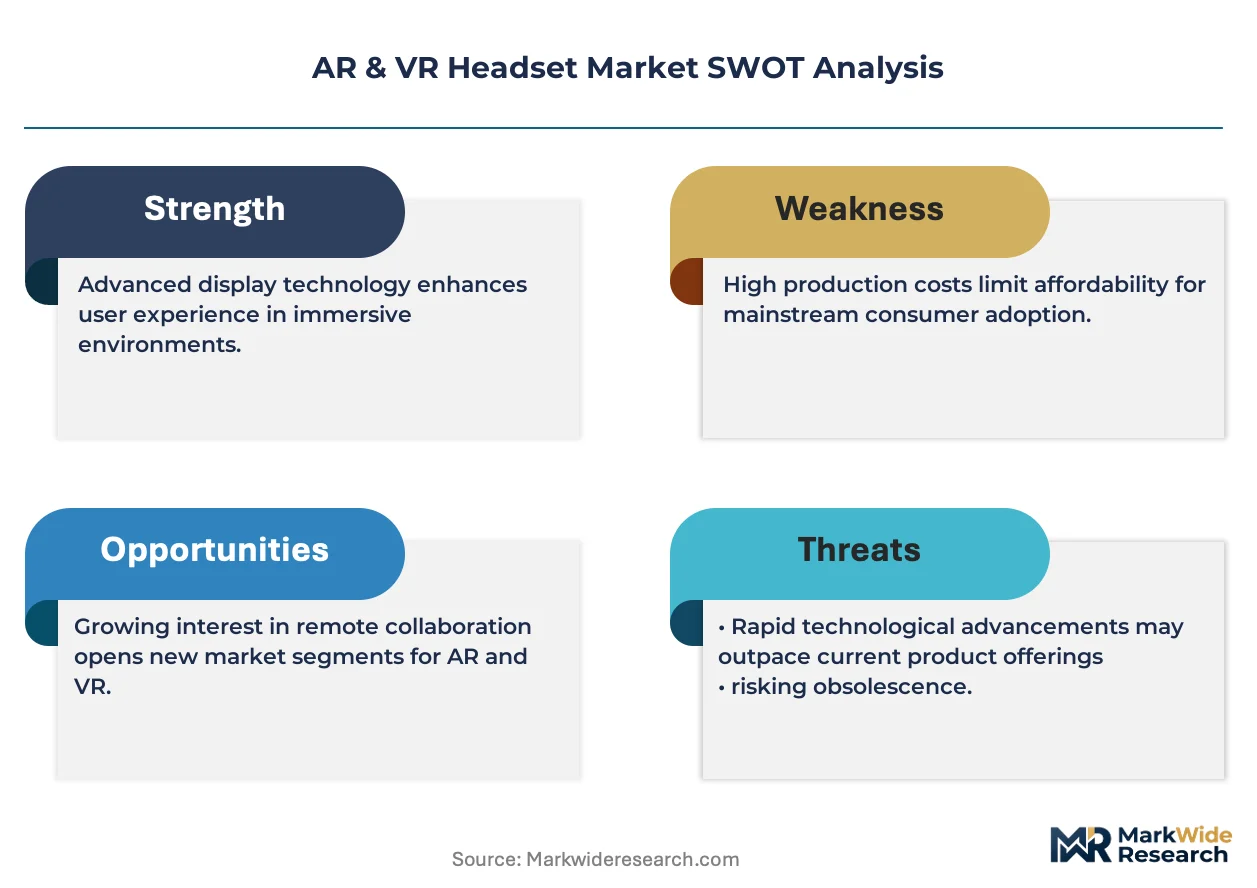
The EU AI Act's biometric data classification requirements are forcing headset manufacturers to redesign sensor architectures and compliance documentation, compressing product development timelines while elevating engineering costs across European distribution channels.
Growth Catalysts
- Clinical-grade VR therapy:FDA clearance pathways for pain management and PTSD intervention are expanding reimbursable use cases within United States healthcare systems, pulling enterprise headset procurement into hospital networks.
- Automotive engineering simulation:Germany's Stuttgart and Munich clusters are deploying AR headsets for assembly line validation and technician training, creating sustained B2B demand with multi-year service contracts.
- Wireless standalone form factors:90-110 degree field-of-view specifications at sub-90 Hz refresh rate thresholds are eliminating motion sickness barriers for consumer adoption in home entertainment environments.
Market Restraints
- OLED panel supply concentration:Premium tier display sourcing depends on Korean and Taiwanese foundry capacity, exposing manufacturers to input cost volatility and allocation rationing during semiconductor cycles.
- EU MDR CE marking timelines:Clinical-grade headset certification now requires 18-24 month conformity assessment windows, delaying European healthcare market entry against faster FDA 510(k) pathways.
- Smartphone AR substitution:Handheld spatial computing through camera-based overlays satisfies price-sensitive enterprise pilot programs, limiting tethered VR headset penetration in inspection workflows.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronics assembly are attracting contract manufacturers to establish headset production facilities serving Middle Eastern and African distribution.
- 5G edge-cloud rendering:Convergence of millimeter-wave connectivity and distributed GPU processing enables lightweight eyewear form factors that offload compute from local silicon.
- Saudi healthcare privatization:MOHAP regulatory harmonization with FDA standards is accelerating VR therapy imports for rehabilitation centers in Riyadh and Jeddah medical zones.
Industry Challenges
- Optical engineering talent scarcity:Waveguide design and pancake lens fabrication expertise concentrates in Silicon Valley and Taipei, forcing manufacturers to acquire specialized teams through premium compensation.
- Biometric data compliance complexity:GDPR Article 9 special category processing requirements intersect with EU AI Act conformity for pupil tracking and gaze estimation, demanding dual legal frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR & VR Headset Market |
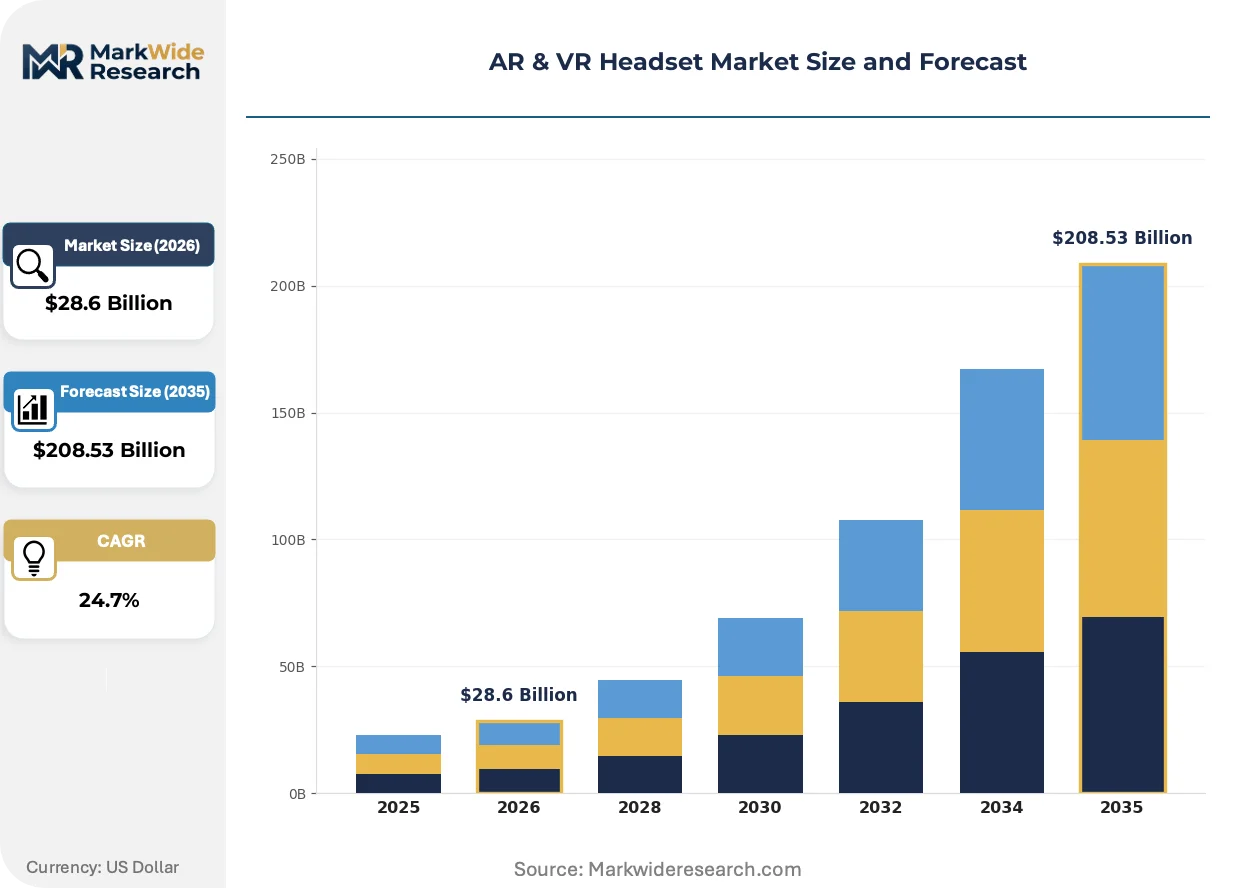
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $208.53 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Smartphone-Based, PC-Based Application: Gaming, Training, Education, Therapy User Type: Individual Consumers, Enterprises, Educational Institutions, Healthcare Providers Technology: OLED, LCD, Motion Tracking, Spatial Audio |
| Companies Covered | Meta, Sony Group Corporation, Apple Inc., ByteDance, DPVR, HTC Corporation, Microsoft Corporation, Picotech, Xreal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR & VR Headset Market Trends and Innovations
Pancake optical stacks are compressing headset thickness while expanding field-of-view, triggering industrial design pivots across both consumer and enterprise product lines as ergonomics displace raw performance in purchasing criteria.
Silicon-carbide waveguide substrates are miniaturizing projection engines from 40mm to 18mm thickness without luminance degradation. Automotive HUD suppliers are licensing these architectures for AR eyewear, compressing the traditional 36-month optical development cycle into 14-month iterations. This miniaturizing trend is enabling fashion-forward frame designs that pass workplace safety certification.
EU AI Act risk-classification mandates for biometric inference systems are forcing headset makers to segregate data processing between on-device and edge-cloud architectures. Manufacturers serving European healthcare and enterprise sectors must now maintain dual firmware branches. German industrial users in Bavaria are demanding explicit audit trails for gaze-data retention as procurement qualification criteria.
Enterprise buyers are unbundling hardware acquisition from content licensing, shifting from perpetual software ownership to per-seat annual subscriptions. This transition compresses vendor cash conversion cycles while elevating customer lifetime value metrics. United States defense contractors and Japanese automotive suppliers are piloting this model most aggressively, using it to justify expanded pilot program budgets.
AR & VR Headset Market Segmentation
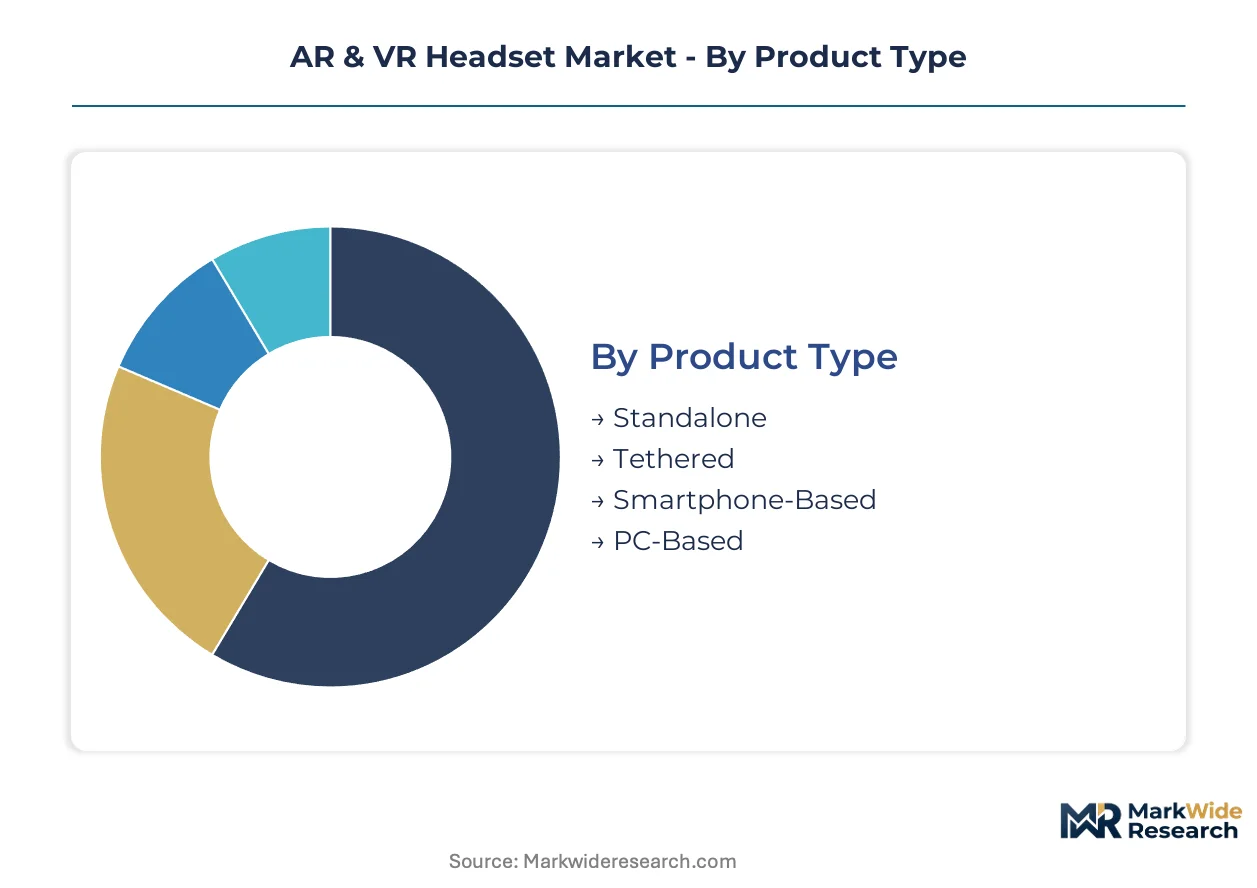
Segmentation in the AR & VR headset market reveals divergent channel economics. Consumer retail, enterprise direct sales, and institutional procurement each favor distinct form factors and price-performance configurations.
Product Type:
Standalone headsets flow through mass retail and direct-to-consumer channels. Tethered configurations dominate enterprise procurement offices and systems integrators.
- Standalone:Wireless all-in-one units integrate processing, display, and battery within the head-mounted enclosure. Consumer demand concentrates in United States home entertainment environments where cable-free setup eliminates friction. Meta's Quest ecosystem anchors this segment through content library depth and social feature integration.
- Tethered:External compute dependency via PC or console connection delivers superior graphical fidelity and reduced latency. German automotive engineering clusters around Stuttgart and Munich deploy these for assembly line validation where precision rendering justifies infrastructure investment.
- Smartphone-Based:Shell devices leverage handset processing and display, occupying entry-level price bands through carrier retail partnerships.
- PC-Based:External GPU dependency serves simulation-heavy applications in defense contractor training environments and Japanese automotive supplier technical centers.
By volume, Standalone leads. By growth pace, Tethered is climbing the fastest in enterprise verticals.
Application:
Margin concentration varies sharply across use cases. Gaming generates volume throughput. Training commands superior attach rates for service contracts and content licensing.
- Gaming:Immersive entertainment remains the largest addressable application, with 90-110 degree field-of-view specifications and 90+ Hz refresh rates minimizing motion sickness in extended sessions. United States consumer retail channels prioritize wireless convenience and social multiplayer features over raw performance metrics.
- Training:Workforce simulation delivers multi-year service contracts with customized content development. FDA clearance pathways for VR-based skills assessment are expanding reimbursable deployment within hospital networks and industrial safety programs.
- Education:Institutional procurement through school districts and university technology offices favors durable hardware with centralized device management platforms.
- Therapy:Clinical-grade applications require CE marking under EU MDR for European healthcare system entry, with 18-24 month conformity assessment windows delaying market access relative to FDA 510(k) pathways.
By installed base, Gaming dominates. By margin expansion, Therapy shows the steepest trajectory as reimbursement codes mature.
User Type:
Procurement authority and budget cycles differentiate customer economics. Individual consumers purchase episodically. Enterprises commit to multi-year fleet deployments.
- Individual Consumers:Price-sensitive purchasers responding to content library breadth and social feature ecosystems. Retail channel promotions and holiday purchasing cycles drive volume concentration.
- Enterprises:B2B procurement offices in Germany's automotive engineering clusters specify AR headsets for technician training with explicit audit trail requirements for gaze-data retention under EU AI Act compliance frameworks.
- Educational Institutions:District-level technology coordinators prioritize durability specifications and centralized fleet management over performance metrics.
- Healthcare Providers:United States hospital networks scaling immersive therapy programs for PTSD and chronic pain management require FDA-cleared devices with clinical evidence packages.
By unit volume, Individual Consumers lead. By contract value per seat, Healthcare Providers are expanding most quickly.
Technology:
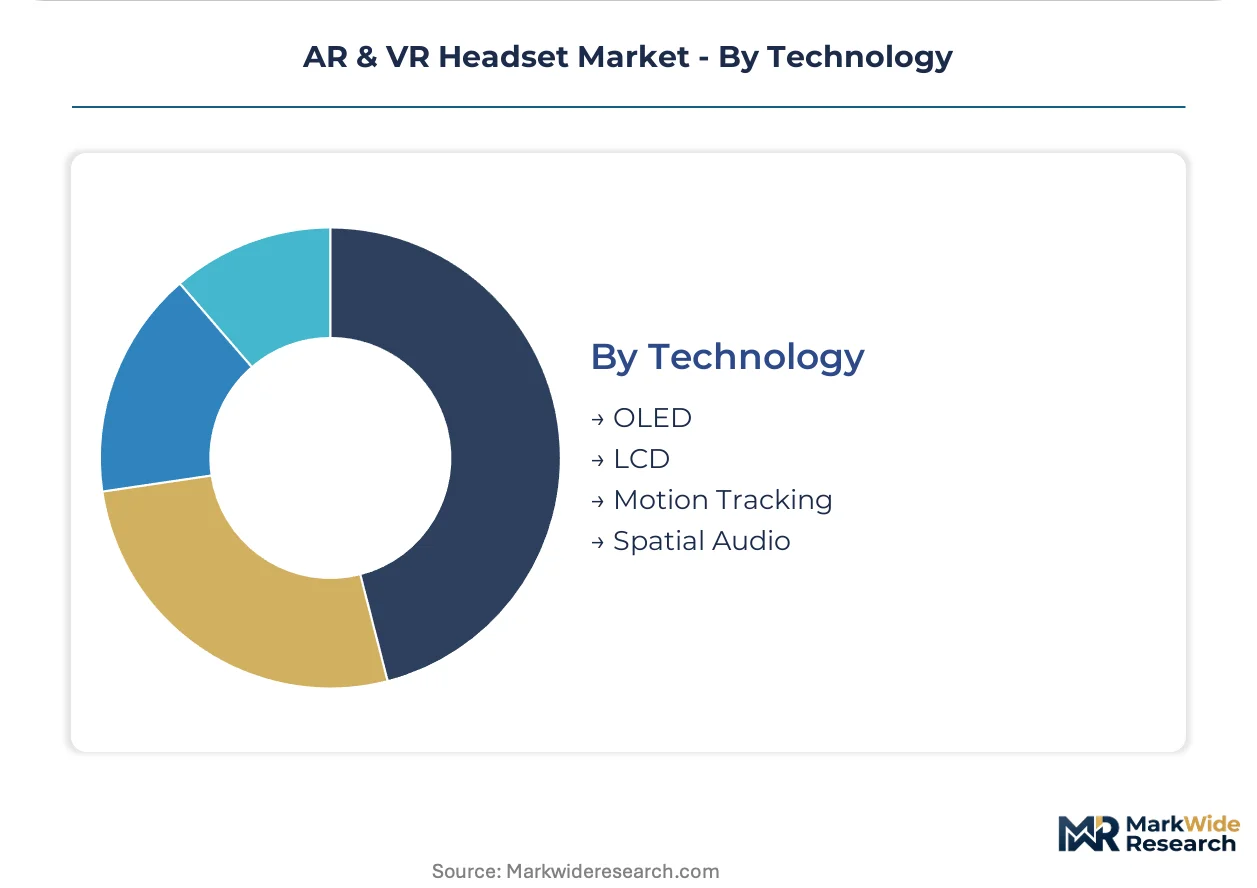
Display technology stratifies across price tiers. Premium positioning demands OLED panels. Mass-market penetration relies on LCD cost structures.
- OLED:Self-emissive pixels deliver infinite contrast ratios and sub-millisecond response times. Korean and Taiwanese foundry capacity concentration exposes manufacturers to input cost volatility during semiconductor allocation cycles.
- LCD:Backlit liquid crystal configurations occupy mass-market price bands through mature supply chains and scale economies in Chinese panel assembly.
- Motion Tracking:Six-degree-of-freedom sensor fusion enables room-scale positional tracking through integrated accelerometers, gyroscopes, and computer vision.
- Spatial Audio:Head-related transfer function processing creates three-dimensional soundscapes for immersion depth and communication clarity in collaborative virtual environments.
By revenue contribution, OLED leads. By manufacturing scale, LCD maintains the widest deployment footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme subsidies for electronics assembly are attracting contract manufacturers to establish headset production facilities serving Middle Eastern and African distribution channels. This policy incentive is reshaping regional supply configurations as manufacturers diversify beyond traditional Asian manufacturing bases.
United States
FDA clearance pathways for VR-based pain management and PTSD intervention are expanding reimbursable use cases within hospital networks. FCC radio equipment authorization shapes wireless connectivity standards for cross-border market access. Healthcare providers in California and Texas are scaling immersive therapy programs for chronic pain management.
Germany
Automotive engineering clusters around Stuttgart and Munich deploy AR headsets for assembly line validation and technician training. EU AI Act conformity requirements for biometric inference capabilities force firmware architecture redesigns. Bavarian industrial users demand explicit audit trails for gaze-data retention as procurement qualification criteria.
China
Domestic foundry capacity for OLED and LCD panel assembly supports mass-market price band penetration. MIIT standards and GB certification frameworks govern wireless connectivity and device safety. Yangtze River Delta manufacturing zones concentrate optical component fabrication for export-oriented headset assembly.
Saudi Arabia
MOHAP regulatory harmonization with FDA standards accelerates VR therapy imports for rehabilitation centers. Healthcare privatization initiatives in Riyadh and Jeddah medical zones create demand for clinical-grade devices. The Eastern Province is emerging as a distribution hub for Middle Eastern and North African markets.
Japan
METI industrial policy supports enterprise training deployment in automotive supplier technical centers. JIS standards and PMDA consultation frameworks influence therapeutic device classification. Kansai region manufacturers integrate AR headsets into precision assembly workflows for electronics and machinery production.
AR & VR Headset Market Competitive Landscape
Listed leaders compete with private specialists across ecosystem control and hardware integration dimensions. The vendor base stratifies into three tiers: platform-scale ecosystems, component-integrated device makers, and specialized optical engineering houses. Two dominant competitive moves are reshaping positioning: technology licensing from automotive HUD suppliers for waveguide miniaturization, and strategic partnerships between headset manufacturers and cloud rendering providers for 5G edge-compute offloading.
Within the platform-scale tier, Meta and Apple occupy positions that exemplify divergent ecosystem strategies—one leveraging content library breadth and social feature integration, the other commanding premium positioning through custom silicon and spatial computing interfaces. Sony Group Corporation anchors the tethered configuration segment through console integration. These three entities represent the structural poles around which competitive dynamics organize: standalone wireless convenience, premium spatial computing, and console-tethered fidelity.
| Leading Market Players |
|---|
| Meta |
| Sony Group Corporation |
| Apple Inc. |
| ByteDance |
| DPVR |
| HTC Corporation |
| Microsoft Corporation |
| Picotech |
| Xreal |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month CE marking timelines under EU MDR compress procurement planning horizons for clinical-grade headsets while Korean and Taiwanese OLED foundry allocation cycles amplify pricing power for premium tier manufacturers serving enterprise healthcare contracts.
Pricing Analysis
Certification level creates the primary spread across headset price bands. FDA-cleared therapeutic devices command subscription-based annual per-seat licensing with service attach rates, while consumer standalone units operate on transactional hardware margins with content marketplace revenue. Cost compression in mass-market LCD configurations intensifies as Chinese panel assembly scales, though enterprise buyers in German automotive clusters show low price sensitivity when explicit audit trails for gaze-data retention accompany procurement.
Supply Chain Analysis
Taiwan Strait transit exposure concentrates waveguide and pancake lens fabrication capacity for optical miniaturization. Manufacturing draws from Korean OLED foundries, Chinese LCD assembly zones, and German precision engineering clusters for automotive HUD component licensing. Single-source vulnerability in silicon-carbide substrate processing elevates supply risk for AR eyewear form factors. Distribution runs through contract manufacturers establishing India PLI-subsidized facilities for Middle Eastern and African channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR & VR headset market is exiting a semiconductor allocation trough as OLED supply normalization and 5G edge-cloud rendering capex cycles inflect demand upward.
For Market Incumbents: Consolidate optical engineering talent pools in Silicon Valley and Taipei through acquisition of specialized waveguide design teams rather than organic hiring at premium compensation. Deepen backward integration into pancake lens fabrication to offset Korean foundry pricing volatility. Lock multi-year service contracts with German automotive engineering clusters around Stuttgart and Munich before EU AI Act compliance documentation requirements harden procurement qualification barriers.
For New Entrants and Emerging Players: Differentiate on clinical-grade therapy specialization targeting Saudi healthcare privatization in Riyadh and Jeddah medical zones where MOHAP-FDA regulatory harmonization accelerates import pathways. Pursue white-space in lightweight 5G-enabled eyewear for enterprise inspection workflows where smartphone AR substitution limits tethered VR penetration. Lead with per-seat annual subscription models to compress incumbent cash conversion cycles and justify expanded pilot budgets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-rendering-dependent headset architectures as compute offloading reduces local silicon requirements. Target acquisition profiles center on optical engineering houses with silicon-carbide waveguide IP and automotive HUD licensing relationships. The signal to watch is German industrial user adoption of explicit gaze-data audit trail requirements as procurement qualification criteria, indicating enterprise willingness to pay for compliance-integrated solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Component Acquisition | Waveguide design teams in Silicon Valley and Taipei compress 36-month development cycles to 14-month iterations. |
| CE Marking Pathway Investment | EU MDR conformity assessment windows determine European healthcare market entry timing against FDA 510(k) routes. |
| 5G Edge-Cloud Partnership | Millimeter-wave connectivity enables lightweight eyewear form factors that offload compute from local silicon. |
| India PLI Manufacturing Scale-Up | Electronics assembly subsidies attract contract manufacturers serving Middle Eastern and African distribution channels. |
| Clinical Reimbursement Strategy | FDA clearance pathways for PTSD and pain management expand reimbursable use cases within United States hospital networks. |
Research Methodology
Desk research of SEC filings from headset manufacturers, ETSI spectrum harmonization documentation, and FDA 510(k) clearance databases preceded structured interviews with optical engineering directors, hospital procurement managers, German automotive training coordinators, and cloud rendering platform executives. Primary fieldwork combined with secondary validation across customs trade data, EU MDR conformity assessment timelines, and PLI scheme beneficiary disclosures. Bottom-up unit shipment modeling and top-down value chain triangulation anchored segmentation outputs.
Variance decomposition across product type, application, and technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from installed base growth rates, replacement cycle compression, and average selling price trajectories by certification tier. Industry-specific inputs incorporated OLED foundry allocation schedules, EU AI Act implementation phases, and 5G millimeter-wave deployment timelines in target enterprise clusters.
Material uncertainties — semiconductor cycle volatility, EU AI Act enforcement intensity, and FDA software-as-medical-device guidance evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization progress and enterprise subscription model adoption curves. Practitioners should keep alternative scenarios live as biometric data compliance complexity and optical engineering talent scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market