
 Global Volte Market | 2026-2036
Global Volte Market Size, Share, and Industry Trends Forecast 2026-2036
Global Volte Market Outlook
Telecom engineering talent scarcity in IP Multimedia Subsystem integration is reorganizing how carriers build voice cores. Ericsson leverages its end-to-end portfolio to anchor large-scale VoLTE transformations across multiple continents. Nokia Corporation competes through cloud-native IMS specialization, while Huawei Technologies Co. Ltd. sustains cost-engineered deployment momentum in emerging markets despite trade restrictions.
Voice over LTE (VoLTE) transmits voice calls as packetized data over 4G LTE radio networks using IMS architecture, replacing circuit-switched legacy infrastructure with spectral efficiency gains of roughly three times per hertz. Its primary purpose is enabling high-definition voice services while freeing spectrum for data traffic. The technology segment shows Voice over LTE maintaining dominant installed base share while 5G NR voice exhibits the steepest growth trajectory. Services within the component segment capture disproportionate margin pools due to complex IMS integration and ongoing network optimization requirements.
The Federal Communications Commission shapes US carrier VoLTE mandates through 3G sunset enforcement and emergency calling reliability standards. Europe's EMA and national regulators enforce CE-marked device interoperability under the Radio Equipment Directive, while India's TRAI accelerates refarming timelines that push MNOs toward all-IP voice. Stakeholders must monitor spectrum refarming deadlines and 5G SA voice interworking complexity as determinants of capital allocation priority.
Market Dynamics
Carrier migration from circuit-switched voice to all-IP architectures is compressing equipment refresh cycles and forcing vendor consolidation around cloud-native IMS platforms.
Growth Catalysts
- Spectrum Refarming Mandates:India's TRAI accelerates 2G/3G sunset timelines, compelling Bharti Airtel and Reliance Jio to fast-track VoLTE coverage expansion into rural districts.
- 5G SA Voice Interworking:The 3GPP Release 16 framework enables seamless handover between 4G VoLTE and 5G NR voice, reducing subscriber friction during network evolution phases.
- Emerging Market Subscriber Density:Indonesia and Nigeria exhibit concentrated mobile-first populations where VoLTE deployment unlocks spectral efficiency for data-heavy usage patterns.
Market Restraints
- IMS Integration Complexity:Multi-vendor interoperability testing extends deployment timelines by 8-14 months for carriers running hybrid Ericsson-Nokia core environments.
- Silicon Supply Concentration:Baseband processor fabrication concentrates in Taiwan and South Korea, exposing equipment vendors to geopolitical disruption risks.
- Legacy Device Interoperability:CE-marked device certification under Europe's Radio Equipment Directive creates friction for non-European handset manufacturers seeking market entry.
Strategic Opportunities
- Voice over New Radio (VoNR):5G standalone architectures in South Korea and Japan create first-mover advantage for vendors with mature cloud-native IMS stacks.
- Fixed Wireless Access Convergence:VoLTE voice services bundled with FWA broadband packages target underserved suburban households in the United States and Germany.
- Emergency Services Modernization:FCC mandates for location-accurate E911 over IP networks drive replacement demand for outdated selective router infrastructure.
Industry Challenges
- IMS Engineering Talent Scarcity:Specialized expertise in Session Border Controller configuration and Diameter/SIP protocol interworking commands 40% wage premiums above general telecom engineering roles.
- Multi-Generational Voice Interworking:Carriers must maintain simultaneous support for CSFB, VoLTE, and VoNR during transition windows, multiplying operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Volte Market |
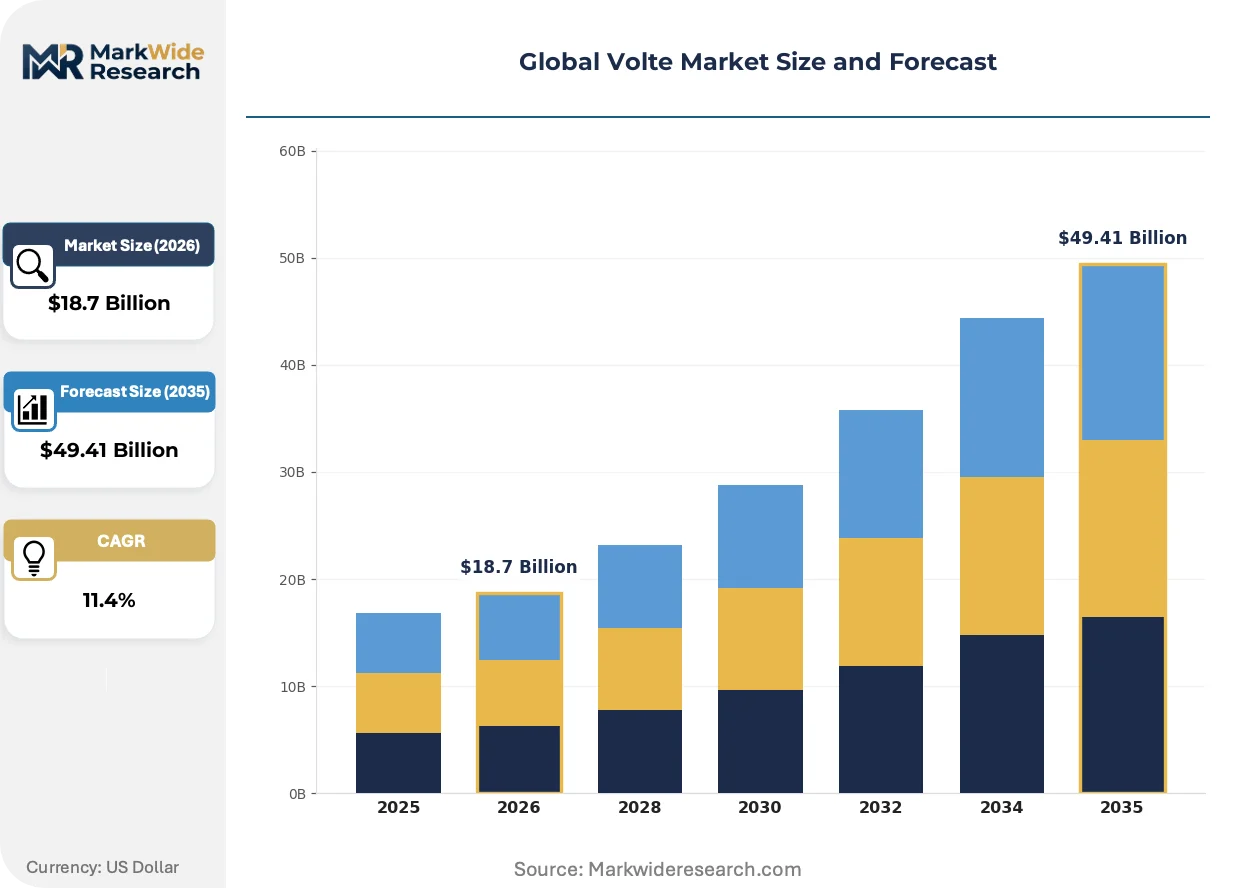
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Private Network, Public Cloud, Hybrid Cloud, On-Premises End User: Telecom Operators, Enterprises, Government, MNOs Technology: Voice over LTE, 5G NR, Circuit Switched Fallback, IMS Component: Hardware, Software, Services, Others |
| Companies Covered | Ericsson, Nokia Corporation, Huawei Technologies Co. Ltd., AT&T Inc., Verizon Communications Inc., SK Telecom Co. Ltd., Bharti Airtel Limited, KT Corporation, LG Uplus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Volte Market Strategic Shifts
Virtualized network functions are displacing proprietary hardware appliances, while AI-driven traffic management and open RAN architectures rewrite procurement criteria for voice core infrastructure.
Cloud-native IMS cores are miniaturizing deployment footprints through containerized microservices architectures. Tier-2 carriers in Poland and Mexico adopt these compressed implementations to avoid capital-intensive centralized data center builds. The technology is miniaturizing total cost of ownership curves, enabling sub-scale operators to launch VoLTE services previously restricted to national incumbents.
Europe's F-Gas Regulation and accompanying ETSI standards now mandate energy-efficiency disclosures for network equipment procurement. Carrier sustainability committees in Germany and France have elevated power consumption metrics to top-three vendor selection criteria. Asian equipment suppliers are responding with liquid-cooled baseband units and sleep-mode optimization for low-traffic hours.
Enterprise buyers now unbundle voice core maintenance from initial deployment contracts, shifting toward multi-year managed service agreements with outcome-based SLAs. This restructuring concentrates vendor accountability in India and Brazil where carrier IT departments lack scale for self-managed IMS operations. The model compresses upfront capital outlays while elongating vendor revenue recognition timelines.
Global Volte Market Segmentation
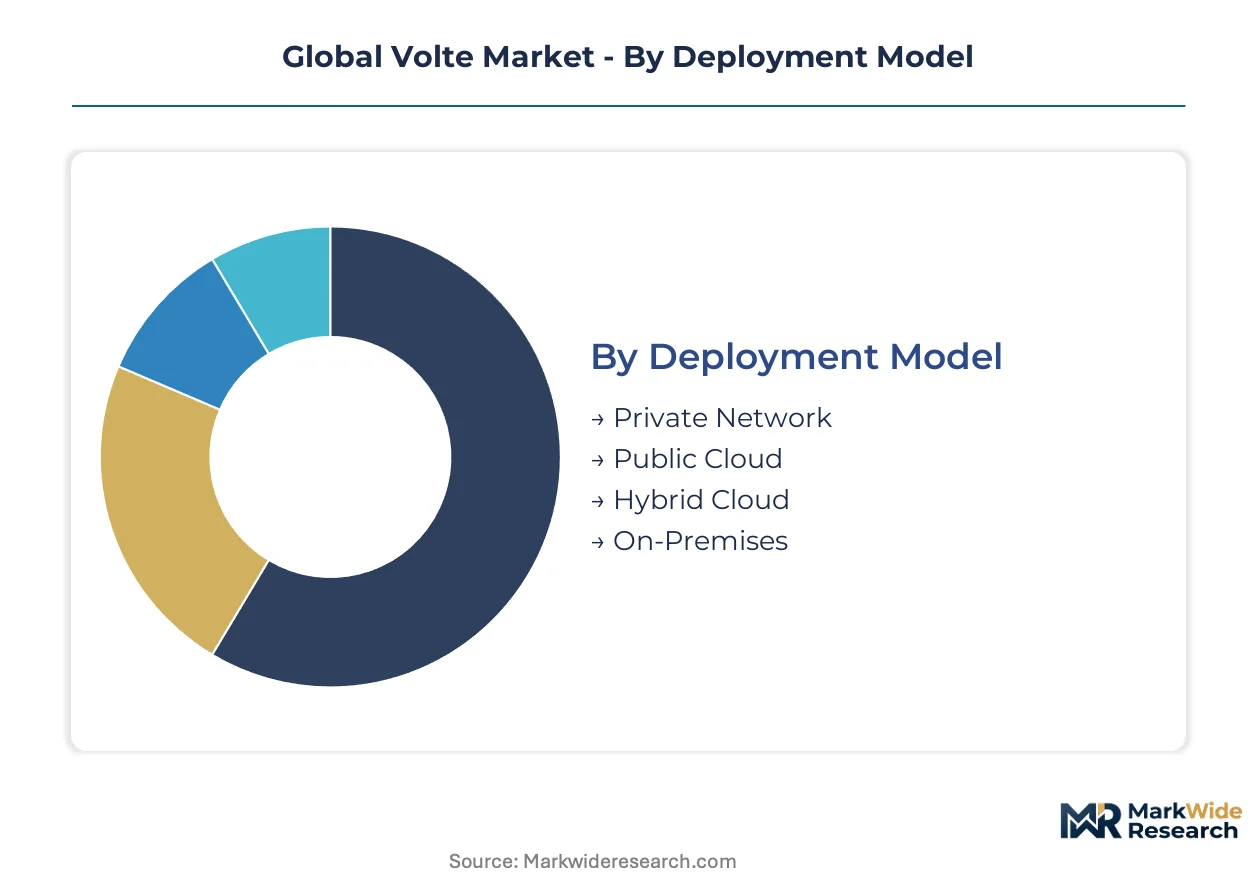
VoLTE market segmentation reveals how infrastructure investment priorities split between legacy migration paths and next-generation voice architectures. Deployment models and technology choices determine capital intensity, while end-user concentration shapes vendor go-to-market strategies.
Deployment Model:
Public cloud deployments face the strongest substitution pressure from hybrid alternatives that balance operational flexibility with data sovereignty requirements.
- Private Network:Dedicated infrastructure serving defense, utilities, and mining operations with strict latency and isolation mandates. Demand concentrates in Saudi Arabia and Australia where critical infrastructure operators pursue sovereign voice cores.
- Public Cloud:Multi-tenant IMS hosting delivered by hyperscalers, attractive to Tier-2 and Tier-3 carriers lacking data center scale. Cost efficiency drives adoption in Mexico and Poland among sub-national operators.
- Hybrid Cloud:Control-plane functions remain on-premises while media processing scales elastically into cloud. German and French carriers favor this model under GDPR and national security frameworks.
- On-Premises:Traditional appliance-based deployment in centralized carrier facilities. Legacy footprints persist in Brazil and Nigeria where connectivity constraints limit cloud viability.
On-Premises anchors the volume base while Hybrid Cloud gains share at the steepest rate.
End User:
Cost tier differentiation separates capital-intensive national infrastructure from lean enterprise implementations.
- Telecom Operators:Incumbent and competitive carriers building subscriber-scale voice cores with five-nines reliability requirements. Bharti Airtel and Reliance Jio in India drive the largest current deployment wave.
- MNOs:Mobile network operators distinct from fixed-line incumbents, often cloud-native in architecture. Indonesian and Nigerian MNOs prioritize spectral efficiency gains from rapid VoLTE overlay.
- Enterprises:Large corporations deploying private voice networks for campus and industrial settings. German automotive manufacturers and Japanese electronics firms lead this segment.
- Government:Public safety and administrative networks with encrypted communications mandates. UAE and Saudi Arabia invest heavily in sovereign secure voice infrastructure.
Telecom Operators command the majority of current spending while Enterprises expand most quickly as private 5G networks proliferate.
Technology:
Application-driven selection separates consumer voice services from specialized industrial and emergency use cases.
- Voice over LTE:Packetized voice over 4G LTE radio with IMS core anchoring, delivering HD voice and spectral efficiency. Deployment concentrates in India and Indonesia where 2G/3G sunset deadlines force migration urgency.
- 5G NR:Native voice over 5G standalone architecture eliminating LTE dependency. South Korea and Japan lead commercial deployment with mature cloud-native IMS stacks.
- Circuit Switched Fallback:Legacy interworking mechanism routing voice to 2G/3G when LTE coverage fails. Declining relevance as VoLTE coverage matures in urban corridors.
- IMS:IP Multimedia Subsystem core architecture enabling session control across access technologies. Foundation layer for converged voice, video, and messaging services.
Voice over LTE dominates installed capacity while 5G NR climbs the fastest as standalone networks achieve critical mass.
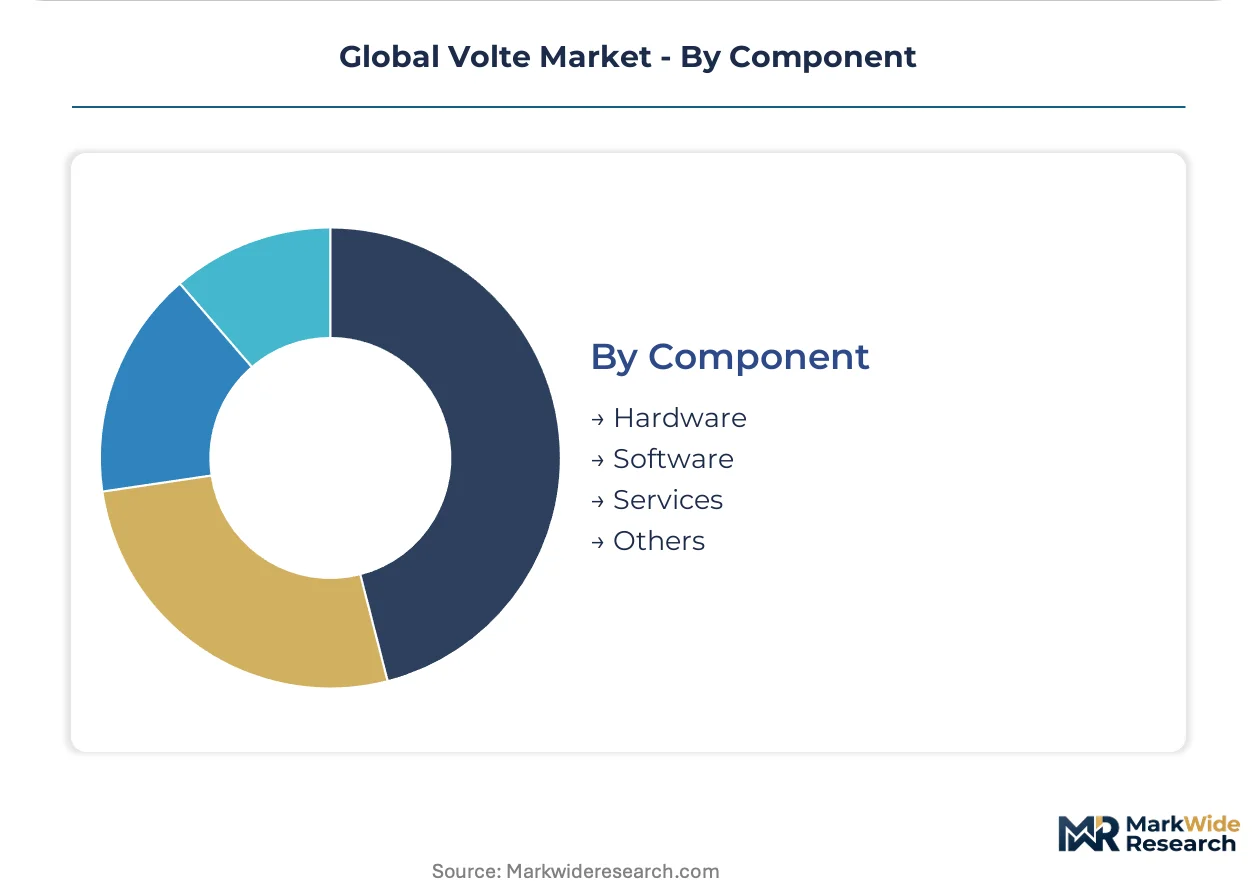
Component:
Margin concentration favors software and services over hardware as virtualization compresses equipment refresh cycles.
- Services:System integration, IMS deployment, and ongoing network optimization commanding premium pricing. Complex multi-vendor interoperability testing in hybrid Ericsson-Nokia environments extends engagement duration.
- Software:Virtualized network functions and cloud-native IMS platforms displacing proprietary appliances. Containerized microservices reduce deployment footprints for Tier-2 carriers.
- Hardware:Physical servers, switches, and radio equipment for on-premises and private network builds. Taiwan and South Korea fabrication concentration exposes supply risk.
- Others:Ancillary elements including licensing, training, and support contracts. Typically bundled within broader service agreements.
Hardware retains the largest revenue base while Services captures expanding margin pools through outcome-based managed service structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes VoLTE infrastructure as spectrum-refarming urgency, while Germany treats it as energy-efficiency compliance, and South Korea deploys it as 5G standalone voice advancement. These divergent consumption patterns fragment vendor go-to-market strategies across geographies.
United States
Carriers prioritize E911 location-accuracy mandates and 3G sunset enforcement over raw capacity expansion. The FCC's emergency calling reliability standards drive selective router replacement in suburban corridors. Verizon and AT&T concentrate VoLTE overlay deployment in Texas and California metro clusters.
India
Bharti Airtel and Reliance Jio compress nationwide IMS deployment timelines under TRAI's accelerated 2G/3G refarming deadlines. The regulator's spectrum reallocation mandates force voice core investment into rural districts previously served by circuit-switched infrastructure. Deployment concentrates in Maharashtra and Karnataka telecom circles.
Germany
Deutsche Telekom and Vodafone Germany weight energy-efficiency metrics as top-three procurement criteria under the EU F-Gas Regulation and accompanying ETSI standards. Sustainability committees mandate liquid-cooled baseband disclosures. Industrial VoLTE adoption clusters in Bavarian automotive manufacturing corridors.
South Korea
SK Telecom and KT Corporation advance VoNR commercialization over 5G standalone architectures ahead of global peers. The Ministry of Science and ICT's 5G spectrum allocation frameworks prioritize native voice interworking. Seoul Capital Area hosts the densest cloud-native IMS stack deployments.
Indonesia
Telkomsel and Indosat Ooredoo Hutchison exploit VoLTE spectral efficiency to serve mobile-first subscriber densities in Jakarta and Surabaya. The Ministry of Communication and Informatics accelerates 3G shutdown timelines across Java island. Infrastructure investment concentrates in Greater Jakarta's data center corridors.
Global Volte Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in VoLTE infrastructure supply. Ericsson and Nokia Corporation anchor the consolidated upper tier through end-to-end portfolio breadth, while Huawei Technologies Co. Ltd. sustains cost-engineered deployment momentum despite trade restrictions. Specialist vendors concentrate on cloud-native IMS microservices and Session Border Controller optimization. Competitive positioning hardens around multi-year managed service agreements and outcome-based SLAs.
Among Nordic integrated vendors, Ericsson and Nokia Corporation exemplify the full-stack archetype spanning radio access through core networks. Huawei Technologies Co. Ltd. represents the emerging-market cost-optimization archetype. SK Telecom Co. Ltd. and KT Corporation occupy positions as operator-technology hybrids that export domestic 5G voice expertise. These entities sit within a vendor base where geographic origin increasingly determines market access scope.
| Leading Market Players |
|---|
| Ericsson |
| Nokia Corporation |
| Huawei Technologies Co. Ltd. |
| AT&T Inc. |
| Verizon Communications Inc. |
| SK Telecom Co. Ltd. |
| Bharti Airtel Limited |
| KT Corporation |
| LG Uplus Corporation |
| Others |
Value Chain & Pricing Dynamics
CE marking under Europe's Radio Equipment Directive gates both vendor qualification and price differentiation simultaneously, forcing non-European equipment manufacturers into costly interoperability testing that stratifies pricing tiers by certification burden and geographic origin.
Pricing Analysis
Long-term managed service agreements with outcome-based SLAs dominate carrier procurement, displacing upfront capital purchases. Price differentiation hinges on IMS integration complexity and cloud-native architecture maturity, with Tier-2 carriers in Poland and Mexico exhibiting highest price sensitivity due to compressed deployment budgets. Cost compression in hardware tiers is intensifying because virtualized network functions displace proprietary appliances. National incumbents with five-nines reliability requirements prove least price-sensitive, prioritizing vendor accountability over unit economics.
Supply Chain Analysis
Extended lead times for baseband processors now stretch equipment delivery schedules, compressing carrier upgrade windows. Fabrication concentrates in Taiwan and South Korea, with assembly and systems integration anchored in China and Vietnam. The chain draws from silicon wafers, radio frequency components, and liquid-cooled thermal management systems. Single-source vulnerability in advanced node semiconductor production exposes vendors to geopolitical disruption. Distribution runs through carrier-direct procurement teams and systems integrators serving sub-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VoLTE infrastructure is approaching a platform-economics inflection where cloud-native IMS interoperability determines ecosystem lock-in, with 3GPP Release 16 handover frameworks between 4G VoLTE and 5G NR voice reshaping competitive moats.
For Market Incumbents: Compound cloud-native IMS stack maturity to defend against emerging specialist vendors offering containerized microservices. Deepen backward integration into Session Border Controller software development to capture margins fleeing hardware commoditization. Prioritize certification investment for CE-marked device interoperability under Europe's Radio Equipment Directive to maintain carrier-direct channel control. For New Entrants and Emerging Players: Lead with miniaturized deployment footprints targeting Tier-2 carriers in Mexico and Poland lacking data center scale for centralized IMS builds. Indonesia and Nigeria present the most penetrable geographies given mobile-first subscriber densities and accelerated 3G sunset timelines. Pursue outcome-based managed service agreements that elongate revenue recognition while compressing carrier upfront capital outlays. For Investors and Strategic Acquirers: TRAI's accelerated spectrum refarming deadlines in India reshape the acquisition landscape toward vendors with proven rural district deployment capability. The 5-10 year viability window favors cloud-native IMS specialists over hardware-centric legacy players. Monitor 5G standalone voice interworking complexity as the signal indicating which vendor stacks achieve carrier preference.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Platform Integration | Containerized microservices enable Tier-2 carrier market entry in Poland and Mexico. |
| Managed Service Agreement Restructuring | Outcome-based SLAs concentrate vendor accountability in India and Brazil. |
| Energy-Efficiency Certification Investment | Liquid-cooled baseband disclosures satisfy German and French sustainability procurement criteria. |
| 5G NR Voice Interworking Development | Release 16 compliance determines competitive positioning in South Korea and Japan. |
| Session Border Controller Specialization | Diameter/SIP protocol expertise commands wage premiums amid engineering scarcity. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with carrier network planning executives, IMS integration engineers, vendor product managers, and regulatory affairs specialists at national telecom regulators. Secondary validation drew from 3GPP release documentation, TRAI spectrum refarming orders, FCC E911 mandates, carrier capex disclosures, and equipment vendor SEC filings. Bottom-up deployment volume estimates triangulated against top-down market sizing derived from spectrum auction values and infrastructure investment announcements.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment model architecture, end-user carrier tier, voice technology generation, and component category mix. CAGRs were derived from carrier-reported subscriber migration timelines and vendor order backlog trajectories. Forecast inputs incorporated IMS engineering labor market tightness and silicon fabrication capacity allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained carrier migration urgency or unanticipated 3G sunset deadline extensions would require recalibration. Forecasts reflect documented assumptions regarding multi-vendor interoperability testing durations and cloud-native platform adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Repeaters Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Parabolic Antenna Market