
 Camu Camu Extract Market | 2026-2036
Camu Camu Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Camu Camu Extract Market Outlook
Asset-light contract manufacturing and third-party extraction leasing is reconfiguring competitive entry barriers for mid-scale botanical suppliers. NP Nutra leverages its South American sourcing infrastructure to secure consistent raw material flows. Naturalin Bio-Resources Co., Ltd. anchors its position through integrated cultivation-to-extract operations in China. NOW Foods competes via established retail channel relationships and certified organic product lines.
Camu camu extract is a concentrated preparation derived from the fruit of Myrciaria dubia, standardized typically for vitamin C content exceeding 12-15% by weight and delivered as spray-dried powder or hydroalcoholic liquid. The extract serves primarily as a natural antioxidant and immune-support ingredient across nutraceutical and functional food matrices. Powder formulations dominate volume throughput due to superior stability in bulk ingredient handling and blending operations. Dietary supplements capture the largest value pool within applications, while functional foods represent the fastest-expanding consumption category as beverage makers reformulate with clean-label botanicals.
Peru's national biodiversity authority and Brazil's environmental licensing framework govern wild harvest volumes and export documentation for native camu camu populations. The USDA National Organic Program and EFSA novel food consultation pathways shape import eligibility and label claims in North American and European destination markets. Stakeholders must monitor evolving extraction solvent regulations and organic certification reciprocity agreements to preserve cross-border market access.
Market Dynamics
Wild harvest quotas enforced by Peru's national biodiversity authority are compressing raw material availability, forcing extractors toward cultivation partnerships and solvent innovation to maintain vitamin C standardization at viable cost structures.
Growth Catalysts
- Immune-positioned nutraceutical demand:Formulators in dietary supplements are expanding botanical procurement for vitamin C fortification, pulling extract volumes through Brazil's Amazon processing corridor.
- EFSA novel food consultation pathways:Clarified import eligibility for spray-dried camu camu powder is enabling European functional food market entry for compliant suppliers.
- Clean-label beverage reformulation:Functional drink manufacturers are replacing synthetic ascorbic acid with standardized natural extracts to meet consumer ingredient transparency expectations.
Market Restraints
- Wild population concentration risk:Native Myrciaria dubia stands cluster in Peru's Amazon basin and western Brazil, exposing supply chains to climate volatility and extraction licensing delays.
- Organic certification reciprocity gaps:Non-aligned standards between USDA National Organic Program and Brazil's certifying bodies create documentation friction for cross-border ingredient flows.
- Synthetic vitamin C substitution:Fermentation-derived ascorbic acid from Chinese manufacturers competes on cost for applications where natural provenance carries limited price premium.
Strategic Opportunities
- Underpenetrated functional food applications:Bakery and dairy matrices in North American markets remain open for heat-stable extract formulations with proven bioavailability retention.
- Cultivation-to-extract backward integration:Controlled orchard establishment in Colombia and Ecuador offers supply security independent of wild harvest quota fluctuations.
- Direct-to-manufacturer platform distribution:B2B ingredient marketplaces are disintermediating traditional broker networks for mid-scale botanical buyers seeking transparent provenance documentation.
Industry Challenges
- Phytochemical standardization expertise scarcity:Analytical chemists capable of validating 12-15% vitamin C content consistency across seasonal fruit batches command premium compensation in South American extraction hubs.
- Hydroalcoholic solvent regulatory divergence:Extraction facilities must maintain parallel compliance with EPA solvent residual limits for US-bound shipments and REACH annex restrictions for European destinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camu Camu Extract Market |
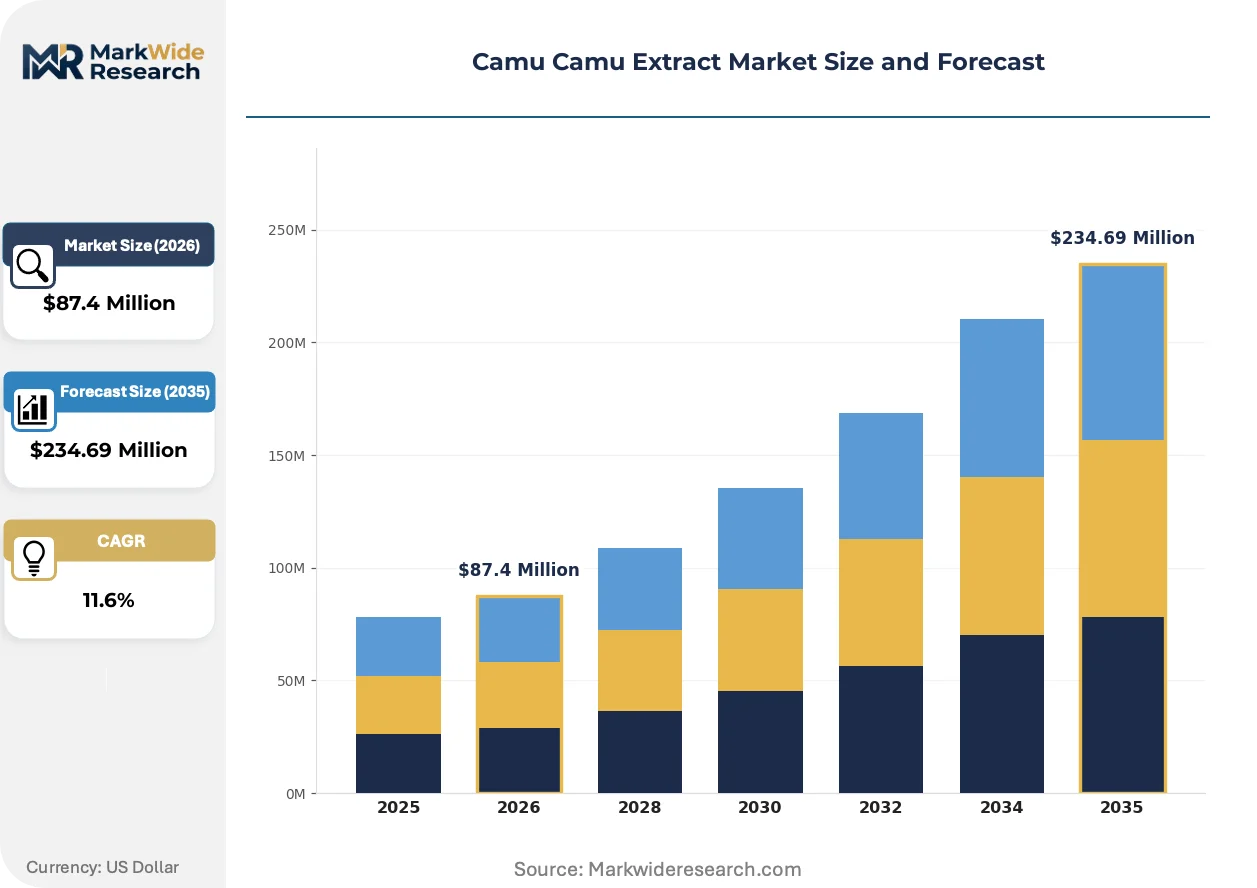
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Extracts End User: Retail Consumers, Health Professionals, Nutraceutical Companies, Food Manufacturers Application: Dietary Supplements, Functional Foods, Skincare Products, Beverages Distribution Channel: Online Retail, Supermarkets, Health Shops, Specialty Stores |
| Companies Covered | NP Nutra, Naturalin Bio-Resources Co., Ltd., Nexira, The Green Labs LLC, Ambe Phytoextracts Pvt. Ltd., Herbal Ingenuity Inc., NOW Foods, Van Drunen Farms, HP Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camu Camu Extract Market Strategic Shifts
Near-infrared spectroscopy deployment at receiving stations is transforming raw material quality verification, compressing batch release timelines while tightening phytochemical consistency across geographically dispersed supply origins.
Spectroscopic analysis instrumentation is digitizing quality control workflows at Peruvian and Brazilian collection points. Regional cooperatives and integrated processors are adopting handheld NIR devices for field-side vitamin C estimation, reducing laboratory dependency. This technology compression is enabling real-time pricing adjustments based on phytochemical potency rather than weight alone.
USDA National Organic Program enforcement against fraudulent botanical certification is intensifying documentation requirements for imported extracts. Third-party certifiers are implementing blockchain-traceable chain-of-custody systems to verify wild harvest origin claims. Dietary supplement manufacturers sourcing for premium positioning are absorbing compliance costs to preserve label integrity and retail channel access.
Buyers are consolidating supplier relationships around vertically integrated processors with captive cultivation or long-term cooperative contracts. Small-scale extractors lacking upstream control are experiencing volume displacement as procurement departments prioritize supply security over unit cost optimization. This concentration pattern is most visible among North American nutraceutical contract manufacturers reformulating immunity portfolios.
Camu Camu Extract Market Segmentation
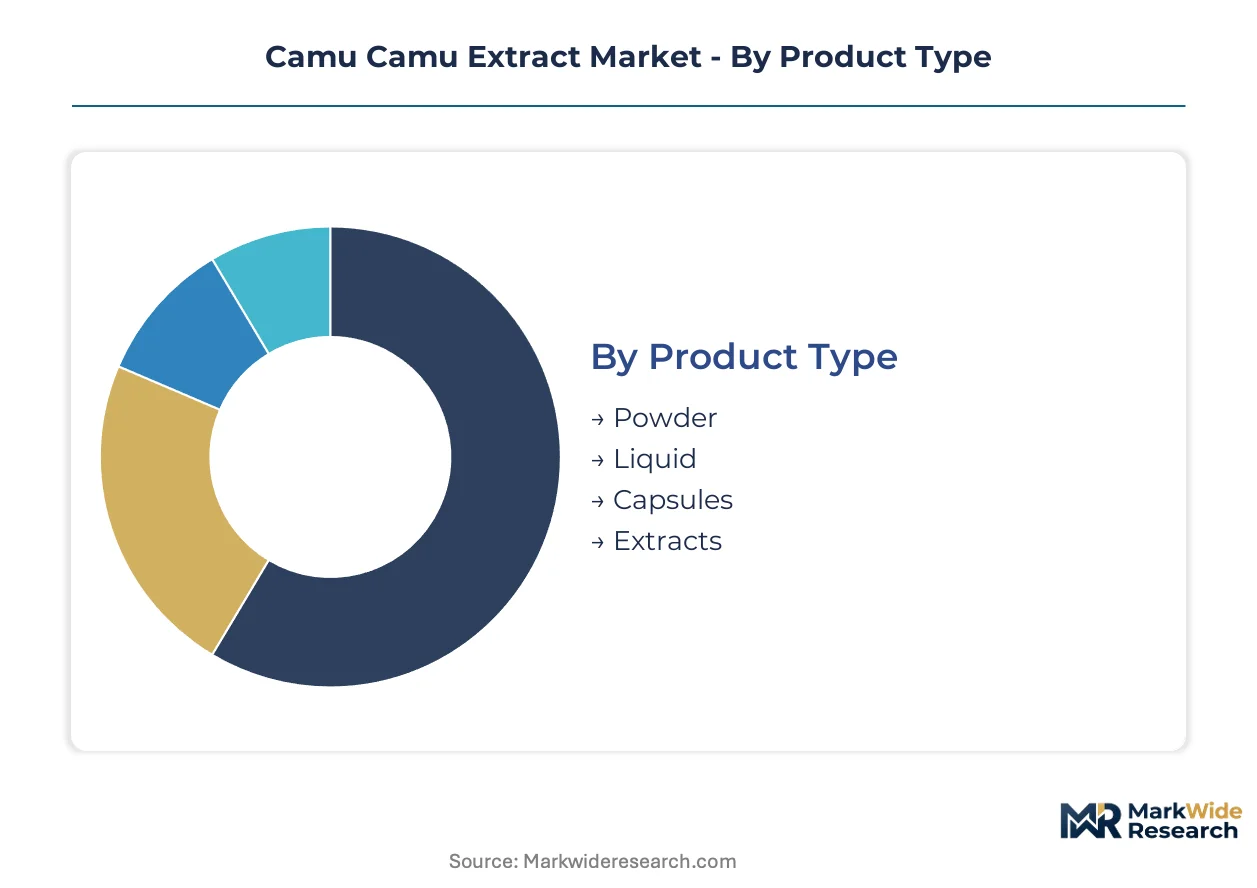
Segmentation in the camu camu extract market reveals how procurement patterns diverge across customer sophistication levels and application requirements. Technical buyers prioritize vitamin C standardization and solvent documentation, while retail channels emphasize organic certification visibility and packaging formats suited to shelf merchandising.
Product Type:
After-sales service intensity varies sharply across product formats, with liquid extracts demanding technical support for solvent handling and stability guidance while powder formats require minimal post-sale intervention.
- Powder:Spray-dried formulations standardized to 12-15% vitamin C by weight dominate bulk ingredient procurement for blending operations. Nutraceutical contract manufacturers in Brazil's Amazon processing corridor specify powder for immunity-positioned capsules and tablets, drawn by superior stability in climate-controlled warehousing and mechanized handling compatibility.
- Liquid:Hydroalcoholic extracts deliver faster bioavailability absorption for functional beverage applications. Beverage formulators in Peru and Colombia specify liquid formats for clean-label reformulations, though EPA and REACH solvent residual compliance adds documentation burden for cross-border shipments.
- Capsules:Pre-encapsulated finished products serve direct-to-consumer supplement brands seeking manufacturing outsourcing.
- Extracts:Concentrated preparations for further processing by integrated nutraceutical facilities with in-house formulation capabilities.
By volume, Powder leads. By growth pace, Liquid is ahead.
End User:
Cost tier stratification separates commodity-volume buyers from premium-positioned purchasers, with nutraceutical companies absorbing compliance premiums for certified organic provenance while retail consumers remain price-sensitive to synthetic vitamin C alternatives.
- Nutraceutical Companies:Mid-scale and large botanical buyers procure standardized extracts for immunity portfolio expansion, requiring chain-of-custody documentation and third-party potency verification. These buyers consolidate supplier relationships around vertically integrated processors with captive cultivation or long-term cooperative contracts in Peru's regulated harvest zones.
- Food Manufacturers:Functional food reformulators integrate camu camu for clean-label antioxidant positioning in bakery and dairy matrices. North American processors specifically seek heat-stable formulations with proven bioavailability retention for mainstream retail distribution.
- Retail Consumers:Individual purchasers through direct channels prioritize single-ingredient transparency and USDA Organic or equivalent certification marks.
- Health Professionals:Practitioner-channel distribution requires clinical dosing guidance and batch-specific certificate of analysis availability.
By procurement volume, Nutraceutical Companies dominate. By expansion trajectory, Food Manufacturers are climbing the fastest.
Application:
Application selection maps directly to regulatory pathway complexity, with dietary supplements navigating FDA notification requirements while functional foods face novel food consultations through EFSA for European market entry.
- Dietary Supplements:Capsule, tablet, and softgel formulations capture established demand from immunity-conscious consumers. Brazilian and Peruvian extractors prioritize supplement-grade production for North American contract manufacturers reformulating botanical portfolios away from synthetic ascorbic acid.
- Functional Foods:Beverage, bakery, and dairy integration represents the steepest expansion trajectory as clean-label reformulation accelerates. Heat stability and flavor masking requirements drive extract specification toward low-temperature processed powders with minimal residual solvents.
- Beverages:Ready-to-drink and concentrate applications favor liquid extract formats for dissolution efficiency.
- Skincare Products:Cosmetic-grade extracts with antioxidant positioning for topical vitamin C stability in emulsion systems.
By current revenue contribution, Dietary Supplements leads. By market momentum, Functional Foods is gaining share fastest.
Distribution Channel:
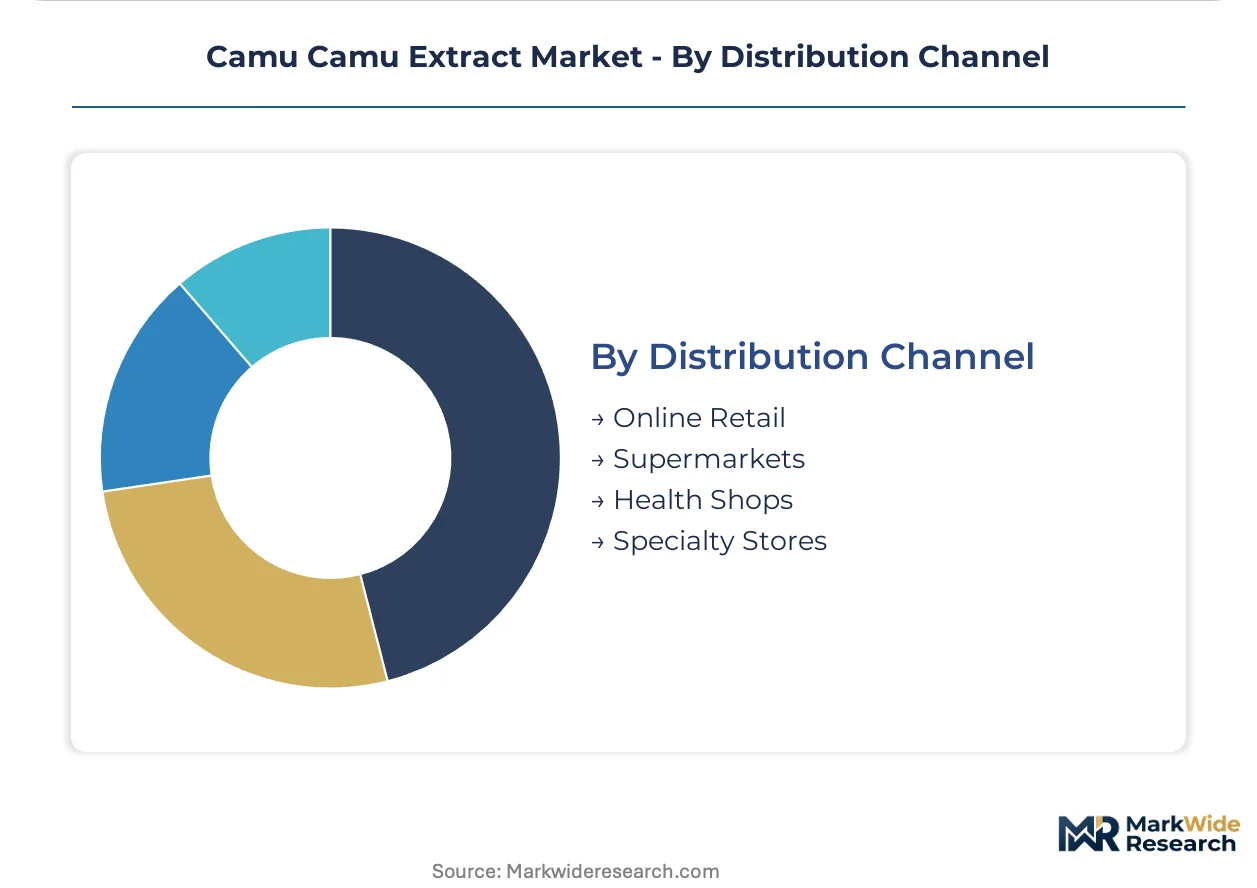
Channel selection reflects buyer sophistication segmentation, with specialty stores and health shops serving ingredient-educated consumers while supermarkets and online retail capture convenience-oriented and price-comparison purchasers.
- Online Retail:Direct-to-consumer platforms and B2B ingredient marketplaces are disintermediating traditional broker networks. Mid-scale botanical buyers utilize transparent provenance documentation and real-time pricing based on phytochemical potency rather than weight alone.
- Health Shops:Brick-and-mortar specialty retailers serve premium-positioned consumers seeking staff consultation and certified organic product verification.
- Supermarkets:Mass retail placement requires economies of scale and established brand recognition for shelf space allocation.
- Specialty Stores:Natural product and co-op channels emphasize local sourcing narratives and cooperative supply chain stories.
By transaction volume, Online Retail leads. By customer lifetime value expansion, Health Shops is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's biodiversity authority enforces wild harvest quotas that constrain raw material flows, while Brazil's environmental licensing framework governs extraction volumes in the Amazon basin. These regulatory instruments are reshaping procurement geography as extractors seek cultivation partnerships outside quota-restricted zones.
Peru
Immunity-positioned nutraceutical demand from North American contract manufacturers pulls extract volumes through Lima-based processing facilities. The national biodiversity authority regulates wild harvest quotas to prevent overextraction of native Myrciaria dubia stands. Iquitos and Pucallpa anchor the upstream collection corridor where regional cooperatives control berry sourcing and field-side quality verification.
Brazil
Clean-label beverage reformulation drives procurement of standardized powders for antioxidant fortification. ANVISA oversees export documentation and environmental licensing for Amazon-sourced botanicals. Manaus and Belém concentrate extraction capacity within the Amazon processing corridor, with regional cooperatives managing upstream supply security.
United States
Dietary supplement manufacturers reformulate immunity portfolios away from synthetic ascorbic acid toward certified organic extracts. The USDA National Organic Program enforces chain-of-custody documentation for imported botanicals. California and Utah host contract manufacturing clusters where procurement departments prioritize vertically integrated suppliers with transparent provenance systems.
China
Fermentation-derived synthetic vitamin C competes on cost for applications where natural provenance carries limited price premium. The National Medical Products Administration governs import eligibility for botanical extracts used in domestic formulation. Zhengzhou and Xi'an concentrate extraction equipment manufacturing and third-party analytical services for standardization verification.
Germany
Functional food manufacturers seek heat-stable extract formulations for bakery and dairy matrix integration. EFSA novel food consultation pathways determine import eligibility for spray-dried camu camu powder in European applications. Hamburg and Frankfurt serve as entry points for South American botanical shipments requiring REACH-compliant solvent documentation.
Camu Camu Extract Market Competitive Environment
Channel-controlling players compete with product-specialist players across differentiated procurement tiers. The vendor base organizes around three strategic archetypes: South American integrated processors with captive cultivation, Chinese extraction-scale operators with equipment advantages, and North American brand-holders with retail channel relationships. Dominant competitive moves include backward integration into orchard establishment and B2B marketplace disintermediation of traditional broker networks.
Among South American integrated processors, NP Nutra exemplifies the upstream-control archetype through its regional sourcing infrastructure. Naturalin Bio-Resources Co., Ltd. occupies a position within the China-based extraction-scale tier. NOW Foods anchors the North American brand-holder segment with established retail distribution and certified organic positioning. These three company structures represent the primary competitive vectors shaping procurement consolidation patterns.
| Leading Market Players |
|---|
| NP Nutra |
| Naturalin Bio-Resources Co., Ltd. |
| Nexira |
| The Green Labs LLC |
| Ambe Phytoextracts Pvt. Ltd. |
| Herbal Ingenuity Inc. |
| NOW Foods |
| Van Drunen Farms |
| HP Ingredients |
| Others |
Value Chain & Pricing Dynamics
Peru's regulated wild harvest zones concentrate upstream berry sourcing in the hands of regional cooperatives, pushing margin pools downstream toward extraction facilities with solvent innovation capabilities and certified organic processing infrastructure. Synthetic ascorbic acid from Chinese fermentation facilities exerts persistent price ceiling pressure on natural extract premiums, compressing viable pricing bands for non-differentiated suppliers.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with USDA Organic and EFSA novel food compliance commanding substantial markups over conventional grades. Three-tier pricing structure separates wild-harvest premium extracts from cultivated standard grades and commodity spot powder. Pricing pressure stems from fermentation-derived synthetic vitamin C undercutting natural provenance claims in cost-sensitive applications. Nutraceutical contract manufacturers exhibit lowest price sensitivity due to immunity-portfolio positioning requirements, while beverage reformulators remain most cost-conscious.
Supply Chain Analysis
Wild Myrciaria dubia berries draw from Peru's Amazon basin and western Brazil's collection corridors, with cultivated alternatives emerging in Colombia and Ecuador. Hydroalcoholic solvents, spray-drying equipment, and phytochemical standardization expertise constitute critical input dependencies. Single-source vulnerability concentrates in Peru's biodiversity-regulated harvest quotas, exposing processors to licensing delays and climate-driven yield volatility. Distribution runs through B2B ingredient marketplaces disintermediating traditional broker networks, with vertically integrated processors capturing preferred procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemists capable of validating vitamin C standardization across seasonal batches command premium compensation, creating a persistent talent bottleneck that constrains quality throughput at extraction facilities. This capability scarcity rewards early movers who secure phytochemical expertise through apprenticeship pipelines or acquisition.
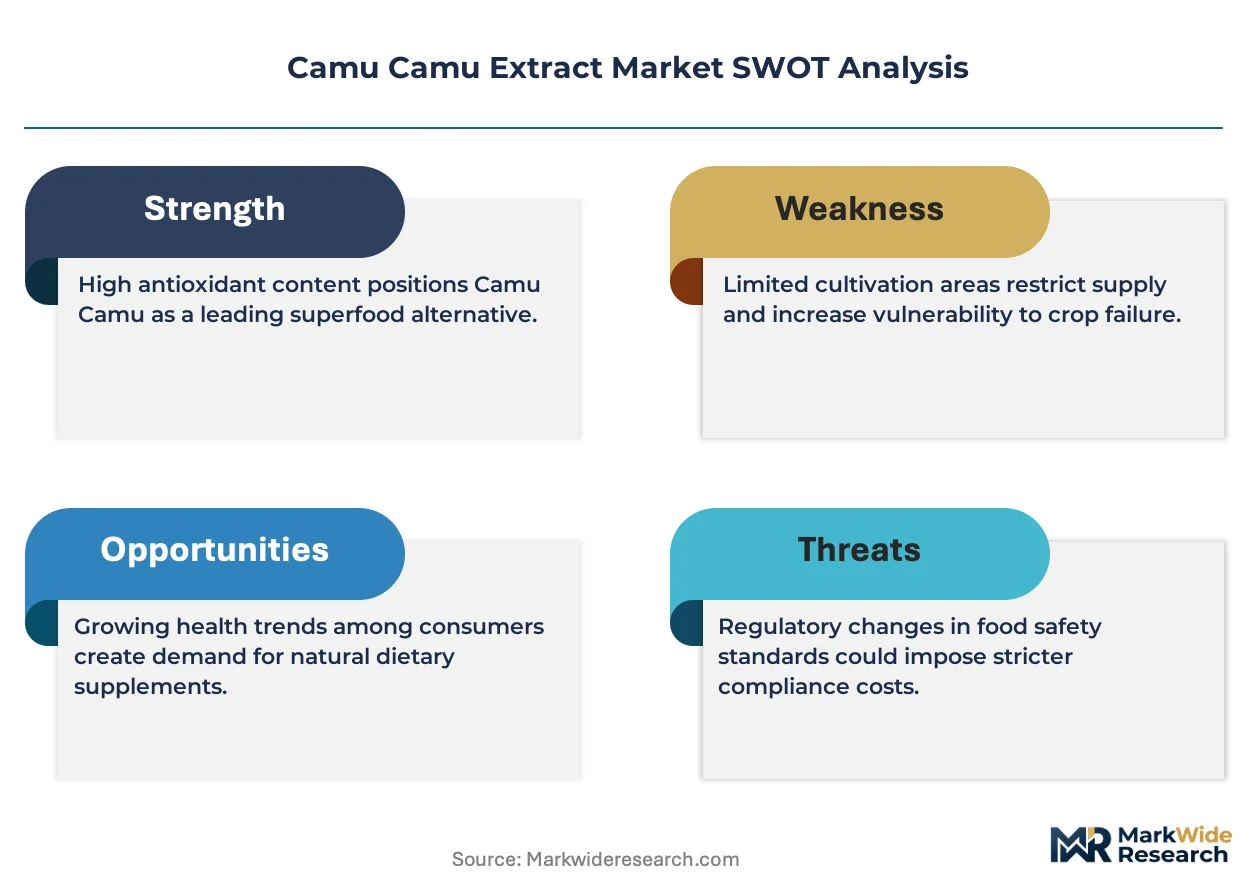
For Market Incumbents: Harden supply security through captive orchard establishment in Colombia and Ecuador, insulating production from Peru's wild harvest quota fluctuations. Invest in near-infrared spectroscopy deployment at receiving stations to compress batch release timelines and tighten phytochemical consistency. Defend against synthetic vitamin C substitution by emphasizing certified organic provenance and blockchain-traceable chain-of-custody documentation for premium supplement channels. For New Entrants and Emerging Players: Functional food applications in North American bakery and dairy matrices represent the most penetrable entry point, as heat-stable extract formulations with proven bioavailability retention remain under-supplied. Direct-to-manufacturer platform distribution offers disintermediation leverage against established broker networks, particularly for mid-scale botanical buyers seeking transparent provenance documentation. Lead with technical support capabilities for solvent handling guidance to differentiate from commodity powder suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed South American integrated processors holding long-term cooperative contracts in regulated harvest zones. Five-to-ten year viability hinges on cultivation-to-extract backward integration completion before wild quota compression accelerates. Watch for EFSA novel food consultation pathway acceleration as inflection indicator for European functional food market entry eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cultivation Partnership Establishment | Colombian and Ecuadorian orchard development reduces dependency on Peru's biodiversity-regulated wild harvest quotas. |
| Solvent Innovation Investment | Parallel EPA and REACH compliance capabilities preserve cross-border market access for hydroalcoholic extract shipments. |
| B2B Marketplace Platform Launch | Direct-to-manufacturer distribution disintermediates traditional broker networks for transparent phytochemical potency pricing. |
| Organic Certification Expansion | USDA National Organic Program alignment protects label integrity against intensifying enforcement actions. |
| Near-Infrared Spectroscopy Deployment | Field-side vitamin C estimation reduces laboratory dependency and enables real-time procurement adjustments. |
Study Parameters
A standing panel of extraction facility operators, nutraceutical procurement directors, and regional cooperative managers provided ongoing calibration across the study period. Primary interviews with ANVISA licensing specialists, USDA Organic Program certifiers, and EFSA novel food consultants combined with secondary validation from customs records, botanical trade databases, and SEC filings of publicly listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing across product format, end user, application, and distribution channel dimensions.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling capturing powder versus liquid format splits, nutraceutical company versus food manufacturer procurement patterns, and dietary supplement versus functional food application trajectories. CAGRs derived from historical volume trajectories adjusted for regulatory pathway acceleration and synthetic substitution elasticity. Cultivation partnership announcements and biodiversity authority quota revisions served as industry-specific forecast inputs.
Practitioners should monitor wild harvest quota adjustments, organic certification reciprocity negotiations, and EFSA novel food consultation throughput for early signals of supply constraint or market access expansion. Forecasts reflect documented assumptions regarding solvent regulatory stability and immunity-positioned nutraceutical demand persistence. Cross-checking against botanical ingredient import statistics and extraction equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Concentrate Protein Market