
 Internet of Senses Market | 2026-2036
Internet of Senses Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Senses Market Foresight
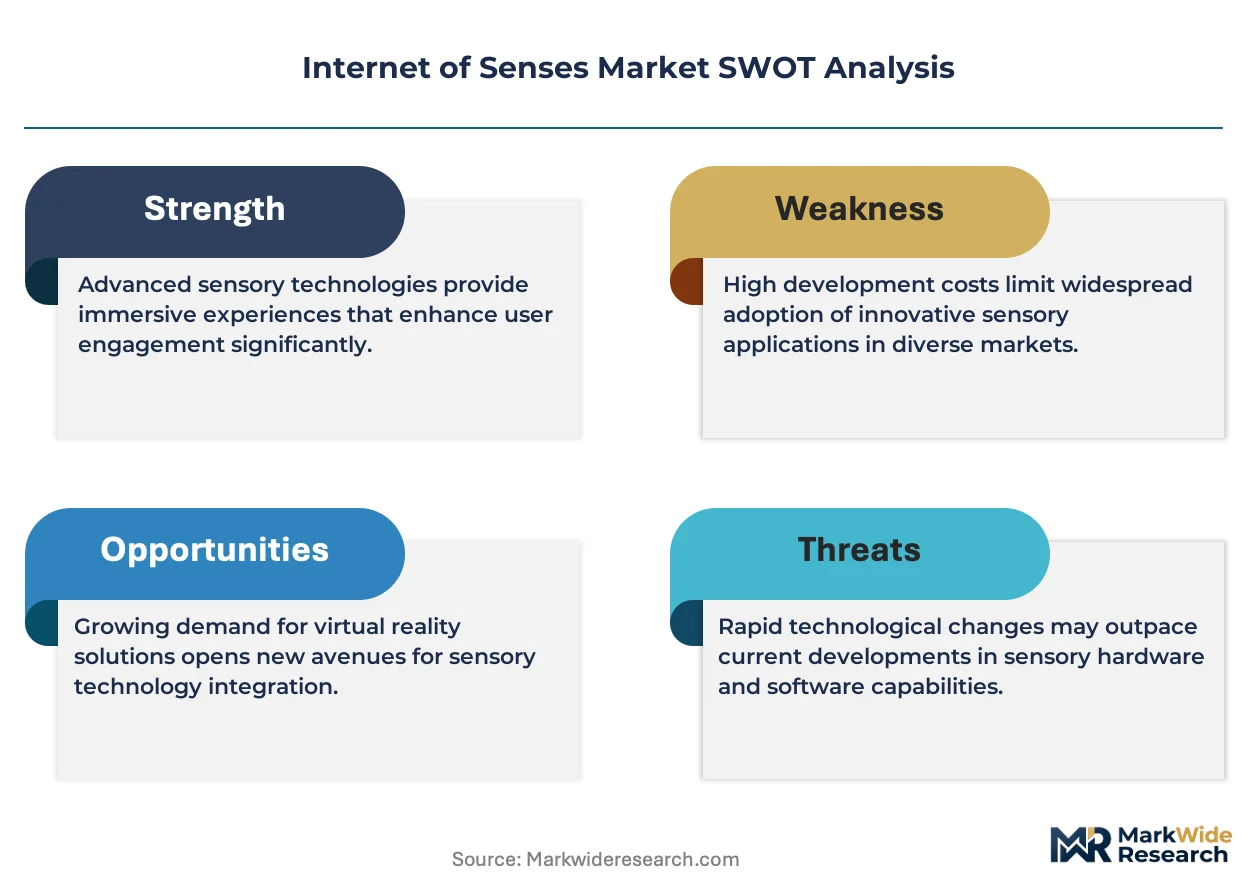
ISO/IEC 27001 certification for sensory data security is collapsing the barrier between consumer electronics entrants and medical-grade system suppliers. NVIDIA leverages its GPU architecture to anchor real-time neural rendering pipelines for olfactory and gustatory simulation. Qualcomm competes through integrated haptics silicon that extends tactile feedback resolution into sub-millimeter precision for wearable form factors.
The Internet of Senses encompasses networked hardware, software protocols, and neural interfaces that capture, transmit, and reproduce multisensory stimuli across distributed environments, operating through sub-10ms latency thresholds to preserve perceptual coherence. Its primary commercial purpose centers on closing the sensory gap between physical presence and digital interaction for remote collaboration, therapy, and commerce. Haptics and sensory processing technologies lead current deployment, while AR applications in healthcare represent the fastest-expanding margin pool as reimbursement frameworks mature. Wearables dominate device-type volume, though IoT sensors embedded in environmental infrastructure capture the highest per-unit data value for enterprise clients.
FDA digital health pre-certification, EU AI Act risk classification for biometric inference, and GDPR Article 9 special-category data rules collectively determine which sensory platforms achieve market access and which face deployment restrictions. The EU F-Gas Regulation additionally constrains thermal feedback devices using refrigerant-based actuators, pushing manufacturers toward solid-state alternatives. Stakeholders must monitor whether emerging national brain-computer interface statutes fragment compliance requirements before standardization bodies harmonize cross-border sensory data protocols.
Market Dynamics
Latency compression below 10 milliseconds is restructuring competitive positioning across sensory hardware, software, and infrastructure layers simultaneously.
Growth Catalysts
- FDA digital health pre-certification:The pathway accelerates haptic surgical training system deployments across US hospital networks.
- Remote surgical training demand:Healthcare providers invest in force-feedback platforms to close skill transfer gaps between teaching and community hospitals.
- EU AI Act biometric inference rules:Risk classification frameworks create compliance-driven procurement preferences for certified sensory data processors.
Market Restraints
- GDPR Article 9 special-category data:Cross-border sensory data flows face fragmentation as member states interpret biometric inference rules divergently.
- Refrigerant-dependent thermal actuators:EU F-Gas Regulation phase-down schedules force hardware redesigns toward solid-state alternatives.
- Sub-millimeter haptic resolution:Precision requirements strain MEMS foundry capacity concentrated in East Asian manufacturing clusters.
Strategic Opportunities
- ISO/IEC 27001 sensory data certification:Security standards create entry paths for consumer electronics suppliers into medical-grade procurement channels.
- Environmental IoT sensor networks:Enterprise infrastructure deployments capture premium per-unit data values for industrial digital twin applications.
- AR therapy reimbursement maturation:Payers in Germany and France expand coverage frameworks for immersive mental health interventions.
Industry Challenges
- Neural interface talent scarcity:Brain-computer interface engineering expertise concentrates in academic and defense-adjacent institutions.
- Multi-jurisdiction BCI statutes:Emerging national brain-computer interface laws in Brazil and South Korea fragment compliance requirements ahead of ISO harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Senses Market |
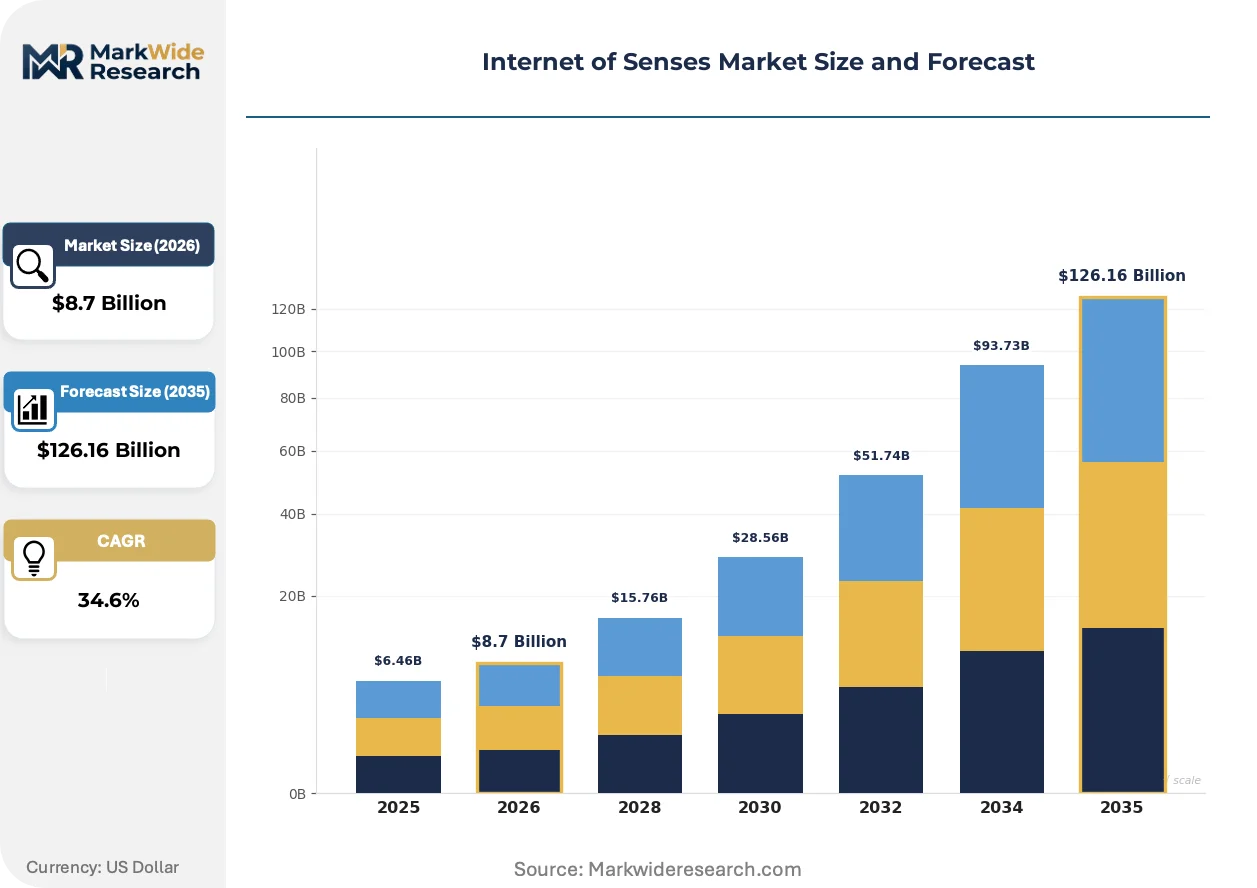
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AR, VR, Haptics, Sensory Processing Application: Entertainment, Healthcare, Education, Retail End User: Consumers, Businesses, Developers, Researchers Device Type: Wearables, Sensors, IoT Devices, Mobile Apps |
| Companies Covered | Amazon, Sony, Google, NVIDIA, Qualcomm, Microsoft, Samsung, IBM, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Senses Market Shifts & Advancements
Real-time neural rendering pipelines are compressing development timelines for olfactory and gustatory simulation platforms previously confined to laboratory environments.
Solid-state thermal feedback actuators are displacing refrigerant-based systems across wearable and environmental form factors. Medical device manufacturers in Germany and Switzerland adopt piezoelectric and electrocaloric alternatives to maintain EU market access. The shift compresses supply chain lead times while eliminating F-Gas compliance documentation burdens.
EU AI Act risk classification for biometric inference is restructuring vendor qualification requirements. High-risk sensory data processing systems must demonstrate conformity with harmonized standards before CE marking. Healthcare and workplace safety applications face the steepest compliance ramps, driving consolidation toward vertically integrated platform suppliers.
Hospital procurement departments now bundle haptic training systems with outcome-based service commitments rather than capital equipment purchases. Device-as-a-service contracts spread deployment costs across multi-year operating budgets. The United States exhibits the fastest contract structure evolution, with IDN consolidation amplifying buyer negotiating leverage.
Internet of Senses Market Segmentation
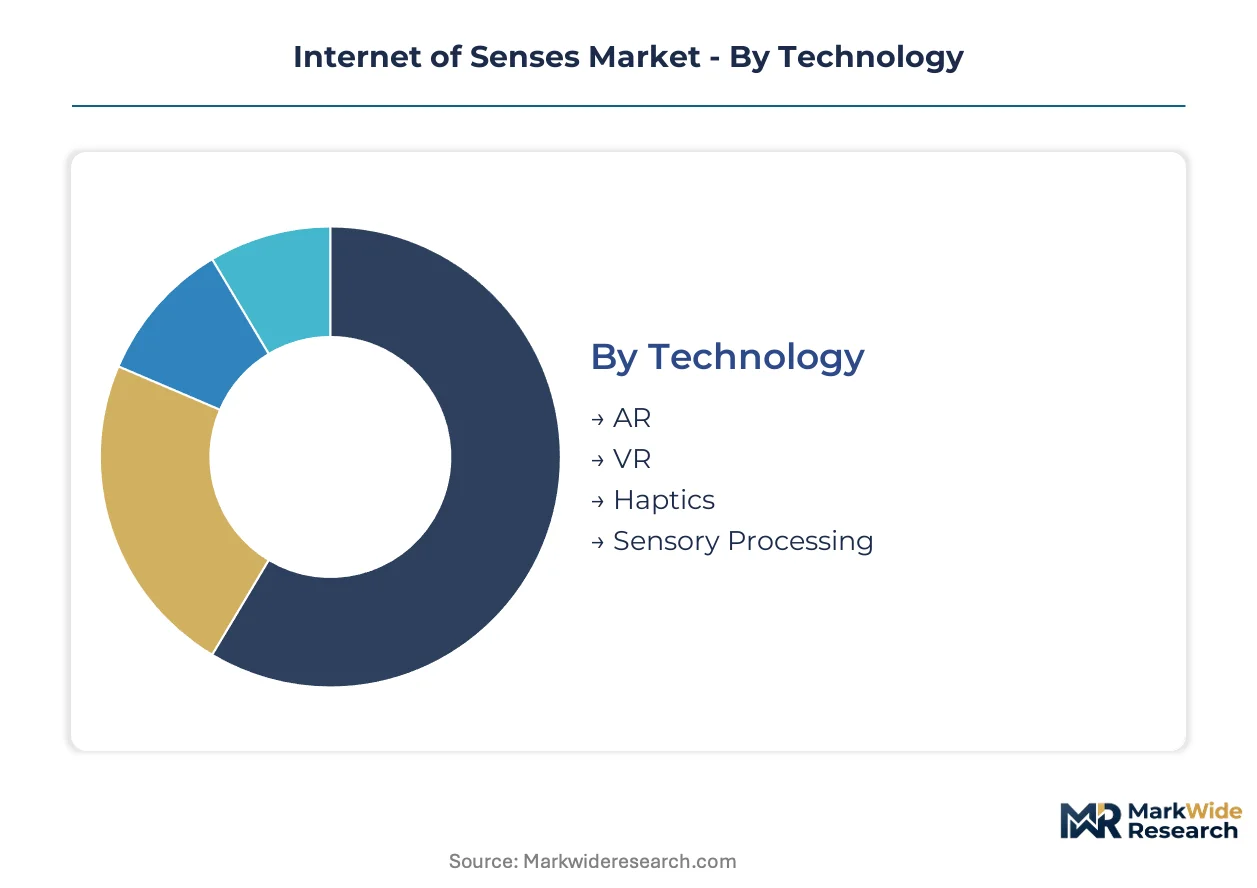
Segmentation in the Internet of Senses Market reveals how latency thresholds, sensory fidelity requirements, and regulatory compliance costs concentrate value across distinct technology-application intersections. Understanding these divisions exposes where procurement budgets flow and which vendor capabilities unlock premium pricing.
Technology:
Haptics and sensory processing dominate domestic procurement in the United States and Germany, while AR and VR systems show stronger export orientation toward Asia-Pacific healthcare markets.
- Haptics:Force-feedback mechanisms with sub-millimeter precision enable remote surgical training and industrial teleoperation. Demand concentrates in US hospital networks pursuing FDA digital health pre-certification pathways for resident education programs.
- Sensory Processing:Real-time neural rendering pipelines compress olfactory and gustatory simulation latency below 10 milliseconds. German automotive and Swiss medical device manufacturers deploy these systems for immersive design review and therapeutic applications.
- AR:Optical waveguide and spatial computing platforms overlay synthetic sensory stimuli onto physical environments. Japanese industrial firms and French mental health clinics drive procurement volume.
- VR:Fully enclosed visual-auditory environments with emerging haptic integration serve entertainment and clinical exposure therapy. South Korean gaming conglomerates and US Veterans Affairs medical centers represent anchor demand.
Haptics holds the largest share; momentum sits with sensory processing as EU AI Act biometric inference rules elevate certified platform valuations.
Application:
Healthcare applications command the steepest compliance premiums, while entertainment and retail segments compete on consumer price elasticity.
- Healthcare:Remote surgical training, AR therapy reimbursement, and biometric inference diagnostics require ISO/IEC 27001 certification and GDPR Article 9 compliance. German and French payers expanding coverage frameworks for immersive mental health interventions.
- Education:Haptic-enabled skill transfer platforms connect teaching hospitals with community facilities. US academic medical centers and British surgical colleges procure force-feedback systems through multi-year device-as-a-service contracts.
- Entertainment:Consumer-grade olfactory and gustatory simulation targets premium experience venues. South Korean and UAE entertainment developers testing solid-state thermal feedback for theme park deployments.
- Retail:Virtual product interaction with tactile and thermal feedback reduces return rates for apparel and furniture. US and UK e-commerce platforms piloting sensory-enabled digital showrooms.
Healthcare captures the highest margin pool; education is climbing fastest as reimbursement frameworks mature and procurement shifts to outcome-based contracting.
End User:
Business procurement dominates volume for certified medical-grade systems, while consumer demand concentrates in entertainment and wellness applications.
- Businesses:Enterprise clients in manufacturing, healthcare, and defense specify sub-10ms latency and cross-border data sovereignty compliance. German industrial digital twin deployments and US integrated delivery networks anchor procurement.
- Researchers:Academic and defense-adjacent institutions concentrate brain-computer interface engineering expertise. Swiss neuroscience centers and South Korean government laboratories funding neural interface development programs.
- Consumers:Individual purchasers access sensory platforms through gaming peripherals and wellness wearables. Price sensitivity limits penetration to premium segments in US, Japanese, and South Korean markets.
- Developers:Software and content creators require SDK access and neural rendering pipeline documentation. NVIDIA and Qualcomm providing toolchains for olfactory simulation and high-resolution haptics.
Businesses hold the largest share; researchers are expanding most quickly as national BCI statutes in Brazil and South Korea fragment compliance requirements ahead of ISO harmonization.
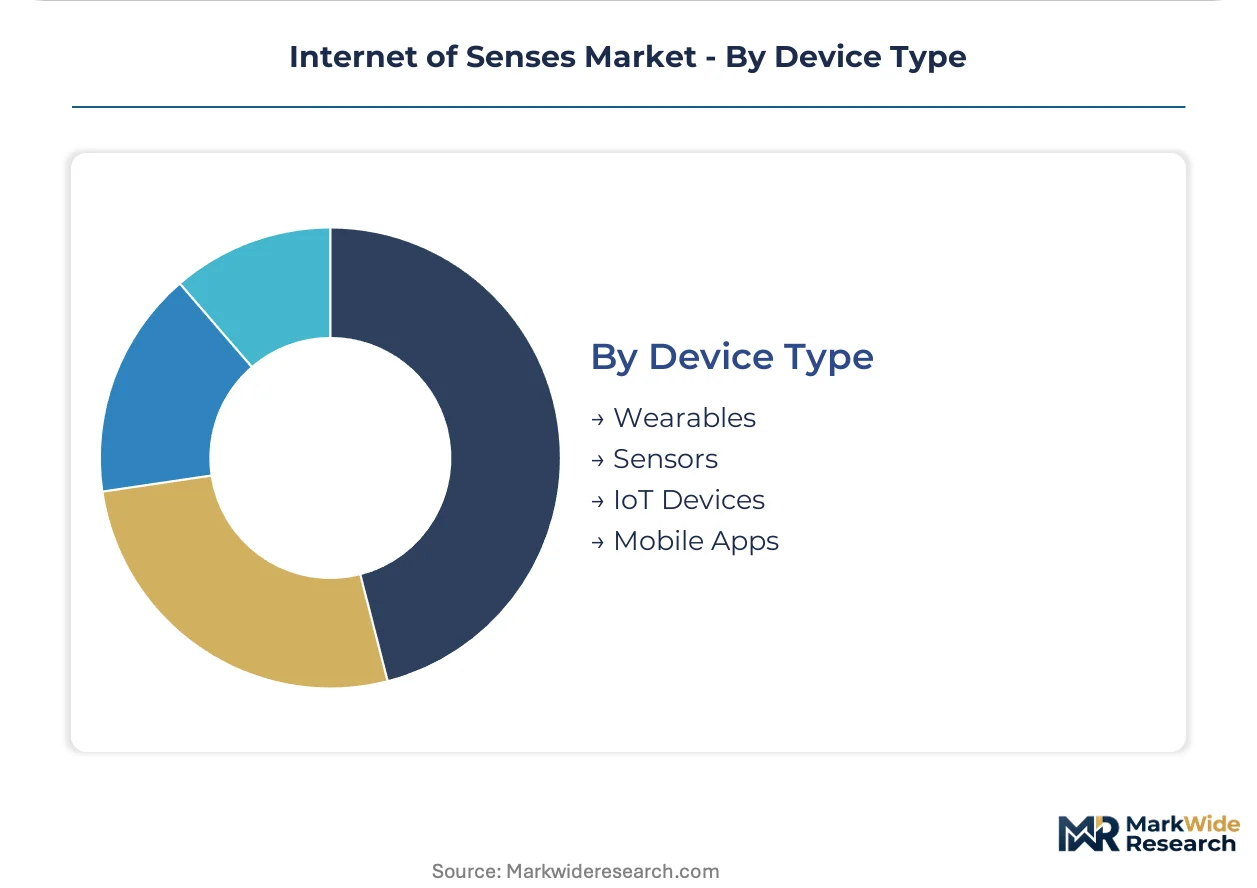
Device Type:
Wearables and mobile apps reach consumer distribution channels, while environmental IoT sensors capture enterprise premium pricing.
- IoT Devices:Environmental infrastructure sensors embedded in manufacturing floors and clinical spaces generate the highest per-unit data value. German automotive plants and US hospital networks deploying industrial digital twin applications.
- Wearables:Haptic gloves, thermal feedback vests, and olfactory masks dominate unit volume. MEMS foundry capacity constraints in East Asian manufacturing clusters limit sub-millimeter resolution supply.
- Sensors:Distributed biometric and environmental capture nodes feed sensory processing pipelines. Swiss medical device manufacturers adopting piezoelectric alternatives to maintain EU F-Gas Regulation compliance.
- Mobile Apps:Software layers delivering sensory content to commodity hardware face commoditization pressure. Differentiation depends on exclusive content libraries and cloud rendering partnerships.
IoT Devices command the highest unit economics; wearables are gaining share fastest as solid-state thermal actuators displace refrigerant-based systems and compress supply chain lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sub-10 millisecond latency requirements for perceptual coherence concentrate infrastructure investment around fiber-dense metropolitan clusters with direct transatlantic and transpacific cable landings.
United States
FDA digital health pre-certification pathways accelerate haptic surgical training deployments across integrated delivery networks. HIPAA and emerging state-level brain-computer interface statutes fragment compliance requirements ahead of federal harmonization. Boston and San Francisco Bay Area clusters anchor neural interface engineering talent pools for defense-adjacent and academic research programs.
Germany
Automotive industrial digital twin applications drive environmental IoT sensor procurement for immersive design review workflows. EU AI Act biometric inference risk classification and F-Gas Regulation phase-down schedules force solid-state thermal actuator redesigns. Stuttgart and Munich manufacturing corridors concentrate MEMS foundry demand for sub-millimeter haptic resolution systems.
China
MIIT standards for low-latency networking infrastructure expand domestic capacity for real-time sensory data transmission. GB standards and dual carbon goals constrain refrigerant-based thermal feedback device manufacturing. Shenzhen and Shanghai hardware ecosystems dominate wearable haptics assembly while facing MEMS precision component import dependencies.
South Korea
National brain-computer interface statutes under MFDS jurisdiction fragment compliance ahead of ISO harmonization efforts. Gaming conglomerates and government laboratories co-fund neural rendering pipeline development for olfactory simulation. Seoul Capital Area and Busan-Ulsan corridors concentrate immersive entertainment venue deployment and BCI engineering programs.
Switzerland
Swissmedic medical device frameworks and GDPR Article 9 special-category data rules elevate certified sensory platform valuations for therapeutic applications. Piezoelectric thermal actuator adoption accelerates as EU F-Gas Regulation eliminates refrigerant-based alternatives. Zurich and Geneva neuroscience centers anchor brain-computer interface research with defense and academic institutional linkages.
Internet of Senses Market Competitive Landscape
Listed leaders compete with private specialists across haptic silicon, neural rendering, and cloud infrastructure layers. The vendor base stratifies between GPU-architecture anchors, integrated mobile silicon suppliers, and hyperscale cloud operators. Three archetypes dominate: semiconductor platform owners, device-as-a-service bundlers, and sensory content pipeline operators. M&A activity concentrates on neural interface startups and MEMS foundry capacity, while strategic partnerships between hardware suppliers and healthcare IDNs reshape procurement channels.
Within the semiconductor platform tier, NVIDIA and Qualcomm exemplify divergent architectural approaches to sensory fidelity. NVIDIA occupies a position anchored on GPU-based neural rendering for olfactory and gustatory simulation. Qualcomm sits within the mobile-integrated vector, emphasizing sub-millimeter haptic resolution for wearable form factors. Among hyperscale operators, Amazon represents the cloud-rendering and content-distribution archetype, leveraging infrastructure density to compress latency thresholds for consumer-facing sensory applications.
| Leading Market Players |
|---|
| Amazon |
| Sony |
| NVIDIA |
| Qualcomm |
| Microsoft |
| Samsung |
| IBM |
| Apple |
| Others |
Supply & Pricing Matrix
ISO/IEC 27001 certification gates both supplier qualification and price differentiation simultaneously, separating medical-grade sensory platforms from consumer electronics entrants while compressing margins for uncertified hardware vendors.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing across premium certified, standard compliant, and economy consumer levels. Price differentiation rests on FDA pre-certification status and GDPR Article 9 compliance grade, with certified medical systems commanding substantial premiums over uncertified alternatives. Cost compression in economy wearables is intensifying because MEMS foundry capacity constraints in East Asia limit sub-millimeter haptic supply. Consumer gaming segments exhibit highest price sensitivity, while US hospital networks and German automotive OEMs show lowest elasticity due to outcome-based contracting preferences.
Supply Chain Analysis
Strait of Malacca transit underwrites East Asian MEMS component flows to European and North American assembly facilities, creating logistics vulnerability for sub-millimeter precision haptics. Supply concentrates in Taiwan, South Korea, and China for MEMS foundry capacity, with Germany and Switzerland anchoring piezoelectric thermal actuator production. Raw material dependencies span rare-earth magnets for haptic motors, gallium nitride for low-latency processing chips, and specialized polymers for olfactory simulation membranes. Single-source vulnerability concentrates in TSMC-adjacent advanced node capacity. Distribution runs through device-as-a-service contracts for healthcare and direct component supply for automotive and industrial OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as FDA digital health pre-certification pathways mature and reimbursement frameworks for AR therapy expand across German and French payer systems.
For Market Incumbents: Compound certification moats by accelerating ISO/IEC 27001 and EU AI Act high-risk system conformity investments before harmonized standards crystallize. Defend against consumer electronics entrants by locking multi-year device-as-a-service contracts with US integrated delivery networks. Prioritize backward integration into MEMS foundry partnerships to secure sub-millimeter haptic resolution capacity. For New Entrants and Emerging Players: FDA digital health pre-certification fast-tracks offer the most penetrable entry vector for haptic surgical training systems targeting community hospital networks. White-space concentrates in solid-state thermal actuator supply for EU F-Gas Regulation compliance, with German automotive and Swiss medical device manufacturers seeking refrigerant-free alternatives. Go-to-market should leverage outcome-based contracting models rather than capital equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across neural rendering pipeline development as real-time olfactory simulation demands GPU cluster investments. Long-term viability favors vertically integrated platform suppliers combining haptic silicon, sensory processing software, and healthcare compliance expertise. Watch for MFDS and ANVISA brain-computer interface statute harmonization as inflection signal for cross-border sensory data platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Investment | Medical-grade procurement channel access unlocks premium pricing for sensory data platforms. |
| Solid-State Thermal Actuator Transition | EU F-Gas Regulation compliance eliminates refrigerant-based competitor supply from European markets. |
| Device-as-a-Service Contract Structuring | Outcome-based pricing spreads haptic system costs across multi-year hospital operating budgets. |
| MEMS Foundry Capacity Partnership | Sub-millimeter precision haptic supply security insulates against East Asian manufacturing bottlenecks. |
| Neural Rendering Pipeline Development | Real-time olfactory and gustatory simulation capabilities differentiate platform offerings for entertainment and therapy. |
Research Methodology
Operator-level perspectives from haptic hardware engineers, hospital procurement managers, sensory processing software architects, and biomedical compliance officers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU AI Act implementation guidance, GPO contract databases, and hyperscaler neural rendering capex disclosures. Bottom-up unit economics and top-down regulatory market sizing triangulated volume and value estimates.
Sensitivity analysis tested forecast robustness across latency threshold achievement, MEMS foundry capacity expansion scenarios, and reimbursement framework maturation timelines. Segmentation dimensions modeled include technology tier, application compliance grade, end-user procurement authority, and regional regulatory cluster. CAGRs derived from installed base growth, replacement cycle compression, and premium certified system mix shifts. Industry-specific inputs incorporated EU F-Gas Regulation phase-down schedules and emerging BCI statute fragmentation patterns.
Underlying assumptions cover FDA pre-certification pathway stability and GDPR Article 9 enforcement consistency, with deviation risk concentrated in multi-jurisdiction BCI law fragmentation and MEMS supply chain disruption. Forecasts reflect these conditions with revision triggers tied to regulatory harmonization milestones and foundry capacity investment announcements. Revision becomes warranted when neural interface talent scarcity crosses thresholds that stall platform development timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market