
 Payment Orchestration Platform Market | 2026-2036
Payment Orchestration Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Orchestration Platform Market Intelligence
The gap between premium orchestration stacks and commodity gateway aggregation is restructuring how merchants evaluate vendor relationships. Primer leverages its no-code workflow engine to sustain differentiation among enterprise retailers requiring complex routing logic. Gr4vy anchors its position through deep cloud-native architecture, while Akurateco competes on white-label flexibility for regional banks.
A payment orchestration platform is a middleware layer that unifies multiple payment service providers, acquirers, and fraud tools through a single API integration point, typically processing transactions with sub-200ms latency while enabling intelligent routing based on cost, success rate, or geographic rules. Its primary commercial purpose is to eliminate vendor lock-in, optimize authorization rates, and reduce total cost of payment acceptance for merchants operating across borders. API Integration services dominate current deployment volumes because merchants prioritize rapid connectivity over custom builds, while Fraud Detection capabilities represent the fastest-growing margin pool as chargeback liability rules tighten. Public Cloud deployment leads among mid-market adopters seeking elastic scaling, though Hybrid Cloud configurations are gaining traction among European financial institutions navigating data residency requirements.
PCI DSS mandates from the payment card industry and GDPR obligations enforced by European regulators shape product architecture by requiring tokenization and regional data segregation as baseline features. The EU AI Act introduces additional compliance layers for automated fraud scoring models, forcing vendors to document algorithmic decision pathways. Merchants and platform providers must monitor how open banking regulations in the United Kingdom and PSD3 evolution across the European Union alter the competitive balance between bank-direct and card-network routing.
Market Dynamics
Merchant demand for authorization rate optimization is compressing the competitive window between pure gateway aggregators and full-stack orchestration platforms, forcing vendors to demonstrate measurable lift on transaction success within 90-day proof-of-concept cycles.
Growth Catalysts
- PCI DSS Level 1 Certification Mandates:Retailers processing over 6 million card transactions annually must maintain certified infrastructure, driving consolidation toward orchestration layers that absorb compliance burden.
- Multi-Acquirer Resilience Requirements:E-commerce merchants in Germany, the United Kingdom, and France are deploying redundant routing to eliminate single points of failure during peak transaction windows.
- Open Banking API Standardization:PSD2-driven account-to-account payment rails are creating net-new transaction volumes that orchestration platforms capture through unified API abstraction.
Market Restraints
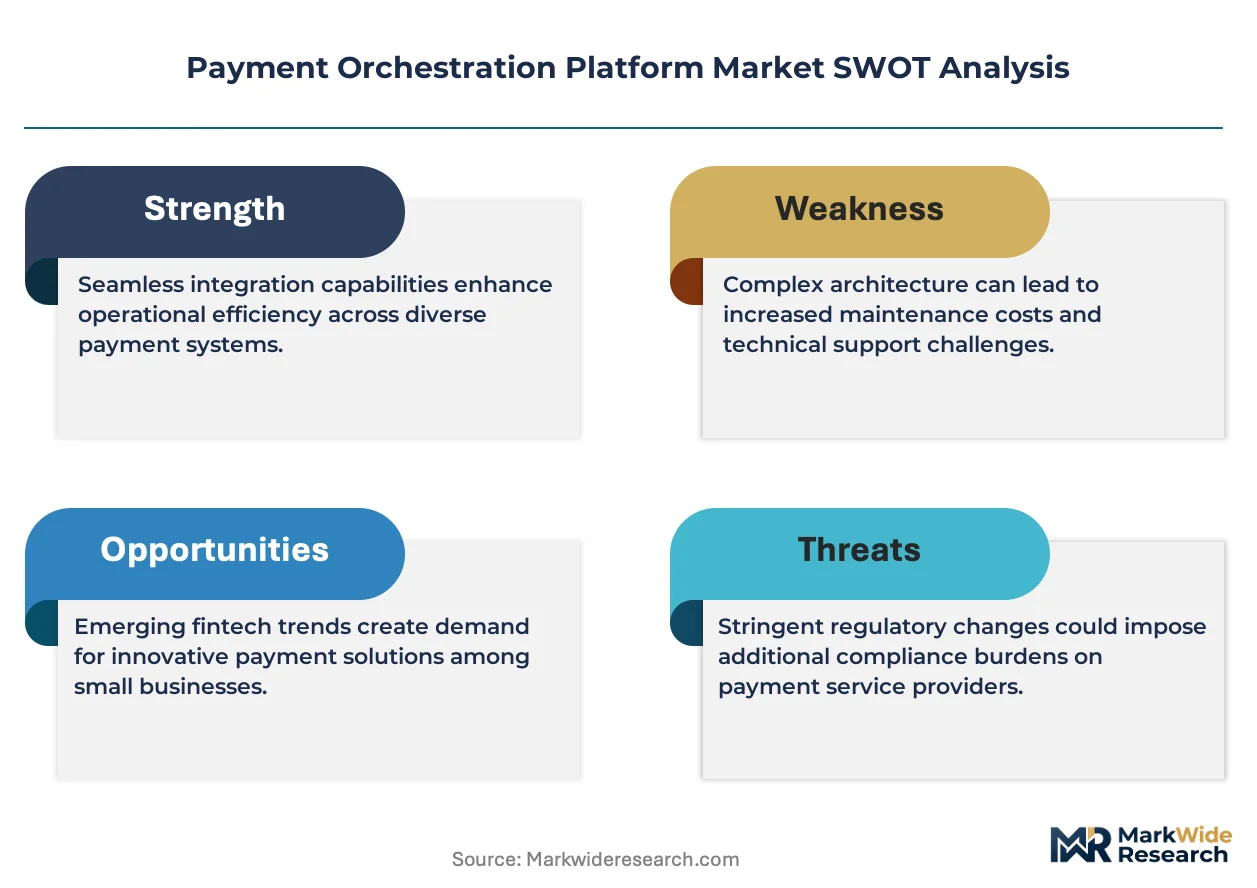
- Cloud Infrastructure Concentration Risk:Three hyperscale providers dominate orchestration hosting, creating systemic vulnerability if regional outages cascade across payment stacks.
- Tokenization Cost Inflation:Network token fees from Visa and Mastercard are compressing margins for high-volume merchants already operating on thin interchange-plus pricing.
- GDPR Data Residency Friction:Cross-border transaction routing requires regional data segregation that fragments liquidity pools and complicates real-time fraud scoring.
Strategic Opportunities
- Embedded Finance Convergence:Orchestration vendors that integrate Buy-Now-Pay-Later decisioning engines with core routing logic can capture merchant lending origination fees.
- EU AI Act Compliance Services:Automated fraud scoring documentation requirements create recurring revenue streams for platforms offering algorithmic audit trails as a service.
- Unified Reconciliation Layer:Merchants operating across 15-plus acquirers face manual settlement matching; automated reconciliation represents uncontracted wallet share.
Industry Challenges
- Legacy ERP Integration Complexity:Enterprise merchants running SAP or Oracle financial modules require 6-to-12-month implementation cycles that delay orchestration deployment.
- Scheme Certification Bottlenecks:New market entrants face 18-month approval timelines from Visa and Mastercard for direct network connectivity, privileging incumbents with existing certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Orchestration Platform Market |
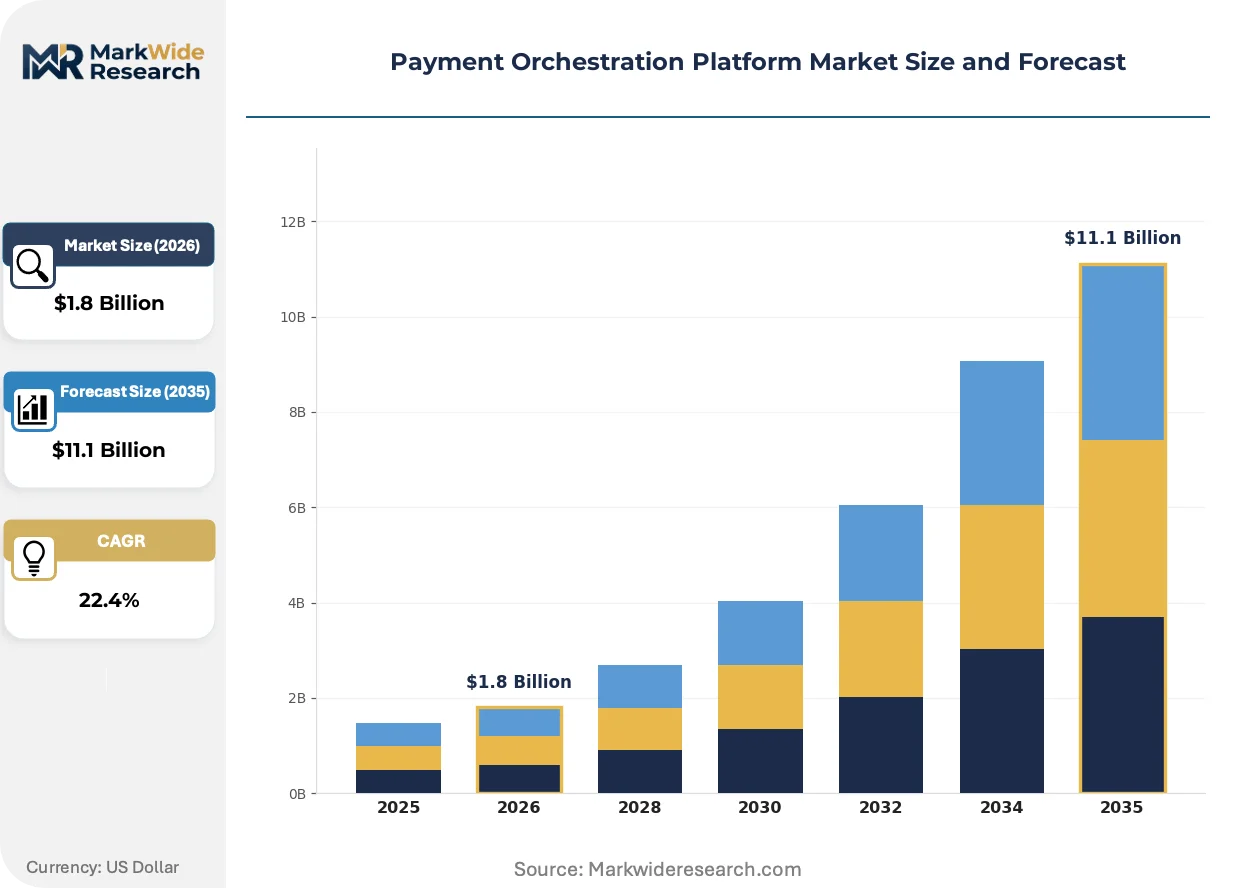
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Integration, Webhooks, Payment Gateway, Fraud Detection Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: E-commerce, Retail, Hospitality, Financial Institutions Transaction Type: Recurring Payments, One-Time Payments, International Transactions, In-App Purchases |
| Companies Covered | Primer, Gr4vy, Akurateco, Solidgate, IXOPAY, Rapyd, Spreedly, Paydock, BlueSnap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Orchestration Platform Market Strategic Shifts & Innovations
Real-time payment rails and embedded machine learning are converging to transform how transaction routing decisions are executed, shifting competitive advantage from connectivity breadth toward predictive intelligence.
Intelligent routing engines that dynamically select acquirers based on predicted authorization probability are rewriting how merchants optimize payment costs. Large omnichannel retailers are deploying these systems across 50-plus processor relationships within 18-month rollout cycles. The technology is compressing the value of static routing tables and elevating vendors with proprietary success-rate prediction models.
The EU AI Act's algorithmic transparency requirements are mandating explainable decision pathways for automated fraud scoring systems. Orchestration platforms must now document feature weights and model drift across European deployments. High-risk merchant categories including digital goods and travel are accelerating procurement of compliant infrastructure ahead of enforcement deadlines.
Merchant procurement teams are consolidating vendor relationships from an average of 12 separate payment contracts toward 3-to-4 orchestrated relationships. Mid-market retailers are displacing point-solution fraud vendors in favor of bundled platforms. This concentration is most visible in the United Kingdom, where open banking adoption has conditioned finance teams to expect unified reporting across payment methods.
Payment Orchestration Platform Market Segmentation
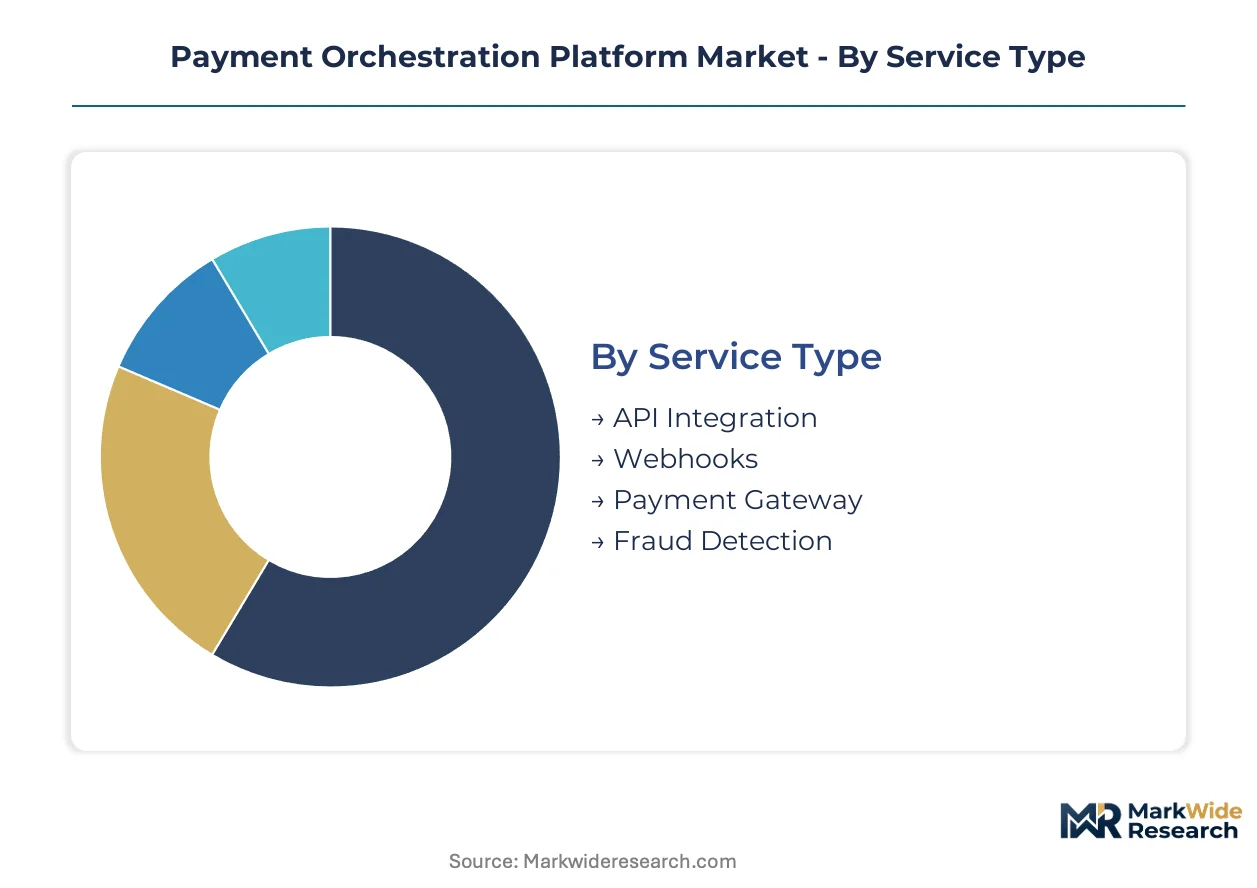
Payment orchestration platforms segment across service architecture, infrastructure deployment, buyer vertical, and transaction mechanics. Each dimension shapes procurement criteria, implementation complexity, and margin structure for vendors competing across merchant tiers.
Service Type:
Merchants prioritize connectivity speed and fraud liability exposure when evaluating service tier investments.
- API Integration:Unified RESTful endpoints abstract multiple PSPs through single credential sets, eliminating redundant technical contracts. German and UK e-commerce merchants deploy this layer first to compress 12-week integration cycles into days. PCI scope reduction drives procurement decisions among mid-market retailers lacking dedicated compliance teams.
- Fraud Detection:Machine learning models score transaction risk in sub-200ms windows, triggering step-up authentication or blocking before authorization attempts. EU AI Act documentation requirements are accelerating vendor consolidation as merchants seek pre-certified algorithmic audit trails. Digital goods merchants in France face acute chargeback liability pressure.
- Webhooks:Event-driven callbacks enable real-time reconciliation and notification workflows across distributed systems.
- Payment Gateway:Traditional card-routing infrastructure with static failover rules.
API Integration leads on scale; Fraud Detection leads on momentum.
Deployment Model:
Infrastructure location decisions hinge on data residency mandates and elasticity requirements across transaction volume curves.
- Public Cloud:Elastic compute pools scale processing capacity during peak retail windows without capital commitment. Mid-market adopters in the United Kingdom favor this model for Black Friday and holiday transaction surges. GDPR-compliant regional instances from hyperscale providers address sovereign data concerns.
- Hybrid Cloud:Sensitive token vaults reside on-premises while routing logic executes in cloud environments. French and German financial institutions navigate PSD3 data localization expectations through this architecture. Separation of cardholder data from processing layers reduces audit scope.
- Private Cloud:Dedicated tenant environments with single-merchant infrastructure isolation.
- On-Premises:Fully captive hardware stacks for maximum control over cryptographic material.
Public Cloud dominates transaction throughput; Hybrid Cloud climbs the fastest among regulated European deployers.
End User:
Vertical-specific authorization rate benchmarks and refund velocity requirements shape platform configuration priorities.
- E-commerce:Pure-play digital merchants route across 15-plus acquirer relationships to optimize cross-border authorization probability. Subscription billing complexity demands recurring payment token lifecycle management. Peak load engineering separates tier-1 platforms from commodity aggregators.
- Financial Institutions:Regional banks white-label orchestration layers to offer merchant-acquiring services without building proprietary stacks. PSD2 account-to-account payment integration requires open banking API abstraction. Compliance documentation burdens favor turnkey vendor partnerships.
- Retail:Omnichannel merchants unify in-store and online payment flows.
- Hospitality:Pre-authorization and delayed capture workflows dominate hotel and travel use cases.
E-commerce commands absolute deployment volume; Financial Institutions expand most quickly as banking-as-a-service models proliferate.
Transaction Type:
Payment timing and geography determine routing logic complexity and fraud model calibration requirements.
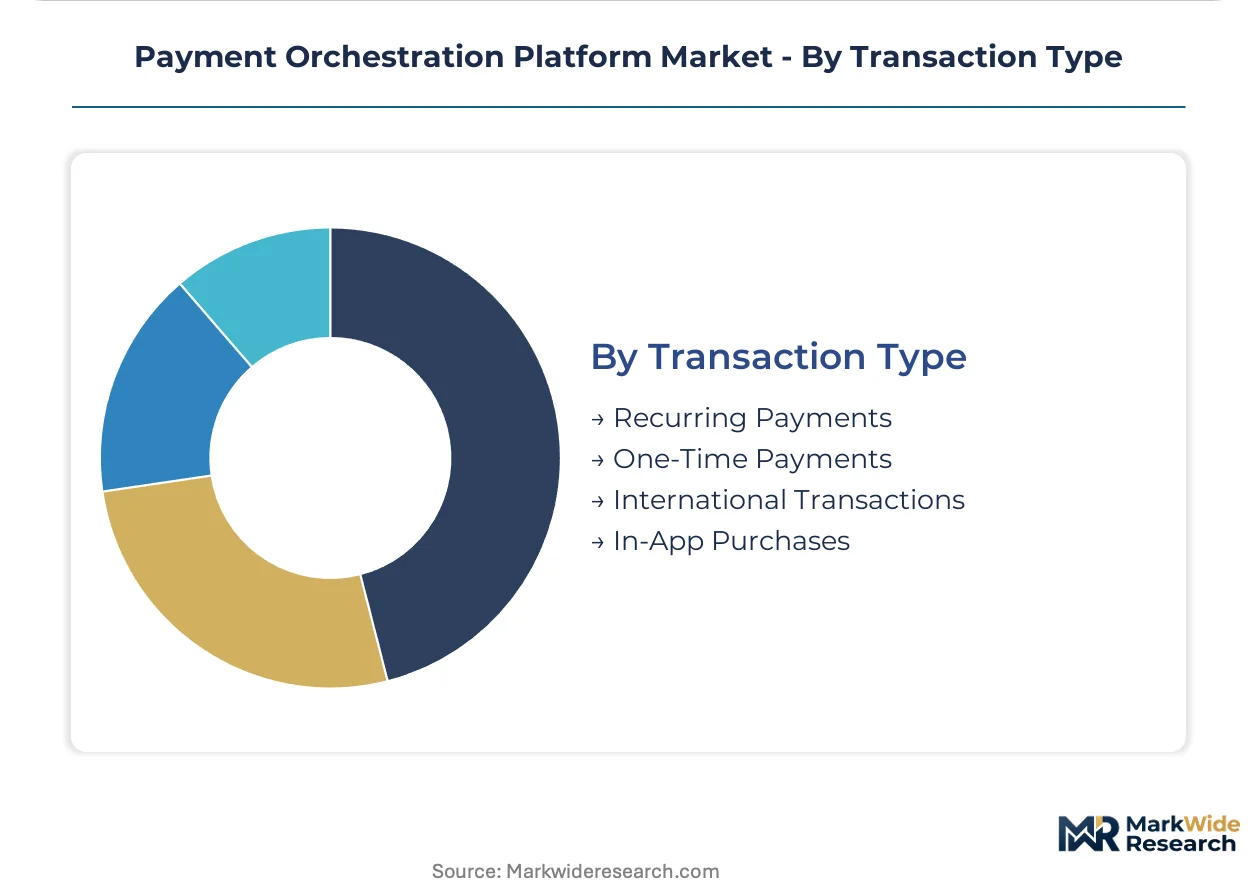
- Recurring Payments:Stored credential protocols from Visa and Mastercard mandate token refresh cycles and explicit cardholder consent tracking. Subscription merchants in Germany face strong customer authentication friction under PSD2 dynamic linking rules. Dunning management integration separates orchestration platforms from basic gateway services.
- International Transactions:Multi-currency settlement and local acquiring optimization reduce interchange costs on cross-border sales. UK merchants selling into European Union markets post-Brexit navigate scheme fee restructuring. Dynamic currency conversion adds margin capture opportunity.
- One-Time Payments:Single-purchase authorization with minimal stored data requirements.
- In-App Purchases:Mobile-native checkout flows with biometric authentication integration.
Recurring Payments anchors platform stickiness through token vault retention; International Transactions gains share fastest as merchant cross-border sales expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United Kingdom diverge in orchestration adoption velocity, with German merchants prioritizing multi-acquirer redundancy while UK retailers accelerate open banking API integration. France occupies a middle position, balancing PSD2 compliance with embedded finance experimentation. The United States and Australia round out the five-country analysis, each presenting distinct regulatory and infrastructure environments.
United States
Merchants processing high-volume card transactions drive demand for PCI DSS Level 1 certified orchestration layers. The Federal Trade Commission monitors payment data practices under Section 5 of the FTC Act, creating compliance overhead for cross-border routing. Silicon Valley fintech clusters in San Francisco and New York City anchor vendor development activity, with enterprise retailers in both metros deploying intelligent routing engines across 20-plus processor relationships.
Germany
E-commerce merchants operating during peak retail windows require redundant acquirer failover to eliminate single points of failure. The Federal Financial Supervisory Authority enforces PSD2 strong customer authentication rules that complicate subscription billing workflows. Berlin and Munich host the densest concentration of payment infrastructure startups, where regional banks white-label orchestration stacks to compete with direct acquiring relationships.
United Kingdom
Finance teams conditioned by open banking adoption now expect unified reporting across card and account-to-account payment methods. The Financial Conduct Authority oversees PSD2 implementation and emerging AI Act alignment for automated fraud scoring. London's fintech corridor dominates vendor headquarters placement, while Manchester and Birmingham enterprise retailers consolidate from 12 separate payment contracts toward three orchestrated relationships.
France
Digital goods merchants face acute chargeback liability pressure, accelerating procurement of EU AI Act-compliant fraud infrastructure. The Commission Nationale de l'Informatique et des Libertés enforces GDPR data residency requirements that fragment cross-border liquidity pools. Paris anchors the national payment innovation cluster, with Lyon and Marseille mid-market retailers deploying hybrid cloud configurations to separate token vaults from routing logic.
Australia
Merchants expanding into Southeast Asian markets leverage orchestration platforms to navigate multi-currency settlement complexity. The Australian Prudential Regulation Authority supervises payment system stability without direct orchestration-specific mandates. Sydney and Melbourne host the primary fintech development centers, where domestic retailers pilot real-time payment rail integration ahead of broader Asia-Pacific expansion.
Payment Orchestration Platform Market Key Industry Players
Top-tier vendors anchor enterprise relationships requiring sub-200ms latency and complex routing logic, while mid-tier specialists compete on white-label flexibility for regional banks. The vendor base stratifies across three functional tiers: no-code workflow engines, cloud-native infrastructure stacks, and compliance-focused turnkey solutions. Two dominant competitive moves define current positioning: strategic partnerships with hyperscale cloud providers and vertical integration into embedded finance decisioning engines.
Within the no-code workflow tier, Primer exemplifies vendors targeting enterprise retailers with visual routing configuration tools. Gr4vy occupies a position among cloud-native specialists emphasizing infrastructure elasticity. Akurateco represents the white-label flexibility archetype, serving regional financial institutions seeking turnkey merchant-acquiring capabilities without proprietary stack development.
| Leading Market Players |
|---|
| Primer |
| Gr4vy |
| Akurateco |
| Solidgate |
| IXOPAY |
| Rapyd |
| Spreedly |
| Paydock |
| BlueSnap |
| Others |
Cost & Logistics Intelligence
Merchant procurement consolidation toward unified orchestration stacks is compressing vendor margins and forcing hyperscale infrastructure commitments. Platform providers must absorb PCI DSS certification costs and tokenization fees while maintaining sub-200ms latency guarantees, reshaping how pricing tiers align with cloud-native delivery investments.
Pricing Analysis
Capacity additions in hyperscale cloud regions are reshaping price floors for public cloud orchestration deployments. Pricing stratifies across enterprise-grade SLA tiers, mid-market bundled offerings, and white-label infrastructure licenses, with certification grade and transaction volume scale as primary differentiation drivers. Cost compression in the mid-market tier is intensifying because merchants displace point-solution vendors for bundled platforms. Regional banks and financial institutions exhibit highest price sensitivity due to thin merchant-acquiring margins, while omnichannel retailers with 50-plus processor relationships prioritize latency performance over unit economics.
Supply Chain Analysis
Regional distribution centers operated by AWS, Microsoft Azure, and Google Cloud form the hub-and-spoke backbone for orchestration platform delivery. Supply concentrates in the United States, Germany, and the United Kingdom where hyperscale data center clusters anchor processing capacity. The technology stack draws from specialized token vault hardware, machine learning inference accelerators, and open banking API middleware. Single-source vulnerability in cloud infrastructure concentration creates systemic exposure if regional outages cascade across payment stacks. Distribution runs through direct enterprise sales channels and white-label partnerships with regional financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The payment orchestration market functions as a geographic-arbitrage play where regulatory divergence between EU AI Act compliance requirements and US FTC oversight creates cost-advantaged deployment zones for algorithmic audit trail services.
For Market Incumbents: Anchor enterprise relationships through PCI DSS Level 1 certification investments that new entrants cannot replicate within 18-month scheme approval timelines. Defensive consolidation moves include acquiring specialized fraud scoring vendors to pre-empt EU AI Act documentation requirements and expanding hybrid cloud capacity in Frankfurt and Paris to capture PSD3 data localization mandates. The threat of hyperscale cloud providers launching native orchestration services elevates urgency for vendor-neutral positioning. For New Entrants and Emerging Players: Regional bank white-label partnerships offer the most penetrable entry vector given incumbent certification backlogs and 6-to-12-month ERP integration complexity that delays full-stack deployment. White-space targets include automated reconciliation layers for merchants operating across 15-plus acquirers and embedded finance decisioning engines capturing merchant lending origination fees. A channel-centric go-to-market strategy through system integrators serving SAP and Oracle financial modules accelerates enterprise access. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native orchestration specialists possessing existing Visa and Mastercard scheme certifications that compress competitive windows. Long-term viability in the five-to-ten year window hinges on algorithmic transparency capabilities as EU AI Act enforcement tightens. Acquisition target archetypes include fraud scoring vendors with pre-certified audit trail documentation and reconciliation automation platforms addressing uncontracted wallet share. The signal to watch is merchant procurement team consolidation velocity from twelve separate payment contracts toward three-to-four orchestrated relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fraud detection, routing logic, and reconciliation into single API endpoints for merchant consolidation. |
| Strategic Partnership | Hyperscale cloud alliances address GDPR data residency requirements through regional instance deployments. |
| Acquisition of Specialist Firm | Fraud scoring vendors with EU AI Act-compliant documentation accelerate regulatory positioning. |
| Geographic Expansion | Hybrid cloud capacity in Frankfurt and Paris captures PSD3 localization mandates. |
| Product Launch | Embedded finance decisioning engines capture merchant lending origination fees beyond transaction routing. |
Research Approach
Bottom-up merchant transaction volume modeling reconciled against top-down orchestration vendor capacity tracking forms the analytical core. Primary interviews with payment operations directors, CTOs at omnichannel retailers, platform engineers, and regulatory compliance officers combined with secondary validation against SEC filings, hyperscaler capex disclosures, and open banking API documentation. Triangulation across stakeholder inputs and published infrastructure investment data ensures segmentation integrity.
Historical trendline analysis of authorization rate optimization investments and fraud detection procurement patterns anchored the projection framework. Segmentation dimensions modeled include service architecture tier, deployment model, end-user vertical, and transaction mechanics across the analysis window. CAGRs derived from merchant adoption velocity curves and regulatory mandate implementation timelines, with specific inputs from PCI DSS certification pipeline data and scheme approval backlogs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to open banking API standardization velocity and EU AI Act enforcement calibration. Forecasts reflect documented assumptions regarding merchant consolidation behavior and hyperscale infrastructure expansion commitments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Point of Sale Terminals Market
Payments
Europe Credit Cards Market
Payments
China Virtual Cards Market
Payments
North America Payments Market
Payments
North America Payment Analytics Software Market
Payments
Crypto Payment Gateway Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Spain POS Terminals Market
Payments
Hungary POS Terminal Market
Payments
Japan Credit Cards Market
Payments
China Mobile Payments Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
Norway Mobile Payments Market
Payments
Asia-Pacific Payment Gateway Market
Payments
South Korea Mobile Payment Market
Payments
Canada Gift Card and Incentive Card Market