
 Europe Vegan Supplements Market | 2026-2036
Europe Vegan Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vegan Supplements Market Foresight
Direct-to-consumer subscription revenue is reconfiguring margin pools away from traditional retail markups in the Europe vegan supplements sector. Holland & Barrett leverages its brick-and-mortar network across British high streets to sustain omnichannel loyalty. Glanbia Plc anchors its position through in-house production of pea and rice protein isolates for third-party brands. Kerry Group competes by supplying fermented vitamin B12 and omega-3 algal oil to European contract manufacturers.
Europe vegan supplements comprise orally administered nutrient products formulated without animal-derived ingredients, typically utilizing plant protein isolates, algal DHA, cultured B12, and chelated minerals synthesized through fermentation or solvent-free extraction. These products serve consumers seeking to meet micronutrient requirements without reliance on dairy, gelatin, or fish-based inputs. Protein powders occupy the largest revenue pool within product type segmentation due to gym culture penetration and meal-replacement trends, while gummies represent the fastest-growing form category as brands reformulate pectin-based alternatives to replace gelatin. Online retail channels capture expanding margin share as subscription models and influencer marketing reduce customer acquisition costs relative to supermarkets and health stores.
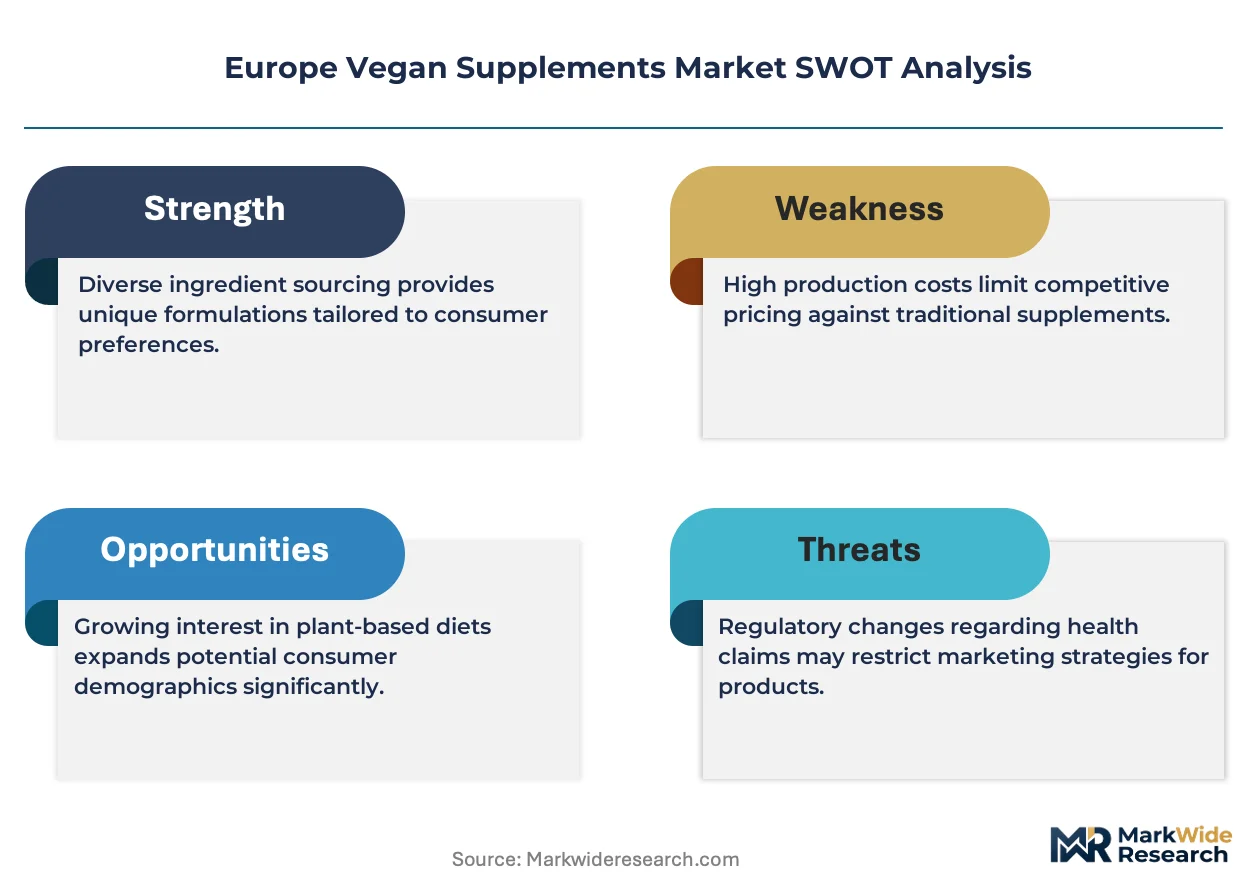
EFSA maintains strict novel food authorization pathways for algae-derived and fermented ingredients entering European formulations. REACH and EU Green Deal sustainability mandates compel manufacturers to document supply chain carbon intensity and eliminate synthetic excipients. The EU AI Act will soon govern algorithmic personalization in direct-to-consumer supplement recommendation engines. Stakeholders must track regulatory divergence between EFSA harmonized standards and emerging national sustainability labels in France, Germany, and the Netherlands.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail margins across Europe while EFSA novel food pathways force manufacturers toward algae-derived and fermented nutrient platforms.
Growth Catalysts
- EU Green Deal sourcing mandates:The Farm to Fork strategy redirects investment toward sustainable algae cultivation and precision fermentation infrastructure.
- Fitness culture penetration:German and British gym chains are expanding private-label plant protein placement through in-house retail channels.
- Precision fermentation:This biotechnology enables cost-competitive cultured vitamin B12 and omega-3 production without marine ecosystem dependency.
Market Restraints
- Input cost volatility:Pea protein isolate prices fluctuate with Canadian and Ukrainian yellow pea harvest cycles.
- Regulatory friction:EFSA novel food authorization timelines extend 18-24 months for algae-derived ingredients entering formulations.
- Supply concentration risk:European algal DHA production clusters in Portugal and southern France create geographic vulnerability.
Strategic Opportunities
- Underpenetrated Eastern Europe:Poland and Romania show rising health-conscious consumer bases with limited dedicated vegan supplement retail presence.
- Regulatory tailwind:France's national sustainability labeling scheme creates first-mover advantage for carbon-documented supply chains.
- Pharmacy channel expansion:German Apotheken are adding dedicated plant-based nutrition sections to capitalize on clinician trust.
Industry Challenges
- Formulation talent scarcity:Food technologists skilled in pectin-based gummy stabilization without gelatin remain scarce across European manufacturing hubs.
- Certification complexity:Dual V-Label and Vegan Society accreditation requirements extend product launch timelines.
- Capex intensity:In-house fermentation capacity demands substantial upfront investment in bioreactor infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vegan Supplements Market |
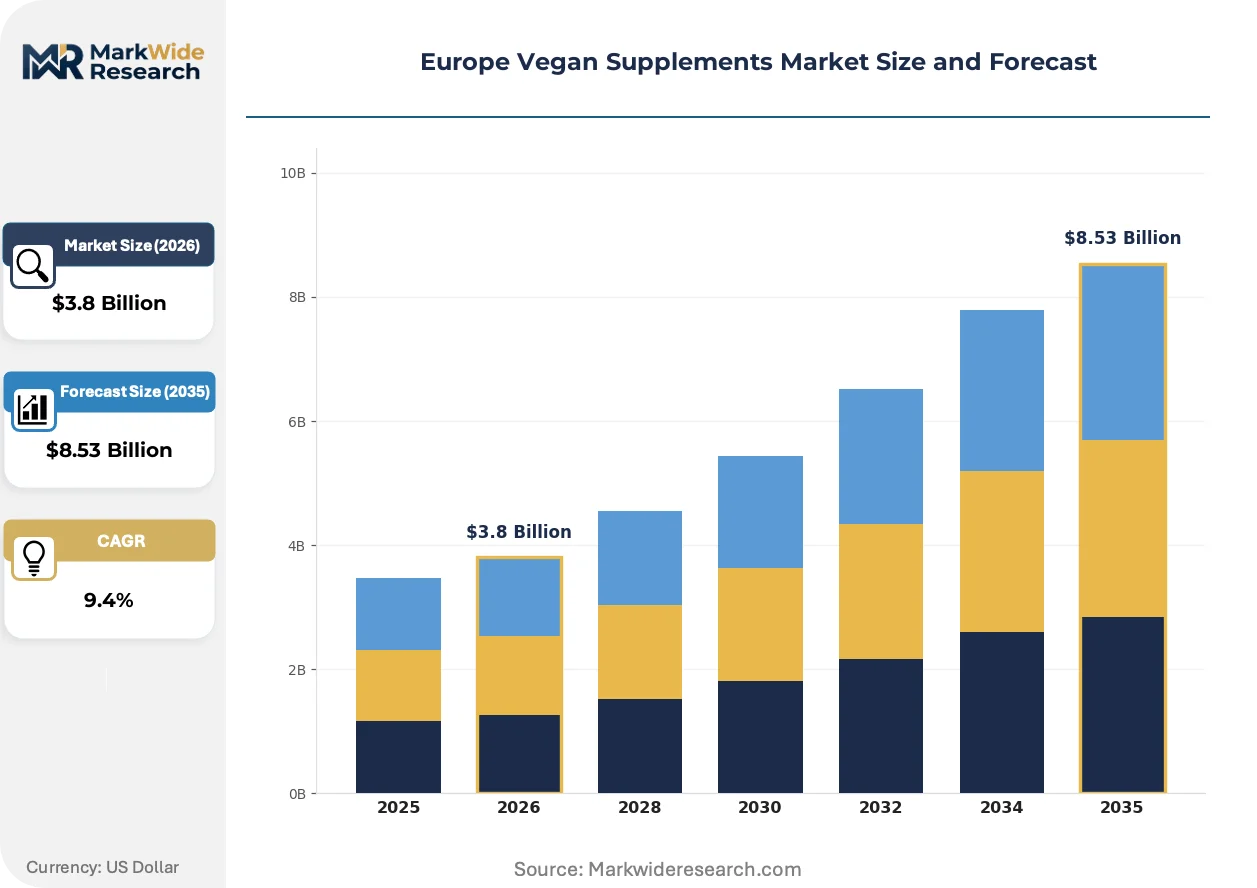
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Vitamins, Minerals, Herbal Extracts End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Seniors Form: Pills, Powders, Gummies, Liquids Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | Holland & Barrett, Sylphar N.V. (Nutravita Limited), Glanbia Plc, Herbalife Nutrition, GreenVits, Vanatari International GmbH, Vitamin Buddy Limited, Nestle SA, Kerry Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vegan Supplements Market Shifts & Advancements
Formulation science and distribution architecture are undergoing simultaneous transformation as brands navigate tightening sustainability mandates and shifting consumer access preferences.
Fermentation-based nutrient synthesis is digitizing quality control protocols through real-time metabolite monitoring and AI-driven bioprocess optimization. Contract manufacturers in the Netherlands and Denmark are adopting these platforms to reduce batch-to-batch variability. This convergence is digitizing compliance documentation for EFSA submission packages while compressing development cycles.
REACH sustainability disclosure requirements now mandate supply chain carbon intensity reporting for all synthetic excipients entering European formulations. Manufacturers must document cradle-to-gate emissions for binders, coatings, and flow agents previously treated as commodity inputs. Small and mid-sized brands lacking lifecycle assessment capabilities are outsourcing compliance to specialized consultancies in Germany and Belgium.
Subscription-based replenishment is displacing supermarket impulse purchases among core vegan supplement consumers. Dutch and British direct-to-consumer platforms leverage algorithmic personalization to reduce churn and increase average order values. This behavioral shift concentrates most visibly among urban millennials in London, Amsterdam, and Berlin who prioritize convenience over in-store browsing.
Europe Vegan Supplements Market Segmentation
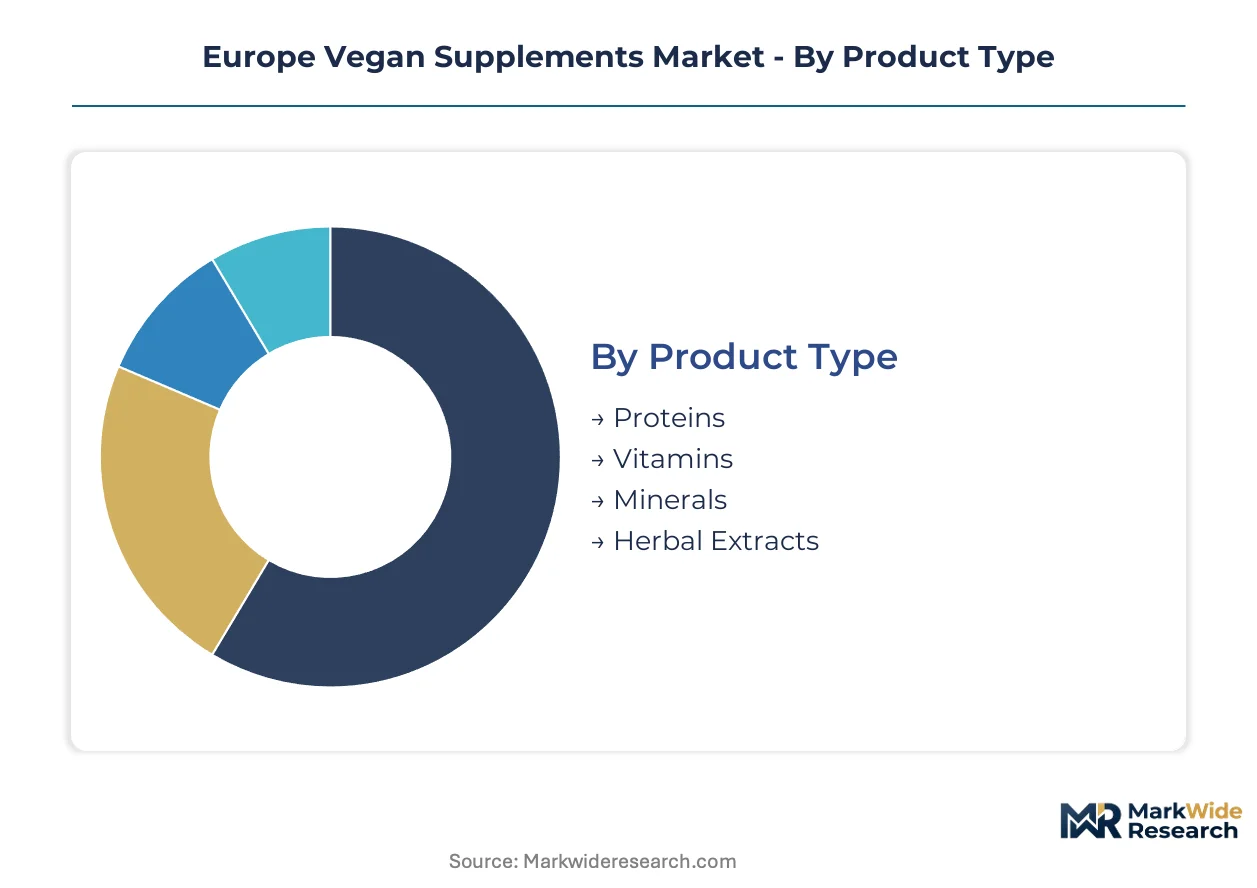
Segmentation in the Europe vegan supplements market reveals distinct demand profiles across consumption occasions, user physiology, and purchase contexts. Manufacturers configure formulation portfolios and channel strategies around these fracture lines to capture margin pools.
Product Type:
Plant-derived nutrient platforms span functional categories from macronutrient replacement to micronutrient fortification and botanical bioactive delivery.
- Proteins:Pea, rice, and fava bean isolates supply complete amino acid profiles through enzymatic hydrolysis and spray-drying. German and British gym chains drive volume through private-label placement in Manchester, Berlin, and Hamburg retail channels constrained by EFSA novel food timelines for emerging legume sources.
- Vitamins:Cultured B12, algal D3, and fermented K2 replace animal-derived equivalents through precision biotechnology. Demand concentrates among health-conscious consumers in Amsterdam and Copenhagen seeking verified bioavailability without synthetic excipients under REACH disclosure mandates.
- Minerals:Chelated iron, zinc, and magnesium utilize amino acid carriers to enhance absorption in plant-based diets. French and Italian consumers prioritize these for menstrual health and bone density support.
- Herbal Extracts:Ashwagandha, turmeric, and adaptogenic blends target stress modulation and recovery. Regulatory complexity around novel botanical claims limits formulation velocity.
The dominant share belongs to Proteins, while Vitamins is closing the gap fastest.
End User:
Physiological requirements and lifestyle intensity shape dosage formulation, delivery format preferences, and price elasticity across distinct consumer cohorts.
- Fitness Enthusiasts:Amateur and recreational athletes pursuing body recomposition and recovery optimization. London and Amsterdam boutique fitness studios drive subscription replenishment of post-workout protein and creatine alternatives.
- Health-Conscious Consumers:Preventive wellness seekers managing energy, immunity, and longevity through daily micronutrient protocols. Berlin and Copenhagen urban professionals exhibit highest subscription retention rates.
- Athletes:Competitive and professional performers requiring batch-tested, contaminant-free formulations for anti-doping compliance. German Olympiastützpunkte and British performance centers mandate third-party certification.
- Seniors:Aging populations addressing sarcopenia, bone density, and cognitive maintenance through bioavailable formats. French and Italian pharmacy channels capture this demographic through clinician recommendation.
Fitness Enthusiasts command the largest addressable base, though Seniors are expanding most quickly as European demographic aging accelerates.
Form:
Delivery technology selection balances bioavailability engineering, consumer convenience, and manufacturing scalability across European production hubs.
- Powders:Bulk protein and meal-replacement formats enabling dose customization and flavor stacking. Dutch contract manufacturers dominate spray-drying capacity for pea and rice isolates.
- Gummies:Pectin-based chewables replacing gelatin through starch molding and moisture-control engineering. British and German brands lead pectin stabilization expertise, though formulation talent scarcity constrains expansion.
- Pills:Compressed tablets and hard-shell capsules for micronutrient precision dosing. Portuguese algal oil encapsulation clusters supply DHA and EPA in vegan shells.
- Liquids:Liposomal and emulsified formats for enhanced absorption of fat-soluble vitamins. Premium positioning in Scandinavian markets offsets higher packaging costs.
Powders retain volume leadership, while Gummies gains share fastest as pectin technology matures and adult palatability preferences shift.
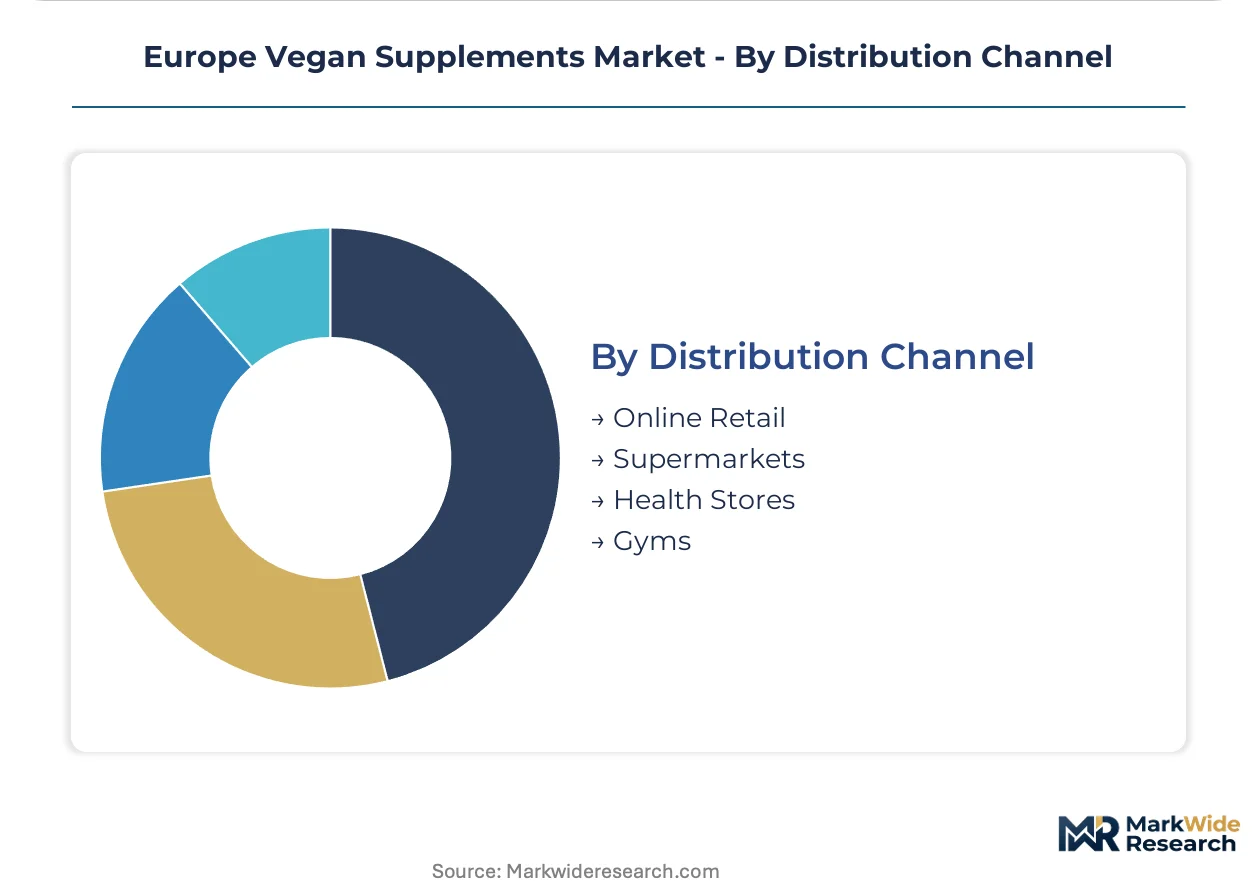
Distribution Channel:
Channel selection determines margin capture, customer acquisition economics, and regulatory exposure across European retail architectures.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators leveraging algorithmic personalization and subscription mechanics. Dutch and British operators compress customer acquisition costs through influencer partnerships and replenishment automation.
- Health Stores:Specialist brick-and-mortar networks providing tactile evaluation and staff consultation. Holland & Barrett's British high street presence sustains omnichannel loyalty through click-and-collect integration.
- Supermarkets:Mass-market penetration through dedicated plant-based aisles and promotional placement. German and French retailers expand shelf space under EU Green Deal sourcing visibility requirements.
- Gyms:Point-of-consumption impulse and replenishment through in-house retail and vending. Berlin and Hamburg chains integrate private-label protein into membership ecosystems.
Online Retail holds the dominant position, though Health Stores maintains fastest expansion through experiential differentiation and subscription bridge programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish and Romanian buyers exhibit the highest price elasticity in Eastern Europe, while Scandinavian consumers in Copenhagen and Stockholm accept premium positioning for fermented vitamin platforms and algal oil formulations.
Germany
Berlin's boutique fitness studios and Hamburg's gym chains drive subscription replenishment of pea protein isolates and creatine alternatives. The country's Apotheken channel expansion mandates clinician-trusted plant-based nutrition sections under national pharmacy regulations. Bavaria's precision fermentation clusters near Munich supply cultured B12 to contract manufacturers across the Rhine corridor.
United Kingdom
London's urban millennials and Manchester's health-conscious professionals sustain the highest direct-to-consumer subscription retention rates for algorithmically personalized micronutrient protocols. EFSA novel food pathways constrain speed-to-market for emerging legume protein sources entering British formulations. Holland & Barrett's high street network anchors omnichannel loyalty through integrated click-and-collect infrastructure.
France
Parisian preventive wellness seekers and Lyon-based aging populations prioritize bioavailable mineral chelates for bone density and menstrual health support. The national sustainability labeling scheme creates first-mover advantage for carbon-documented supply chains under France's environmental certification framework. Provence-Alpes-Côte d'Azur hosts algal cultivation pilots supplying DHA precursors to encapsulation specialists.
Netherlands
Amsterdam's direct-to-consumer platforms and Rotterdam's contract manufacturing hubs compress customer acquisition costs through influencer partnerships and replenishment automation. REACH sustainability disclosure mandates require cradle-to-gate emissions documentation for all synthetic excipients entering Dutch formulations. Eindhoven's bioprocess engineering clusters digitize real-time metabolite monitoring for fermentation quality control.
Poland
Warsaw's emerging health-conscious consumer base and Krakow's limited dedicated vegan supplement retail presence create whitespace for pharmacy channel entry. The country's national food safety regulator enforces labeling standards for novel plant protein sources entering Polish formulations. Silesian manufacturing zones attract toll processing contracts from Western European brands seeking cost-competitive pectin-based gummy production.
Europe Vegan Supplements Market Competitive Landscape
Specialist retailers and diversified nutrition conglomerates split the market into distinct competitive spheres with divergent margin capture mechanisms. The vendor base clusters around three strategic archetypes: brick-and-mortar specialists with omnichannel loyalty programs, diversified ingredient suppliers with captive fermentation capacity, and direct-to-consumer platforms with algorithmic personalization engines. Dominant competitive moves include backward integration into pea protein isolate production and strategic partnerships with precision fermentation technology providers.
Within the diversified nutrition tier, Glanbia Plc and Kerry Group occupy positions as ingredient platform providers to European contract manufacturers, while Holland & Barrett exemplifies the brick-and-mortar specialist archetype with sustained high street presence. Nestle SA represents the multinational conglomerate vector pursuing portfolio diversification into plant-based nutrition categories.
| Leading Market Players |
|---|
| Holland & Barrett |
| Sylphar N.V. (Nutravita Limited) |
| Glanbia Plc |
| Herbalife Nutrition |
| GreenVits |
| Vanatari International GmbH |
| Vitamin Buddy Limited |
| Nestle SA |
| Kerry Group |
| Others |
Supply & Pricing Matrix
EFSA novel food authorization timelines extending 18-24 months for algae-derived ingredients compress margin flexibility across formulation tiers while concentrating procurement power among manufacturers with captive fermentation infrastructure. This regulatory chokepoint widens pricing spreads between premium certified products and commodity-grade alternatives while reshaping supplier selection criteria toward vertically integrated producers.
Pricing Analysis
Subscription replenishment revenue drives lifetime value for direct-to-consumer platforms serving Berlin and London urban millennials. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified formulations with carbon-documented supply chains from uncertified alternatives. Cost compression in economy tiers intensifies as Ukrainian and Canadian yellow pea harvest volatility feeds input price uncertainty. Health-conscious consumers in Amsterdam and Copenhagen exhibit lowest price sensitivity, while Polish and Romanian buyers in emerging markets demand value positioning.
Supply Chain Analysis
Dutch and Danish contract manufacturers hold dominant fermentation capacity for cultured vitamin B12 and algal omega-3 production. Raw material sourcing draws from Portuguese algal cultivation clusters, Bavarian precision fermentation facilities, and Ukrainian-Canadian yellow pea protein isolate suppliers. Single-source vulnerability concentrates in algal DHA production limited to Portugal and southern France. Distribution runs through direct-to-consumer platforms, German Apotheken networks, and British high street health stores with omnichannel integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe vegan supplements market sits at a post-pandemic wellness cyclical recovery phase driven by sustained gym culture penetration and preventive health protocol normalization among urban professionals.
For Market Incumbents: Harden supply chain resilience through backward integration into pea protein isolate production and captive precision fermentation capacity near Munich or Eindhoven. Invest in dual V-Label and Vegan Society certification to extend competitive moats against emerging private-label entrants from German gym chains and British supermarket operators. For New Entrants and Emerging Players: Pursue whitespace in Polish and Romanian pharmacy channels where dedicated vegan supplement retail presence remains limited. Target Warsaw and Krakow health-conscious consumers through clinician-trusted positioning in Apotheken-format entry. Leverage Silesian toll manufacturing zones for cost-competitive pectin-based gummy production serving Western European brands. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified ingredient platforms with captive biotechnology infrastructure. Long-term viability over the next decade hinges on fermentation-based nutrient synthesis capabilities and EFSA regulatory navigation expertise. Monitor EFSA novel food authorization velocity as the critical inflection signal for formulation pipeline expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Bavarian and Eindhoven bioprocess clusters enable cost-competitive cultured B12 and algal oil production. |
| Direct-to-Consumer Platform Integration | Amsterdam and London operators compress customer acquisition costs through algorithmic personalization engines. |
| Dual Certification Investment | Simultaneous V-Label and Vegan Society accreditation extends product launch timelines but secures premium positioning. |
| Pharmacy Channel Penetration | German Apotheken expansion capitalizes on clinician trust for aging and preventive wellness demographics. |
| Eastern European Distribution Buildout | Polish and Romanian retail whitespace offers first-mover advantage before Western brand saturation accelerates. |
Research Methodology
Operator-level perspectives from formulation scientists at Dutch contract manufacturers, procurement leads at German gym chain private-label divisions, regulatory affairs specialists navigating EFSA novel food pathways, and category buyers at British health store networks anchored the qualitative base. Secondary validation drew from EFSA novel food authorization databases, REACH sustainability disclosure filings, EU Green Deal Farm to Fork strategy documentation, and customs records tracking yellow pea protein isolate trade flows. Bottom-up demand modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing around regulatory authorization timelines, input cost volatility, and subscription retention rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, end user physiology, delivery form technology, and distribution channel architecture. CAGRs derived from segment-level growth trajectory analysis incorporating precision fermentation cost curves and direct-to-consumer penetration saturation curves.
Sensitivities concentrate around EFSA novel food approval velocity, Ukrainian-Canadian pea harvest cycles, and algal cultivation yield variability. Forecasts reflect documented assumptions on regulatory harmonization and consumer subscription behavior stability. Quarterly review of EFSA authorization queue depth, REACH disclosure compliance rates, and direct-to-consumer churn metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
North America Beta-Glucan Market