
 Vitamins Gummies Market | 2026-2036
Vitamins Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamins Gummies Market Analysis
Multi-source ingredient procurement is shifting toward vertically integrated gelatin and pectin supply chains as manufacturers seek cost stability. Bayer AG leverages captive botanical sourcing networks across temperate growing regions. Church & Dwight anchors North American production capacity through dedicated contract manufacturing partnerships. Pfizer Inc. competes on pharmaceutical-grade quality certifications that differentiate its gummy portfolio from conventional nutraceuticals.
Vitamins gummies are chewable confectionery-delivery vehicles containing micronutrients suspended in hydrocolloid matrices, typically gelatin or pectin, formed through starch mogul or depositing processes at controlled temperatures to preserve thermolabile actives like vitamin C and D. Their primary commercial purpose centers on improving compliance among populations averse to tablets or capsules, particularly children and seniors with dysphagia concerns. Multivitamins and immune support formulations dominate current revenue pools, while sleep aids with melatonin represent the fastest-growing product type as stress-related wellness spending expands. Adults constitute the largest end-user segment by volume, though pregnant women command premium pricing due to stringent folate and DHA fortification requirements.
FDA dietary supplement GMPs, EFSA health claims regulations, and WHO nutrient reference values collectively govern permissible vitamin concentrations and label assertions across major markets. Compliance with evolving maximum daily limits for fat-soluble vitamins shapes formulation architecture and restricts market access for non-compliant imports. Stakeholders must monitor pending harmonization between Codex Alimentarius standards and national pharmacopeias to anticipate reformulation costs and export eligibility shifts.
Market Dynamics
Clean-label formulation mandates and pediatric compliance requirements are compressing gelatin supply chains while accelerating pectin adoption across manufacturing networks. This structural pivot is forcing simultaneous reformulation of texture profiles and stability testing protocols.
Growth Catalysts
- FDA Dietary Supplement GMPs:Pharmaceutical-grade certification requirements are pulling contract manufacturers toward controlled-environment production, expanding addressable market for certified gummy producers.
- Pediatric dysphagia prevalence:Clinical recognition of swallowing difficulties in children is cementing chewable formats as standard-of-care in pediatric nutrition protocols across hospital and retail channels.
- Stress-related wellness spending:Consumer allocation toward sleep and anxiety management is expanding melatonin and adaptogen gummy categories faster than traditional vitamin segments.
Market Restraints
- Gelatin input volatility:Bovine and porcine collagen sourcing disruptions from disease outbreaks and trade restrictions are compressing margin structures for conventional manufacturers.
- Fat-soluble vitamin limits:EFSA and FDA maximum daily limits for vitamins A, D, E, K are constraining formulation flexibility and forcing portfolio simplification.
- Tablet substitution:Effervescent and orally disintegrating tablet formats are capturing price-sensitive consumers seeking lower per-dose costs.
Strategic Opportunities
- Geriatric underpenetration:Japan's aging demographic presents white space for condition-specific formulations targeting sarcopenia and cognitive health with pharmaceutical channel partnerships.
- Plant-based pectin convergence:Citrus fiber extraction advances combined with precision depositing equipment are enabling clean-label positioning at scale.
- D2C subscription models:Personalized nutrition platforms are bypassing traditional retail markup structures while capturing longitudinal consumer data.
Industry Challenges
- Thermolabile active preservation:Vitamin C and probiotic stability through starch mogul processing requires specialized temperature control engineering that extends qualification timelines.
- Cross-jurisdictional label harmonization:Divergent health claim permissions between FDA, EFSA, and China's SAMR are forcing SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamins Gummies Market |
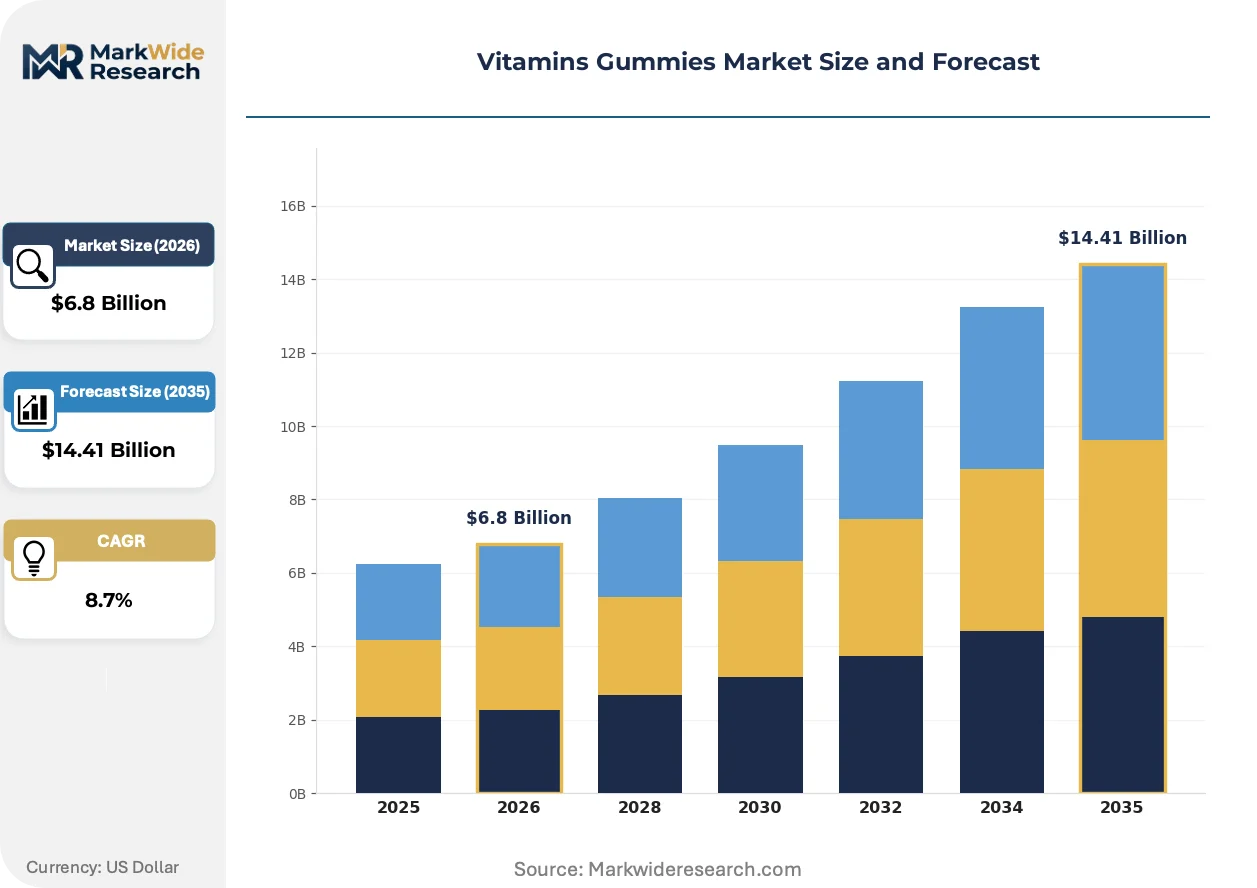
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Omega-3, Sleep Aids, Immune Support Flavor: Cherry, Orange, Grape, Mixed Berry End User: Adults, Children, Pregnant Women, Seniors Distribution Channel: Online, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Bayer AG, Church & Dwight, Amway Corporation, Haleon, Pharmavite, Pfizer Inc., Nature's Bounty, SmartyPants Vitamins, Hero Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamins Gummies Market Emerging Trajectories
Biopolymer matrix engineering and precision dosing hardware are converging to transform gummy manufacturing from batch confectionery toward pharmaceutical-grade continuous processing. This evolution is compressing development cycles while raising technical barriers to entry.
Pectin-carrageenan hybrid gelling systems are rewriting texture and stability benchmarks for plant-based formulations. Pediatric and vegan consumer segments are adopting these alternatives faster than gelatin-dependent legacy portfolios. The shift is compressing conventional gelatin supplier bargaining power while rewarding citrus fiber processors with captive extraction capabilities.
EFSA's evolving health claims substantiation requirements are tightening clinical evidence standards for immune and cognitive benefit assertions. Manufacturers must now commission human intervention studies to maintain label permissions, raising R&D intensity disproportionately for mid-tier players. The sleep and stress category faces the steepest compliance gradient given historical reliance on traditional use claims.
Healthcare practitioner endorsement channels are displacing unassisted retail discovery for prenatal and pediatric segments. Pharmacies and clinician offices are capturing margin through white-label partnerships with verified manufacturers. Germany's pharmacy-dominant distribution structure exemplifies this shift, where Apotheken consultation requirements filter product assortment toward clinically validated portfolios.
Vitamins Gummies Market Segmentation
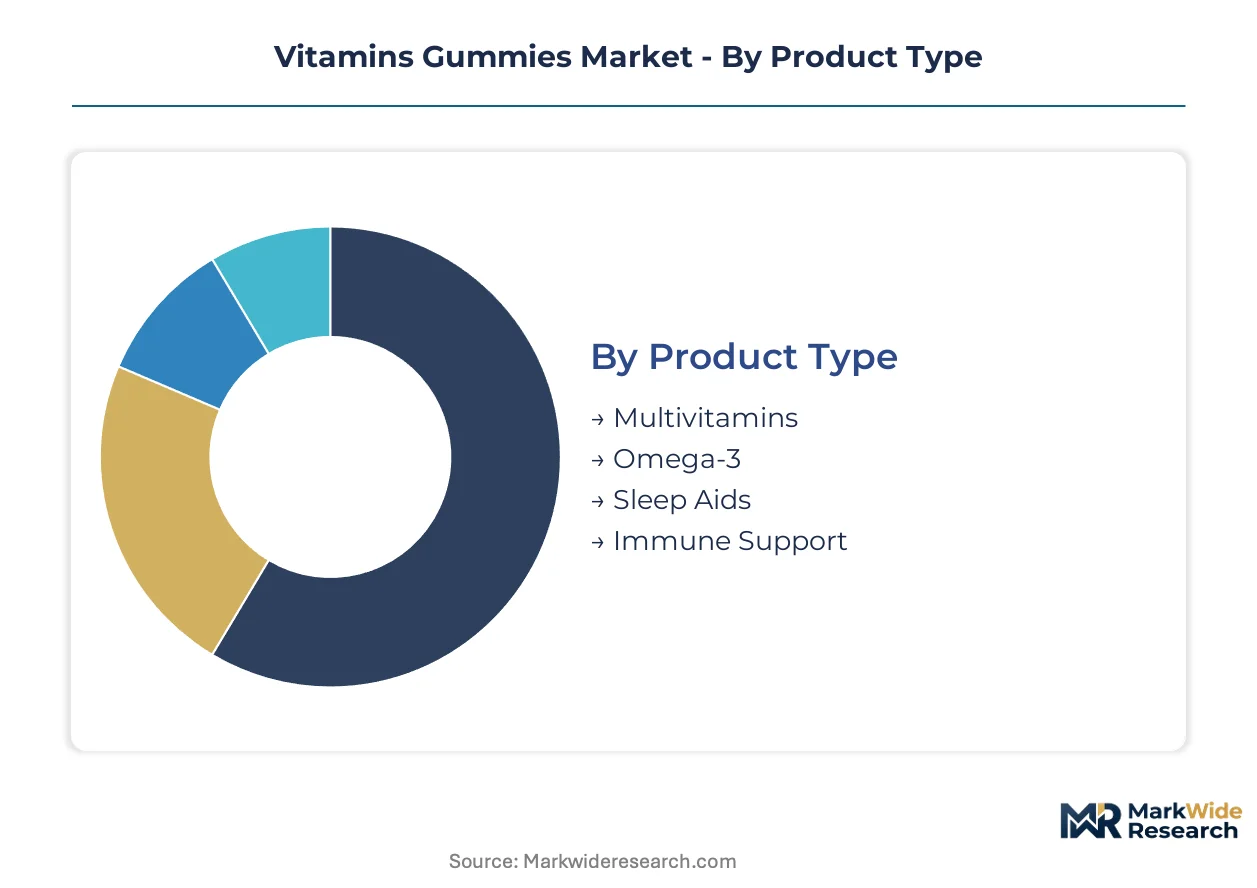
Segmentation in vitamins gummies reveals divergent formulation priorities across consumer life stages and purchasing contexts. Manufacturers must balance thermolabile active preservation with palatability engineering to capture distinct volume and premium tiers.
Product Type:
Volume concentration clusters in mass-market multivitamins, while premium pricing attaches to condition-specific formulations with clinical substantiation requirements.
- Multivitamins:Broad-spectrum micronutrient matrices deliver daily reference values across water-soluble and fat-soluble vitamins in single-dose formats. Demand concentrates in the United States through mass retail channels where household penetration exceeds other developed markets, constrained by EFSA and FDA maximum daily limits that force portfolio standardization.
- Sleep Aids:Melatonin-infused gummies with magnesium and L-theanine target stress-related wellness spending. Germany's pharmacy-dominant Apotheken channel captures premium distribution for clinically validated sleep formulations, with SAMR registration requirements creating entry barriers for imported SKUs in China.
- Omega-3:Algal and fish oil emulsions suspended in pectin matrices deliver EPA/DHA without capsule aversion.
- Immune Support:Vitamin C, zinc, and elderberry combinations require specialized temperature control during starch mogul processing.
Mature deployment sits with Multivitamins. Newer deployment is concentrated in Sleep Aids.
Flavor:
Palatability engineering directly determines pediatric compliance rates and geriatric repeat purchase behavior across markets.
- Cherry:Anthocyanin-derived colorants and natural flavor systems dominate pediatric formulations. United States retail shelves allocate disproportionate shelf space to cherry variants, with clean-label mandates from California's Proposition 65 enforcement compressing artificial additive formulations.
- Mixed Berry:Blended profiles mask mineral off-notes in prenatal iron-fortified gummies. China's tier-one cities command premium positioning for mixed berry SKUs with reduced sugar content, responding to SAMR nutrition labeling requirements that highlight added sugars.
- Orange:Citrus-derived vitamin C synergy enables natural positioning claims.
- Grape:Synthetic color alternatives face EFSA scrutiny under evolving food additive assessments.
Volume leadership resides with Cherry. Premium differentiation concentrates in Mixed Berry.
End User:
Dysphagia prevalence and swallowing difficulty recognition reshape format preferences across demographic boundaries.
- Adults:Working-age consumers drive baseline volume through convenience-seeking behavior and subscription platform adoption. Germany's statutory health insurance reimbursement discussions for specific vitamin deficiencies create channel arbitrage opportunities between pharmacy and direct-to-consumer models.
- Pregnant Women:Folate and DHA fortification requirements trigger pharmaceutical-grade quality certifications and clinician endorsement protocols. The United States prenatal segment commands the steepest pricing premiums due to ACOG guideline alignment and pharmacy benefit manager formulary positioning.
- Children:Pediatric dysphagia protocols in Japanese hospital systems cement chewable formats as standard-of-care.
- Seniors:Sarcopenia-targeted formulations with vitamin D and protein co-delivery represent underdeveloped white space.
Revenue concentration favors Adults. Margin expansion concentrates in Pregnant Women.
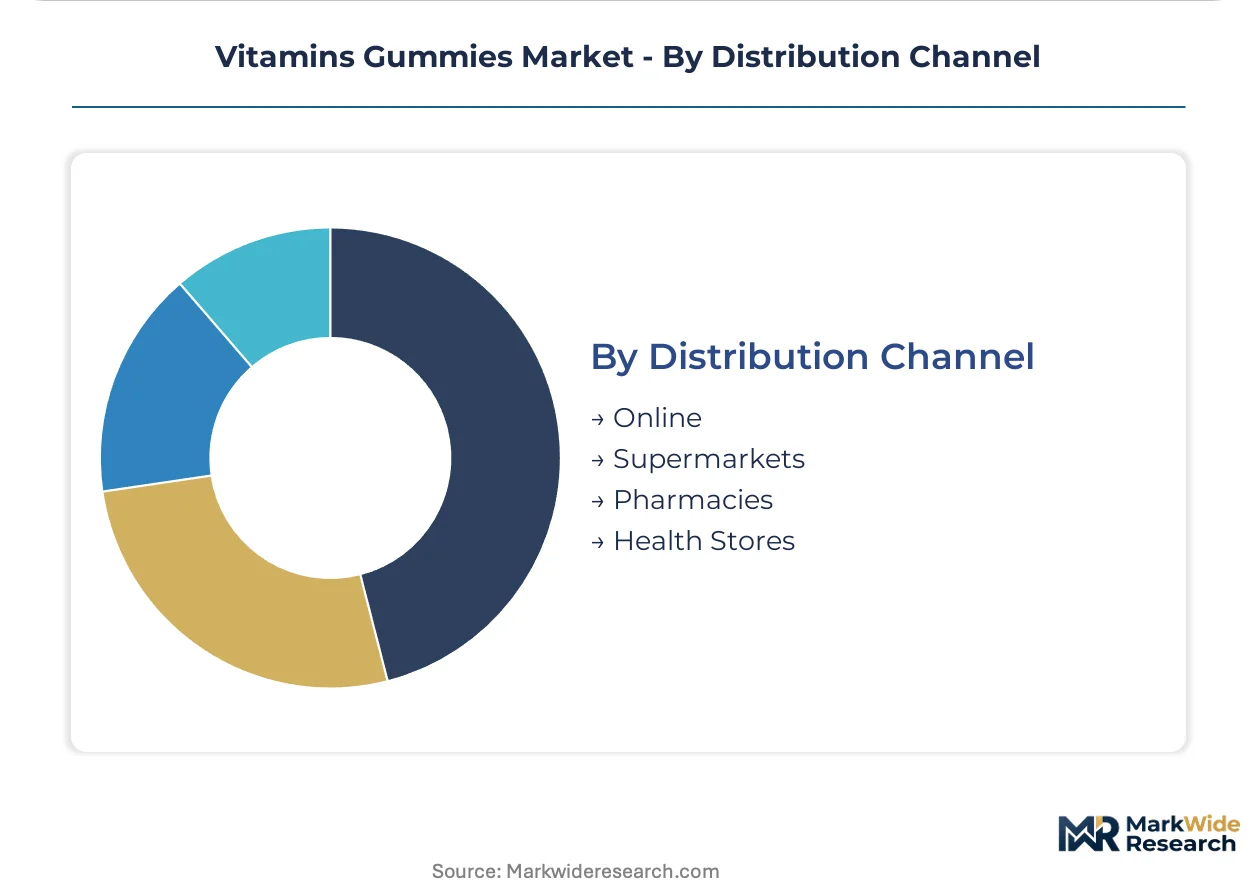
Distribution Channel:
Channel selection determines regulatory exposure and consumer education investment requirements.
- Pharmacies:Consultation requirements in Germany's Apotheken system filter assortment toward clinically validated portfolios with EFSA-compliant health claims. Pharmacist endorsement commands 15-25% price premiums over unassisted retail discovery for prenatal and pediatric segments.
- Online:Direct-to-consumer platforms bypass traditional retail markup structures while capturing longitudinal adherence data. China's cross-border e-commerce channels enable SAMR-registered imports to reach tier-two and tier-three cities without brick-and-mortar distribution.
- Supermarkets:Mass-market multivitamin volume concentrates in club store formats with private-label competition.
- Health Stores:Specialty retailers curate clean-label and vegan-certified assortments with trained staff consultation.
Regulatory rigor peaks at Pharmacies. Digital penetration expands fastest through Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gelatin and pectin feedstock localities in the United States, Germany, and China anchor the vitamins gummies industry's geographic footprint, with each market shaped by distinct regulatory architectures and consumer compliance preferences.
United States
Pediatric dysphagia protocols and subscription platform adoption drive volume concentration. FDA dietary supplement GMPs enforce pharmaceutical-grade certification requirements that filter contract manufacturer eligibility. New Jersey and California host dense clusters of gummy production facilities serving mass retail and direct-to-consumer channels.
Germany
Pharmacy-dominant distribution through Apotheken channels commands premium pricing for clinically validated formulations. EFSA health claims regulations mandate human intervention studies for immune and cognitive benefit assertions. Bavaria's pharmaceutical manufacturing corridor concentrates pectin-based clean-label production capacity.
China
Tier-one city consumers prioritize reduced-sugar positioning and cross-border e-commerce access to imported SKUs. SAMR registration requirements create entry barriers for foreign manufacturers seeking brick-and-mortar distribution. Yangtze River Delta industrial zones house precision depositing equipment manufacturers serving domestic gummy producers.
Japan
Geriatric sarcopenia-targeted formulations represent underdeveloped white space as aging demographics expand addressable demand. PMDA consultation requirements shape pharmaceutical channel partnerships for condition-specific products. Kanto region hospitals cement chewable formats as standard-of-care in pediatric nutrition protocols.
United Kingdom
Clean-label vegan certification drives pectin adoption faster than gelatin-dependent legacy portfolios. MHRA borderline product classifications determine whether gummies register as foods or medicines. London-based direct-to-consumer platforms capture longitudinal adherence data through personalized nutrition subscriptions.
Vitamins Gummies Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit starch mogul lines for pharmaceutical-grade continuous processing. The vendor base organizes around three tiers: multinational pharmaceutical conglomerates with captive botanical networks, mid-sized nutraceutical specialists with pharmacy channel partnerships, and agile direct-to-consumer platforms with personalized formulation engines. Strategic differentiation clusters on clean-label certification acquisition and healthcare practitioner endorsement protocols. M&A activity targets pectin extraction capabilities and precision dosing hardware suppliers.
Among pharmaceutical-origin conglomerates, Bayer AG and Pfizer Inc. occupy positions defined by pharmaceutical-grade quality certifications and regulatory compliance infrastructure. Church & Dwight exemplifies the North American contract manufacturing partnership model, anchoring production capacity through dedicated supplier relationships rather than captive facilities. These three entities represent divergent archetypes: integrated pharmaceutical heritage, outsourced manufacturing scale, and hybrid commercial structures.
| Leading Market Players |
|---|
| Bayer AG |
| Church & Dwight |
| Amway Corporation |
| Haleon |
| Pharmavite |
| Pfizer Inc. |
| Nature's Bounty |
| SmartyPants Vitamins |
| Hero Nutritionals |
| Others |
Supply Flow & Price Mechanics
Pectin feedstock costs from citrus fiber processors cascade through three distinct pricing tiers, with pharmaceutical-grade certifications commanding premiums over mass-market multivitamin formats as gelatin supply disruptions compress margin structures for conventional manufacturers.
Pricing Analysis
Warranty-backed quality certifications separate pharmaceutical-grade gummy producers from unverified contract manufacturers, with FDA dietary supplement GMP compliance and EFSA health claims substantiation functioning as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and clinician endorsement protocols. Pricing pressure stems from bovine and porcine collagen sourcing volatility, with tablet substitution capturing price-sensitive consumers seeking lower per-dose costs. Subscription platform adopters exhibit lowest price sensitivity, while supermarket mass-market buyers face highest cost consciousness.
Supply Chain Analysis
Direct-to-consumer channels handle personalized nutrition platform demand, while pharmacy-dominant distribution in Germany's Apotheken system filters toward clinically validated portfolios. Raw material sourcing concentrates in the United States, Germany, and China, with citrus fiber extraction capabilities and precision depositing equipment manufacturers anchoring upstream capacity. Gelatin and pectin hydrocolloid matrices, thermolabile active ingredients, and starch mogul processing equipment constitute critical input dependencies. Single-source vulnerability in bovine collagen supply chains from disease outbreak regions threatens formulation continuity for legacy manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA dietary supplement GMP certification functions as a cost-of-compliance barrier, with pharmaceutical-grade quality infrastructure creating sustainable moats against unverified import competition.
For Market Incumbents: Anticipate pectin-carrageenan hybrid formulation adoption accelerating as clean-label mandates compress gelatin-dependent portfolios. Backward integration into citrus fiber extraction capabilities secures input cost stability against volatile collagen markets. Capacity addition in Bavaria's pharmaceutical manufacturing corridor reinforces European pharmacy channel positioning against mid-tier nutraceutical specialists.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms to bypass traditional retail markup structures and capture longitudinal adherence data. Japan's geriatric sarcopenia-targeted formulations represent the most penetrable white space, with PMDA consultation requirements filtering competition toward established pharmaceutical partnerships. White-label manufacturing for healthcare practitioner endorsement channels offers lowest customer acquisition friction.
For Investors and Strategic Acquirers: SAMR registration completion for imported SKUs is the leading indicator that cross-border e-commerce penetration into China's tier-two and tier-three cities has achieved regulatory escape velocity. Long-term viability favors acquisition targets with captive pectin extraction capabilities and precision dosing hardware integration. Watch for EFSA health claims enforcement actions against traditional use assertions as the signal for R&D intensity escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Extraction Capability Acquisition | Citrus fiber captive supply insulates against gelatin price volatility and enables clean-label positioning. |
| Pharmaceutical-Grade Certification Investment | FDA GMP compliance differentiates portfolios from unverified imports and commands pharmacy channel premiums. |
| Direct-to-Consumer Platform Launch | Subscription models bypass retail markups while capturing longitudinal consumer adherence data for formulation refinement. |
| Healthcare Practitioner Endorsement Protocol | Clinician validation in Germany's Apotheken system filters competition toward clinically substantiated portfolios. |
| Precision Depositing Equipment Integration | Continuous processing technology from Yangtze River Delta manufacturers compresses development cycles for thermolabile actives. |
Methodological Framework
Multi-period observation of SAMR registration timelines, EFSA health claims enforcement patterns, and pectin-gelatin price spreads anchored the trend analysis, supplemented by interviews with gummy manufacturing plant managers, pharmacy procurement leads at German Apotheken, regulatory affairs specialists, and direct-to-consumer platform operators. Secondary validation drew from FDA dietary supplement GMP inspection records, EFSA substantiation databases, customs trade data for hydrocolloid imports, and SEC filings of publicly traded nutraceutical manufacturers. Bottom-up volume modeling across product type, flavor profile, end-user demographic, and distribution channel segments triangulated against top-down market sizing.
Input-output matrices mapped raw material feedstock flows through starch mogul and precision depositing processing stages to downstream channel pricing tiers across the analysis window. Segmentation dimensions modeled included product formulation type, certification grade tier, end-user life stage, and regional regulatory cluster. CAGRs were derived from regression analysis of historical volume trajectories adjusted for pediatric dysphagia protocol adoption rates and stress-related wellness spending shifts. Forecast inputs incorporated pectin adoption curves, clinician endorsement channel penetration, and cross-border e-commerce regulatory evolution.
Raw material supply disruptions, regulatory harmonization failures between Codex Alimentarius and national pharmacopeias, and thermolabile active degradation breakthroughs are the dominant revision risks requiring scenario modeling. Forecasts reflect documented assumptions regarding clean-label mandate timelines and pharmacy channel reimbursement discussions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Activated Charcoal Supplement Market