
 Global Dispensing Systems Market | 2026-2036
Global Dispensing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dispensing Systems Market Analysis
Capital-intensity divergence between automated electromechanical platforms and manual dispensing equipment is bifurcating competitive strategy across the sector. Nordson Corporation leverages precision fluid control technologies to dominate industrial adhesive and coating applications. Graco Inc. anchors its position through high-pressure hydraulic systems serving construction and automotive end users. AptarGroup Inc. differentiates via pump and valve specialization for cosmetics and pharmaceutical packaging, sustaining premium positioning through material science expertise.
Dispensing systems integrate mechanical actuators, flow-control valves, and programmable logic controllers to deliver measured quantities of liquids, gels, or powders with repeatability tolerances often below one percent. These systems serve industrial automation, laboratory accuracy, and consumer convenience across manufacturing and commercial environments. Pump systems occupy the largest installed base due to their versatility across viscosity ranges and end-user sectors. Electromechanical technology is capturing the fastest expansion as manufacturers replace pneumatic and manual alternatives for precision and traceability. Food and beverage applications command substantial volume, though pharmaceutical end users generate higher margin pools driven by FDA validation requirements and cleanroom compatibility standards.
FDA 21 CFR Part 11 and EU MDR frameworks mandate electronic record-keeping and device traceability, compelling suppliers to embed compliance into system architecture. EPA emissions guidelines and REACH substance restrictions further constrain material selection for chemical and industrial dispensing applications. Stakeholders must monitor evolving ISO 13485 quality management requirements alongside state-level pharmaceutical manufacturing regulations in the United States and Germany. The convergence of regulatory stringency and automation economics will determine which technology platforms achieve scalable deployment across regulated industries.
Market Dynamics
Electromechanical dispensing platforms are decomposing pneumatic system dominance across pharmaceutical and food processing lines, compressing total cost of ownership while forcing suppliers to rearchitect service models around predictive maintenance and remote diagnostics.
Growth Catalysts
- Pharmaceutical manufacturing automation:FDA 21 CFR Part 11 mandates for electronic batch records drive replacement of manual dispensing stations with validated electromechanical systems across sterile injectable production.
- REACH substance restrictions:ECHA regulations on perfluorinated compounds compel material science investments in fluoropolymer-free seals and gaskets, opening premium positioning for compliant European suppliers.
- China domestic capacity expansion:NMPA localization requirements for medical device components accelerate captive dispensing system production for biologics fill-finish operations.
Market Restraints
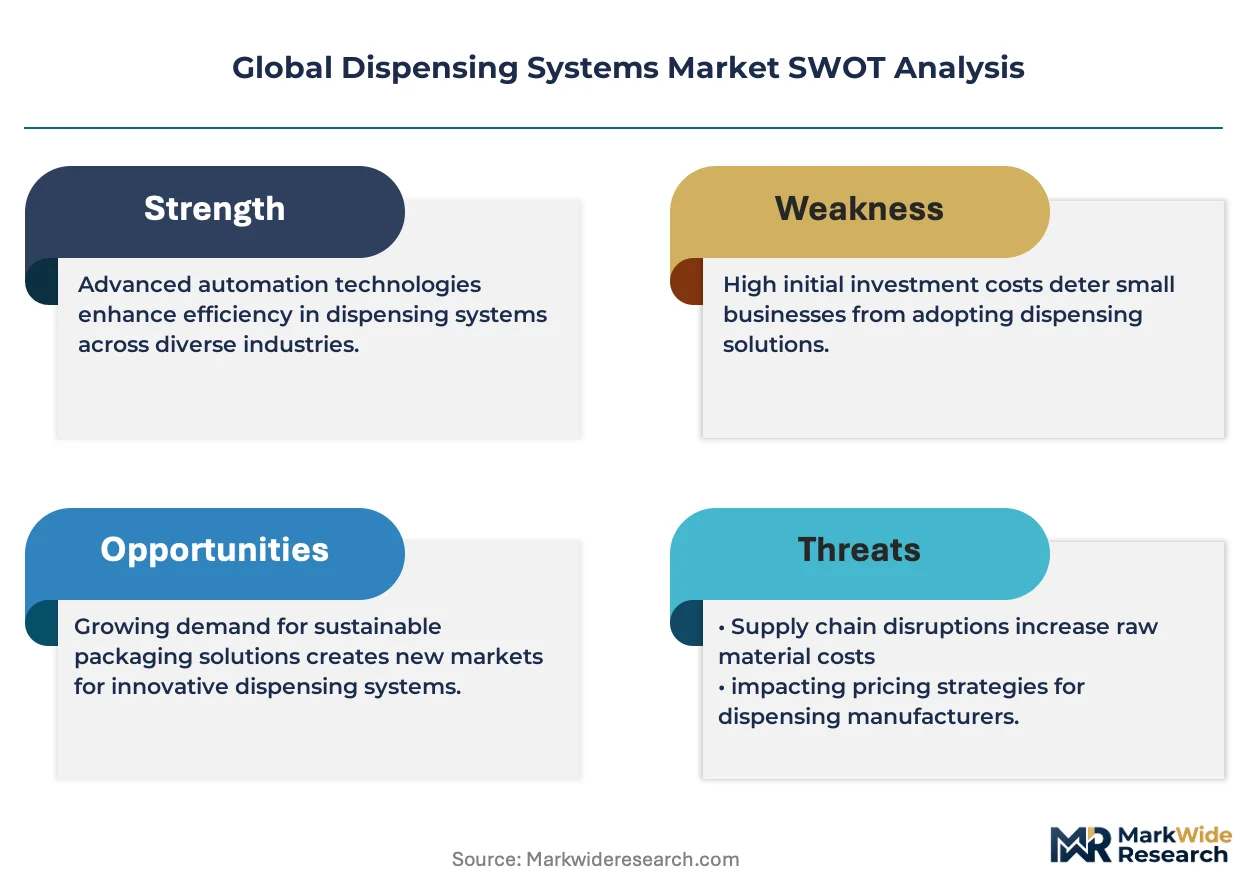
- Stainless steel alloy volatility:Nickel and molybdenum price swings compress margin predictability for hygienic pump manufacturers serving dairy and beverage sectors.
- Precision sensor supply concentration:German and Japanese flow meter specialists control 80% of Coriolis mass flow technology, creating single-source vulnerability for high-accuracy pharmaceutical dispensing.
- Cleanroom validation timelines:ISO 14644-1 certification cycles extending 18-24 months delay revenue recognition for new pharmaceutical installations.
Strategic Opportunities
- India contract manufacturing expansion:CDSCO streamlined medical device regulations and PLI scheme incentives attract dispensing system deployment for export-oriented pharmaceutical packaging.
- Cell and gene therapy fill-finish:Ultra-low volume precision dispensing below 50 microliters opens specialized system architecture for personalized medicine production.
- Digital twin integration:Convergence of PLC-based dispensing with IIoT analytics enables outcome-based service contracts tying vendor compensation to uptime metrics.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineers combining fluid dynamics, embedded software, and regulatory documentation command 40% wage premiums, constraining R&D scaling.
- Legacy system integration friction:Brownfield pharmaceutical facilities running 1990s-era SCADA architectures resist seamless connectivity with modern electromechanical dispensing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dispensing Systems Market |
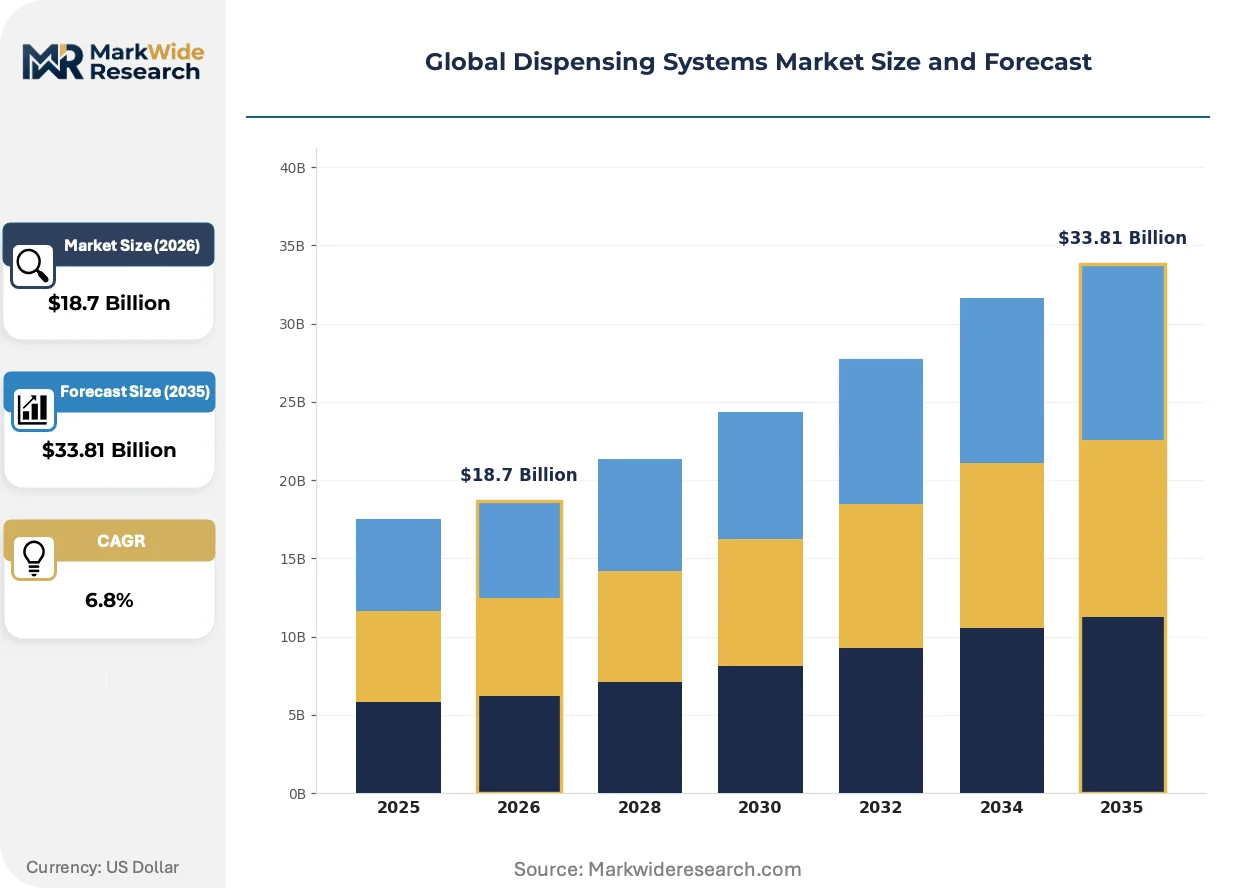
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pump Systems, Valves, Nozzles, Dispensers Technology: Electromechanical, Pneumatic, Hydraulic, Manual End User: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics Application: Industrial Automation, Household Use, Laboratory, Retail |
| Companies Covered | McKesson Corporation, Henkel, Nordson Corporation, Swisslog Healthcare, Graco Inc., Omnicell, 3M, AptarGroup Inc., Becton Dickinson (BD), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dispensing Systems Market Emerging Trajectories
Precision fluid handling architectures are fragmenting into modular, software-defined platforms that separate mechanical actuation from control intelligence, enabling remote reconfiguration without hardware replacement.
Positive displacement pump technology is decomposing traditional peristaltic dominance in biopharmaceutical dispensing. Single-use diaphragm pumps with integrated pressure sensors eliminate tubing fatigue failure modes. Aseptic fill-finish operators in Germany and Switzerland are adopting these systems for high-value monoclonal antibody production. The technology is decomposing aftermarket tubing revenue pools while shifting supplier economics toward disposable pump head subscriptions.
EU MDR technical documentation requirements are compressing product lifecycle management architectures for dispensing system manufacturers. Annex I general safety and performance obligations now mandate clinical evidence for devices contacting pharmaceutical products. French and Italian packaging machinery builders are restructuring quality management systems to accommodate notified body scrutiny. The regulation is accelerating consolidation among subscale European suppliers lacking dedicated regulatory affairs functions.
Buyer concentration among global pharmaceutical contract manufacturers is compressing vendor negotiation leverage. Lonza, Catalent, and Samsung Biologics now specify dispensing system architectures across multi-site networks, forcing equipment suppliers to standardize configurations rather than customize per facility. This pattern is most visible in Singapore and South Korea, where CDMO campus expansions concentrate procurement decisions with single engineering teams.
Global Dispensing Systems Market Segmentation
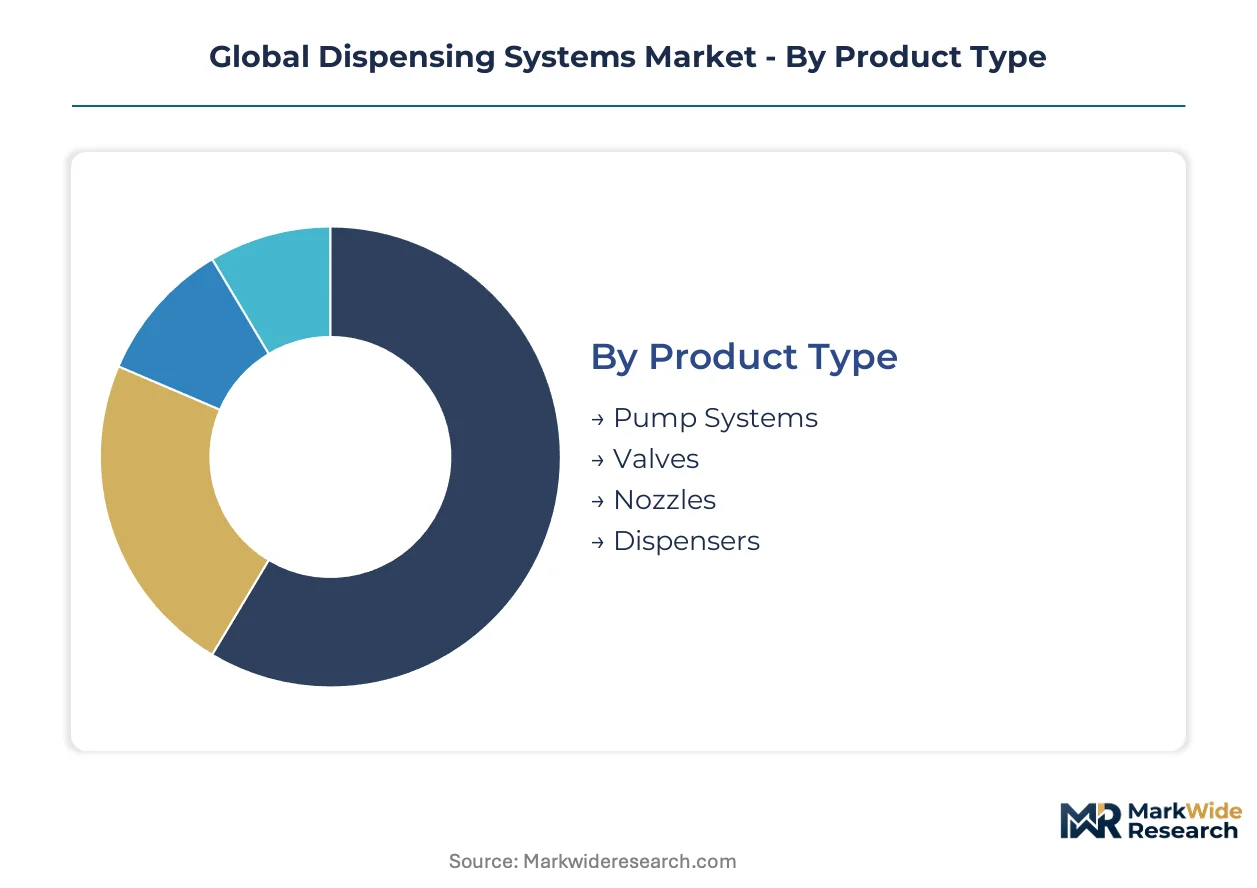
Dispensing system architectures fragment across multiple technical and commercial dimensions, each creating distinct margin pools and competitive barriers. Understanding how product specifications, technology choices, and end-use requirements intersect determines supplier positioning and investment prioritization across the forecast period.
Product Type:
Margin concentration tracks directly to precision requirements and validation intensity, with pharmaceutical-grade systems commanding substantial premiums over industrial commodity alternatives.
- Pump Systems:Positive displacement and peristaltic configurations dominate biopharmaceutical fill-finish operations, where repeatability tolerances below one percent justify capital investment. Demand clusters in Germany and Switzerland for monoclonal antibody production, with FDA 21 CFR Part 11 validation requirements extending replacement cycles and aftermarket service contracts. The dominant share belongs to Pump Systems, while Dispensers are closing the gap fastest.
- Valves:Proportional solenoid and piezoelectric actuation technologies enable micro-liter dosing accuracy for cell and gene therapy applications. Swiss and German CDMOs specify valve architectures across multi-site networks, standardizing configurations rather than customizing per facility.
- Nozzles:Atomizing and jet-dispensing geometries serve coating and adhesive applications in automotive and electronics manufacturing.
- Dispensers:Manual and semi-automatic units address laboratory and retail environments where throughput requirements remain modest.
Supplier economics bifurcate between validated pharmaceutical-grade platforms and industrial commodity alternatives.
Technology:
Cost tier stratification separates capital-intensive automated platforms from labor-dependent manual alternatives, with electromechanical systems displacing legacy pneumatic infrastructure across regulated industries.
- Electromechanical:Servo-driven actuators with integrated encoders deliver programmable stroke control and electronic batch record compatibility. NMPA localization requirements in China accelerate captive production for biologics fill-finish, while EU MDR technical documentation mandates reshape European supplier architectures.
- Pneumatic:Compressed-air systems retain installed base in food processing and chemical handling where explosive atmosphere certifications apply.
- Hydraulic:High-pressure systems anchor construction and heavy equipment applications requiring force multiplication.
- Manual:Hand-operated dispensers serve laboratory and small-batch production environments with minimal capital constraints.
Electromechanical platforms capture the steepest expansion trajectory as manufacturers prioritize traceability and predictive maintenance capabilities.
End User:
Application maturity varies sharply across sectors, with pharmaceutical validation requirements creating structural barriers that protect incumbent suppliers.
- Pharmaceuticals:Sterile injectable and aseptic fill-finish operations demand ISO 14644-1 cleanroom compatibility and FDA-validated electronic records. CDSCO streamlined regulations and PLI scheme incentives in India attract deployment for export-oriented packaging.
- Food & Beverage:Hygienic pump specifications for dairy and beverage sectors face stainless steel alloy price volatility affecting margin predictability.
- Chemicals:EPA emissions guidelines and REACH substance restrictions constrain material selection for seals and gaskets.
- Cosmetics:Pump and valve specialization for premium packaging sustains material science differentiation.
Pharmaceutical end users generate the highest margin pools despite lower unit volumes compared to food processing.
Application:
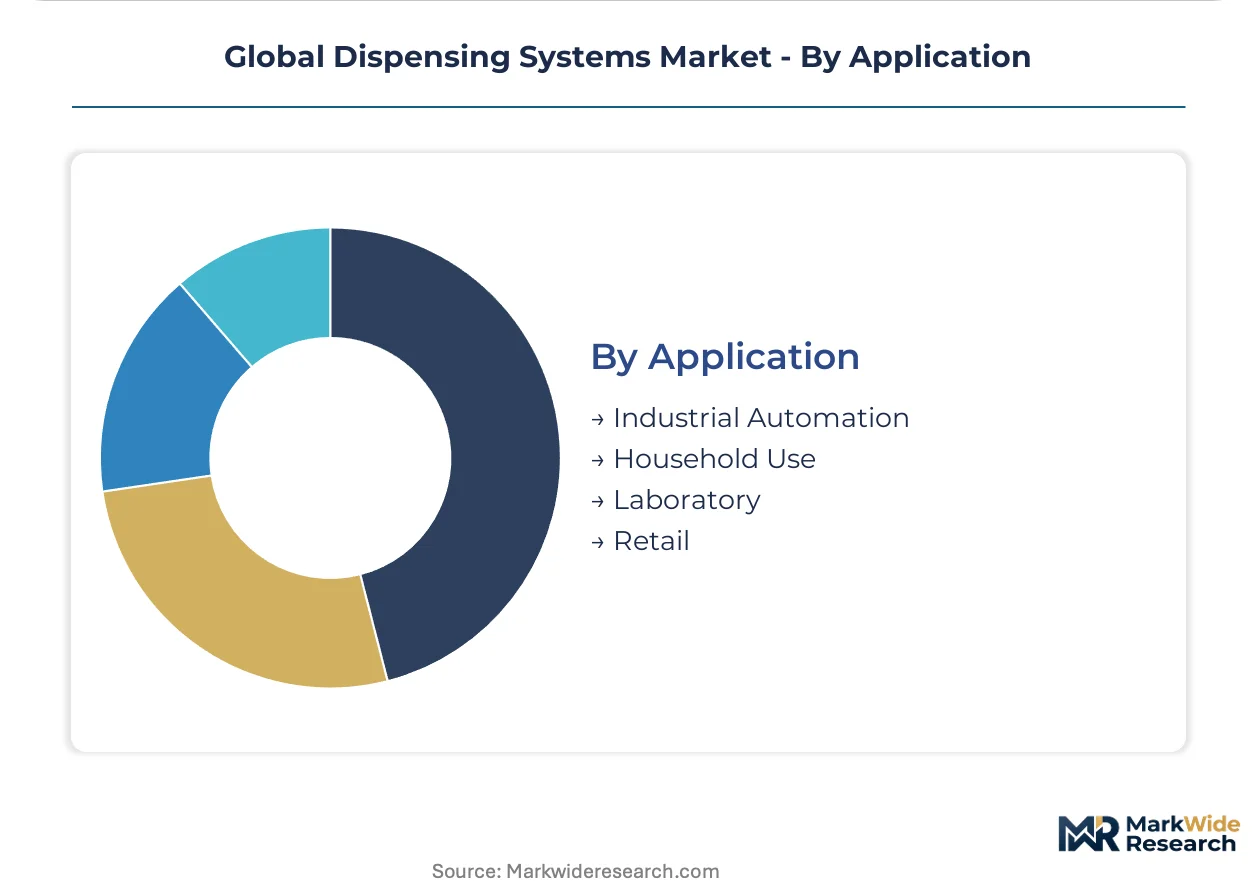
Customer type concentration shapes procurement patterns, with industrial automation buyers prioritizing uptime metrics and laboratory users emphasizing precision specifications.
- Industrial Automation:PLC-integrated dispensing with IIoT analytics enables outcome-based service contracts tying vendor compensation to operational metrics. Lonza, Catalent, and Samsung Biologics specify architectures across multi-site networks in Singapore and South Korea.
- Laboratory:Ultra-low volume precision below fifty microliters opens specialized system architecture for personalized medicine production.
- Household Use:Consumer convenience applications emphasize ergonomic design and cost minimization over technical performance.
- Retail:Point-of-sale dispensing for cosmetics and specialty foods prioritizes aesthetic integration and brand differentiation.
Industrial automation commands the dominant revenue position, while laboratory applications are gaining share fastest through cell and gene therapy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss pharmaceutical clusters, while volume expansion accelerates in Chinese and Indian manufacturing corridors. Suppliers navigate divergent regulatory timelines and validation requirements across these geographies.
Germany
Sterile injectable production and monoclonal antibody fill-finish operations drive precision dispensing demand. EMA and EU MDR technical documentation mandates reshape supplier architectures for notified body scrutiny. The Rhine-Main and Upper Bavaria regions concentrate CDMO campus expansions where Lonza and Catalent standardize equipment specifications across multi-site networks.
United States
FDA 21 CFR Part 11 electronic batch record requirements accelerate replacement of manual dispensing stations with validated electromechanical systems. EPA emissions guidelines constrain material selection for chemical handling applications. The Boston-Cambridge biotech corridor and Research Triangle Park anchor cell and gene therapy fill-finish investments requiring ultra-low volume precision below fifty microliters.
China
NMPA localization requirements for medical device components accelerate captive dispensing system production for biologics fill-finish operations. MIIT industrial upgrading programs support domestic precision equipment manufacturing. The Yangtze River Delta and Pearl River Delta clusters concentrate pharmaceutical contract manufacturing expansion with Samsung Biologics and domestic CDMOs specifying standardized architectures.
India
CDSCO streamlined medical device regulations and PLI scheme incentives attract dispensing system deployment for export-oriented pharmaceutical packaging. FSSAI hygienic processing standards extend demand into dairy and beverage sectors. Maharashtra and Gujarat host the fastest contract manufacturing expansion, with Ahmedabad and Mumbai-Pune pharmaceutical clusters driving equipment procurement decisions.
Switzerland
Swissmedic oversight and high-value monoclonal antibody production sustain premium positioning for precision fluid handling systems. REACH substance restrictions on perfluorinated compounds compel material science investments in fluoropolymer-free seals. The Basel biopharma corridor concentrates Novartis and Roche fill-finish operations where single-use diaphragm pumps with integrated pressure sensors displace peristaltic alternatives.
Global Dispensing Systems Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized precision equipment fabricators. The vendor base stratifies across three tiers: multinational platforms spanning adhesive, coating, and healthcare applications; mid-cap specialists in pump and valve technologies; and regional fabricators serving commodity industrial segments. Strategic moves center on M&A for regulatory compliance capabilities and capacity expansion in Asian pharmaceutical corridors.
Among diversified industrial platforms, Nordson Corporation and Graco Inc. anchor the precision fluid control and high-pressure hydraulic vectors respectively. AptarGroup Inc. occupies a position within the pump and valve specialization tier for cosmetics and pharmaceutical packaging. These three entities exemplify how material science expertise and validation capabilities sustain premium positioning across regulated end-use sectors.
| Leading Market Players |
|---|
| McKesson Corporation |
| Henkel |
| Nordson Corporation |
| Swisslog Healthcare |
| Graco Inc. |
| Omnicell |
| 3M |
| AptarGroup Inc. |
| Becton Dickinson (BD) |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with embedded capacity reservations lock in supply access for pharmaceutical-grade dispensing systems while providing price visibility against nickel and molybdenum alloy volatility. These arrangements concentrate procurement leverage among CDMO networks in Germany, Switzerland, and Singapore, compressing margin buffers for component suppliers facing REACH substance compliance costs.
Pricing Analysis
Configured-to-order pricing for FDA-validated electromechanical systems commands spreads of 40-60% above standard industrial pump configurations. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade platforms with ISO 14644-1 certification from food-processing hygienic pumps and commodity chemical handling equipment. Price differentiation hinges on validation documentation depth and cleanroom compatibility grade. Cost compression in standard industrial tiers is intensifying because stainless steel input volatility forces suppliers to absorb margin erosion or lose volume to Asian competitors. Contract manufacturing buyers exhibit lowest price sensitivity due to regulatory compliance imperatives, while dairy and beverage processors demonstrate highest sensitivity to capital expenditure timing.
Supply Chain Analysis
Strategic stockpiling of precision flow sensors and servo motors dominates inventory strategy among German and Swiss dispensing system fabricators, contrasting with just-in-time preferences for standard pneumatic components. Manufacturing concentration centers on Germany, Switzerland, and China, with Coriolis mass flow technology drawing from German and Japanese specialist suppliers. Raw material dependencies include nickel-molybdenum stainless alloys, fluoropolymer-free seal compounds, and rare-earth servo motor magnets. Single-source vulnerability for high-accuracy pharmaceutical flow measurement creates structural supply chain risk. Distribution runs through authorized service integrators in regulated markets and direct OEM relationships in industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among global pharmaceutical contract manufacturers, with Lonza, Catalent, and Samsung Biologics consolidating procurement decisions across multi-site networks and standardizing equipment specifications rather than accepting facility-level customization.
For Market Incumbents: Fortify regulatory compliance capabilities through dedicated EU MDR technical documentation functions and notified body relationship management. Deepen backward integration into precision sensor supply chains to mitigate single-source vulnerability for Coriolis mass flow technology. Capacity addition in Indian pharmaceutical corridors under CDSCO streamlined regulations captures PLI scheme incentives and export-oriented packaging demand. For New Entrants and Emerging Players: Predictive maintenance service layers represent the most significant incumbent underservice gap, with existing suppliers slow to rearchitect around remote diagnostics and uptime-based compensation models. Cell and gene therapy fill-finish applications below fifty microliter precision volumes offer the most penetrable white space, as established players optimize for larger-batch monoclonal antibody production. Partnership with Swiss and German CDMO engineering teams provides credible go-to-market positioning without full validation infrastructure investment. For Investors and Strategic Acquirers: Mid-cap pump and valve specialists with existing ISO 13485 quality management systems and material science expertise in fluoropolymer-free seals represent the most attractive acquisition target archetype. Long-term viability over the next decade hinges on positioning for personalized medicine production scale-up and digital twin integration. Watch for inflection when cell and gene therapy fill-finish capacity crosses regulatory approval thresholds and triggers specialized dispensing system procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Infrastructure Investment | Dedicated EU MDR documentation functions enable notified body scrutiny navigation for pharmaceutical-grade platforms. |
| Backward Integration into Precision Sensors | In-house Coriolis flow measurement capability mitigates German-Japanese supplier concentration risk. |
| Service Model Rearchitecture | Outcome-based contracts tying compensation to uptime metrics align vendor economics with CDMO operational priorities. |
| Geographic Capacity Expansion | Indian pharmaceutical corridor presence captures CDSCO streamlined regulations and PLI scheme incentives. |
| Digital Twin Platform Development | IIoT analytics integration enables predictive maintenance and remote reconfiguration without hardware replacement. |
Methodological Framework
Desk research of regulatory filing databases, customs and trade flow records, and equipment supplier technical documentation preceded structured interviews with pharmaceutical manufacturing engineers, CDMO procurement directors, regulatory affairs specialists, and aftermarket service managers. Primary fieldwork combined with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA EU MDR technical documentation requirements, and NMPA localization directives. Bottom-up unit economics modeling triangulated against top-down market sizing from national pharmaceutical production statistics and industrial automation capex disclosures.
Variance decomposition across product type, technology platform, end-use sector, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions included pump versus valve versus nozzle architectures, electromechanical versus pneumatic versus hydraulic actuation, pharmaceutical versus food and beverage versus chemical end users, and industrial automation versus laboratory versus retail applications. CAGRs derived from installed base replacement cycles, capacity expansion announcements, and technology substitution elasticities. Forecast inputs incorporated cleanroom validation timeline delays, stainless steel alloy price volatility assumptions, and precision sensor supply concentration effects.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU MDR, and NMPA medical device frameworks; material policy shifts would require re-modeling of validation timeline and compliance cost assumptions. Forecasts reflect assumptions regarding pharmaceutical manufacturing automation adoption rates, electromechanical displacement of pneumatic systems, and CDMO buyer concentration trajectories. Revision becomes warranted when cleanroom certification cycle durations or precision sensor supply availability crosses threshold levels that alter capital deployment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Dispensing Booth Market