
 India Veterinary Healthcare Market | 2026-2036
India Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
India Veterinary Healthcare Market Foresight
Pharmaceutical-grade biologics is rotating toward the center of competitive strategy as Indian livestock operations upgrade from generic antibiotics to targeted vaccines and hormonal therapeutics. Zoetis sustains technology leadership in recombinant vaccine platforms for bovine and poultry applications. Hester Biosciences anchors domestic manufacturing with integrated fill-finish capacity at its Gujarat facilities. Elanco Animal Health competes through deep distribution partnerships with state veterinary departments and cooperative federations.
India veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in food-producing and companion animals, incorporating active pharmaceutical ingredients with purity thresholds typically exceeding 98.5% for injectable formulations and cold-chain distribution maintaining 2-8°C for thermolabile biologicals. Its primary purpose centers on preserving livestock productivity for India's position as the world's largest milk producer while extending companion animal lifespans in urbanizing metros. Vaccines command the largest revenue pool among product types due to mandatory foot-and-mouth disease and brucellosis programs, yet diagnostics is expanding fastest as polymerase chain reaction-based pathogen identification replaces conventional microscopy at progressive dairy cooperatives. Feed additives concentrate margin capture among multinational suppliers given premix formulation complexity and import dependency for trace mineral sources.
BIS certification requirements for veterinary drug manufacturing, CDSCO oversight of novel biological approvals, and state-level livestock department procurement guidelines collectively elevate compliance costs while favoring organized producers with dedicated regulatory affairs teams. The FSSAI's antibiotic residue monitoring in milk and meat is tightening withdrawal period enforcement, directly shaping pharmaceutical prescribing patterns among veterinary practitioners. Stakeholders must monitor how India's proposed veterinary drug schedule revisions under the Drugs and Cosmetics Act intersect with state-level bans on growth-promoting antibiotics to anticipate portfolio restructuring requirements.
Market Dynamics
India's veterinary healthcare sector is reconfiguring around the tension between FSSAI antibiotic residue enforcement and the operational reality of smallholder dairy economics, forcing pharmaceutical portfolios toward preventive biologicals.
Growth Catalysts
- PLI Scheme for Animal Husbandry:Domestic manufacturing incentives are expanding recombinant vaccine fill-finish capacity at organized producers, reducing import dependency for thermolabile biologicals.
- Intensive Dairy Cooperatives:Gujarat and Punjab's commercial herd operations are professionalizing veterinary service procurement, creating concentrated demand for diagnostic platforms and hormonal therapeutics.
- Foot-and-Mouth Disease Eradication Mandate:State livestock department mass vaccination programs are institutionalizing recurring vaccine procurement at scale, anchoring revenue visibility for domestic suppliers.
Market Restraints
- API Import Concentration:Over 60% of veterinary active pharmaceutical ingredients originate from Chinese chemical manufacturers, exposing formulators to supply disruption and currency volatility.
- Cold-Chain Infrastructure Deficits:Last-mile temperature maintenance for 2-8°C biologicals fails in rural Maharashtra and Rajasthan, constraining market penetration of premium vaccines.
- Withdrawal Period Enforcement:FSSAI milk residue testing is compressing antibiotic prescribing windows, forcing practitioners toward costlier alternatives that smallholders resist.
Strategic Opportunities
- PCR-Based Pathogen Identification:Polymerase chain reaction diagnostics are displacing microscopy at progressive cooperatives, opening white space for laboratory service partnerships in untiered cities.
- Trace Mineral Premix Localization:Import substitution incentives under the PLI scheme are attracting investment in domestic chelated mineral production for feed additive formulators.
- Companion Animal Urbanization:Metropolitan pet ownership growth in Bengaluru and Hyderabad is creating demand for chronic disease management protocols previously absent in veterinary practice.
Industry Challenges
- Veterinary Practitioner Density:India operates below WHO-recommended veterinarian-to-livestock ratios, stretching diagnostic and surgical service capacity across dispersed rural holdings.
- CDSCO Biological Approval Timelines:Novel vaccine registration pathways average 18-24 months, delaying market access for platform technologies against emerging zoonotic threats.
- Cooperative Procurement Fragmentation:State-level livestock department tender specifications vary across Maharashtra, Gujarat, and Punjab, forcing suppliers to maintain multiple product registrations and packaging configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Veterinary Healthcare Market |
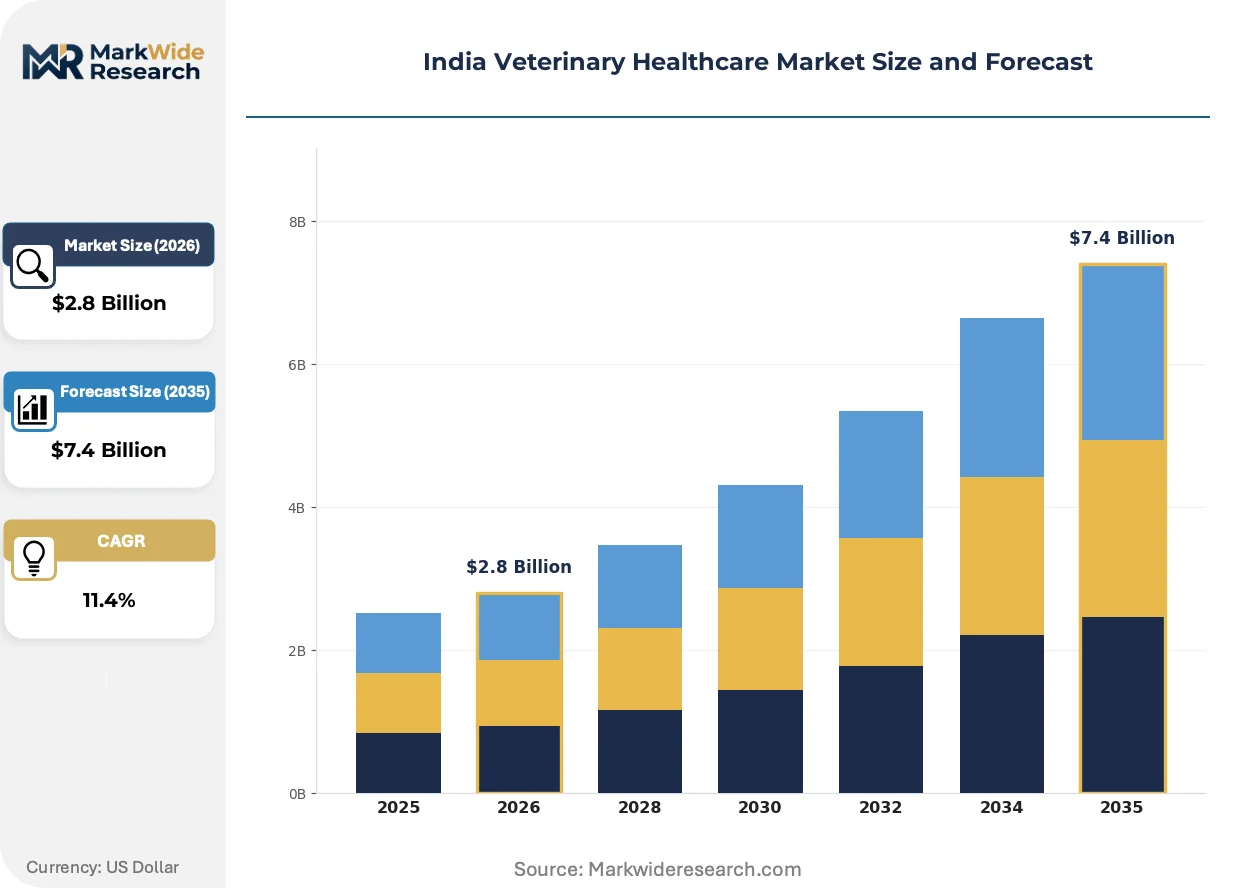
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Diagnostics, Feed Additives End User: Pet Owners, Livestock Farmers, Veterinary Clinics, Animal Hospitals Distribution Channel: Veterinary Pharmacies, Online Channels, Distributors, Direct Sales Service Type: Preventive Care, Surgical Services, Emergency Care, Nutrition Consulting |
| Companies Covered | Elanco Animal Health, Venky's, Zoetis, Neogen Corp., Ceva Sant Animale, Boehringer Ingelheim, Hester Biosciences, Himalaya Animal Health, Merck Animal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Veterinary Healthcare Market Shifts & Advancements
Recombinant vaccine platforms and point-of-care diagnostics are restructuring competitive advantage away from commodity antibiotics toward precision biologicals and data-driven herd management protocols.
mRNA vaccine technology is bifurcating the livestock immunization landscape. The platform enables rapid strain-matched vaccine development against evolving foot-and-mouth disease serotypes. Progressive poultry integrators in Haryana and Telangana are piloting adoption despite cold-chain requirements. This technology is bifurcating procurement budgets between traditional inactivated vaccines and premium platform biologicals, compressing margins at generic manufacturers.
BIS certification amendments for veterinary drug manufacturing are tightening purity thresholds for injectable formulations above 98.5%. The regulation is elevating compliance costs for small-scale compounders while consolidating market share at organized producers with dedicated quality assurance infrastructure. Gujarat-based manufacturers with integrated analytical laboratories are capturing state cooperative tenders that exclude non-certified competitors.
Dairy cooperatives are unbundling veterinary service contracts from input supply arrangements. Progressive federations in Punjab are separating diagnostic testing, artificial insemination, and pharmaceutical procurement into discrete vendor relationships. This pattern is most visible in Amul-linked village societies, where members now vote on service provider selection independent of feed and semen suppliers, compressing legacy integrated distributors.
India Veterinary Healthcare Market Segmentation
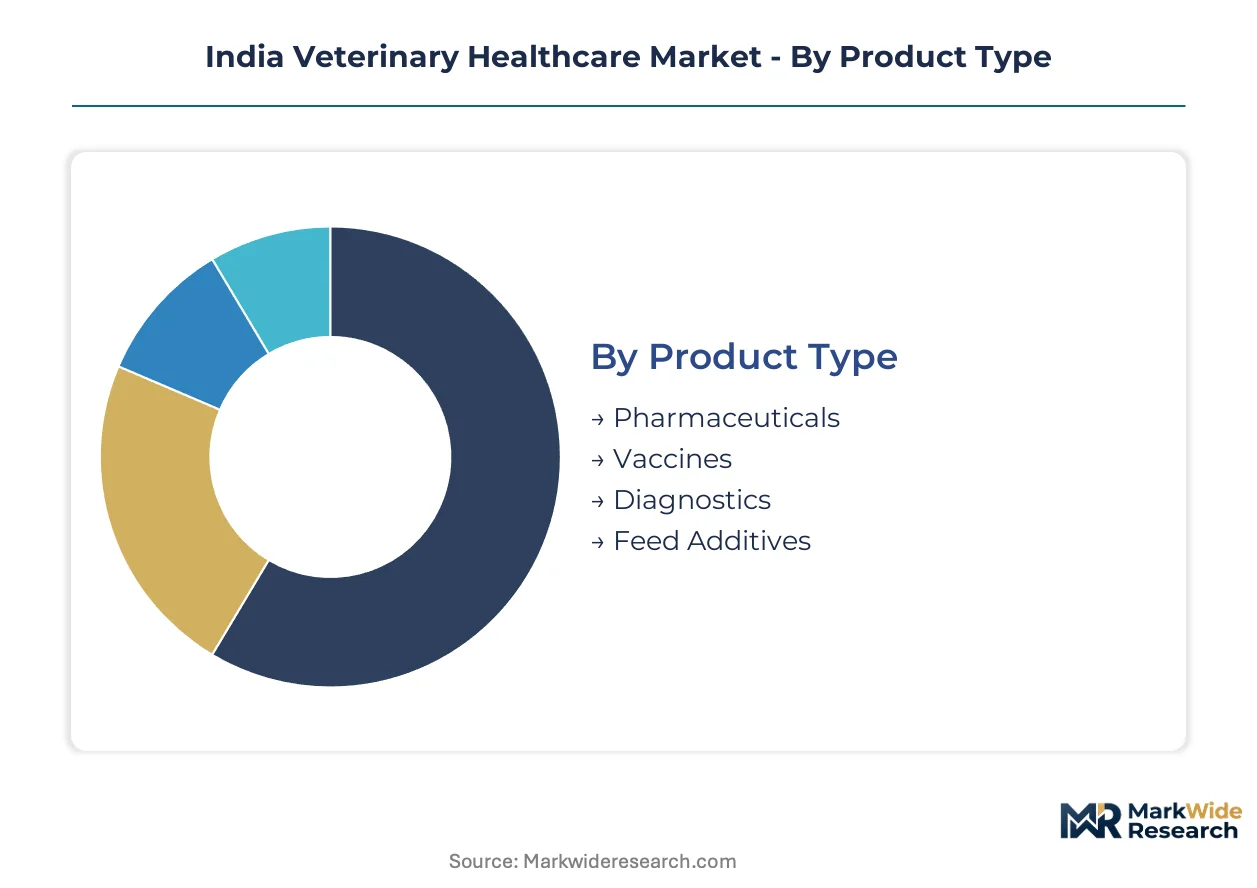
Segmentation in India's veterinary healthcare market reveals how regulatory frameworks and procurement patterns fragment demand across product categories and service channels. CDSCO biological approval pathways and FSSAI residue enforcement create divergent compliance burdens that reshape competitive positioning within each segment.
Product Type:
BIS certification thresholds and CDSCO novel biological registration timelines differentiate compliance intensity across pharmaceutical categories, elevating capital requirements for thermolabile biologicals.
- Pharmaceuticals:Injectable formulations require API purity above 98.5% under BIS amendments, compressing margins at small-scale compounders while consolidating share at Gujarat-based manufacturers with integrated analytical laboratories. Withdrawal period enforcement by FSSAI milk residue testing is forcing practitioners toward costlier alternatives that strain smallholder economics in Maharashtra and Rajasthan.
- Vaccines:Thermolabile biologicals demand 2-8°C cold-chain maintenance from fill-finish through last-mile delivery, constraining penetration in rural infrastructure-deficient zones despite mandatory foot-and-mouth disease and brucellosis programs anchoring state procurement volumes. Recombinant platforms are displacing inactivated formulations at progressive poultry integrators in Haryana.
- Diagnostics:Polymerase chain reaction-based pathogen identification is displacing microscopy at progressive dairy cooperatives.
- Feed Additives:Chelated trace mineral premixes concentrate margin capture among suppliers with import substitution capacity under PLI incentives.
Established volume favors Pharmaceuticals; emerging adoption favors Diagnostics.
End User:
Procurement professionalization varies sharply by scale, with cooperative federations separating service contracts from input supply while individual smallholders resist premium pricing.
- Livestock Farmers:Commercial dairy and poultry operations in Gujarat, Maharashtra, and Punjab are professionalizing herd health management through concentrated bulk procurement of vaccines and hormonal therapeutics. Intensive cooperatives now vote on discrete vendor relationships for diagnostics, artificial insemination, and pharmaceuticals independent of feed suppliers.
- Pet Owners:Metropolitan ownership growth in Bengaluru and Hyderabad is creating demand for chronic disease management protocols previously absent in veterinary practice, with urban clinics capturing recurring revenue from geriatric companion animal care.
- Veterinary Clinics:Point-of-care diagnostic investments are climbing fastest at progressive small animal practices.
- Animal Hospitals:Surgical service capacity concentrates in tier-1 cities with specialist veterinarian density.
Procurement consolidation favors Livestock Farmers; margin expansion favors Pet Owners.
Distribution Channel:
Channel selection reflects product temperature sensitivity and regulatory documentation requirements, with biologicals favoring controlled distribution and generics tolerating fragmented retail.
- Distributors:State veterinary department tender specifications vary across Maharashtra, Gujarat, and Punjab, forcing suppliers to maintain multiple product registrations and packaging configurations. Deep distribution partnerships with cooperative federations anchor revenue visibility for organized manufacturers.
- Direct Sales:Large poultry integrators in Telangana and Haryana are piloting mRNA vaccine adoption through direct procurement relationships, bypassing traditional channel margins for platform biologicals with rapid strain-matching capabilities.
- Veterinary Pharmacies:Cold-chain infrastructure investments concentrate at pharmacy chains with captive logistics.
- Online Channels:Feed additive and nutritional supplement sales are expanding fastest through digital platforms.
Regulatory complexity favors Distributors; technology adoption favors Direct Sales.
Service Type:
Service unbundling at progressive cooperatives is separating preventive protocols from emergency interventions, creating discrete vendor relationships that compress legacy integrated providers.
- Preventive Care:Mass vaccination programs for foot-and-mouth disease eradication are institutionalizing recurring procurement at scale, with state livestock departments anchoring revenue visibility through multi-year tender awards. PCR-based pathogen screening is displacing conventional microscopy at Amul-linked village societies.
- Surgical Services:Capacity constraints emerge below WHO-recommended veterinarian-to-livestock ratios, stretching diagnostic and surgical availability across dispersed rural holdings while urban hospitals capture specialist procedures.
- Emergency Care:After-hours service availability concentrates in metropolitan and peri-urban clusters.
- Nutrition Consulting:Cooperative federations are separating feed formulation advice from input supply arrangements.
Institutional procurement favors Preventive Care; capacity scarcity constrains Surgical Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Indian states, with smallholder-dominated Rajasthan and Madhya Pradesh resisting premium therapeutics while Gujarat and Punjab's commercial cooperatives absorb higher-cost biologicals without volume erosion.
Gujarat
Intensive dairy cooperatives anchored by Amul-linked village societies drive concentrated bulk procurement of vaccines and hormonal therapeutics. The state's PLI scheme beneficiaries are expanding recombinant vaccine fill-finish capacity at organized manufacturing clusters. Anand and surrounding districts host integrated production facilities where BIS-certified manufacturers capture state livestock department tenders.
Punjab
Commercial dairy operations professionalizing herd health management create sustained demand for diagnostic platforms and artificial insemination services. FSSAI antibiotic residue monitoring is tightening withdrawal period enforcement across the state's milk procurement networks. Ludhiana and Jalandhar veterinary service markets are unbundling legacy integrated contracts into discrete vendor relationships.
Maharashtra
Poultry integrators in Pune and Nashik corridors pilot mRNA vaccine adoption for rapid strain-matched immunization against evolving viral threats. Cold-chain infrastructure deficits in rural Marathwada and Vidarbha constrain penetration of thermolabile biologicals despite state vaccination mandates. Mumbai and Thane metropolitan clinics capture companion animal chronic disease management revenue.
Telangana
Progressive poultry operations around Hyderabad are direct-procuring platform biologicals, bypassing traditional distribution channels for rapid strain-matching capabilities. CDSCO biological approval timelines averaging 18-24 months delay market access for novel vaccine technologies. The state's emerging feed additive manufacturing is attracting PLI-linked investment in chelated trace mineral localization.
Haryana
Intensive poultry clusters in Sonipat and Karnal are piloting recombinant vaccine platforms alongside traditional inactivated formulations. State livestock department mass vaccination programs for foot-and-mouth disease institutionalize recurring procurement at scale. Gurgaon and Faridabad urban veterinary practices capture metropolitan pet ownership growth with specialized surgical capacity.
India Veterinary Healthcare Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with recombinant vaccine platforms and point-of-care diagnostics separating premium-positioned suppliers from commodity antibiotic manufacturers. The market exhibits tiered consolidation around multinational biological innovators, domestic integrated manufacturers, and regional generic compounders. Three archetypes dominate: platform technology specialists with CDSCO-registered novel biologicals, integrated domestic producers with captive fill-finish and distribution infrastructure, and cost-optimized formulators serving price-sensitive smallholder segments. Competitive moves concentrate on strategic partnerships with state veterinary departments and cooperative federations, plus capacity expansion in cold-chain distribution networks.
Within the multinational tier, Zoetis and Elanco Animal Health occupy positions as technology anchors for recombinant vaccine platforms and distribution partnerships respectively. Hester Biosciences represents the domestic integrated manufacturer archetype with Gujarat-based fill-finish capacity. These three exemplify the competitive divergence between platform innovation and manufacturing scale in a market reshaping around preventive biologicals.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Venky's |
| Zoetis |
| Neogen Corp. |
| Ceva Sant Animale |
| Boehringer Ingelheim |
| Hester Biosciences |
| Himalaya Animal Health |
| Merck Animal Health |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day API lead times from Chinese chemical manufacturers concentrate pricing power at integrated domestic formulators with captive inventory buffers, while cold-chain biologicals command 40-60% premiums over ambient-stored generics due to last-mile infrastructure costs. BIS certification requirements above 98.5% purity thresholds for injectables further stratify procurement budgets between certified organized producers and price-optimized regional compounders.
Pricing Analysis
After-sales service contracts for herd health management programs drive lifetime value capture beyond initial pharmaceutical sales. Three-tier pricing structure across premium recombinant vaccines, standard inactivated formulations, and economy generic antibiotics separates procurement budgets at cooperative federations. Pricing pressure stems from FSSAI antibiotic residue enforcement compressing smallholder prescribing windows toward costlier biological alternatives. Livestock farmers in Rajasthan and Madhya Pradesh exhibit highest price sensitivity, while Gujarat and Punjab commercial cooperatives absorb premium therapeutics without volume erosion.
Supply Chain Analysis
Inventory concentration in Chinese API manufacturers and Indian formulation hubs exposes downstream producers to supply disruption and currency volatility. Active pharmaceutical ingredients draw from Chinese chemical manufacturers, recombinant vaccine platforms rest on imported master cell banks, and cold-chain distribution hinges on domestic 2-8°C logistics networks. Single-source vulnerability concentrates in thermolabile biological fill-finish capacity. Distribution runs through state veterinary department tender networks and cooperative federation procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level tender specifications and unbundled service contracts creates niche entry points for specialized players targeting discrete procurement verticals.
For Market Incumbents: Compound technology leadership in recombinant platforms through CDSCO registration investments for novel biological pathways, while deepening captive cold-chain distribution networks in Gujarat and Punjab to defend against direct-procurement pilots at poultry integrators. Certification barriers and fill-finish capacity scarcity protect margin structures against generic erosion. For New Entrants and Emerging Players: Anchor in PCR-based diagnostic services for progressive dairy cooperatives separating testing contracts from pharmaceutical procurement, particularly in tier-2 Maharashtra and Telangana cities where laboratory infrastructure lags cooperative professionalization. Direct technical service partnerships with village societies bypass legacy distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because state procurement institutionalization and PLI scheme manufacturing incentives favor scaled domestic producers with integrated regulatory affairs and quality assurance infrastructure. Target acquisition archetype: BIS-certified manufacturers with existing state livestock department tender awards. Signal to watch: CDSCO approval timeline compression for platform biologicals indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Distribution Expansion | Captures premium vaccine margins in infrastructure-deficient rural Maharashtra and Rajasthan zones. |
| CDSCO Novel Biological Registration | Accelerates market access for mRNA platforms against evolving foot-and-mouth disease serotypes. |
| Cooperative Service Contract Unbundling | Separates diagnostic, pharmaceutical, and artificial insemination procurement at Amul-linked federations. |
| PLI-Linked Manufacturing Scale-Up | Expands domestic recombinant vaccine fill-finish capacity reducing import dependency. |
| PCR Diagnostic Laboratory Partnership | Displaces microscopy at progressive dairy cooperatives with pathogen identification services. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary pharmaceutical manufacturing executives, state livestock department procurement officers, cooperative federation managers, and diagnostic laboratory directors and refined through secondary validation against CDSCO biological approval databases, FSSAI residue monitoring reports, state tender documentation, and PLI scheme beneficiary disclosures. Bottom-up volume estimates from product-level procurement data were triangulated against top-down market sizing from industry association aggregates.
Variance decomposition across product type, end-user scale tier, distribution channel, and regional regulatory cluster segments structured the analytical framework. CAGRs were derived from segment-level growth trajectory modeling incorporating PLI scheme capacity addition timelines, FSSAI enforcement intensity projections, and cooperative professionalization adoption curves. Forecast inputs included state vaccination program budget allocations and poultry integrator technology adoption patterns.
Material uncertainties — CDSCO approval timeline variability, PLI scheme disbursement pacing, and FSSAI enforcement intensity shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway maturation and infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Bovine Collagen Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
OTC Cat Medicines Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Pet Veterinary Diet Market