
 Digital Banking Market | 2026-2036
Digital Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Banking Market Analysis
Subscription-based API access is expanding the addressable market for banking infrastructure vendors. Temenos AG leverages its cloud-native core banking suite to anchor deployments across tier-one institutions in Europe and Asia-Pacific. Fiserv, Inc. sustains competitive density through its merchant-acquiring and payment processing integration. Backbase differentiates by occupying the engagement banking layer, helping incumbents rebuild front-end experiences without full core replacements.
Digital banking encompasses the delivery of financial services through internet-connected platforms, web interfaces, and mobile applications, typically operating on cloud-native architectures with RESTful APIs enabling real-time transaction processing and third-party service integration. Its primary commercial purpose is to reduce operational costs per customer while enabling personalized financial products through data analytics and automated decision engines. Mobile banking services lead transaction volume globally due to smartphone penetration and biometric authentication adoption, while AI-based solutions represent the fastest-growing technology segment as institutions deploy predictive models for credit underwriting and fraud detection. Payment solutions within digital wallets command concentrated margin pools from interchange fees and merchant services.
The European Banking Authority's PSD2 open-banking mandates and the EU AI Act's risk-classification requirements for automated credit decisions shape product development cycles and compliance expenditures for vendors serving European institutions. In the United States, the OCC's fintech charter framework and state-level money transmission laws create a fragmented licensing environment that influences market entry strategy. India's RBI guidelines on digital lending and data localization requirements further constrain architecture choices for platforms targeting South Asian deployment. Stakeholders must monitor evolving capital requirements for cloud-hosted banking infrastructure as regulators reassess operational risk frameworks for technology-dependent financial services.
Market Dynamics
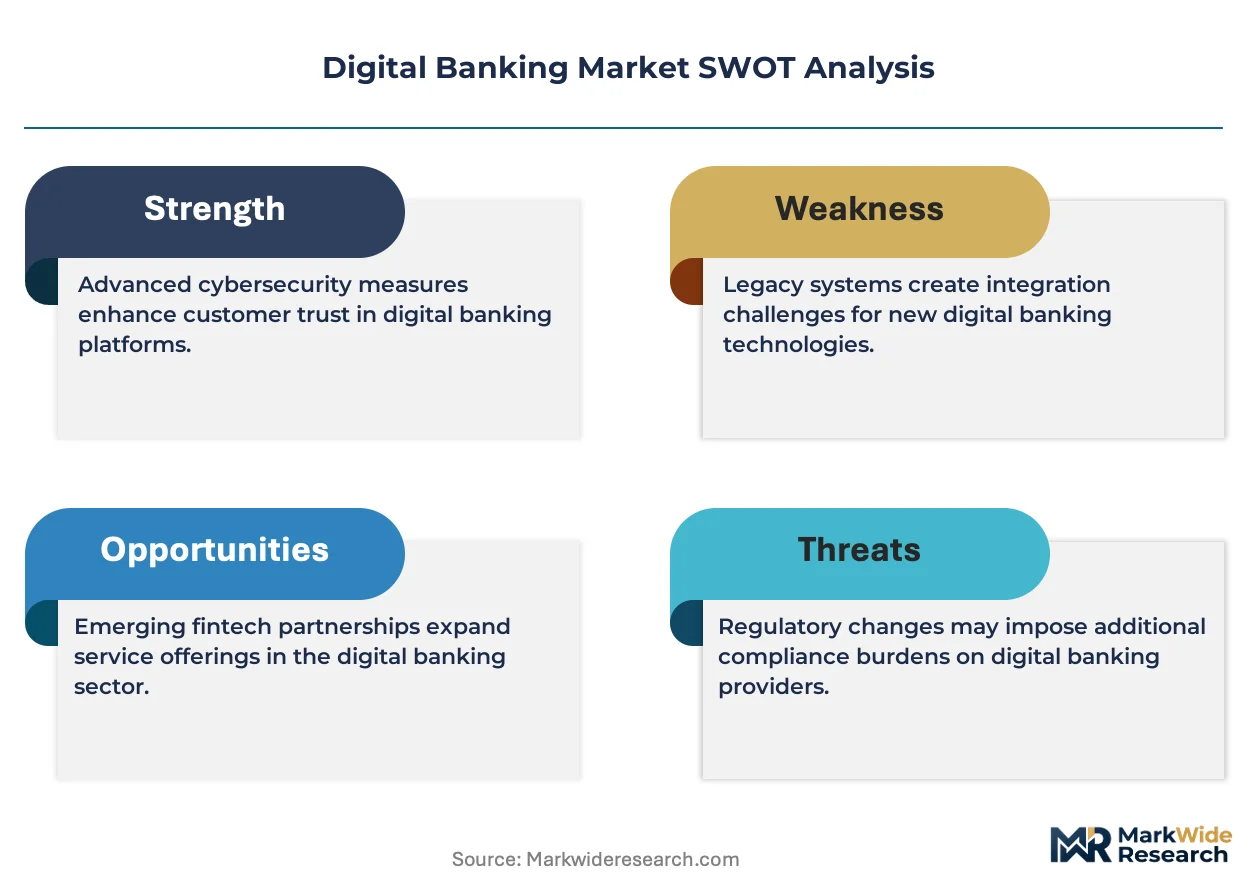
API-first architecture is compressing the competitive moat between neobanks and legacy institutions, forcing incumbents to decouple monolithic core systems into modular microservices or surrender treasury relationships to cloud-native challengers.
Growth Catalysts
- India's PLI Scheme for Fintech Infrastructure:Domestic production-linked incentives are accelerating local data center buildouts and reducing foreign cloud dependency for licensed banks.
- Small Business Treasury Migration:SMEs are abandoning branch-dependent cash management for real-time API-enabled platforms that integrate accounting software directly.
- Biometric Authentication:Fingerprint and facial recognition deployment on smartphones is eliminating password friction and expanding mobile transaction velocity.
Market Restraints
- Data Localization Mandates:India's RBI requirements for domestic data storage are forcing architecture duplication and raising compliance costs for foreign platform providers.
- Core System Concentration:Three legacy vendors dominate mainframe banking infrastructure, creating vendor lock-in and migration friction for tier-two institutions.
- Cloud Concentration Risk:Hyperscaler dominance in AWS, Azure, and GCP creates single-point-of-failure exposure for regulated financial workloads.
Strategic Opportunities
- EU AI Act Compliance Services:Automated credit decision risk-classification requirements are creating demand for explainable AI audit tools and model governance platforms.
- Embedded Finance Convergence:Banking-as-a-Service APIs merging with e-commerce checkout flows are opening non-bank distribution channels for deposit and lending products.
- US OCC Fintech Charter Pathway:Specialized national banking licenses are enabling direct Federal Reserve access without state-by-state money transmission compliance.
Industry Challenges
- Legacy Core Integration Complexity:Decades-old COBOL systems resist real-time API exposure, forcing expensive middleware layers that degrade performance.
- Cloud Risk Talent Scarcity:Shortage of engineers with both financial services domain expertise and Kubernetes-native infrastructure skills is slowing migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Banking Market |
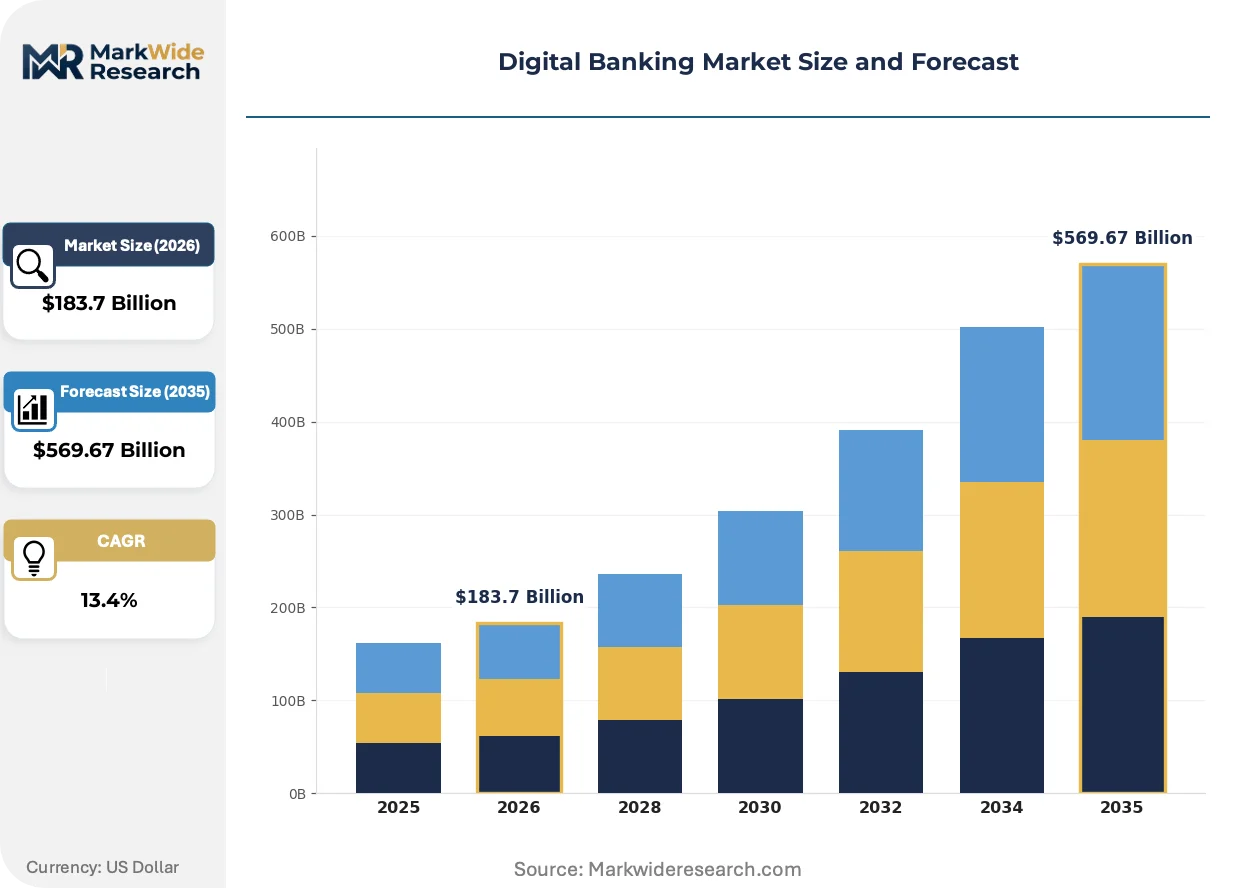
| Market Size in 2026 | $183.7 Billion |
| Market Size in 2035 | $569.67 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Banking, Mobile Banking, Digital Wallets, Payment Solutions Customer Type: Retail Customers, Small Businesses, Corporates, Financial Institutions Technology: Blockchain, AI-Based Solutions, Cloud Computing, Biometric Authentication Application: Fund Transfers, Account Management, Credit Services, Financial Advisory |
| Companies Covered | Temenos AG, Fiserv, Inc., Finastra, Fidelity National Information Services, Inc. (FIS), Finacle, Backbase, Thought Machine, nCino, Q2 Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Banking Market Emerging Trajectories
Real-time payment rails and generative AI are compressing product development cycles from quarters to weeks, while regulatory fragmentation forces vendors to maintain parallel compliance stacks across jurisdictions.
Embedded finance infrastructure is consolidating around standardized Banking-as-a-Service APIs that abstract core banking functions into composable modules. Retail merchants and SaaS platforms are adopting these white-label capabilities within eighteen-month implementation windows. This consolidation is collapsing the traditional boundary between financial and non-financial software stacks.
Europe's PSD2 open-banking mandates and the EU AI Act's risk-classification framework are mandating algorithmic transparency for automated lending decisions. Vendors must now maintain auditable model lineage and human-in-the-loop override capabilities. Tier-one institutions in Germany and France are responding by acquiring specialized regtech capabilities rather than building internally.
Corporate treasury departments are unbundling monolithic banking relationships, selecting specialized providers for payments, foreign exchange, and working capital. This fragmentation is displacing the single-bank model that dominated corporate banking for decades. The shift is most visible among mid-market enterprises in the United Kingdom and Netherlands seeking best-of-breed API performance.
Digital Banking Market Segmentation
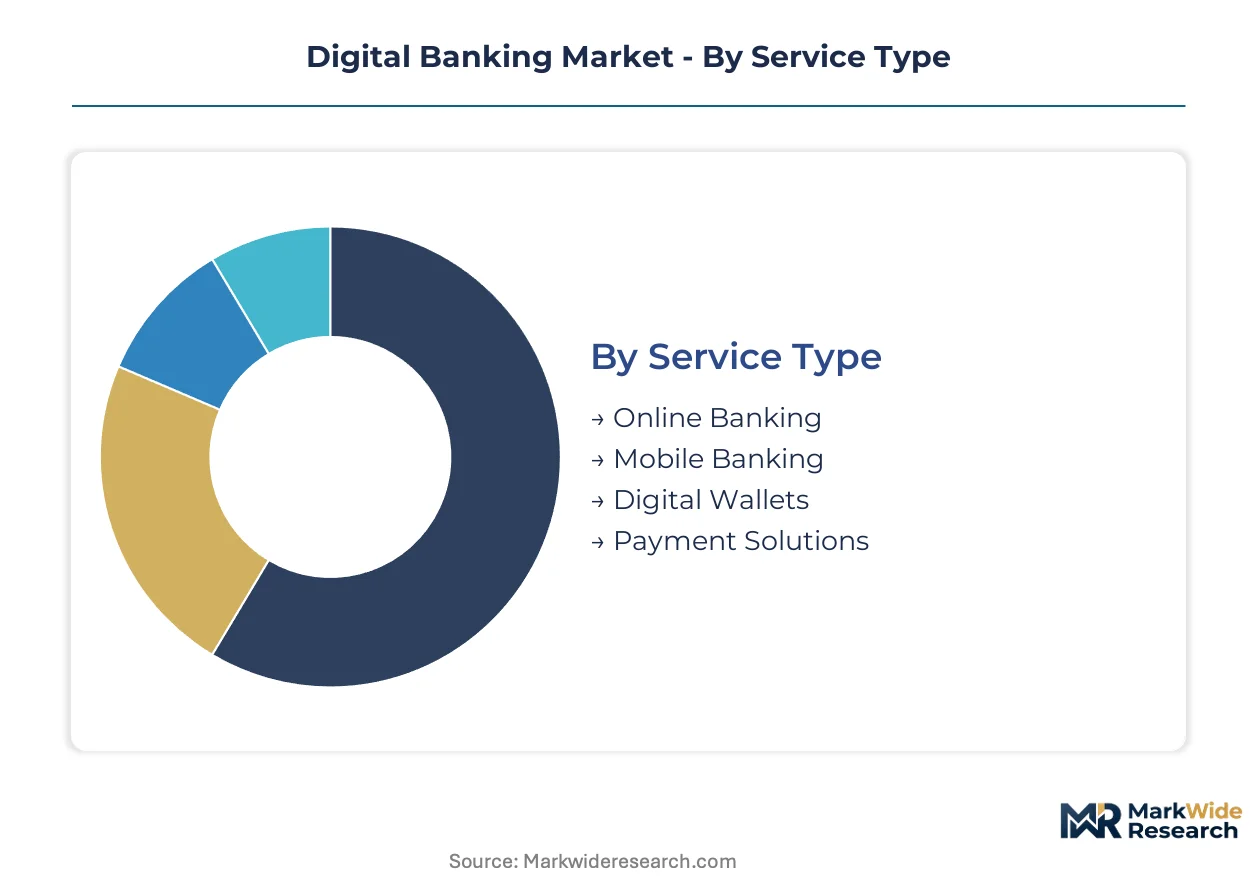
Digital banking vendors design modular architectures around distinct service delivery modes, customer risk profiles, and technology stacks. Segmentation determines API licensing tiers, compliance obligations, and infrastructure deployment patterns across regulated markets.
Service Type:
Upgrade cycles compress as institutions replace branch-dependent workflows with API-native interfaces, forcing parallel investments across multiple service channels.
- Online Banking:Browser-based transactional interfaces serve legacy customer bases requiring desktop accessibility. European banks under PSD2 mandates concentrate demand here for account aggregation portals.
- Mobile Banking:Smartphone-native applications with biometric login and push notification architecture dominate transaction velocity. India's UPI integration and smartphone penetration drive concentrated deployment by domestic banks.
- Digital Wallets:Stored-value instruments enabling merchant checkout and peer-to-peer transfers.
- Payment Solutions:Real-time rail connectivity and cross-border settlement infrastructure.
Volume placements concentrate in Mobile Banking; the faster expansion belongs to Payment Solutions.
Customer Type:
Cost-to-serve differentials widen as automated onboarding reduces marginal acquisition expense for high-volume, low-balance segments.
- Retail Customers:Individual depositors and borrowers accessing basic transactional and credit products. Neobanks in Germany and Brazil target this segment with zero-fee positioning.
- Small Businesses:SMEs requiring integrated treasury, invoicing, and working capital management. API-enabled platforms displace branch relationships in the United Kingdom and Netherlands.
- Corporates:Multi-entity treasuries demanding real-time liquidity visibility and FX execution.
- Financial Institutions:Banks and credit unions white-labeling infrastructure from Banking-as-a-Service providers.
Small Businesses command the steepest expansion trajectory; Financial Institutions anchor current volume concentration.
Technology:
Margin structures diverge sharply between commodity cloud infrastructure and proprietary AI model layers requiring specialized compliance governance.
- Blockchain:Distributed ledger infrastructure for settlement finality and programmable contracts. Singapore and UAE regulators pilot wholesale CBDC applications.
- AI-Based Solutions:Predictive underwriting, fraud detection, and conversational interfaces. EU AI Act risk-classification mandates reshape procurement criteria for German and French institutions.
- Cloud Computing:Hyperscaler-hosted core banking and data analytics workloads.
- Biometric Authentication:Fingerprint, facial recognition, and voiceprint identity verification.
Cloud Computing dominates current infrastructure spend; AI-Based Solutions are climbing the fastest.
Application:
Customer lifetime value correlates directly with application depth, as advisory and credit relationships generate recurring revenue versus transactional fund transfers.
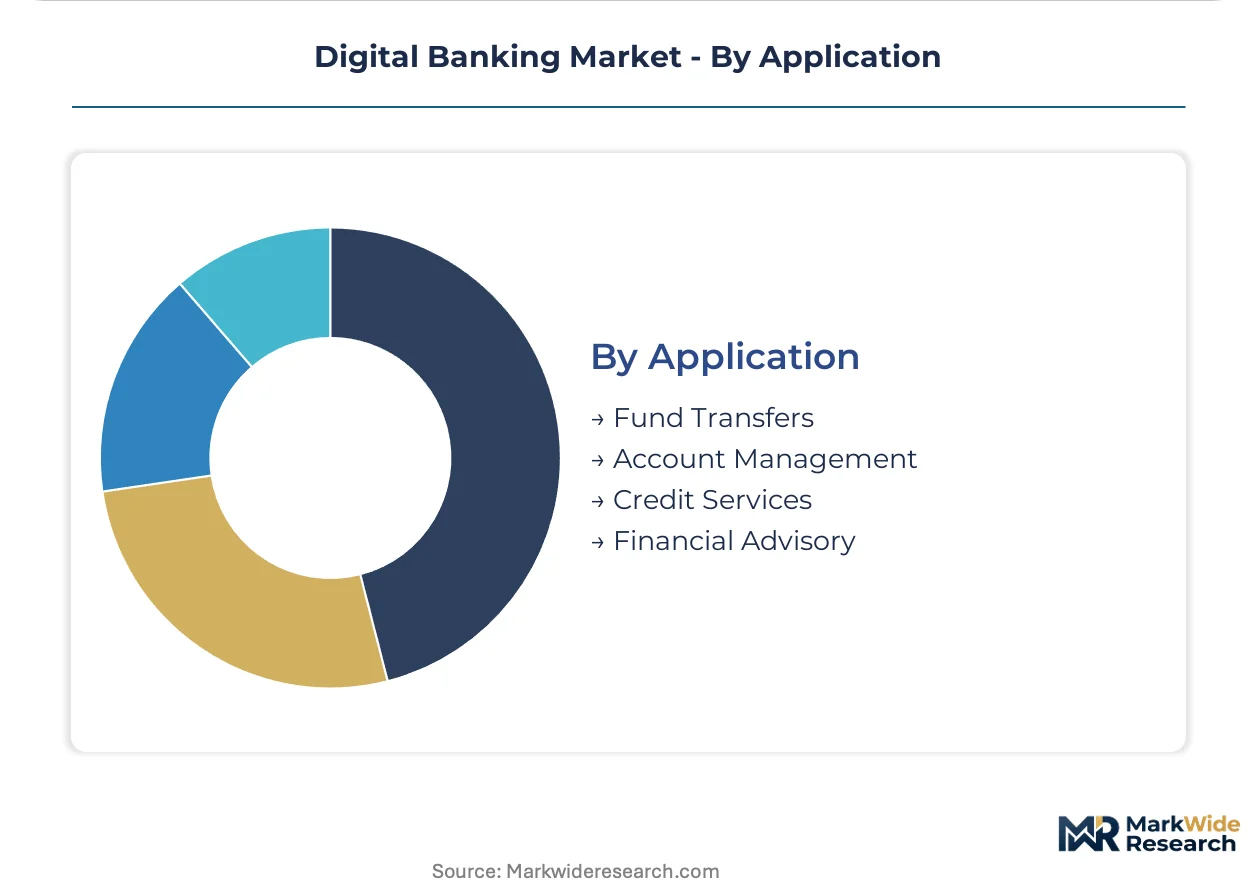
- Fund Transfers:Domestic and cross-border payment execution via real-time rails. India's IMPS and UPI networks concentrate volume.
- Account Management:Balance inquiry, statement retrieval, and self-service configuration. Mobile-first neobanks in Brazil and Mexico differentiate here.
- Credit Services:Automated underwriting, disbursement, and collections for consumer and commercial lending.
- Financial Advisory:Algorithmic portfolio construction and goal-based planning tools.
Fund Transfers anchor transaction volume; Credit Services deliver the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates in established financial centers, while consumption accelerates in emerging markets where smartphone penetration outpaces legacy banking infrastructure. Regulatory divergence shapes deployment architecture across jurisdictions.
United States
Neobank proliferation and embedded finance adoption drive platform demand among fintech challengers. The OCC's fintech charter framework enables direct Federal Reserve access for qualified applicants. New York and San Francisco anchor development clusters where Banking-as-a-Service providers concentrate engineering talent.
United Kingdom
Open banking API proliferation and SME treasury unbundling reshape competitive dynamics. The Financial Conduct Authority's regulatory sandbox accelerates pilot deployments for novel payment architectures. London's Square Mile hosts dense concentrations of core banking modernization projects at tier-one institutions.
Germany
Industrial Mittelstand demand for real-time liquidity management propels API-enabled treasury platform adoption. The EU AI Act's risk-classification mandates reshape procurement criteria for automated credit solutions. Frankfurt's financial district anchors regtech acquisition activity as institutions seek explainable AI audit capabilities.
India
UPI transaction volume expansion and small business digitization create concentrated infrastructure demand. The Reserve Bank of India's PLI scheme for fintech infrastructure accelerates domestic data center buildouts. Mumbai and Bangalore host competing development ecosystems for cloud-native core banking deployments.
Singapore
Wealth management platform modernization and cross-border payment hub status attract vendor investment. The Monetary Authority of Singapore's digital banking license framework admits non-bank operators to wholesale markets. The Marina Bay financial district concentrates regional headquarters for core banking software providers.
Digital Banking Market Vendor Landscape
Top-tier vendors anchor cloud-native core banking deployments at tier-one institutions, while mid-tier specialists occupy vertical niches and regional markets. The vendor base stratifies across three functional layers: core processing engines, engagement banking interfaces, and embedded finance orchestration platforms. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into compliance automation tooling.
Within the engagement banking tier, Backbase occupies a position exemplifying front-end modernization without full core replacement. Temenos AG and Fiserv, Inc. anchor the core infrastructure vector, representing contrasting architectural philosophies around cloud-native versus hybrid deployment models. These three entities collectively illustrate the competitive tension between modular best-of-breed stacks and integrated end-to-end suites.
| Leading Market Players |
|---|
| Temenos AG |
| Fiserv, Inc. |
| Finastra |
| Fidelity National Information Services, Inc. (FIS) |
| Finacle |
| Backbase |
| Thought Machine |
| nCino |
| Q2 Software, Inc. |
| Others |
Supply Flow & Price Mechanics
Hyperscaler compute pricing indices cascade through digital banking infrastructure tiers, compressing margins for cloud-native challengers while forcing legacy vendors into hybrid deployment concessions. Subscription-based API licensing stratifies across premium core-banking suites, standard engagement-layer platforms, and economy-tier white-label modules, with India's data localization mandates adding architecture duplication costs that foreign providers absorb or pass downstream.
Pricing Analysis
Margin tightening in the engagement banking tier reflects hyperscaler compute cost pass-through and intensifying competition from modular specialists. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and compliance automation depth, with certification against RBI guidelines and EU AI Act risk-classification frameworks commanding substantial premiums. Cost-down pressure on standard-tier deployments accelerates because neobanks prioritize API velocity over feature depth. Small businesses exhibit highest price sensitivity, while tier-one institutions in Germany and Singapore accept premium positioning for model governance tooling.
Supply Chain Analysis
India's PLI scheme for fintech infrastructure and RBI data localization requirements are reshaping sourcing patterns toward domestic data center buildouts and local engineering talent pools. Supply concentration rests on United States hyperscaler dominance, Indian domestic cloud infrastructure expansion, and European regtech specialization for algorithmic transparency. Critical dependencies include Kubernetes-native orchestration layers, explainable AI model repositories, and biometric authentication SDKs. Single-source vulnerability concentrates in AWS, Azure, and GCP control planes for regulated financial workloads. Distribution runs through direct enterprise sales for core banking suites and API marketplace integrations for embedded finance orchestration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital banking infrastructure sits in a core-system replacement cycle, with API-first architectures displacing COBOL-based legacy stacks that resist real-time transaction processing. Cloud-native microservices are replacing monolithic deployments as the dominant technology transition across tier-one and tier-two institutions.
For Market Incumbents: Anchor defensive positioning through selective backward integration into compliance automation tooling, particularly for EU AI Act model governance requirements. Prioritize talent acquisition in Kubernetes-native infrastructure engineering to narrow capability gaps with cloud-native challengers. Threat exposure concentrates in Banking-as-a-Service APIs that enable non-bank distributors to capture customer relationships without balance sheet investment.
For New Entrants and Emerging Players: The premium-economy price-point gap in SME treasury platforms creates white-space opportunity for modular API providers targeting mid-market enterprises in the United Kingdom and Netherlands. Underpenetrated segments include real-time liquidity visibility tools for industrial Mittelstand and white-label embedded finance for retail merchants. Go-to-market leverage concentrates on rapid eighteen-month implementation windows and accounting software integration partnerships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized regtech capabilities in Germany and France where tier-one institutions seek explainable AI audit tools rather than internal development. Long-term viability across the analysis window hinges on vendor ability to maintain parallel compliance stacks across RBI, PSD2, and OCC regulatory frameworks. Acquisition target archetypes include mid-tier engagement banking specialists with proven tier-two migration track records. Signal to monitor: core banking modernization project delays at European institutions as EU AI Act enforcement timelines clarify.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core Modernization | Decouples monolithic COBOL systems into microservices that enable real-time transaction processing for tier-one banks. |
| Compliance Automation Acquisition | Secures explainable AI audit capabilities required by EU AI Act risk-classification mandates for automated credit decisions. |
| Domestic Data Center Buildout | Satisfies RBI data localization requirements while reducing foreign cloud dependency for India-licensed banking platforms. |
| Embedded Finance Partnership | Extends deposit and lending distribution through non-bank channels via Banking-as-a-Service API integration. |
| Biometric Authentication Deployment | Eliminates password friction and expands mobile transaction velocity through smartphone-native identity verification. |
Methodological Framework
Document review covered regulatory filings from RBI, EBA, and OCC, complemented by interviews with core banking software executives, API platform engineers, and SME treasury managers at mid-market enterprises. Secondary validation drew from hyperscaler capex disclosures, fintech infrastructure PLI scheme announcements, and EU AI Act implementation guidance. Bottom-up segmentation modeling triangulated against top-down market sizing from banking technology expenditure surveys.
Cross-referencing historical deployment timelines against panel input from platform engineering leaders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service delivery mode, customer risk profile, technology stack architecture, and regional regulatory cluster. CAGRs were derived from installation base expansion rates and API transaction volume trajectories. Industry-specific forecast inputs incorporated UPI transaction growth patterns and open banking API proliferation metrics.
Underlying measurement precision varies by segment; mobile banking and payment solutions carry tighter precision than blockchain infrastructure and wealth management advisory tools. Forecasts reflect assumptions around regulatory enforcement timelines and hyperscaler pricing stability. Revision risks concentrate in data localization mandate expansion, core system vendor consolidation, and cloud concentration regulatory responses. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Corporate Digital Banking Market
Banking
Global Banking BPS Market
Banking
Retail Banking Market
Banking
Cloud Computing Banking Market
Banking
Mobile Banking Market
Banking
Europe Neobanking Market
Banking
Canada Data Analytics in Banking Market
Banking
Machine Learning in Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
US Commercial Banking Market
Banking
US Retail Banking Market
Banking
Merchant Banking Services Market
Banking
Disaster Recovery in Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Australia Data Analytics in Banking Market
Banking
Middle East and Africa Neobanking Market