
 Encapsulated Lactic Acid Market | 2026-2036
Encapsulated Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Lactic Acid Market Foresight
Market Dynamics
REACH is pivoting the cost-of-entry calculus for encapsulated acidulant suppliers seeking European market access. BASF leverages its polymer science heritage to control coating material quality for sustained-release formulations. Cargill anchors North American supply through backward integration into corn-derived lactic acid feedstock. Corbion specializes in fermentation-derived acidulants with tailored encapsulation matrices for bakery applications.
Product Landscape
Encapsulated lactic acid consists of a lactic acid core shielded by lipid, protein, or carbohydrate barrier layers, typically 50-500 microns in diameter, designed to delay acid release until triggered by moisture, pH shift, or mechanical stress. Its primary purpose is to protect acid-sensitive active ingredients, extend shelf stability, and enable targeted delivery in processed foods, pharmaceuticals, and personal care formulations. Spray drying dominates manufacturing scale for commodity powder grades, while coacervation commands premium positioning in pharmaceutical nutrient delivery systems where precise release kinetics determine bioavailability. Encapsulated powder formats lead volume across food preservation applications, whereas bead structures capture margin in probiotic products requiring gastric acid protection.
Regulatory Environment
EMA pharmaceutical guidelines, EFSA food additive safety panels, and ISO 22000 quality management standards collectively govern encapsulation material acceptability and migration limits across European markets. These frameworks compel manufacturers to validate coating integrity and substantiate shelf-life claims through accelerated stability protocols. Stakeholders must monitor evolving ECHA substance restriction proposals that could reclassify common encapsulation polymers and force formulation redesigns ahead of compliance deadlines.
Market Dynamics
REACH compliance deadlines are compressing supplier margins while simultaneously elevating coating material specifications across European probiotic and bakery applications. This regulatory pressure is redistributing market share toward integrated polymer science capabilities and fermentation-derived feedstock control.
Growth Catalysts
- Probiotic shelf-stability mandates:German dairy brands require gastric-acid-resistant encapsulation for live culture viability, pulling lipid-matrix bead demand from Frankfurt contract manufacturers.
- EFSA food additive safety panels:Accelerated approval pathways for fermentation-derived acidulants enable faster formulation turnover in clean-label bakery segments.
- Spray drying scale economies:Commodity powder grades achieve unit cost thresholds that unlock penetration in emerging Asian processed meat preservation.
Market Restraints
- Corn price volatility:Feedstock cost swings compress margin predictability for non-integrated lactic acid producers lacking captive agricultural supply.
- ECHA substance restriction proposals:Pending reclassification of common encapsulation polymers forces preemptive formulation redesign expenditure ahead of compliance deadlines.
- Free acid substitution:Unencapsulated lactic acid retains cost advantage in non-sensitive applications where shelf stability is secondary to acidulant function.
Strategic Opportunities
- Pharmaceutical nutrient delivery:Coacervation precision for bioavailability-critical formulations commands premium positioning in controlled-release supplement markets.
- ISO 22000 certification arbitrage:Quality management standardization enables supplier qualification across pan-European dairy and supplement brand procurement.
- Personal care acidulant protection:Encapsulated formats for pH-sensitive active ingredients in topical formulations remain underdeveloped relative to food applications.
Industry Challenges
- Polymer science talent scarcity:Coating material engineering expertise concentrates at legacy chemical firms, constraining independent encapsulation specialist scale-up.
- Accelerated stability protocol costs:Shelf-life claim substantiation requires capital-intensive environmental chamber infrastructure and analytical validation.
- Legacy spray drying asset retrofit:Existing powder production lines demand modification for bead structure output to serve probiotic gastric protection specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Lactic Acid Market |
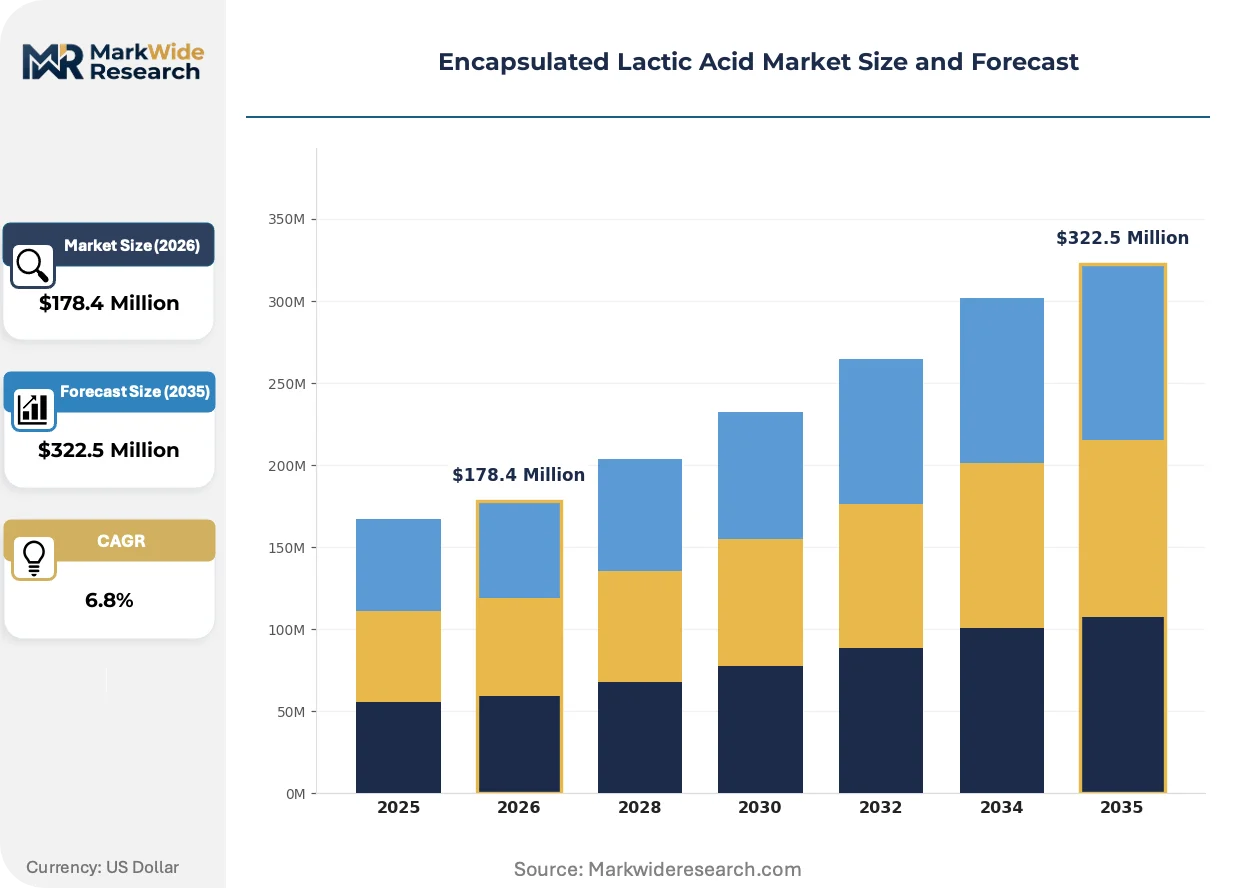
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $322.5 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encapsulated Powder, Liquid, Granules, Beads End User: Food & Beverages, Pharmaceuticals, Personal Care, Bioengineering Application: pH Regulation, Food Preservation, Nutrient Delivery, Probiotic Products Technology: Spray Drying, Coacervation, Extrusion, emulsion |
| Companies Covered | BASF, Cargill, Balchem Corporation, Futerro, NatureWorks, LG Chem, Corbion, Wiberg Canada, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Lactic Acid Market Shifts & Advancements
Encapsulation matrix engineering is converging with precision fermentation to enable acidulant formats that respond to multiple release triggers rather than single-mechanism delivery.
Hybrid protein-lipid coating systems is unifying moisture-triggered and pH-triggered release mechanisms within single particle architectures. Probiotic manufacturers in the Netherlands and Denmark are piloting these dual-responsive formats for intestinal-targeted delivery. The technology is compressing the performance gap between commodity spray-dried powders and pharmaceutical-grade coacervation systems.
EMA pharmaceutical guidelines on excipient functionality are tightening documentation requirements for coating material biocompatibility in nutrient delivery applications. Manufacturers must now validate polymer migration limits through extraction studies rather than compositional declarations alone. Supplement brands sourcing from German functional ingredient clusters are restructuring supplier qualification protocols to accommodate these evidentiary burdens.
Clean-label procurement patterns now disqualify synthetic coating materials from premium positioned product lines regardless of technical performance. Bakery and dairy buyers in France and Italy are substituting carbohydrate-based barrier layers for traditional lipid encapsulation to satisfy ingredient declaration preferences. This specification shift is elevating demand for modified starch and maltodextrin matrix expertise among European contract manufacturers.
Encapsulated Lactic Acid Market Segmentation
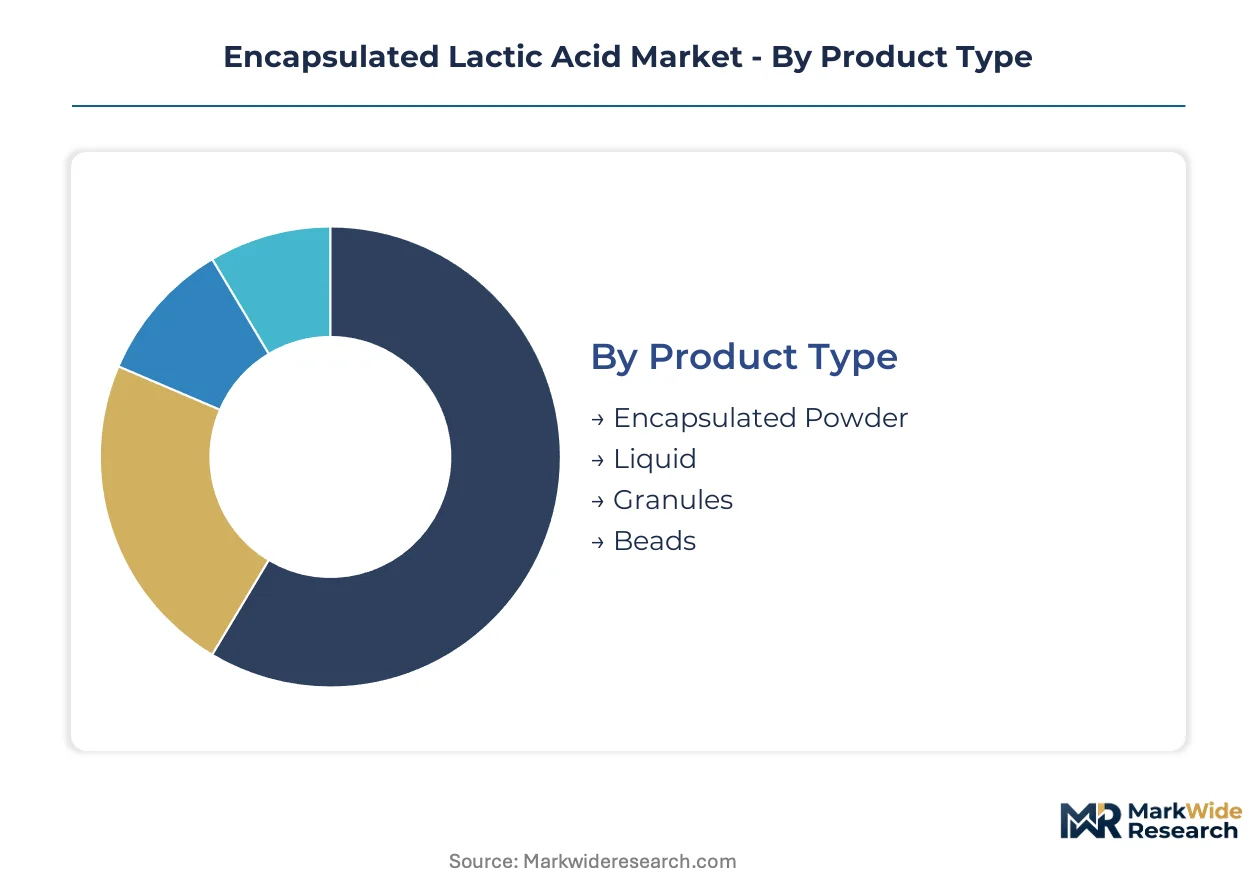
Encapsulated lactic acid markets fragment across four intersecting axes: physical format determines handling economics, end-use dictates regulatory burden, application specifies release kinetics, and manufacturing technology fixes capital intensity. Suppliers must align capability position against these dimensions to avoid margin erosion from specification mismatch.
Product Type:
Physical format selection governs dissolution kinetics, packaging density, and equipment compatibility across downstream processing lines.
- Encapsulated Powder:Spray-dried particles with lipid or carbohydrate coatings dominate commodity food preservation applications. German dairy processors specify powder grades for automated dosing systems in Frankfurt-area contract manufacturing facilities.
- Liquid:Suspension formats suit continuous-flow beverage acidulation where rapid dispersion trumps shelf stability. Cargill's corn-derived feedstock integration supports North American liquid supply security against agricultural price swings.
- Granules:Intermediate particle size bridges powder flowability and bead precision for mid-tier bakery applications. French clean-label buyers increasingly specify carbohydrate-encapsulated granules over synthetic coatings.
- Beads:Lipid-matrix spheres enable gastric-acid-resistant probiotic delivery through pH-triggered release mechanisms. Netherlands and Denmark manufacturers pilot hybrid protein-lipid coatings for intestinal targeting.
Encapsulated powder leads on scale; beads lead on momentum.
End User:
Customer category determines regulatory pathway complexity and quality certification requirements.
- Food & Beverages:Clean-label bakery and dairy segments in France and Italy drive carbohydrate-based encapsulation substitution away from synthetic coatings. EFSA additive safety panels accelerate approval pathways for fermentation-derived acidulants in this segment.
- Pharmaceuticals:EMA excipient functionality guidelines now demand extraction studies for polymer migration validation, not merely compositional declarations. Coacervation precision commands premium positioning in controlled-release supplement markets.
- Personal Care:Topical pH-sensitive active protection remains underdeveloped relative to food applications, presenting white-space opportunity for acidulant barrier technologies.
- Bioengineering:Fermentation process control applications leverage encapsulated acid for bioreactor pH modulation without direct acid addition shock.
Food and beverages leads on scale; pharmaceuticals leads on margin expansion.
Application:
Functional use case determines release trigger specification and coating matrix engineering priorities.
- pH Regulation:Moisture-triggered release dominates processed meat preservation in emerging Asian markets where spray drying scale economies unlock penetration.
- Food Preservation:Acidulant protection of acid-sensitive actives extends shelf stability in ambient distribution channels. REACH purity benchmarks tighten coating material specifications across European supply.
- Nutrient Delivery:Bioavailability-critical formulations require precise release kinetics achievable through coacervation systems. ISO 22000 certification enables supplier qualification across pan-European supplement procurement.
- Probiotic Products:Gastric-acid resistance mandates lipid-matrix encapsulation for live culture viability through stomach transit. German dairy brands source bead specifications from Frankfurt functional ingredient clusters.
Food preservation leads on scale; probiotic products leads on growth velocity.
Technology:
Manufacturing method fixes capital intensity, particle precision, and regulatory documentation burden.
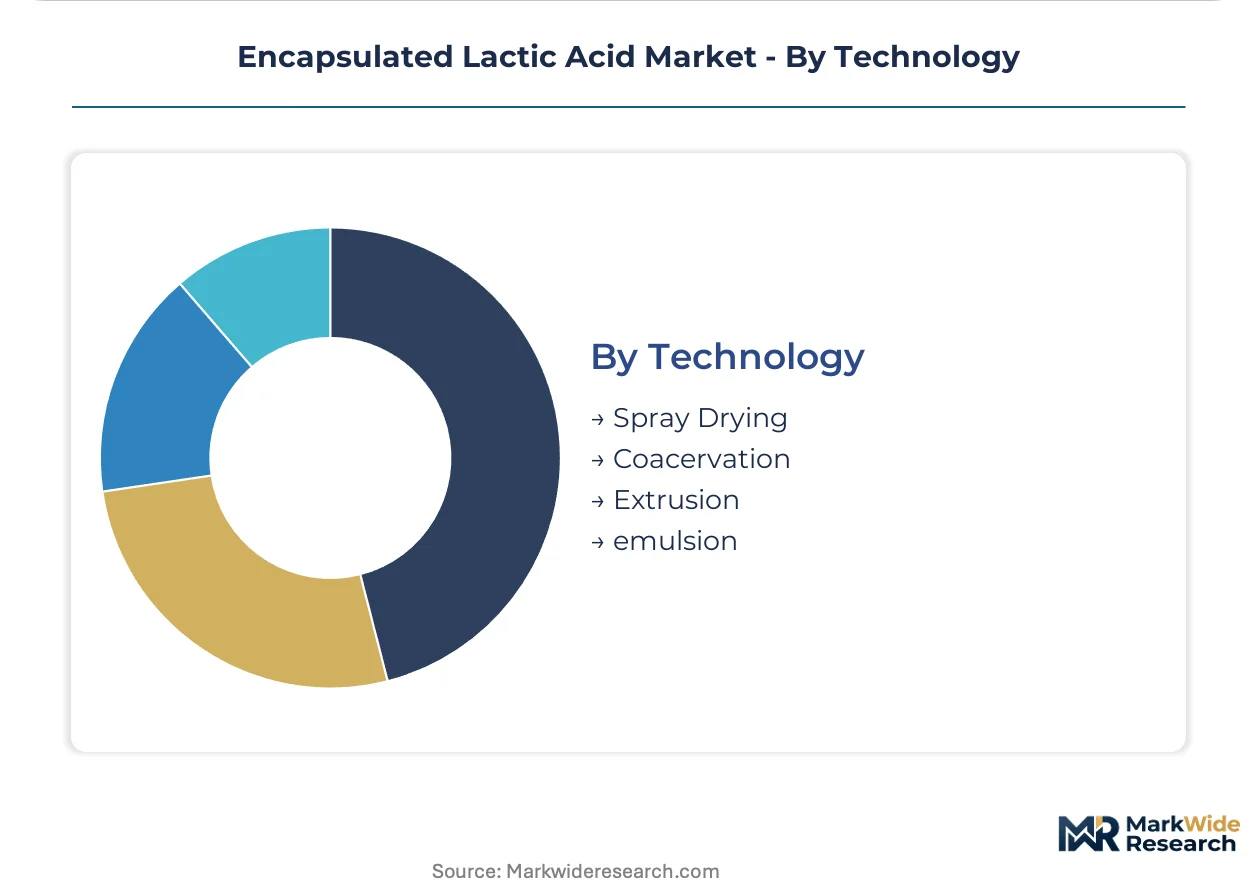
- Spray Drying:Commodity powder production achieves unit cost thresholds for volume applications. Legacy asset retrofit demands modification for bead structure output to serve probiotic specifications.
- Coacervation:Phase-separation precision enables pharmaceutical-grade nutrient delivery with controlled-release kinetics. Polymer science talent scarcity concentrates capability at legacy chemical firms.
- Extrusion:Continuous processing suits high-throughput food applications with moderate precision requirements. Carbohydrate matrix expertise elevates among European contract manufacturers serving clean-label demand.
- Emulsion:Oil-water interface stabilization supports lipid-based encapsulation for moisture-triggered release systems. Hybrid protein-lipid developments converge emulsion and coacervation advantages.
Spray drying leads on scale; coacervation leads on value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer science talent concentrates in Germany's Rhine-Main cluster, where coating material engineering expertise anchors European encapsulation capability. This workforce distribution shapes regional supply hierarchies and determines which markets capture premium formulation margins.
Germany
Frankfurt's functional ingredient cluster supplies pan-European dairy and supplement brands with gastric-acid-resistant bead specifications. REACH compliance deadlines tighten coating material purity benchmarks for probiotic applications. Contract manufacturers in Hesse serve clean-label bakery demand from French and Italian buyers seeking carbohydrate-based encapsulation alternatives.
United States
Corn belt agricultural integration secures lactic acid feedstock supply for North American encapsulation capacity. FDA food additive regulations govern acidulant safety documentation for processed meat preservation applications. Midwest spray drying infrastructure achieves unit cost thresholds that penetrate emerging Asian markets through commodity powder exports.
Netherlands
Dual-responsive hybrid protein-lipid coating systems attract pilot-scale probiotic manufacturing investment from Danish and Dutch nutrition brands. EFSA accelerated approval pathways for fermentation-derived acidulants enable faster clean-label bakery formulation turnover. Rotterdam-area contract manufacturers specialize in moisture-triggered release systems for processed food preservation.
France
Clean-label procurement patterns in Paris and Lyon food manufacturing disqualify synthetic coating materials from premium positioned product lines. ANSM pharmaceutical guidelines on excipient functionality tighten documentation requirements for polymer biocompatibility validation. Auvergne-Rhône-Alpes encapsulation specialists develop modified starch matrix expertise for carbohydrate-based barrier layers.
China
Spray drying scale economies in Yangtze River Delta chemical processing zones target commodity powder penetration in domestic processed meat preservation. SAMR food safety standards govern acidulant additive approvals for bakery and dairy applications. Zhejiang and Jiangsu province manufacturers retrofit legacy powder production lines for bead structure output to serve probiotic gastric protection specifications.
Encapsulated Lactic Acid Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive polymer science capabilities. Three to five legacy firms control premium coating material supply while independent encapsulation specialists struggle to scale without comparable R&D infrastructure. Strategic archetypes include backward-integrated agricultural processors, fermentation-derived acidulant specialists, and diversified chemical conglomerates with polymer matrix expertise. Dominant competitive moves encompass capacity expansion in spray drying assets and strategic partnerships for probiotic-targeted bead manufacturing technology.
Among diversified chemical conglomerates, BASF anchors European coating material quality control through its polymer science heritage, while Dow occupies a comparable position in North American excipient supply. Cargill exemplifies the backward-integrated agricultural processor archetype through its corn-derived lactic acid feedstock control. Corbion represents fermentation-derived specialization with tailored encapsulation matrix capabilities for clean-label applications. These three firms collectively illustrate how feedstock security and polymer engineering expertise determine competitive positioning across spray-dried commodity and precision coacervation market tiers.
| Leading Market Players |
|---|
| BASF |
| Cargill |
| Balchem Corporation |
| Futerro |
| NatureWorks |
| LG Chem |
| Corbion |
| Wiberg Canada |
| Dow |
| Others |
Supply & Pricing Matrix
Spray drying scale economies in commodity powder production are compressing unit costs for emerging market penetration while simultaneously concentrating supply leverage among legacy chemical conglomerates with captive polymer science capabilities. This manufacturing-method transition rewards integrated players who control both lactic acid feedstock and coating material engineering, forcing independent specialists into specification niches where technical differentiation commands premium positioning.
Pricing Analysis
The bundled-vs-unbundled service split separates coating material supply from encapsulation processing, with integrated polymer science providers capturing margin through captive matrix formulation while toll manufacturers compete on volume throughput. Pricing stratifies across pharmaceutical-grade coacervation, food-grade bead structures, and commodity spray-dried powders, with certification tier and release precision as primary differentiation drivers. Cost compression in powder grades is intensifying because Asian processed meat preservation demand pulls supply toward scale economies. Probiotic manufacturers show least price sensitivity due to gastric-acid resistance specifications, whereas commodity food preservation buyers prioritize unit cost above coating sophistication.
Supply Chain Analysis
Direct-to-supplement-brand channels handle German and Dutch probiotic demand, while distributor networks serve fragmented European bakery procurement. Feedstock security draws from corn belt agricultural integration in the United States, fermentation-derived lactic acid specialization in the Netherlands, and petrochemical polymer supply in Germany. Raw material dependencies rest on corn starch for carbohydrate matrices, palm-derived lipids for gastric-resistant coatings, and fermentation feedstocks for clean-label acidulant cores. Single-source vulnerability concentrates in polymer science talent scarcity at legacy chemical firms. Distribution runs through Frankfurt functional ingredient clusters for pan-European dairy supply, with Rotterdam-area contract manufacturers anchoring processed food preservation logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The encapsulated lactic acid market reads as a late-cycle quality story where clean-label procurement patterns and EFSA accelerated approval pathways for fermentation-derived acidulants are elevating specification premiums above commodity cost competition.
For Market Incumbents: Cement polymer science capability gaps through targeted acquisition of coacervation specialists in Germany's Rhine-Main cluster, where talent scarcity constrains independent scale-up. Deepen backward integration into fermentation-derived lactic acid feedstock to defend margin position against corn price volatility and REACH compliance cost compression. Prioritize ISO 22000 certification infrastructure to qualify for pan-European dairy and supplement brand procurement restructuring. For New Entrants and Emerging Players: Contract manufacturing partnerships with Frankfurt-area encapsulation specialists offer lowest-friction entry into probiotic gastric-protection specifications, where German dairy brands source bead formats. Personal care pH-sensitive active protection remains underdeveloped relative to food applications, presenting white-space opportunity for topical acidulant barrier technologies. Target carbohydrate-matrix expertise development to serve French and Italian clean-label bakery substitution away from synthetic lipid coatings. For Investors and Strategic Acquirers: Valuations sit cheapest among independent spray-drying specialists with legacy powder assets requiring bead-structure retrofit for probiotic specifications. Long-term viability over the analysis window favors fermentation-derived acidulant specialists with tailored encapsulation matrix capabilities and EFSA approval pathway momentum. Watch ECHA substance restriction proposal timelines as inflection indicator for preemptive formulation redesign expenditure and polymer reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Corn price volatility mitigation secures margin predictability for REACH-compliant acidulant supply. |
| Coacervation Capability Acquisition | Polymer science talent concentration in legacy chemical firms constrains independent specialist scale-up. |
| ISO 22000 Certification Infrastructure | Quality management standardization enables supplier qualification across pan-European supplement procurement. |
| Hybrid Protein-Lipid Coating Development | Dual-responsive release mechanisms compress the performance gap between commodity powders and pharmaceutical systems. |
| Carbohydrate Matrix Expertise Expansion | Modified starch and maltodextrin capabilities capture French and Italian clean-label bakery specification shifts. |
Research Methodology
Multiple input streams — primary interviews with encapsulation plant managers, procurement leads at German dairy processors, and technical R&D directors at polymer science firms; secondary validation through EFSA additive safety panel records, ECHA substance restriction proposals, and SEC filings from backward-integrated agricultural processors; customs and trade data from European chemical imports — were reconciled through bottom-up and top-down triangulation. Supply-side estimates derived from capacity announcements at Frankfurt-area contract manufacturers and Rotterdam preservation specialists. Demand-side validation incorporated procurement pattern analysis from French clean-label bakery buyers and Dutch probiotic nutrition brands.
Data-stream reconciliation across physical format, end-use category, application function, and manufacturing technology dimensions anchored volume and value projections. Segmentation modeling captured spray drying versus coacervation capital intensity differentials, REACH compliance cost absorption across supplier tiers, and clean-label specification premiums in carbohydrate-matrix substitution. CAGRs were derived from trajectory analysis of fermentation-derived acidulant approval velocities and probiotic shelf-stability mandate adoption curves. Forecast inputs incorporated EMA excipient functionality guideline implementation timelines and ECHA polymer reclassification proposal status.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction decisions, corn price volatility episodes, and polymer science talent migration patterns. Projections reflect assumptions regarding EFSA accelerated pathway continuity, REACH compliance deadline adherence, and clean-label procurement pattern persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Natural Phytosphingosine Market
Specialty Chemicals
Anti-Static Control Products Market