
 United States Pipette Tips Market | 2026-2036
United States Pipette Tips Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pipette Tips Market Analytics
Polypropylene is shifting toward medical-grade virgin resin formulations in pipette tip production, displacing regrind-dependent supply chains that carried contamination risks. Thermo Fisher Scientific leverages its captive resin sourcing to stabilize batch consistency across high-throughput tip lines. Eppendorf sustains premium positioning through precision-molded orifice geometries that reduce coefficient of variation in nanoliter dispensing. Sartorius anchors its US presence with filtered-tip portfolios certified for PCR-grade workflows.
United States pipette tips are precision-molded consumables, typically manufactured from medical-grade polypropylene via injection molding with cavity tolerances below 0.05 millimeters, designed to deliver accurate microliter-to-milliliter liquid transfers in controlled laboratory environments. Filtered tips command premium positioning due to aerosol barrier membranes that prevent cross-contamination in sensitive assays, while non-filtered tips dominate high-volume routine screening where cost-per-tip economics govern procurement. Low-volume tips lead R&D spending as genomic and proteomic workflows push dispensing minima toward sub-microliter precision, and pharmaceutical company end users represent the deepest margin pool due to validated supply requirements and multi-year contractual purchasing.
FDA enforces quality system regulation 21 CFR Part 820 for pipette tips marketed as medical devices, while ISO 8655 standards govern piston-operated volumetric apparatus calibration traceability. EPA Good Laboratory Practice guidelines extend compliance burdens to environmental testing laboratories using these consumables. Stakeholders must monitor evolving USP Chapter 1058 requirements for analytical instrument qualification as lab automation platforms integrate tip-based liquid handlers into continuous validation protocols.
Market Dynamics
Automation migration in US clinical laboratories is compressing demand cycles for pipette tips while elevating precision specifications. FDA 21 CFR Part 820 enforcement and ISO 8655 calibration mandates are forcing resin traceability upgrades that fragment supplier tiers.
Growth Catalysts
- Genomic workflow expansion:Pharmaceutical R&D pipelines in Massachusetts and New Jersey are scaling CRISPR and next-generation sequencing protocols that require sub-microliter dispensing accuracy.
- ISO 13485 compliance mandates:Medical device classification of filtered tips under FDA quality system regulations is accelerating certified supply chain investments.
- PCR-grade certification demand:Diagnostic laboratories are specifying aerosol barrier tips certified for nucleic acid amplification workflows to prevent cross-contamination.
Market Restraints
- Medical-grade polypropylene supply concentration:Virgin resin sourcing depends on a limited base of petrochemical converters with pharmaceutical-grade certification.
- Injection molding capex intensity:Cavity tolerances below 0.05 millimeters require precision tooling that locks out mid-scale entrants.
- Validated supply lock-in:Multi-year contractual purchasing by pharmaceutical end users creates switching friction for secondary suppliers.
Strategic Opportunities
- Low-volume tip specialization:Proteomic workflows pushing toward nanoliter precision create margin expansion potential for precision-molded orifice geometries.
- Environmental testing laboratory segment:EPA Good Laboratory Practice guidelines extend compliance burdens that favor certified tip portfolios.
- Continuous validation protocol integration:USP Chapter 1058 analytical instrument qualification requirements create embedded demand for traceable consumables.
Industry Challenges
- Multi-site calibration standardization:Piston-operated volumetric apparatus traceability across distributed laboratory networks requires centralized metrology investment.
- Legacy liquid handler compatibility:Automated platform integration demands tip geometry standardization that conflicts with proprietary locking mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pipette Tips Market |
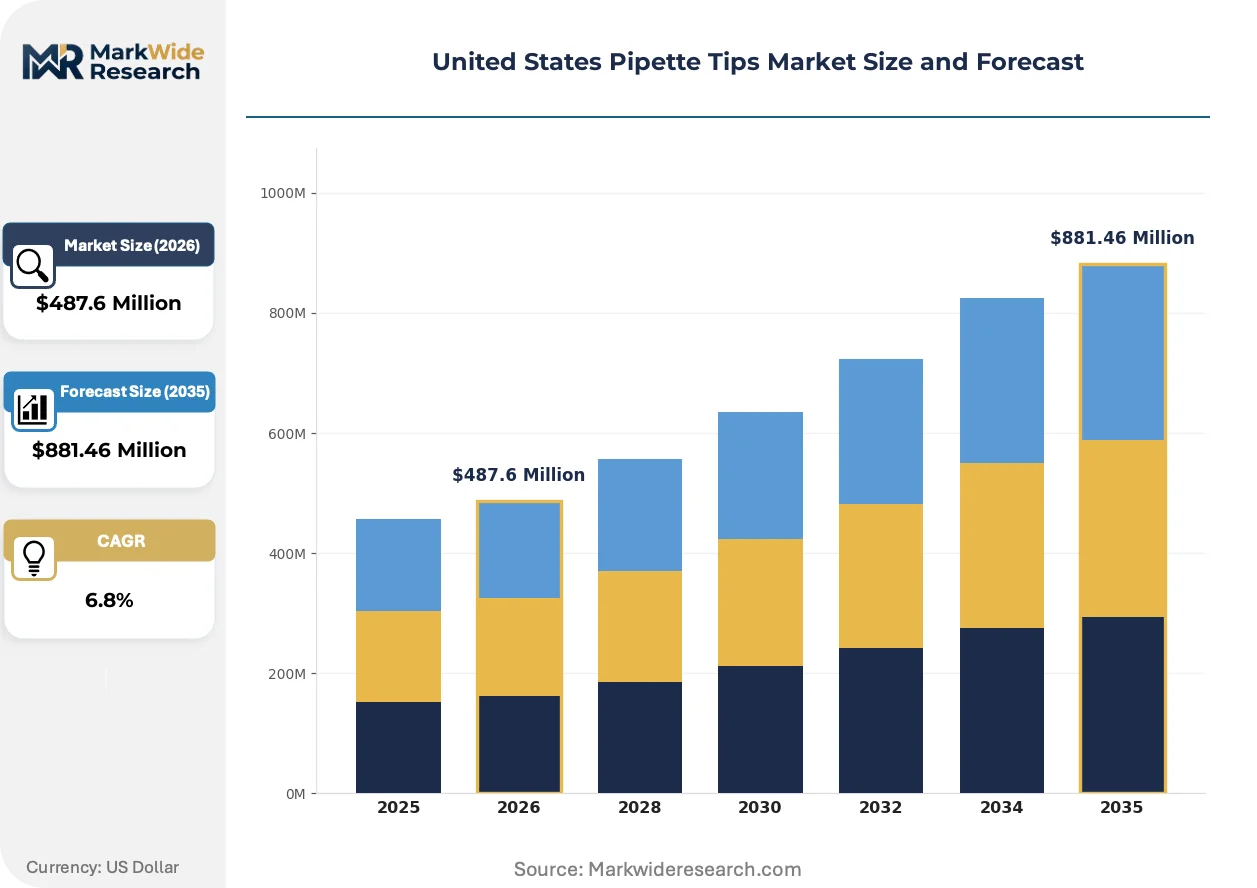
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtered Tips, Non-Filtered Tips, Low-Volume Tips, High-Volume Tips Material: Polypropylene, Polyethylene, Conductive Plastics, Glass Application: Clinical, Research, Environmental, Industrial End User: Laboratories, Hospitals, Educational Institutions, Pharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific, Eppendorf, Sartorius, Corning, Mettler Toledo, Hamilton Company, Gilson, Biotix, Sarstedt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pipette Tips Market Evolving Landscape
Precision molding capabilities and regulatory traceability requirements are bifurcating the US pipette tip supply base into certified premium tiers and commodity screening tiers. Three developments are reshaping competitive positioning.
Medical-grade virgin polypropylene formulations are overtaking regrind-dependent supply chains in pharmaceutical and diagnostic segments. Clinical laboratories in the Northeast corridor are specifying resin batch documentation for PCR workflows. This material transition is compressing margins for converters lacking captive petrochemical relationships.
FDA 21 CFR Part 820 quality system regulation enforcement is tightening device master record requirements for tips marketed as medical devices. Manufacturers must now maintain design history files that trace cavity tolerances to specific injection molding parameters. Filtered tip portfolios face the steepest compliance burden due to aerosol barrier membrane validation protocols.
Consolidated purchasing by pharmaceutical company end users is compressing distributor intermediation in the Northeast and Mid-Atlantic regions. Multi-year contractual frameworks now bundle tip supply with automated liquid handler service agreements. This channel consolidation favors suppliers with integrated logistics capabilities and validated cold-chain documentation.
United States Pipette Tips Market Segmentation
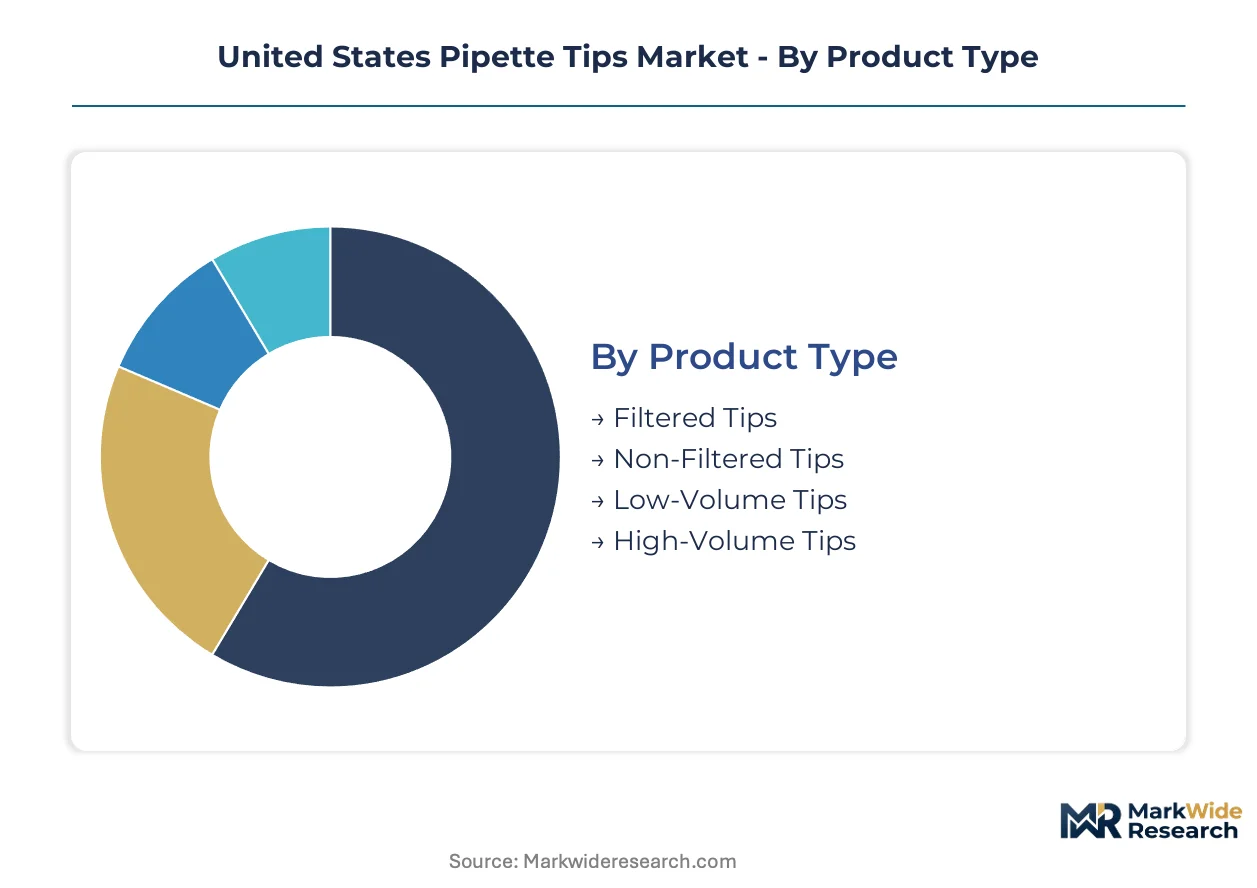
Pipette tip procurement in the United States fragments across performance tiers, material grades, and end-use compliance requirements. Each segmentation dimension carries distinct margin structures and switching costs that reshape supplier positioning.
Product Type:
Filtered tips embed aerosol barrier membranes for contamination-sensitive workflows, while non-filtered variants serve high-throughput screening where cost-per-tip economics dominate. Low-volume and high-volume specifications diverge in precision requirements and automation compatibility.
- Filtered Tips:Hydrophobic polyethylene membranes bonded to polypropylene barrels block aerosol contamination in PCR and cell culture workflows. Massachusetts and New Jersey pharmaceutical clusters specify these for nucleic acid amplification protocols under FDA quality system oversight. ISO 13485-certified supply chains command premium positioning due to device master record traceability mandates.
- Non-Filtered Tips:Standard polypropylene construction without barrier membranes targets high-volume liquid handling in clinical chemistry and drug screening. Northeast contract research organizations procure these in automated platform-compatible racks where cost-per-tip thresholds govern purchasing. Regrind-tolerant resin formulations compete on price in this segment.
- Low-Volume Tips:Precision-molded orifice geometries below 10 microliter nominal capacity serve proteomic and genomic dispensing.
- High-Volume Tips:Milliliter-range capacities support cell culture media transfer and environmental sample aliquoting.
Volume placements concentrate in non-filtered tips; the faster expansion belongs to filtered tips.
Material:
Resin selection determines regulatory pathway and batch consistency. Virgin medical-grade formulations displace regrind-dependent supply chains as FDA traceability requirements tighten.
- Polypropylene:Medical-grade virgin resin dominates pharmaceutical and diagnostic segments due to FDA 21 CFR Part 820 device master record requirements. Captive petrochemical relationships stabilize batch consistency for high-throughput tip lines.
- Polyethylene:Lower density formulations appear in specialized barrier membranes and flexible tip designs.
- Conductive Plastics:Carbon-loaded polymers prevent electrostatic discharge in volatile organic compound handling.
- Glass:Borosilicate construction serves trace metal analysis where polymer contamination risks disqualify plastic tips.
Procurement is shifting toward virgin polypropylene; conductive plastics are gaining share fastest in environmental testing workflows.
Application:
Compliance burdens vary sharply across regulated environments. Clinical and research applications drive premium tier demand, while industrial procurement emphasizes cost efficiency.
- Clinical:Diagnostic laboratories in the Northeast corridor specify PCR-grade certified tips under EPA Good Laboratory Practice guidelines. Automated liquid handler integration demands tip geometry standardization that favors validated supply agreements.
- Research:Academic and government laboratories in Massachusetts and California push dispensing minima toward sub-microliter precision for CRISPR workflows.
- Environmental:Water and soil testing laboratories face GLP documentation burdens that favor certified tip portfolios.
- Industrial:Quality control and manufacturing applications prioritize volume pricing over precision specifications.
Revenue concentrates in clinical applications; research workflows show the steepest expansion trajectory.
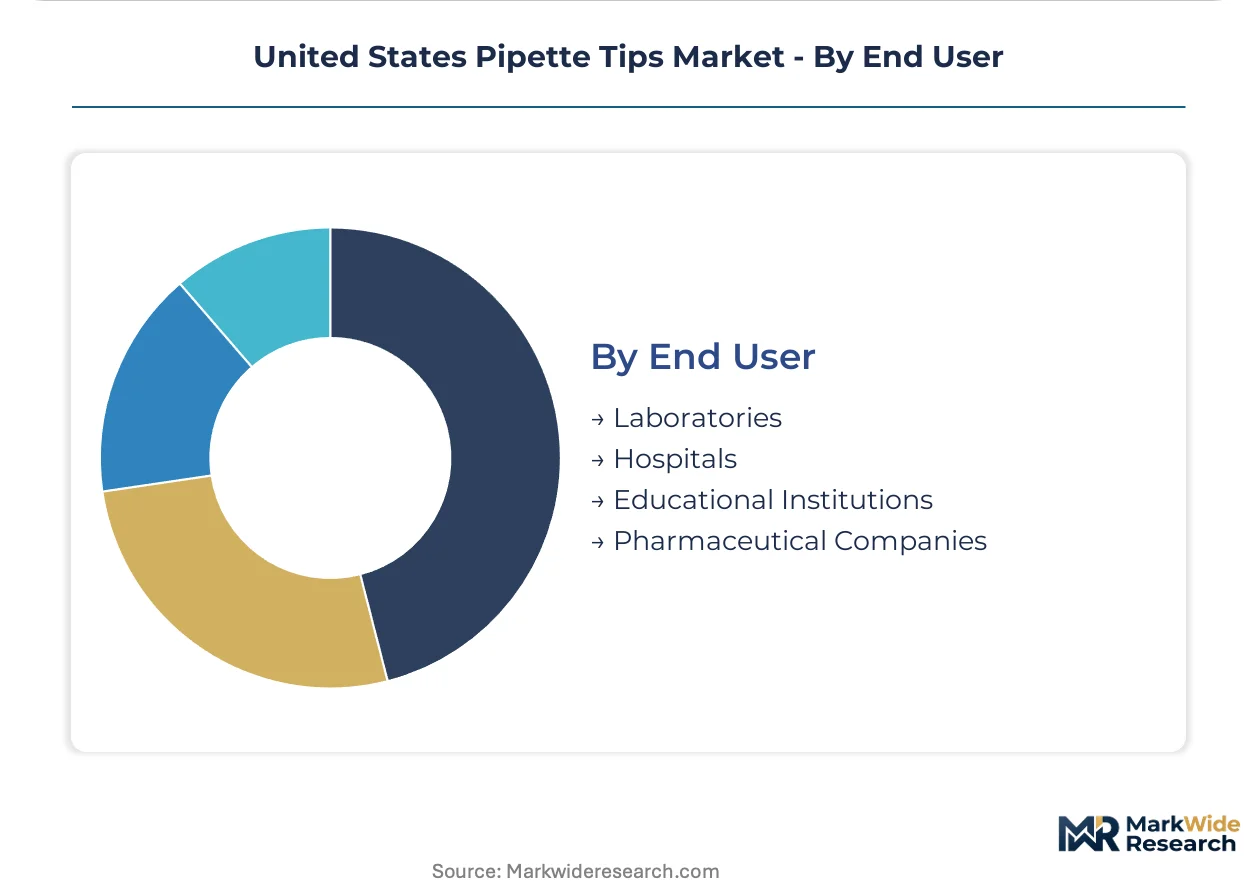
End User:
Purchasing authority and validation requirements fragment the customer base. Pharmaceutical companies lock in multi-year supply agreements, while educational institutions remain price-sensitive spot buyers.
- Pharmaceutical Companies:Validated supply requirements and continuous validation protocols under USP Chapter 1058 embed tip procurement into automated platform service agreements. Multi-year contractual purchasing creates switching friction for secondary suppliers.
- Laboratories:Independent and hospital-affiliated clinical labs balance cost-per-tip economics against aerosol barrier certification needs.
- Hospitals:Centralized supply chains bundle pipette tips with broader laboratory consumables purchasing.
- Educational Institutions:University research programs face budget constraints that favor non-filtered tips and distributor intermediation.
Contract value concentrates in pharmaceutical companies; laboratories represent the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pipette tips concentrates in the Northeast pharmaceutical corridor, where Massachusetts and New Jersey host the densest clusters of genomic research facilities and diagnostic laboratories driving precision consumable procurement.
Northeast Corridor
Massachusetts and New Jersey anchor US demand through CRISPR and next-generation sequencing expansion at pharmaceutical R&D facilities. FDA 21 CFR Part 820 enforcement tightens device master record requirements for tips entering diagnostic workflows. Greater Boston's Kendall Square and New Jersey's Princeton Research Corridor concentrate multi-year contractual purchasing agreements with validated suppliers.
Mid-Atlantic Region
Maryland and Pennsylvania laboratories scale automated liquid handling platforms for clinical chemistry and drug screening applications. EPA Good Laboratory Practice guidelines extend compliance documentation burdens to environmental testing facilities in this zone. Philadelphia's contract research organization cluster drives high-volume non-filtered tip procurement for cost-sensitive screening protocols.
West Coast
California academic and government laboratories push dispensing minima toward sub-microliter precision for proteomic workflows. ISO 8655 calibration mandates govern piston-operated volumetric apparatus traceability across distributed research networks. San Francisco Bay Area biotech clusters specify low-volume tips with precision-molded orifice geometries for genomic applications.
Southwest
Texas medical centers and research institutes expand PCR-grade certified tip inventories for nucleic acid amplification diagnostics. USP Chapter 1058 analytical instrument qualification requirements embed consumable procurement into continuous validation protocols. Houston's Texas Medical Center represents the largest hospital-affiliated laboratory demand concentration outside the Northeast.
Midwest
Illinois and Ohio pharmaceutical manufacturing quality control operations prioritize validated supply chains for batch release testing. OSHA laboratory safety standards intersect with FDA quality system regulations in this industrial laboratory segment. Chicago's contract manufacturing organization cluster sustains steady demand for filtered tips with aerosol barrier membranes.
United States Pipette Tips Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers invest in precision injection molding infrastructure to meet tightening cavity tolerance requirements below 0.05 millimeters. The vendor base stratifies into three tiers: integrated life science conglomerates with captive resin sourcing, precision-molding specialists focused on low-volume genomic applications, and regional converters serving cost-sensitive screening segments. M&A activity and strategic partnerships represent the primary competitive vectors, with acquisition targets clustering around ISO 13485-certified manufacturing assets and automated platform integration capabilities.
Among integrated life science suppliers, Thermo Fisher Scientific exemplifies the conglomerate archetype through its captive petrochemical relationships stabilizing batch consistency. Eppendorf occupies a position within the precision-molding specialist tier, while Sartorius anchors the filtered-tip certification segment. These three entities collectively represent the competitive positioning spectrum: scale-driven resin integration, geometric precision specialization, and regulatory-certified portfolio depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf |
| Sartorius |
| Corning |
| Mettler Toledo |
| Hamilton Company |
| Gilson |
| Biotix |
| Sarstedt |
| Others |
Value Network & Pricing Analysis
Pharmaceutical company procurement committees in Massachusetts and New Jersey govern pricing outcomes through multi-year contractual frameworks that bundle pipette tip supply with automated liquid handler service agreements. This buyer concentration compresses distributor intermediation and embeds cost-per-tip economics into platform-level negotiations.
Pricing Analysis
High-volume non-filtered tips compete on cost-per-tip thresholds in contract research organization screening protocols, while filtered tips with PCR-grade certification command premium positioning through ISO 13485 traceability mandates. Price differentiation stems from resin batch documentation requirements and aerosol barrier membrane validation protocols. Pricing pressure intensifies in the standard tier as regrind-tolerant resin formulations from regional converters undercut virgin medical-grade supply. Educational institutions represent the most price-sensitive segment, while pharmaceutical end users prioritize validated supply continuity over unit cost.
Supply Chain Analysis
Medical-grade polypropylene supply rests on a limited base of domestic petrochemical converters with pharmaceutical-grade certification, supplemented by specialized resin imports from Germany and Japan. Raw material dependencies center on virgin propylene feedstock, precision injection molding tooling with cavity tolerances below 0.05 millimeters, and hydrophobic polyethylene for barrier membranes. Single-source vulnerability concentrates in FDA-audited resin batch documentation systems. Distribution runs through integrated life science conglomerates with captive logistics networks and validated cold-chain documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States pipette tips market sits in a material-transition phase as medical-grade virgin polypropylene displaces regrind-dependent supply chains, with precision-molded low-volume geometries replacing legacy high-tolerance tooling.
For Market Incumbents: Extend ISO 13485-certified manufacturing footprints in the Northeast corridor to capture multi-year pharmaceutical contractual frameworks. Lock in captive petrochemical relationships that stabilize batch consistency against resin supply fragmentation. Counter emerging precision-molding specialists through integrated automated platform service agreements that embed tip procurement into liquid handler maintenance contracts.
For New Entrants and Emerging Players: FDA 21 CFR Part 820 enforcement in the United States opens a window for ISO 13485-certified manufacturing assets targeting PCR-grade filtered tip segments underserved by incumbent capacity constraints. Penetrate the environmental testing laboratory segment in the Mid-Atlantic region where EPA Good Laboratory Practice documentation burdens favor certified tip portfolios. Pursue white-label partnerships with automated liquid handler OEMs seeking secondary supply sources for platform-compatible tip geometries.
For Investors and Strategic Acquirers: The window for entry favors precision-molding specialists with validated low-volume tip capabilities and established automated platform integration relationships. Long-term viability hinges on consolidation plays around ISO 13485-certified manufacturing assets as regulatory traceability requirements tighten. Monitor resin batch documentation system investments as the inflection indicator for supply chain control quality.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | FDA quality system regulation enforcement elevates device master record traceability as a competitive barrier. |
| Captive Resin Sourcing Agreement | Medical-grade virgin polypropylene supply concentration rewards backward integration into petrochemical relationships. |
| Precision Molding Capacity Expansion | Genomic workflows pushing toward nanoliter precision require cavity tolerances below 0.05 millimeters. |
| Automated Platform Integration Partnership | Liquid handler OEM service agreements embed tip procurement into continuous validation protocols under USP Chapter 1058. |
| PCR-Grade Portfolio Certification | Diagnostic laboratories in the Northeast corridor specify aerosol barrier tips for nucleic acid amplification workflows. |
Research Methodology
Document review covered FDA 21 CFR Part 820 quality system regulation filings, ISO 13485 certification databases, and EPA Good Laboratory Practice guidance documents, complemented by interviews with laboratory operations directors at pharmaceutical R&D facilities, procurement managers at hospital-affiliated clinical laboratories, and technical directors at contract research organizations. Secondary validation drew from customs trade data, SEC filings of integrated life science conglomerates, and regional economic development authority reports on Northeast pharmaceutical corridor expansion. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, and end-use segmentation dimensions.
Cross-referencing historical procurement patterns against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include filtered versus non-filtered construction, virgin versus regrind resin formulations, clinical versus research versus environmental application contexts, and pharmaceutical company versus laboratory versus educational institution end-user categories. CAGRs were derived from trend extrapolation of automation migration rates and regulatory compliance investment cycles, with genomic workflow expansion and ISO 8655 calibration mandate enforcement as key forecast inputs.
The model assumes a particular technology adoption path for precision-molded low-volume tips; alternative pathways for additive manufacturing or novel polymer formulations would alter the outlook for incumbent injection molding specialists. Forecasts reflect assumptions regarding FDA enforcement continuity and resin supply stability that warrant sensitivity testing. A small set of named triggers—including FDA audit intensity shifts, medical-grade polypropylene supply disruptions, and automated liquid handler platform standardization decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Electronic Multichannel Pipettes Market