
 US Healthcare Professional Training Market | 2026-2036
US Healthcare Professional Training Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Professional Training Market Insights
The Affordable Care Act's quality reporting mandates is repositioning how health systems budget for workforce development. Adtalem Global Education leverages its institutional scale to serve nursing schools and hospital networks nationwide. Ascend Learning anchors the allied health certification segment through its assessment and learning platforms. BIOLASE specializes in laser dentistry training, carving a defensible niche within dental continuing education.
Healthcare professional training encompasses structured educational programs designed to maintain, upgrade, or verify clinical competencies through standardized curricula, simulation-based assessments, and measurable outcome tracking. These programs integrate didactic instruction with hands-on procedural validation to reduce medical errors and ensure compliance with evolving care protocols. Certification courses command premium pricing due to their linkage with licensure renewal and hospital privileging requirements. Virtual learning is expanding fastest among rural and shift-based clinicians who cannot access centralized instruction. Specialty training in technology integration is attracting new entrants as AI-assisted diagnostics and robotic surgery systems proliferate across US hospitals.
FDA oversees device-specific training tied to high-risk equipment approvals, while state medical boards and nursing boards set continuing education hour minimums that create baseline demand. OSHA and HIPAA frameworks further mandate annual compliance training for all patient-facing personnel. Stakeholders must track how Medicare reimbursement adjustments and state-level scope-of-practice expansions reshape which professions require advanced credentials and which delivery formats qualify for credit.
Market Dynamics
Hospital system consolidation across Texas and Florida is centralizing training procurement decisions into fewer hands, compressing vendor margins while demanding scalable, competency-validated curricula that integrate with electronic health record systems.
Growth Catalysts
- OSHA and HIPAA annual mandates:Federal compliance frameworks create baseline demand for standardized training modules across all patient-facing personnel, ensuring recurring revenue streams for accredited providers.
- AI-assisted diagnostics proliferation:US hospitals deploying machine learning imaging tools require specialized certification tracks that validate clinician competency in algorithm-assisted interpretation protocols.
- State medical board redesign:Competency-based education requirements under evolving state guidelines force curriculum overhauls that favor vendors with assessment infrastructure.
Market Restraints
- Simulation equipment cost volatility:High-fidelity manikins and virtual reality hardware face semiconductor supply constraints that inflate capital expenditure for training program launches.
- State licensing reciprocity friction:Inconsistent continuing education credit recognition across state nursing boards complicates national rollout strategies for standardized curricula.
- Substitute learning formats:Free hospital-developed in-house modules and open-source medical education platforms erode pricing power for commercial certification vendors.
Strategic Opportunities
- Rural clinician access gaps:Shift-based nurses and physicians in non-urban markets lack centralized training access, creating white space for asynchronous virtual platforms with mobile-optimized delivery.
- Robotic surgery credentialing:Intuitive Surgical da Vinci systems and competing platforms require vendor-specific certification tracks that lock in training provider relationships.
- Medicare reimbursement adjustments:Quality reporting mandates tied to hospital value-based purchasing programs expand budgets for workforce development initiatives that demonstrate measurable outcome improvements.
Industry Challenges
- Instructional design talent scarcity:Clinical educators with dual competency in pedagogy and simulation technology command premium wages that compress program margins.
- Legacy learning management integration:Health system IT architectures built on decade-old platforms resist API connectivity with modern competency-tracking systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Professional Training Market |
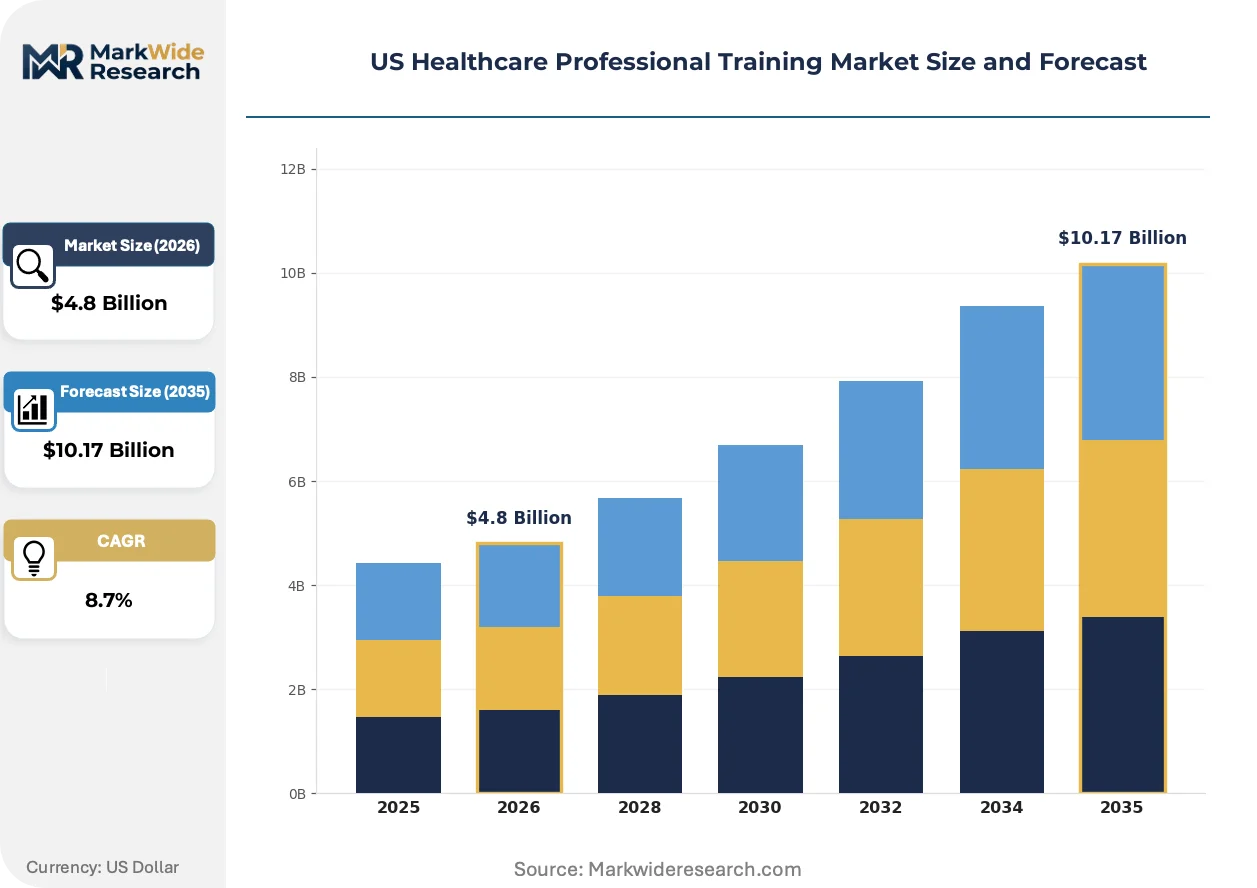
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Certification Courses, Online Tutorials, Workshops, Specialty Training Delivery Mode: In-Person, Virtual Learning, Hybrid, Self-Paced Target Audience: Nurses, Physicians, Allied Health Professionals, Medical Students Content Focus: Patient Safety, Clinical Skills, Ethics, Technology Integration |
| Companies Covered | Spear Education, R3 Medical Training, Adtalem Global Education, Lumis Corp, Xel Care, Ascend Learning, BIOLASE, American College of Healthcare Executives (ACHE), Orbis Education, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Professional Training Market Trends and Innovations
Virtual reality simulation is compressing the cost structure of procedural training while expanding access to rare-case exposure, fundamentally altering how hospitals validate clinician readiness before live patient contact.
Immersive VR modules for emergency response and surgical rehearsal are decentralizing training delivery away from centralized simulation centers toward individual headset-based learning at the point of need. Rural health systems and community hospitals lacking capital for physical labs adopt these platforms fastest, enabling competency validation without travel burden. This technology shift is decentralizing market power from academic medical centers with established simulation infrastructure toward software vendors with scalable cloud-based assessment architectures.
FDA device-specific training requirements for high-risk equipment approvals create mandatory curriculum linkages that vendors must satisfy before market entry. Manufacturers of robotic surgical systems, advanced imaging modalities, and interventional devices face pre-market stipulations for validated instruction protocols. The dental laser segment exemplifies this most acutely, where BIOLASE and competitors must embed training modules into product commercialization timelines.
Health system procurement departments now bundle training contracts with medical device purchases and enterprise software licenses, unbundling standalone education vendor relationships. Hospital value analysis committees demand proof of outcome linkage before renewing annual training subscriptions, favoring platforms with embedded analytics dashboards. This purchasing evolution concentrates most visibly in consolidated Texas and Florida systems where centralized sourcing teams negotiate multi-year enterprise agreements spanning clinical and non-clinical workforce development.
US Healthcare Professional Training Market Segmentation
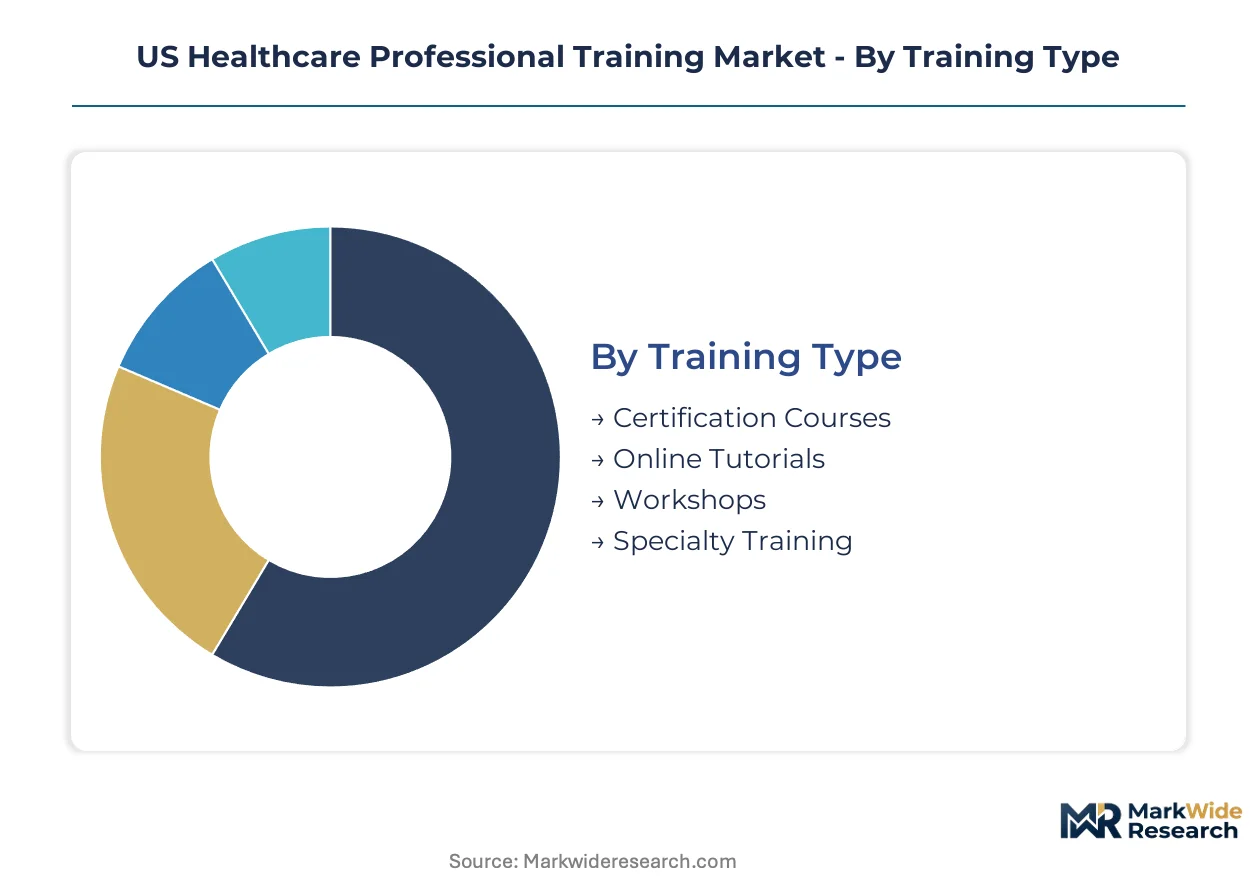
Procurement decisions across US hospital systems diverge sharply by training format, with compliance mandates and workforce scheduling constraints dictating budget allocation. Understanding segment-level demand concentration reveals where vendor margins compress and where pricing power endures.
Training Type:
Hospital value analysis committees weight training investments against measurable outcome linkage, privileging formats with embedded competency validation.
- Certification Courses:Structured programs tied to licensure renewal and hospital privileging requirements command premium pricing through mandatory enrollment. Demand concentrates in Texas and Florida health system consolidations where centralized procurement teams negotiate multi-year enterprise agreements spanning clinical workforce development.
- Specialty Training:Vendor-specific credentialing for robotic surgical systems and AI-assisted diagnostics creates locked-in training provider relationships. Hospital systems deploying Intuitive Surgical da Vinci platforms require completion of manufacturer-validated instruction protocols before clinician privileging.
- Online Tutorials:Asynchronous modules serve rural and shift-based clinicians lacking centralized access, though pricing pressure intensifies from free hospital-developed alternatives.
- Workshops:Short-form intensive sessions address emergent protocol updates and annual OSHA compliance refreshers with lower per-seat economics.
Volume sits with Certification Courses; growth tilts toward Specialty Training.
Delivery Mode:
Capital expenditure constraints and IT architecture limitations reshape how health systems consume educational content across their distributed workforces.
- Virtual Learning:Cloud-based platforms with mobile-optimized delivery expand fastest among community hospitals and rural health systems lacking physical simulation infrastructure. FDA device-specific training requirements for high-risk equipment increasingly embed validated virtual modules into product commercialization timelines.
- Hybrid:Blended formats combining asynchronous didactic instruction with in-person procedural validation satisfy state medical board competency-based education redesigns. Nursing schools and hospital networks favor this structure for its flexibility across shift-based scheduling constraints.
- In-Person:High-fidelity simulation centers at academic medical centers retain dominance for rare-case exposure and emergency response rehearsal despite semiconductor supply constraints inflating manikin costs.
- Self-Paced:Individual headset-based learning at the point of need decentralizes training delivery away from centralized simulation centers, compressing cost structures for procedural validation.
Procurement volumes favor Hybrid delivery; Virtual Learning climbs the fastest as rural access gaps widen.
Target Audience:
Scope-of-practice expansions and Medicare reimbursement adjustments reshape which professions require advanced credentials and which delivery formats qualify for credit.
- Nurses:Mandatory training budgets expand under hospital system consolidation, with competency tracking integrated into electronic health record systems. State nursing board continuing education hour minimums create baseline demand for accredited providers across all delivery formats.
- Physicians:State medical board guidelines accelerating curriculum redesign concentrate demand among vendors with assessment infrastructure capable of outcome documentation.
- Allied Health Professionals:Certification segments anchor demand through assessment and learning platforms tied to licensure renewal cycles.
- Medical Students:Structured educational programs with simulation-based assessments reduce medical errors before live patient contact, though procurement decisions remain tethered to academic institutional budgets.
Enrollment volume concentrates with Nurses; steepest expansion trajectory belongs to Allied Health Professionals as scope-of-practice boundaries shift.
Content Focus:
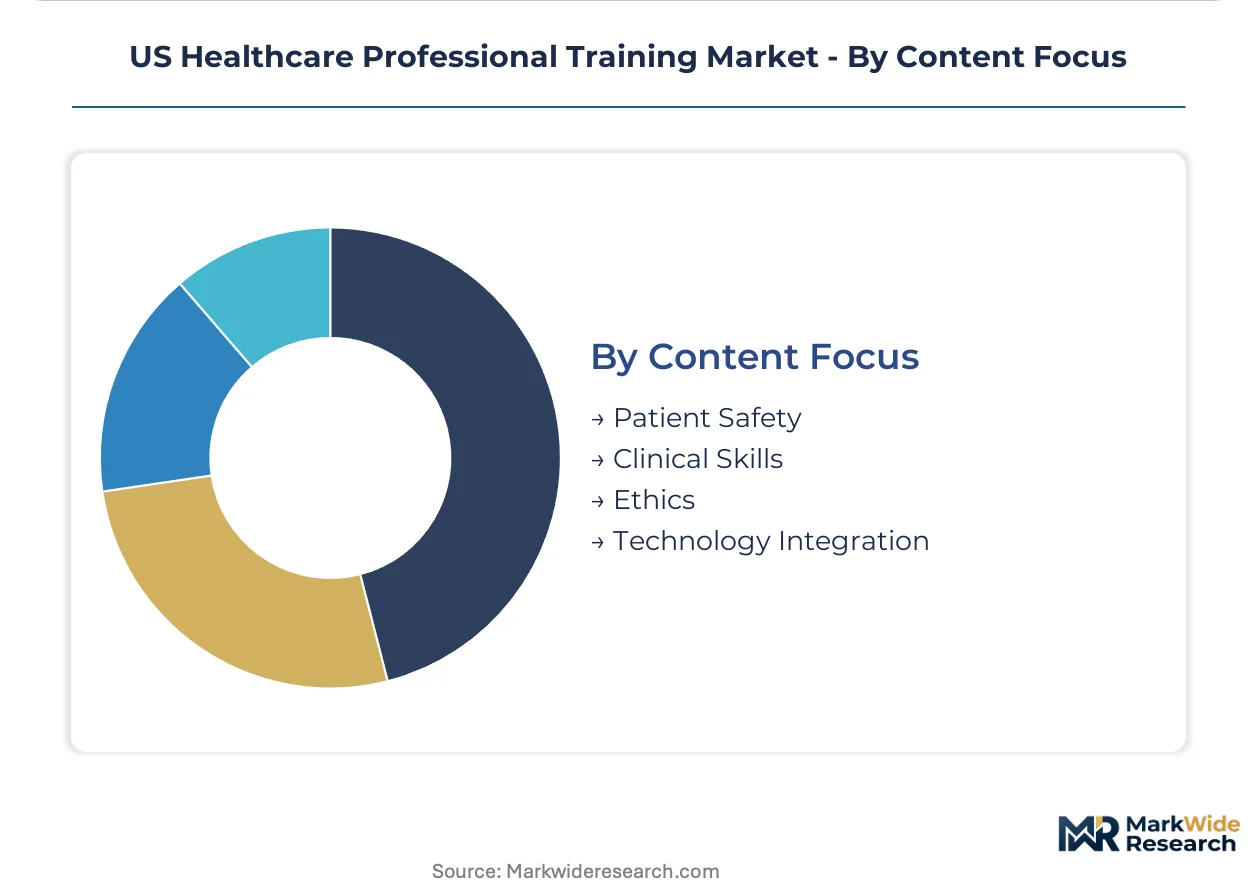
Quality reporting mandates tied to hospital value-based purchasing programs expand budgets for workforce development initiatives demonstrating measurable outcome improvements.
- Technology Integration:AI-assisted diagnostics and robotic surgery systems proliferating across US hospitals attract new training entrants. FDA oversight of device-specific instruction creates mandatory curriculum linkages vendors must satisfy before market entry.
- Patient Safety:Annual compliance frameworks including OSHA and HIPAA mandates ensure recurring revenue streams for standardized modules across all patient-facing personnel.
- Clinical Skills:Procedural validation through hands-on assessment remains essential for hospital privileging, though virtual reality simulation compresses traditional cost structures.
- Ethics:Standardized curricula address evolving care protocols and end-of-life decision-making frameworks with lower differentiation among competing providers.
Budget allocation heaviest for Patient Safety; Technology Integration gains share fastest as AI deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of training content concentrates in established education hubs, while consumption spreads across decentralized hospital networks. Texas and Florida absorb disproportionate procurement volume through health system consolidations. California and the Northeast corridor anchor curriculum development capacity.
Texas
Hospital system consolidations in Dallas-Fort Worth and Houston drive centralized training procurement into fewer decision-making units. State medical board guidelines under the Texas Medical Board accelerate competency-based education requirements for physician licensure renewal. The Texas Medical Center in Houston anchors simulation-based curriculum development for cardiovascular and trauma specialties.
Florida
Large health system mergers across Tampa Bay and South Florida compress vendor margins while demanding scalable EHR-integrated training platforms. Florida Board of Nursing continuing education hour minimums create baseline demand for accredited providers across all delivery formats. The Orlando health corridor concentrates medical simulation manufacturing and VR content development for emergency response training.
California
Academic medical centers in Los Angeles and San Francisco retain dominance for rare-case exposure through high-fidelity simulation infrastructure. OSHA and Cal/OSHA dual compliance frameworks mandate annual safety training for all patient-facing personnel across hospital networks. The Bay Area technology corridor supplies AI-assisted diagnostics training platforms to health systems nationwide.
New York Metro
Academic institutional budgets in Manhattan and Brooklyn tether medical student training procurement to university-affiliated hospital systems. New York State Education Department regulations govern nursing school accreditation and curriculum standards for entry-level programs. The Greater New York Hospital Association coordinates group purchasing for workforce development initiatives across member institutions.
Midwest (Illinois/Ohio/Michigan)
Community hospitals in Chicago and Cleveland adopt virtual learning platforms fastest due to capital constraints on physical simulation labs. State nursing boards in Illinois and Ohio maintain inconsistent continuing education credit recognition that complicates national curriculum rollouts. The Cleveland Clinic anchors specialty training in robotic surgery credentialing for da Vinci system deployment.
US Healthcare Professional Training Market Competitive Landscape
The competitive structure tilts toward institutional-scale education providers with assessment infrastructure. Market concentration remains moderate, with national players serving hospital networks alongside regional specialists addressing niche certification segments. Three archetypes dominate: diversified education conglomerates with nursing school relationships, device-anchored training vendors tied to FDA-mandated instruction protocols, and simulation technology platforms with cloud-based delivery architectures. Competitive moves center on multi-year enterprise agreement negotiations with consolidated health systems and curriculum bundling with medical device purchases.
Within the institutional education tier, Adtalem Global Education and Ascend Learning occupy positions serving nursing schools and hospital networks with national reach. Among device-anchored specialists, BIOLASE exemplifies the FDA-tethered training model where laser dentistry instruction embeds into product commercialization timelines. These three companies represent the dominant competitive archetypes: scale-driven institutional platforms, assessment-anchored certification providers, and regulatory-mandated device training vendors.
| Leading Market Players |
|---|
| Spear Education |
| R3 Medical Training |
| Adtalem Global Education |
| Lumis Corp |
| Xel Care |
| Ascend Learning |
| BIOLASE |
| American College of Healthcare Executives (ACHE) |
| Orbis Education |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between hospital-mandated credentialing and discretionary professional development manifests in both subscription pricing power and content sourcing concentration. Premium vendor relationships with Texas and Florida health system consolidations command multi-year enterprise terms, while commodity online modules face margin compression from hospital-developed substitutes.
Pricing Analysis
Margin tightening in certification courses reflects procurement centralization at consolidated health systems compressing vendor economics. Three-tier pricing structure across enterprise, institutional, and individual levels tracks enrollment scale and EHR integration depth. Cost compression in asynchronous virtual modules accelerates because free hospital-developed alternatives erode pricing power. Hospital value analysis committees exhibit highest price sensitivity for annual compliance refreshers, while robotic surgery credentialing maintains lowest sensitivity due to FDA-mandated vendor lock-in.
Supply Chain Analysis
VR hardware supply rests on Taiwanese semiconductor foundries and Chinese electronics assembly capacity feeding US-based content development. Cloud infrastructure draws from AWS, Azure, and Google data centers concentrated in Virginia, Oregon, and Iowa. Single-source vulnerability in high-fidelity manikin manufacturing from Norway and Germany inflates capital expenditure timelines. Distribution runs through health system GPO contracts and direct enterprise licensing with academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instructional design talent scarcity props pricing for competency-validated curricula across the projection horizon. Hospital system consolidation concentrates procurement leverage while specialized certification tracks retain vendor margin protection.
For Market Incumbents: Lock in multi-year enterprise agreements with Texas and Florida health system consolidations before procurement centralization completes. Deepen backward integration into VR content development studios to defend against simulation technology platform entrants. Prioritize API connectivity investments to reduce legacy learning management integration friction that extends implementation timelines.
For New Entrants and Emerging Players: Begin with rural clinician access gaps in Midwest community hospitals lacking capital for physical simulation labs. Target shift-based nursing segments with mobile-optimized asynchronous delivery formats. Pursue hospital system partnership structures that bundle training contracts with medical device purchases and enterprise software licenses.
For Investors and Strategic Acquirers: Re-rating potential sits with assessment-anchored certification providers given state medical board competency-based education redesigns accelerating curriculum overhaul demand. Long-term viability favors platforms with embedded analytics dashboards demonstrating measurable outcome linkage for value-based purchasing compliance. Watch Medicare reimbursement adjustment announcements as inflection indicators for workforce development budget expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year enterprise agreements with Texas and Florida consolidations lock in recurring revenue streams. |
| FDA Submission Alignment | Device-specific training module validation satisfies pre-market stipulations for robotic surgical system manufacturers. |
| VR Content Development Acquisition | Specialized simulation studios compress cost structures for procedural training delivery at scale. |
| Platform Integration Investment | API connectivity with Epic and Cerner EHR systems reduces implementation friction for health system clients. |
| Reimbursement Strategy Development | Quality reporting documentation aligns training investments with hospital value-based purchasing program requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital CNOs, GPO contracts managers, biomedical engineers, and simulation technology procurement leads combined with secondary validation from FDA 510(k) filings, state medical board continuing education requirements, and hospital procurement databases. Bottom-up enrollment modeling and top-down health system budget allocation analysis provided triangulation across the projection horizon.
Data-stream reconciliation across training format segmentation, delivery mode adoption curves, and target audience enrollment patterns shaped the analytical framework. Segmentation dimensions modeled include certification type, delivery architecture, clinical role, and content focus area across the analysis window. CAGRs derived from health system budget growth trajectories and state-level scope-of-practice expansion timelines. Industry-specific forecast inputs incorporated Medicare reimbursement adjustment schedules and FDA device approval pipelines.
State licensing reciprocity friction, simulation equipment cost volatility, and substitute learning format proliferation are the dominant revision risks. Forecasts reflect assumptions regarding health system consolidation pace and competency-based education mandate adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Healthcare Predictive Analytics Market
Healthcare
Global Anti-Snoring Devices and Snoring Surgery Market
Healthcare
Pacemaker/Defibrillator Lead Extraction Kits Market
Healthcare
Global Smart Contact Lenses Market
Healthcare
Global Local Anesthesia Drugs Market
Healthcare
In Vitro Diagnostic (IVD) Reagent Market
Healthcare
Intracranial Aneurysm Market
Healthcare
Europe Nerve Repair and Regeneration Market
Healthcare
Home Respiratory Therapy Market
Healthcare
Oxygen Concentrators Market
Healthcare
Blood Urea Nitrogen Testing Market
Healthcare
Global Anthrax Vaccine Market
Healthcare
Medical 3D Software Market
Healthcare
Global Positive Airway Pressure Market
Healthcare
Japan Diagnostic Imaging Market
Healthcare
Iceland Pharmaceutical Market