
 Steam Cleaners Market | 2026-2036
Steam Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Cleaners Market Outlook
E-commerce platforms and direct-to-consumer channels are reshaping how steam cleaners reach end users. Kärcher leverages its established dealer network across Europe to sustain brand loyalty in the commercial segment. SharkNinja competes aggressively through Amazon-exclusive launches and social media marketing, while Polti anchors its position in Southern Europe through specialty retail partnerships with appliance chains.
Steam cleaners generate saturated or superheated vapor, typically between 100°C and 180°C, to dissolve grease and sanitize surfaces without chemical detergents. The equipment serves industrial degreasing, medical sterilization prep, and residential deep-cleaning applications where chemical residue poses health or regulatory risks. Cylinder and multi-purpose units dominate commercial procurement due to higher pressure ratings and extended duty cycles, whereas handheld models capture residential trade-down demand. Dry vapor technology leads in healthcare and food-service settings where rapid surface drying prevents microbial regrowth, while continuous-fill systems gain traction in facilities management for uninterrupted operation.
EPA Safer Choice certification and REACH chemical restrictions in Europe elevate steam-based methods over solvent-dependent alternatives. OSHA workplace exposure limits and FDA sanitation guidelines for food-contact surfaces further embed vapor cleaning in regulated environments. Stakeholders must track evolving energy-efficiency standards and water-usage regulations, as these will determine which heating systems and boiler designs retain market access across jurisdictions.
Market Dynamics
EPA Safer Choice certification and REACH chemical restrictions are compressing solvent-dependent cleaning methods while elevating water-based vapor sanitization across regulated facilities. Healthcare systems and commercial kitchens now face binding exposure limits that favor high-temperature steam over chemical alternatives.
Growth Catalysts
- Hospital-grade sterilization prep:United States healthcare facilities are expanding vapor-based surface preparation ahead of terminal sterilization cycles to meet Joint Commission accreditation standards.
- REACH chemical restrictions:European industrial cleaning standards now favor high-temperature vapor sanitation over solvent-dependent degreasing in metal fabrication and food processing plants.
- Commercial kitchen regulations:Germany's strict hygiene codes for food-service operations mandate documented thermal sanitation protocols that cylinder steam units deliver.
Market Restraints
- Copper and aluminum input volatility:Boiler and heating element manufacturing depends on base metal prices that fluctuate with energy and mining supply disruptions.
- Heating system supplier concentration:Specialized boiler component production clusters in Northern Italy and Southern Germany create geographic concentration risk for OEM sourcing.
- Water hardness limitations:Continuous-fill systems face scale buildup and maintenance intervals that shorten operational life in hard-water regions without pretreatment infrastructure.
Strategic Opportunities
- India commercial kitchen sector:Food Safety and Standards Authority of India enforcement gaps in mid-tier restaurants create whitespace for hospital-grade vapor sanitation equipment.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive requirements are pushing European facility managers to document chemical-free cleaning methods for Scope 3 emissions reporting.
- IoT-enabled predictive maintenance:Sensor-integrated steam units that monitor boiler pressure and heating element degradation are opening subscription revenue streams for equipment vendors.
Industry Challenges
- Pressure vessel certification timelines:ASME and PED compliance documentation for commercial-grade boilers extends product launch cycles by 8-14 months.
- Integration with building management systems:Facilities managers face protocol mismatches when connecting continuous-fill steam units to existing BACnet or Modbus networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Cleaners Market |
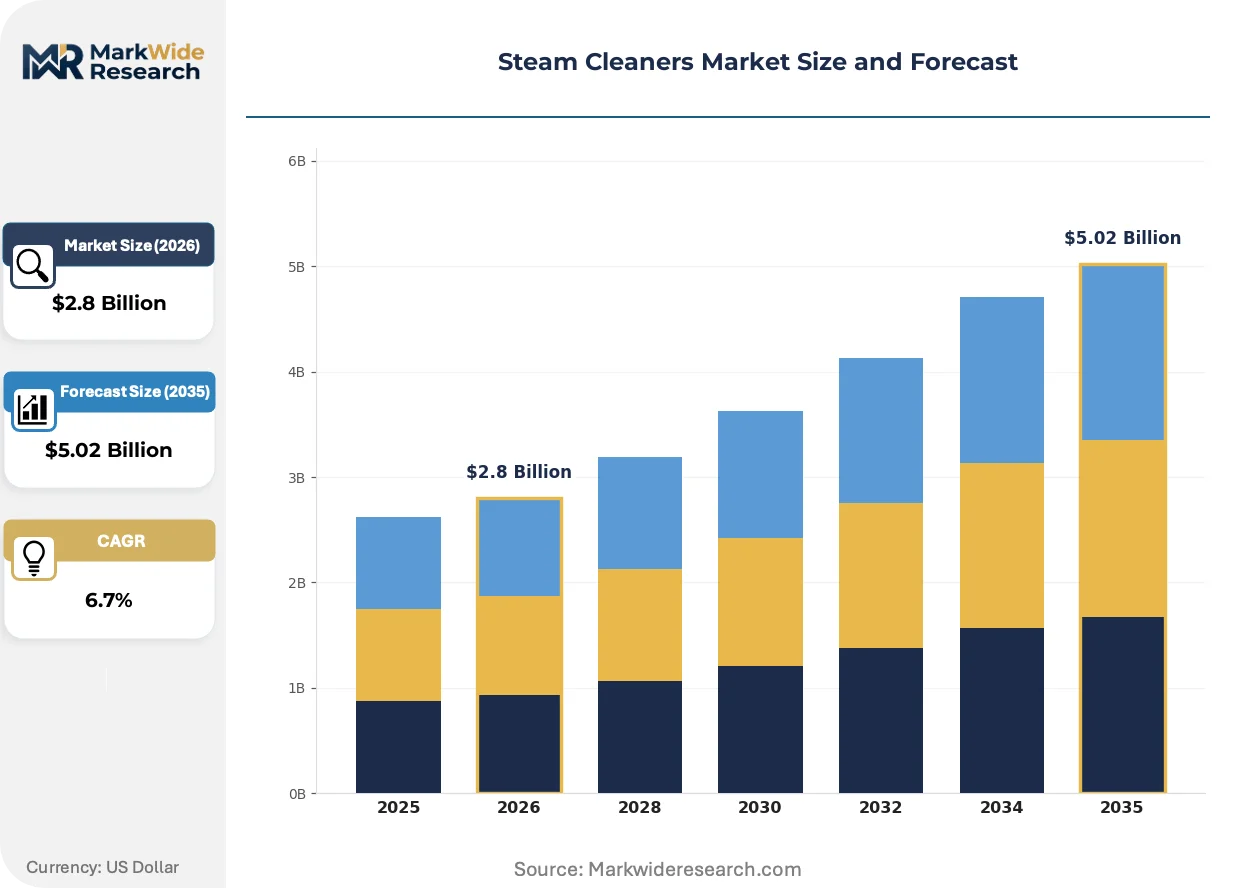
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Cylinder, Multi-Purpose, Commercial Application: Household, Hospitality, Healthcare, Automotive Technology: Dry Vapor, Continuous Fill, Pressurized, Steam Mop End User: Cleaners, Facilities Management, Homeowners, Businesses |
| Companies Covered | Kärcher, Bissell, SharkNinja, Hoover, Polti, Daimer Industries, McCulloch, Vax, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Cleaners Market Strategic Shifts
Dry vapor technology is compressing dwell times and surface drying intervals in regulated environments. Equipment manufacturers are racing to integrate smart diagnostics and connectivity while regulatory bodies tighten chemical disclosure requirements across multiple jurisdictions.
Superheated dry vapor systems operating above 150°C are collapsing the distinction between cleaning and sanitization steps in healthcare and food-service workflows. Hospital environmental services departments in Germany and the United States are adopting these units to eliminate the rinse-and-wipe cycle required by wet-steam alternatives. The technology is collapsing total room-turnover time from 45 minutes to under 15 minutes in isolation room protocols.
California's Proposition 65 chemical warning requirements and the EPA's expanded Safer Choice product category are forcing facilities to document cleaning agent composition. Industrial laundries and food processors now face liability exposure from solvent residues that vapor methods eliminate entirely. The regulatory pressure is most acute in California, where plaintiffs' attorneys actively enforce disclosure violations against cleaning chemical distributors.
Facilities managers are unbundling equipment purchase from maintenance contracts and demanding outcome-based performance guarantees. Large healthcare systems in the United States now specify uptime percentages and mean-time-to-repair commitments in procurement documents rather than accepting standard manufacturer warranties. The shift is visible in Group Purchasing Organization contract templates that prioritize operational availability over capital expenditure minimization.
Steam Cleaners Market Segmentation
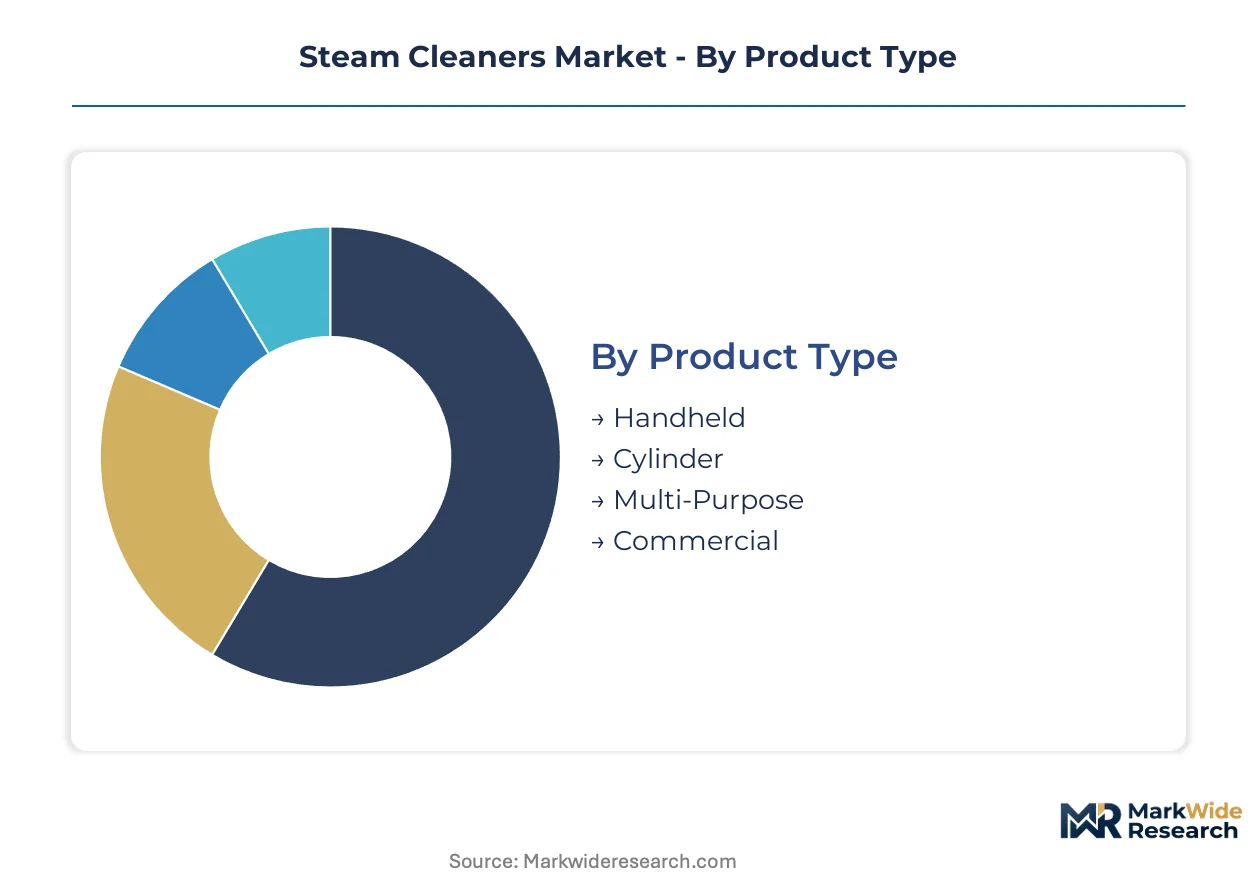
Steam cleaner procurement splits across performance tiers, regulatory environments, and operational duty cycles. Each segment carries distinct certification requirements and maintenance protocols that shape vendor selection and lifecycle costs.
Product Type:
Equipment form factors span residential convenience through industrial-grade pressure ratings and continuous operation capability.
- Cylinder:These units deploy wheeled boiler systems generating sustained pressure above 4 bar for extended degreasing cycles. German commercial kitchens and metal fabrication facilities specify cylinder models to meet documented thermal sanitation protocols under REACH-aligned industrial hygiene codes.
- Multi-Purpose:Modular configurations combine vacuum extraction, detergent injection, and steam generation in single chassis designs. United States healthcare systems favor these for environmental services departments requiring rapid room-turnover in isolation protocols.
- Handheld:Compact residential units target spot cleaning and upholstery maintenance with lower pressure output and limited reservoir capacity.
- Commercial:Fixed-installation systems integrate with building utilities for continuous steam supply in large-scale food processing and industrial laundry operations.
Established volume favors cylinder configurations in regulated commercial environments; emerging adoption favors multi-purpose systems in healthcare facilities consolidating equipment footprints.
Application:
End-use environments impose divergent temperature, pressure, and documentation requirements on equipment specification.
- Healthcare:Hospital-grade vapor sanitation prepares surfaces ahead of terminal sterilization cycles. United States acute care facilities expanding under Joint Commission accreditation standards drive specification of superheated dry vapor systems above 150°C to collapse room-turnover intervals.
- Hospitality:Commercial kitchens face binding hygiene codes mandating thermal sanitation documentation. German food-service operations specify cylinder steam units to satisfy regulatory audit trails.
- Household:Residential deep-cleaning applications prioritize maneuverability and storage footprint over pressure ratings or duty cycle endurance.
- Automotive:Engine bay degreasing and interior detailing demand portable units with chemical-free grease dissolution for EPA Safer Choice-aligned auto detailing shops.
Procurement concentration sits with healthcare systems specifying uptime guarantees; hospitality operators represent the steepest expansion trajectory as regulatory enforcement tightens across European food-service chains.
Technology:
Heating system architecture determines surface drying speed, operational continuity, and maintenance intervals.
- Dry Vapor:Superheated systems operating above 150°C deliver moisture content below 5 percent, eliminating rinse cycles. Healthcare environmental services in Germany and the United States adopt these to compress isolation room turnover from 45 minutes to under 15 minutes.
- Continuous Fill:Reservoir designs permit water replenishment during operation without pressure loss. Facilities management contracts in hard-water regions face scale buildup constraints without pretreatment infrastructure.
- Pressurized:Conventional boiler systems generate saturated steam at 100-150°C for general commercial cleaning where rapid drying is secondary to grease penetration.
- Steam Mop:Residential-focused pad-based systems integrate steam generation with absorbent surfaces for hard-floor maintenance in consumer households.
Technology selection tracks regulatory environment severity; dry vapor commands premium positioning in healthcare accreditation markets while continuous fill penetrates facilities management contracts prioritizing operational availability.
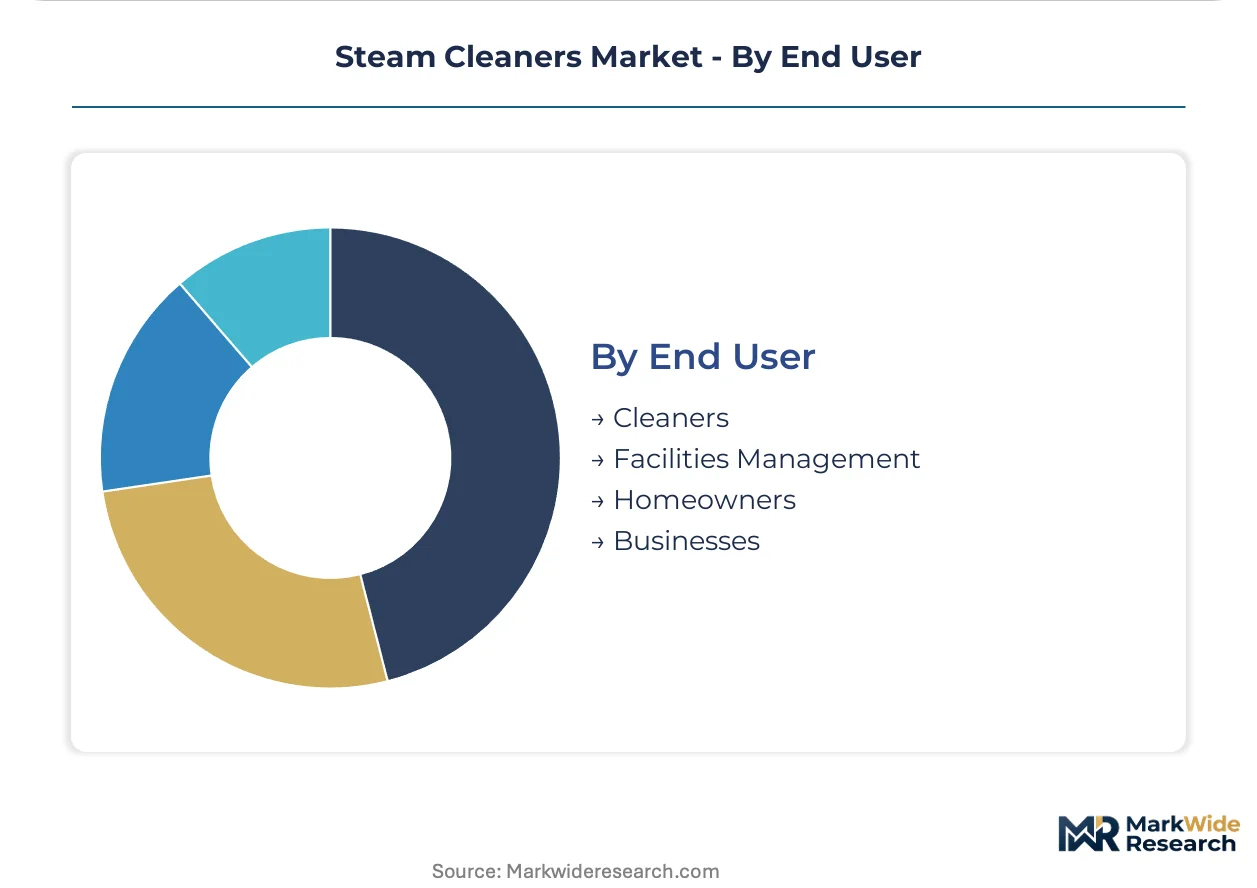
End User:
Buyer sophistication and procurement authority determine specification complexity and service contract structure.
- Facilities Management:Large healthcare systems and commercial property operators now demand outcome-based performance guarantees specifying uptime percentages and mean-time-to-repair commitments rather than standard manufacturer warranties.
- Businesses:Industrial laundries and food processors face liability exposure from solvent residues, elevating vapor methods under California Proposition 65 enforcement and EPA Safer Choice documentation requirements.
- Cleaners:Contract cleaning services prioritize equipment durability and rapid service response to minimize downtime across multiple client sites.
- Homeowners:Price-sensitive residential buyers trade pressure ratings and duty cycles for convenience features and retail availability through e-commerce channels.
Procurement sophistication stratifies sharply; facilities management contracts drive subscription revenue models for predictive maintenance while homeowner segments concentrate in direct-to-consumer digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German industrial cleaning equipment manufacturers to Baltic and North Sea markets, anchoring Europe's distribution hub for hospital-grade vapor sanitation systems.
United States
Joint Commission accreditation standards are expanding vapor-based surface preparation in acute care facilities across the Midwest and Southeast. EPA Safer Choice certification requirements are compressing solvent-dependent methods in California and New York industrial laundries. Cleveland Clinic and Mayo Clinic systems in Ohio and Minnesota specify superheated dry vapor units above 150°C to collapse isolation room turnover intervals.
Germany
Commercial kitchen operators in Bavaria and North Rhine-Westphalia face binding hygiene codes mandating documented thermal sanitation protocols. REACH chemical restrictions are elevating water-based vapor methods over solvent-dependent degreasing in metal fabrication clusters. Stuttgart's automotive supplier network and Munich's hospital procurement consortia specify cylinder steam units with continuous-fill capability for uninterrupted production cycles.
China
GB standards for food-contact surface sanitation are tightening enforcement across Yangtze River Delta food processing plants. The country's national environmental regulator is pushing industrial laundries toward water-based cleaning systems to meet dual carbon goals. Shanghai's commercial kitchen equipment distributors and Guangzhou's hospital procurement offices are sourcing hospital-grade vapor sanitation equipment for mid-tier restaurant chains.
India
FSSAI enforcement gaps in Maharashtra and Karnataka's mid-tier restaurant sectors are creating whitespace for imported vapor sanitation equipment. Central electricity authority grid reliability improvements are enabling continuous-fill steam unit adoption in Delhi-NCR facilities management contracts. Mumbai's hospitality procurement networks and Bangalore's healthcare infrastructure developers are specifying dry vapor technology for rapid surface drying in humid climates.
Japan
METI energy-efficiency standards are shaping heating system architecture in Kanto region hospital procurement. JIS standards for pressure vessel certification are extending product launch timelines for European OEMs entering the market. Tokyo's environmental services departments and Osaka's commercial kitchen operators favor compact multi-purpose units that consolidate equipment footprints in space-constrained facilities.
Steam Cleaners Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: premium European manufacturers with established dealer networks, North American direct-to-consumer specialists leveraging e-commerce platforms, and Asian fabricators serving price-sensitive commercial segments. The competitive structure rewards brand loyalty in regulated healthcare procurement while privileging speed-to-market in residential channels. Dominant competitive moves include geographic expansion through specialty retail partnerships and portfolio diversification into predictive maintenance subscriptions.
Among European-based manufacturers, Kärcher anchors the premium commercial tier through established dealer networks, while Polti occupies a position within Southern European specialty retail channels. SharkNinja exemplifies the direct-to-consumer archetype through Amazon-exclusive launch strategies and social media marketing velocity.
| Leading Market Players |
|---|
| Kärcher |
| Bissell |
| SharkNinja |
| Hoover |
| Polti |
| Daimer Industries |
| McCulloch |
| Vax |
| Techtronic Industries |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's automotive supplier network and Northern Italy's boiler component clusters concentrate specialized heating element manufacturing, feeding downstream pricing power to OEMs serving regulated healthcare and food-service procurement channels across Germany and the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade dry vapor systems from commercial cylinder units and residential handheld models. Price differentiation tracks certification grade—ASME and PED compliance documentation extends commercial-grade product launch cycles—and volume scale, with Group Purchasing Organization contracts commanding steepest discounts. Pricing pressure stems from copper and aluminum input volatility pressuring boiler manufacturing margins. Residential buyers exhibit highest price sensitivity, trading pressure ratings for convenience features, while facilities management contracts prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Copper and aluminum feedstock sourcing draws from mining operations subject to energy supply disruptions, while specialized boiler component production clusters in Northern Italy and Southern Germany create geographic concentration risk for OEM sourcing. Stainless steel pressure vessel fabrication and electronic control module assembly rest on concentrated supplier bases in Germany and China. Single-source vulnerability sits with heating element manufacturers serving multiple OEMs from limited production lines. Distribution runs through established dealer networks in Europe, direct-to-consumer e-commerce platforms in North America, and commercial kitchen equipment distributors in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
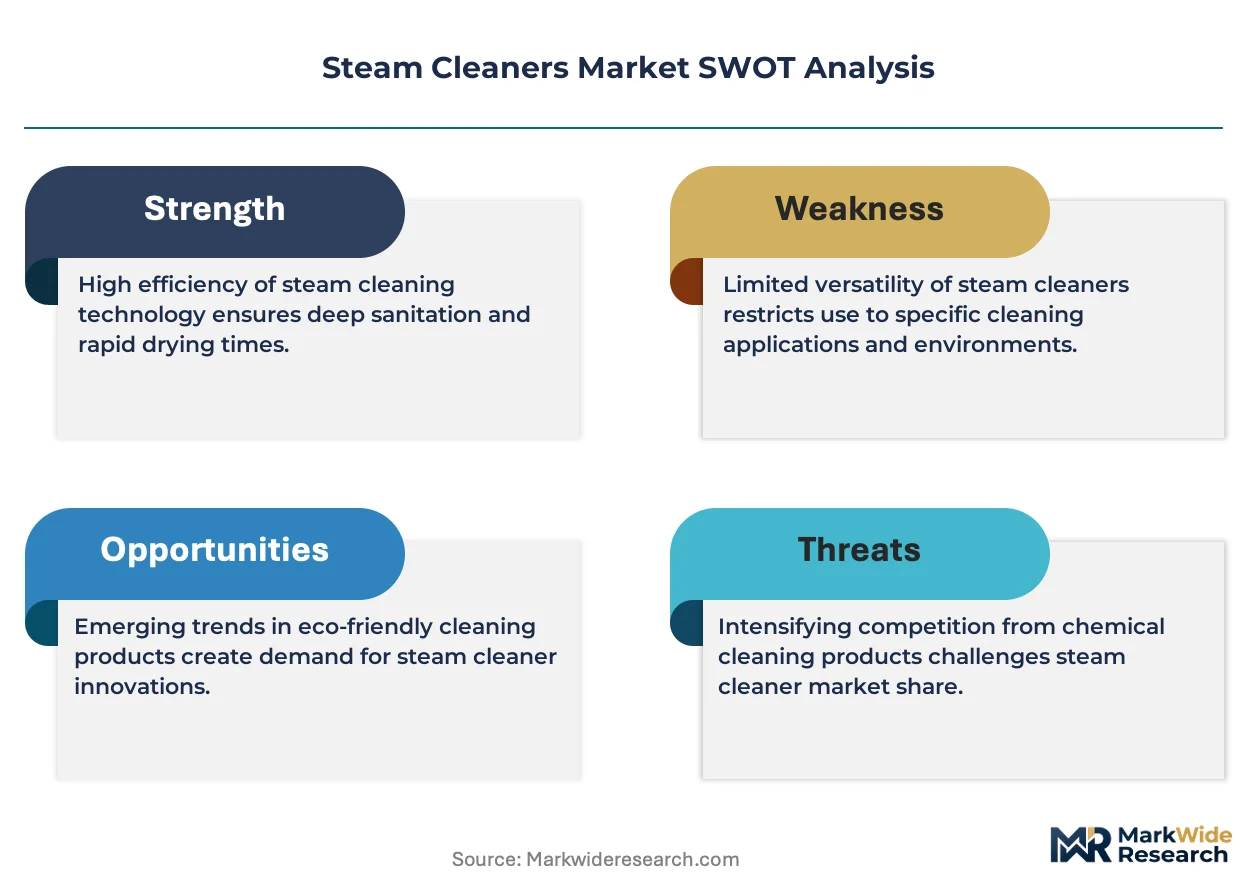
This market operates as a substitution defense against chemical-based cleaning systems, with incumbents navigating displacement pressure from solvent-dependent alternatives facing tightening EPA Safer Choice and REACH chemical disclosure requirements.
For Market Incumbents: Harden certification moats by accelerating ASME and PED compliance documentation investments to extend product launch cycle advantages over emerging competitors. Deepen backward integration into heating element manufacturing to offset copper and aluminum price volatility exposure. Anchor channel control through predictive maintenance subscription models that lock facilities management contracts into long-term service relationships.
For New Entrants and Emerging Players: India's mid-tier restaurant sector under FSSAI enforcement gaps presents whitespace for hospital-grade vapor sanitation equipment lacking domestic supply. Target Delhi-NCR facilities management contracts where grid reliability improvements enable continuous-fill steam unit adoption. Pursue specialty retail partnerships with appliance chains in humid climate markets where rapid surface drying commands premium positioning.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because tightening chemical disclosure rules across multiple jurisdictions embed vapor cleaning in healthcare and food-service procurement specifications. Acquisition targets cluster around IoT-enabled equipment vendors with sensor-integrated boiler pressure monitoring capabilities. Watch CSRD supply chain disclosure enforcement as the inflection signal—accelerated Scope 3 emissions reporting requirements will compress chemical-based cleaning method market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Facilities management contracts now demand uptime percentages rather than standard warranties. |
| ASME Certification Acceleration | Pressure vessel documentation timelines extend commercial-grade product launch cycles by 8-14 months. |
| IoT Sensor Integration | Boiler pressure and heating element degradation monitoring opens recurring revenue streams. |
| Specialty Retail Partnership Expansion | Appliance chain relationships anchor brand loyalty in Southern European consumer segments. |
| Dry Vapor Technology Portfolio Extension | Superheated systems above 150°C collapse isolation room turnover from 45 minutes to under 15 minutes. |
Study Parameters
Initial hypotheses were tested against primary input from environmental services directors, hospital procurement managers, commercial kitchen operators, and aftermarket service heads, and refined through secondary validation against customs records, SEC filings from listed equipment manufacturers, EPA Safer Choice product registries, and REACH chemical restriction databases. Bottom-up equipment shipment data triangulated against top-down facilities spending estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, application environment, heating system architecture, and end-user procurement sophistication. CAGRs derived from equipment replacement cycle analysis and regulatory enforcement timeline projections. Forecast inputs incorporated Joint Commission accreditation standards expansion and CSRD supply chain disclosure implementation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian fabricators serving price-sensitive commercial segments would shift outcomes. Cross-checking against hospital procurement database trends and GPO contract template evolution is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Ceramic Travel Mug Market
Household Items
Sanitary Metal Ware Market
Household Items
Window Rain Guards Market
Household Items
Japan Faucets Market
Household Items
Shower Heads and Systems Market
Household Items
UK Digital Showers Market
Household Items
Netherlands Cookware Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Kick Bucket Market
Household Items
Facial Tissue Market
Household Items
Hangers Market
Household Items
Luxury Massage Chair Market
Household Items
Pet Safe Cleaners Market
Household Items
Paper Towel Dispenser Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Disposable Napkins Market