
 US Flashlights Market | 2026-2036
US Flashlights Market Size, Share, and Industry Trends Forecast 2026-2036
US Flashlights Market Analytics
Capital-intensity divergence between domestic machine shops and overseas assembly networks is bifurcating competitive tiers within the US flashlight industry. Streamlight sustains deep manufacturing ties in Pennsylvania, leveraging in-house aluminum machining for law enforcement contracts. Pelican dominates polymer-housing production for hazardous-environment certifications, while Olight competes through direct-to-consumer channel control and rapid product-cycle iteration.
A flashlight is a portable, battery-powered electroluminescent device engineered to convert electrical energy into directional visible light through LED, incandescent, halogen, or xenon emission technologies, typically housed in aluminum or impact-resistant polymer casings rated for ingress protection and drop resistance. Industrial and emergency applications command premium pricing due to NFPA and MIL-STD compliance requirements, whereas household consumption anchors volume through rechargeable LED handhelds sold via mass retail. Tactical product types concentrate margin pools in military and police procurement channels where SureFire and Streamlight hold entrenched positions.
FCC Part 15 governs electromagnetic emissions from rechargeable flashlight circuitry, while OSHA 1910 illumination standards mandate minimum lumen output and runtime for construction and industrial worksites. NHTSA emergency kit regulations for commercial vehicles further shape product specifications around durability and battery shelf life. Stakeholders must monitor pending EPA battery stewardship rules and state-level right-to-repair legislation that could force design changes to sealed-unit architectures.
Market Dynamics
The US Flashlights Market is experiencing a structural bifurcation between institutional procurement standardization and consumer channel fragmentation. LED thermal management advances and RoHS-aligned material mandates are compressing legacy incandescent supply chains while expanding tactical product premium tiers.
Growth Catalysts
- NFPA 1901 compliance mandates:Fire apparatus illumination standards require minimum lumen output and runtime specifications, driving fleet-wide LED upgrades across municipal departments.
- Hurricane preparedness programs:Texas, Florida, and California emergency management agencies bulk-procure rechargeable tactical models for civilian distribution kits ahead of storm seasons.
- Lithium-ion cell energy density improvements:Solid-state electrolyte research extends runtime-to-weight ratios, enabling smaller form factors without sacrificing output duration.
Market Restraints
- Aluminum billet price volatility:Aerospace and automotive demand competition for 6061-T6 alloy creates input cost instability for machined housing producers.
- Single-source dependency on Asian battery cell suppliers:Cylindrical lithium-ion production concentration in East Asian manufacturing clusters exposes supply continuity risk.
- Sealed-unit architecture limitations:IP68-rated polymer housings prevent user-serviceable battery replacement, shortening effective product lifespan versus modular designs.
Strategic Opportunities
- Right-to-repair legislative momentum:State-level repairability mandates in California and New York create first-mover advantage for modular, field-serviceable flashlight architectures.
- UV-C disinfection convergence:Multi-spectrum LED arrays combining visible and ultraviolet output address healthcare and transit sanitation procurement requirements.
- Direct-to-institutional platform expansion:Bypassing distributor markup through GSA schedule and municipal cooperative purchasing networks captures margin from consolidated public safety buyers.
Industry Challenges
- MIL-STD-810H certification timeline compression:Accelerated defense procurement cycles demand environmental testing completion within 90-day windows that strain third-party lab capacity.
- Legacy inventory obsolescence:Rapid lumen-per-watt improvement cycles strand distributor stock of prior-generation LED emitters before sell-through completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Flashlights Market |
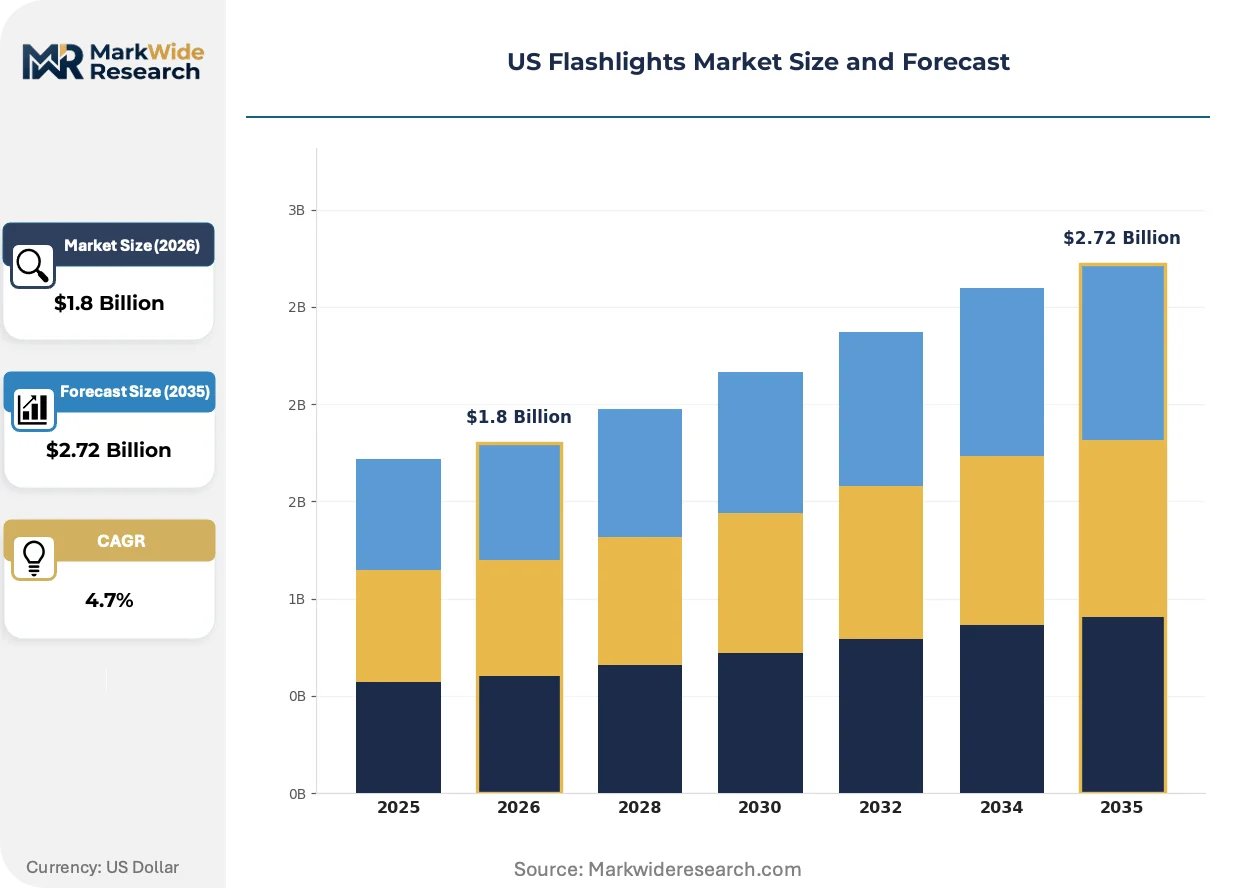
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Rechargeable, Tactical, Headlamps Technology: LED, Incandescent, Halogen, Xenon Application: Outdoor, Emergency, Industrial, Household End User: Consumers, Emergency Services, Military, Construction |
| Companies Covered | Pelican, Coast, Streamlight, Nite Ize, Olight, SureFire, Fenix, BAYCO Products, Maglite, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Flashlights Market Evolving Landscape
Active thermal regulation and smart connectivity modules are redefining performance benchmarks across both tactical and consumer flashlight segments. These advances compress replacement cycles while elevating software-enabled functionality as a competitive differentiator.
Multi-die LED emitters with integrated temperature sensors is decomposing the traditional separation between high-output and extended-runtime product categories. Law enforcement procurement divisions now specify single units replacing previously distinct patrol and searchlight inventories. This consolidation pressures manufacturers holding segmented SKU strategies built around lumen-tier differentiation.
EPA battery stewardship rules under development will mandate extended producer responsibility for end-of-life lithium cell collection and recycling. Industrial flashlight vendors must redesign distribution logistics to accommodate reverse supply chain infrastructure. Municipal procurement specifications in California and New York increasingly require documented recycling compliance pathways.
Bulk institutional buyers are consolidating vendor relationships through multi-year cooperative purchasing agreements that displace spot-market transactions. State-level procurement cooperatives in Texas and Florida aggregate demand from hundreds of smaller departments. This concentration rewards flashlight manufacturers with dedicated public-sector sales infrastructure and GSA schedule compliance capabilities.
US Flashlights Market Segmentation
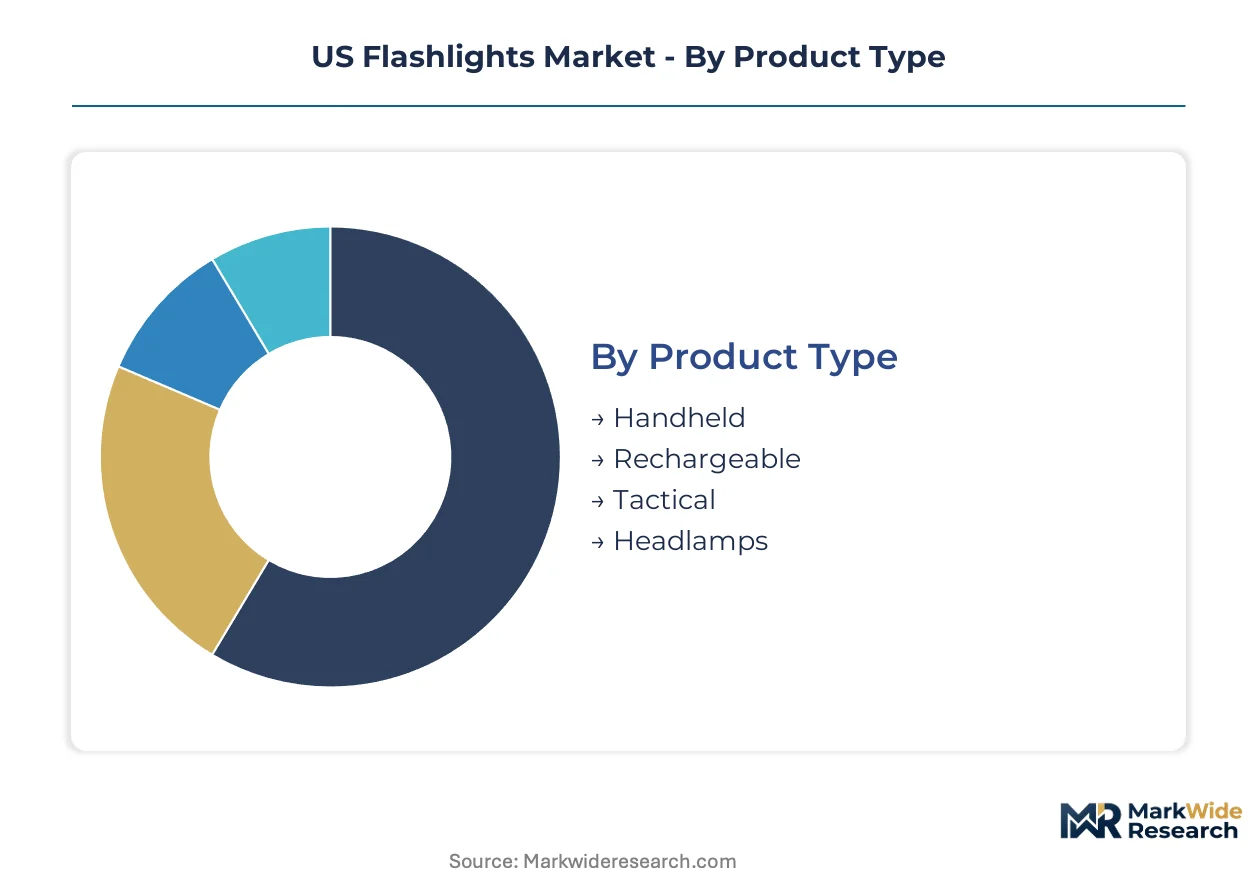
Flashlight segmentation in the US market reveals how procurement channels, certification requirements, and use-case intensity create distinct margin architectures. Understanding these boundaries illuminates where manufacturers must build specialized capabilities versus where scale economies dominate.
Product Type:
Tactical and rechargeable models command the deepest margin pools through institutional certification requirements and battery chemistry premiums.
- Handheld:Standard aluminum or polymer-bodied units with click-switch operation dominate household retail channels. Volume concentrates in big-box stores across California and Texas where hurricane preparedness drives seasonal bulk purchasing.
- Rechargeable:Lithium-ion powered units with USB-C or proprietary dock charging systems. Demand clusters in municipal emergency management agencies in Florida and construction firms under OSHA 1910 illumination mandates, with EPA battery stewardship rules pushing design toward recyclable cell architectures.
- Tactical:MIL-STD-810H certified units with momentary tail switches and strike bezels. Police and military procurement channels in Texas and California require NFPA compliance documentation and 90-day environmental testing turnaround.
- Headlamps:Strap-mounted units with pivoting lamp housings for hands-free operation. Outdoor recreation and industrial inspection applications in Pacific Northwest logging and Appalachian mining operations drive specification around IPX4 minimum water resistance.
The dominant share belongs to handheld units, while rechargeable models are closing the gap fastest through institutional fleet replacement cycles.
Technology:
Cost tier stratification separates legacy thermal emitters from solid-state architectures with active thermal management.
- LED:Multi-die emitters with integrated temperature sensors and PWM dimming circuits. Thermal management advances are compressing lumen-per-watt improvement cycles, stranding distributor inventory of prior-generation chips before sell-through completion.
- Incandescent:Tungsten filament bulbs in sealed reflector housings. RoHS-aligned EPA restrictions on hazardous substances are forcing lead-free solder transitions that raise production costs for remaining specialty manufacturers serving legacy equipment maintenance.
- Halogen:Tungsten-halogen regenerative cycle bulbs with higher color temperature output. Niche theatrical and inspection applications persist where CRI accuracy outweighs efficiency concerns.
- Xenon:High-pressure gas discharge arc lamps with instant-on capability. Limited to high-intensity searchlight applications in Coast Guard and border patrol aviation support where beam distance specifications exceed LED practical limits.
LED architectures hold uncontested volume leadership, with xenon retaining defensible position only in extreme throw-distance applications.
Application:
Customer type intensity determines whether procurement flows through retail, distributor, or direct institutional channels.
- Outdoor:Recreation-focused units prioritizing weight-to-runtime ratios and red-light preservation modes. Appalachian Trail through-hikers and Rocky Mountain hunting outfitters in Colorado drive demand for sub-100g programmable headlamps.
- Emergency:FEMA-compliant units with minimum 72-hour runtime and signaling strobe functions. Texas and Florida emergency management agencies bulk-procure for civilian distribution kits ahead of hurricane season, with NHTSA commercial vehicle regulations shaping durability specifications.
- Industrial:Explosion-proof and intrinsically safe certifications for hazardous location use. OSHA 1910 standards mandate minimum lumen output for construction sites, while NFPA 1901 fire apparatus requirements drive fleet-wide LED upgrades across municipal departments.
- Household:Mass-market units sold through hardware and big-box retail. Price sensitivity anchors volume here, with rechargeable lithium-ion models gradually displacing alkaline-powered inventory.
Emergency applications generate the steepest expansion trajectory as state-level preparedness funding increases, while household consumption provides baseline volume stability.
End User:
Procurement consolidation patterns separate fragmented consumer demand from concentrated institutional purchasing power.
- Consumers:Individual purchasers through Amazon, Home Depot, and specialty outdoor retailers. Direct-to-consumer channel control and rapid product-cycle iteration define competitive positioning here.
- Emergency Services:Fire, police, and EMS departments procuring through cooperative purchasing networks. State-level cooperatives in Texas and Florida aggregate demand from hundreds of smaller departments, rewarding manufacturers with GSA schedule compliance capabilities.
- Military:Defense procurement cycles with MIL-STD-810H environmental testing requirements. Accelerated 90-day certification windows strain third-party lab capacity and favor established vendors with in-house testing infrastructure.
- Construction:OSHA-mandated site illumination with durability specifications for drop and ingress protection. Large general contractors in California and Texas specify fleet-standardized units to simplify compliance documentation.
Emergency services procurement is expanding most quickly as departments modernize duty gear, while military channels remain concentrated among entrenched incumbent suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Florida procurement cooperatives, while California's regulatory complexity compresses margins for manufacturers lacking compliance infrastructure. Hurricane preparedness funding and municipal fleet standardization create divergent competitive conditions across state boundaries.
Texas
State emergency management agencies bulk-procure tactical LED units for civilian distribution kits ahead of hurricane season. The Texas Division of Emergency Management coordinates cooperative purchasing agreements aggregating demand from hundreds of municipal police and fire departments. Houston and Dallas-Fort Worth anchor industrial distribution networks serving Gulf Coast energy sector contractors under OSHA 1910 illumination mandates.
Florida
County-level emergency operations centers standardize on rechargeable lithium-ion models with FEMA-compliant 72-hour runtime specifications. The Florida Department of Emergency Management administers preparedness grants funding fleet-wide LED upgrades for municipal first responders. Miami-Dade and Broward counties concentrate institutional procurement volume through consolidated cooperative purchasing networks.
California
State-level right-to-repair legislation and pending EPA battery stewardship rules force design modifications toward modular field-serviceable architectures. Cal/OSHA enforcement of construction site illumination standards drives specification of IP68-rated units among Bay Area and Los Angeles general contractors. Sacramento anchors regulatory compliance consulting services supporting manufacturers navigating multi-agency certification requirements.
Pennsylvania
In-house aluminum machining capabilities sustain domestic production of MIL-STD-810H certified units for federal law enforcement contracts. Philadelphia and Pittsburgh metropolitan areas concentrate precision manufacturing infrastructure serving defense procurement channels. Pennsylvania-based fabricators leverage proximity to Washington DC for GSA schedule compliance and direct institutional sales relationships.
Pacific Northwest
Outdoor recreation demand clusters around sub-100g programmable headlamps for Appalachian Trail through-hikers and Rocky Mountain hunting outfitters. Oregon and Washington state environmental regulations restrict hazardous substance content in battery chemistries, aligning with RoHS-aligned EPA mandates. Seattle anchors specialty outdoor retail distribution serving backcountry recreation markets across the Mountain West.
US Flashlights Market Competitive Landscape
Concentration sits with entrenched institutional suppliers holding GSA schedule compliance and in-house environmental testing infrastructure. The vendor base stratifies across three tiers: domestic machine shops with captive aluminum supply, polymer-housing specialists certified for hazardous environments, and direct-to-consumer operators controlling rapid product-cycle iteration. Strategic moves center on cooperative purchasing network penetration and modular architecture development anticipating right-to-repair mandates.
Among domestic fabricators, Streamlight represents the machined-aluminum archetype with Pennsylvania-based production infrastructure. Pelican exemplifies polymer-housing specialization for NFPA and MIL-STD compliance requirements. Olight occupies the direct-to-consumer channel control position, leveraging rapid iteration cycles against slower institutional procurement timelines.
| Leading Market Players |
|---|
| Pelican |
| Coast |
| Streamlight |
| Nite Ize |
| Olight |
| SureFire |
| Fenix |
| BAYCO Products |
| Maglite |
| Others |
Value Network & Pricing Analysis
Capacity utilization at domestic aluminum machining centers runs above regional averages, compressing per-unit fixed costs for MIL-STD-certified housing producers while elevating price floors for polymer-specialist competitors lacking comparable scale. This divergence concentrates margin capture among Pennsylvania-based fabricators serving GSA-schedule procurement channels, forcing smaller operators toward commodity rechargeable segments where lithium-ion cell costs dominate landed pricing.
Pricing Analysis
Configured-to-order tactical units with NFPA 1901 documentation and 90-day environmental testing turnaround command premium spreads of 40-60 percent above standard SKUs sold through mass retail. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-certified institutional models from OSHA-compliant industrial units and household alkaline-powered inventory. Pricing pressure stems from aluminum billet cost volatility driven by aerospace demand competition, with household segments exhibiting highest price sensitivity and emergency services procurement showing lowest elasticity due to compliance mandates.
Supply Chain Analysis
Inventory cycles for cylindrical lithium-ion cells stretch 12-16 weeks from East Asian manufacturing clusters, creating working capital intensity that favors scaled assemblers with direct supplier relationships. Component sourcing concentrates in China, South Korea, and Japan for battery cells, with domestic Pennsylvania and California facilities handling final assembly and certification testing. Raw material dependencies span 6061-T6 aluminum billet, polymer resin for IP68 housings, and multi-die LED emitters from Taiwanese foundries. Single-source vulnerability in cylindrical cell supply exposes continuity risk, while distribution runs through GSA-schedule holders, municipal cooperative purchasing networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through state-level cooperative purchasing networks in Texas and Florida, where aggregated municipal demand displaces spot-market transactions and compresses distributor margins. This consolidation rewards vendors with dedicated public-sector sales infrastructure.
For Market Incumbents: Shield institutional relationships by accelerating in-house environmental testing capacity to meet compressed 90-day MIL-STD-810H certification windows that strain third-party lab availability. Deepen backward integration into aluminum machining to offset billet price volatility, while preempting right-to-repair mandates through modular architecture development before California and New York enforcement timelines solidify competitive disadvantage for sealed-unit competitors. For New Entrants and Emerging Players: Post-sale battery stewardship compliance services represent an underserved layer where established vendors lack reverse logistics infrastructure. Target municipal emergency management agencies in Florida counties outside Miami-Dade and Broward, where cooperative purchasing penetration remains incomplete. Pursue direct-to-institutional platform expansion through GSA schedule acquisition, bypassing distributor markup to capture margin from consolidated public safety buyers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with captive battery replacement programs and multi-year cooperative purchasing agreements. Long-term viability favors operators with modular design patents and in-house testing infrastructure rather than pure-brand consumer plays. Acquisition target archetype: mid-scale fabricators with Pennsylvania-based machining capacity and underutilized GSA schedule compliance capabilities. Signal to watch: state-level right-to-repair legislation adoption rates as inflection indicator for modular architecture premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Development | Anticipates California and New York right-to-repair mandates before enforcement solidifies competitive positioning. |
| In-House Environmental Testing Capacity | Compresses 90-day MIL-STD-810H certification timelines that strain third-party laboratory availability. |
| GSA Schedule Compliance Investment | Unlocks Texas and Florida cooperative purchasing networks aggregating hundreds of municipal department demands. |
| Reverse Logistics Infrastructure | Supports EPA battery stewardship rules mandating extended producer responsibility for end-of-life lithium cell collection. |
| Direct-to-Institutional Platform Expansion | Bypasses distributor markup to capture margin from consolidated public safety buyers in state procurement cooperatives. |
Research Methodology
Desk research of SEC filings, municipal procurement databases, and GSA schedule award records preceded structured interviews with law enforcement equipment procurement officers, municipal cooperative purchasing administrators, aluminum machining facility managers, and lithium-ion cell distribution specialists. Primary fieldwork validated secondary findings through structured protocols examining NFPA 1901 compliance documentation requirements, MIL-STD-810H testing turnaround practices, and state-level right-to-repair legislative drafting. Bottom-up assembly of unit economics and top-down reconciliation against reported revenue brackets ensured triangulation integrity.
Variance decomposition across product type, technology architecture, application intensity, and end-user procurement channel informed the analytical framework throughout the projection horizon. CAGRs derived from segment-level demand elasticity modeling and input cost trajectory assumptions, with specific weighting for aluminum billet price volatility, lithium-ion cell energy density improvement cycles, and cooperative purchasing network penetration rates in Texas and Florida.
Underlying assumptions cover sustained NFPA and OSHA enforcement intensity, stable East Asian battery cell supply continuity, and gradual right-to-repair legislative adoption, with deviation risk concentrated in aluminum aerospace demand competition and EPA battery stewardship rule finalization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Hydration Containers Market
Household Items
Infrared Sauna Heaters Market
Household Items
Thermos Drinkware Market
Household Items
Portable Iron Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Heated Mattress Pads Market
Household Items
Global Rimless Toilets Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Sanitary Metal Ware Market
Household Items
Smart Faucets Market
Household Items
Household Scales Market
Household Items
Oman Gas Hobs Market
Household Items
Replacement Sheets Market
Household Items
Brazil Cookware Market
Household Items
Insulated Drinkware Market
Household Items
Europe Handheld Fans Market