
 Global Rimless Toilets Market | 2026-2036
Global Rimless Toilets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rimless Toilets Market Analysis
Ceramic manufacturing clusters in Guangdong Province are rebalancing capacity toward rimless bowl designs as export orders from European distributors strengthen. Toto Ltd. leverages its Washlet integration expertise to anchor premium positioning across Japanese and North American specification channels. Kohler Co. competes through vertically controlled foundry operations that sustain margin capture on vitreous china formulations. Duravit AG differentiates via its patented WonderGliss surface engineering, which extends hygiene performance claims in German-speaking markets.
Rimless toilets eliminate the traditional inner rim cavity, replacing it with a direct-flush channel that distributes water through precisely angled jet openings around the bowl interior; this geometry reduces bacterial harboring zones and cuts water consumption below conventional six-liter benchmarks. Wall-mounted configurations dominate commercial specification due to spatial efficiency and concealed cistern compatibility, while smart toilets represent the fastest-expanding margin pool as sensor-integrated bidet functions migrate from Japanese households into European luxury residential and hospitality segments. Floor-mounted units occupy the volume base across emerging-market residential construction where installation simplicity outweighs premium aesthetics.
EPA WaterSense certification in the United States and EU Ecodesign requirements under the European Commission's sustainable products framework shape minimum efficiency thresholds, compelling manufacturers to recalibrate flush volumes and obtain third-party validation for market access. Japan's JIS standards and Germany's DIN specifications further segment compliance burdens, with METI and KBA-aligned testing protocols creating divergent approval pathways. Stakeholders must monitor tightening water-usage ceilings and antimicrobial surface claims regulation as procurement criteria in institutional healthcare and hospitality sectors harden.
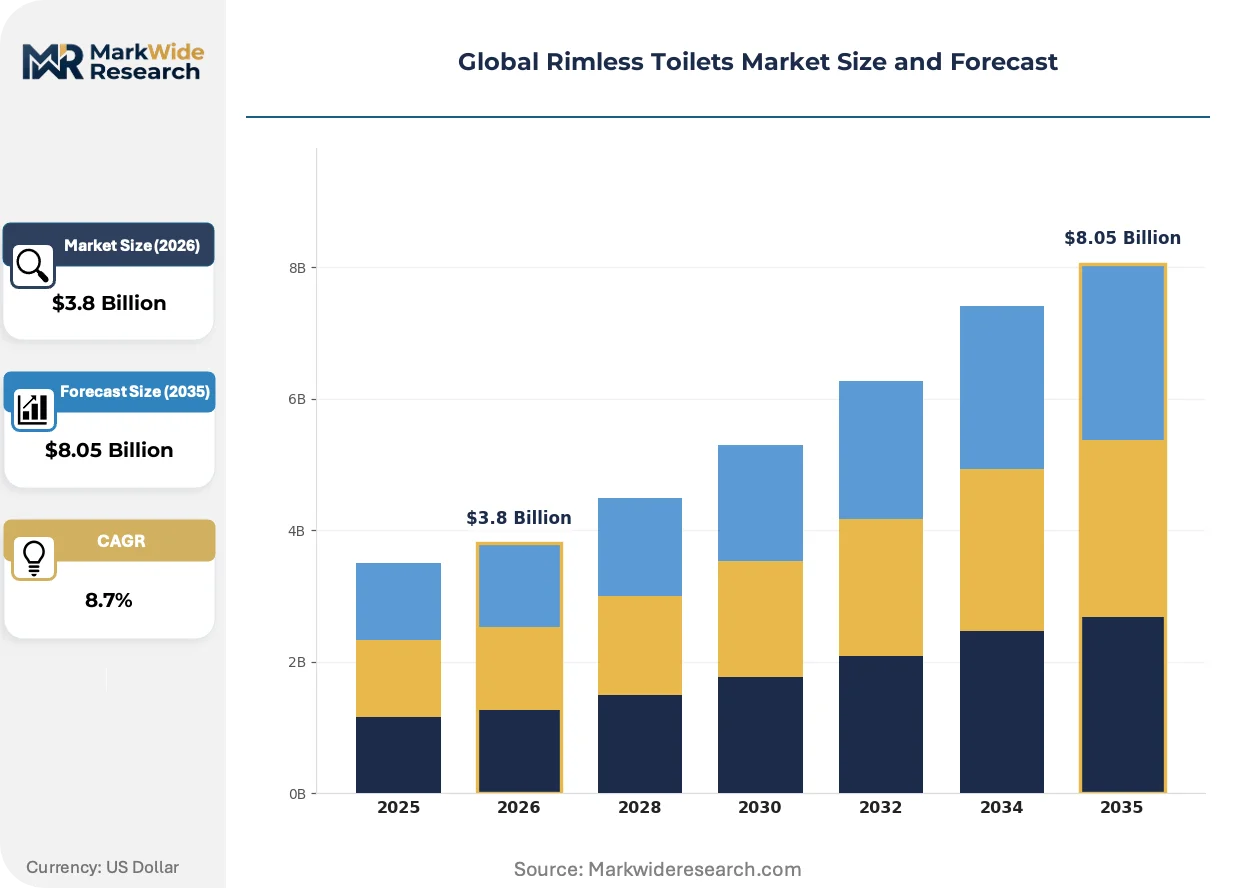
Market Dynamics
Water-efficiency mandates from EPA WaterSense and EU Ecodesign directives are compressing fixture replacement cycles while ceramic manufacturing clusters rebalance capacity toward rimless bowl geometries.
Growth Catalysts
- EPA WaterSense Certification:United States federal procurement standards now require sub-six-liter flush volumes, compelling institutional buyers to specify rimless designs in hospitality and healthcare retrofits.
- Luxury Hospitality Procurement:Southeast Asian resort chains are accelerating specification of wall-mounted rimless units with concealed cisterns to maximize spatial efficiency in premium bathroom footprints.
- Antimicrobial Surface Engineering:Patented ceramic glaze technologies that extend hygiene performance claims are shifting specification criteria in German-speaking renovation markets.
Market Restraints
- High-Purity Kaolin Concentration:Premium vitreous china formulations depend on concentrated supply from specific Guangdong Province mining districts, exposing margin structures to input volatility.
- Technical Retrofit Limitations:Existing floor-mounted rough-in dimensions often preclude direct rimless bowl substitution without structural bathroom modification, slowing residential replacement velocity.
- Divergent Testing Protocols:Japan's METI-aligned JIS standards and Germany's KBA specifications create fragmented approval pathways that extend product launch timelines for multi-market manufacturers.
Strategic Opportunities
- Smart Toilet Convergence:Sensor-integrated bidet functions from Japanese residential origins are expanding into European luxury hospitality and residential segments, creating premium margin pools.
- EU Green Deal Tailwinds:The European Commission's sustainable products framework tightens water-usage ceilings, mandating fixture upgrades across institutional building stock through 2030.
- Healthcare Specification Channel:Antimicrobial surface claims and reduced bacterial harboring zones are penetrating hospital procurement criteria in the United States and Germany.
Industry Challenges
- Precision Jet Engineering Talent:Direct-flush channel design requires specialized fluid dynamics expertise that remains concentrated among Japanese and German engineering teams.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA WaterSense, EU Ecodesign, and JIS compliance testing extends product development cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rimless Toilets Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Mounted, Smart Toilets, Portable Toilets End User: Residential, Commercial, Hospitality, Healthcare Size: Compact, Standard, Luxury, Oversized Distribution Channel: Online Retail, Direct Sales, Home Improvement Stores, Specialty Retailers |
| Companies Covered | Toto Ltd., Kohler Co., Duravit AG, Grohe AG, Hindware Homes, Caroma Industries Limited, Enware Australia Pty Limited, Laufen Bathrooms AG, Villeroy & Boch AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rimless Toilets Market Emerging Trajectories
Rimless toilet technology is expanding into adjacent smart fixture categories while regulatory tightening and procurement model evolution reshape competitive positioning across specification channels.
Direct-flush channel geometry with precisely angled jet openings is expanding into sensor-integrated bidet platforms. Japanese hospitality chains are specifying these combined units at accelerating pace. The technology is expanding into European luxury residential segments where concealed cistern compatibility drives wall-mounted preference.
EU Ecodesign requirements under the European Commission's sustainable products framework are hardening minimum efficiency thresholds. Manufacturers must recalibrate flush volumes below conventional benchmarks and obtain third-party validation for market access. German DIN specifications and healthcare procurement criteria are most affected, with institutional buyers now requiring documented water-consumption certification.
Specification-driven procurement is consolidating around certified efficiency tiers rather than brand preference. Architectural firms and hospitality procurement teams are displacing traditional distributor relationships with direct manufacturer engagement for large-scale renovation projects. This pattern is most visible across German and Japanese commercial construction markets where premium bathroom renovation cycles are shortening.
Global Rimless Toilets Market Segmentation
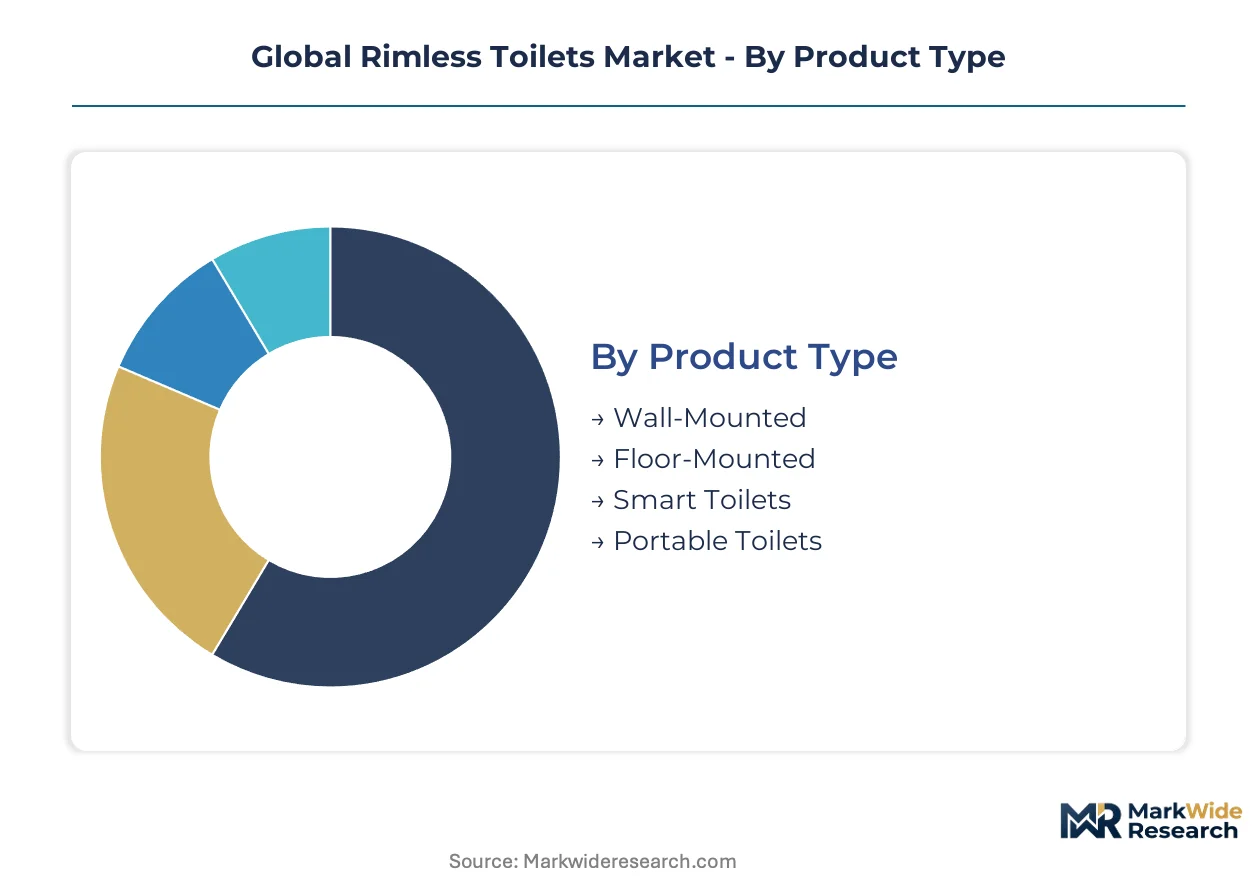
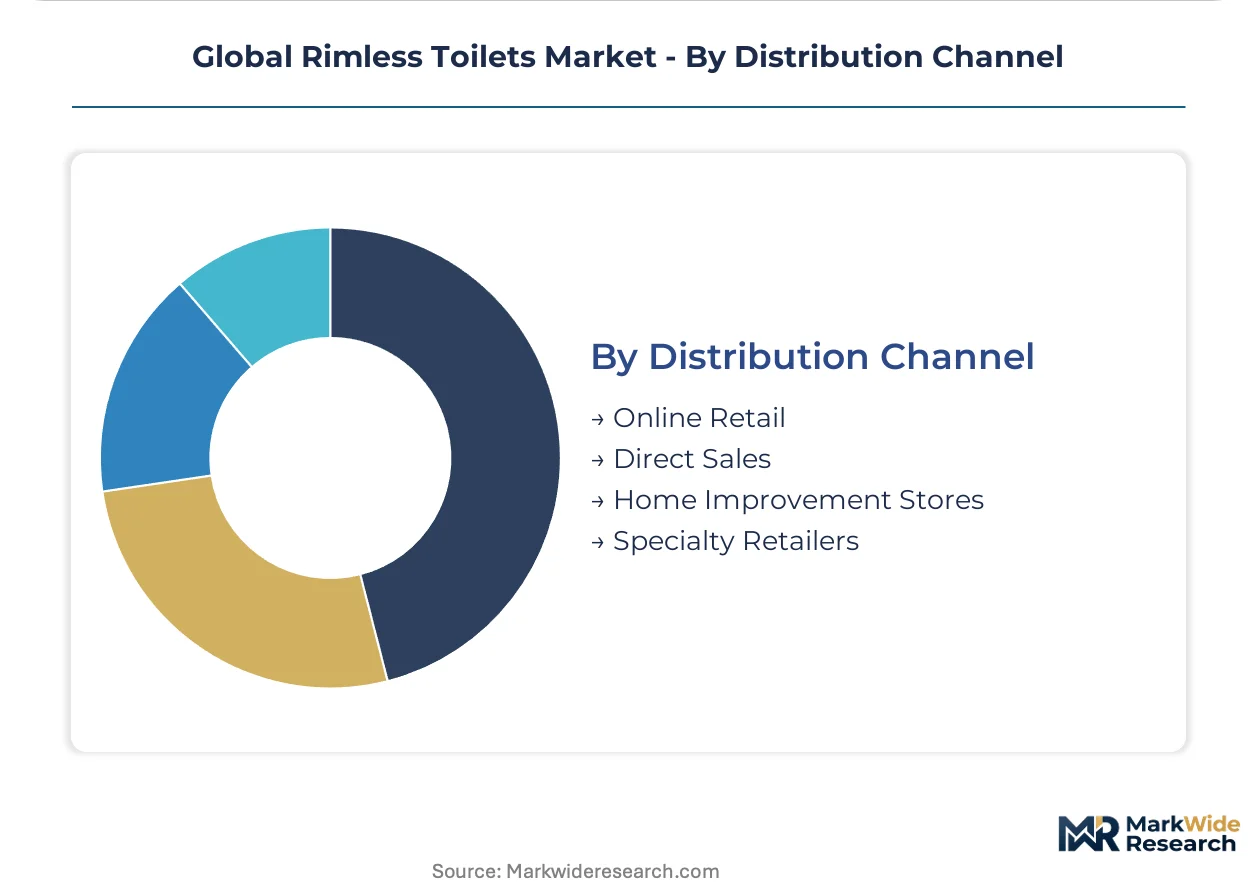
Rimless toilet procurement channels diverge sharply across specification-driven commercial projects and retail-driven residential replacement. Certification requirements from EPA WaterSense, EU Ecodesign, and Japan's JIS standards fragment product development priorities by segment.
Product Type:
EPA WaterSense and EU Ecodesign thresholds apply universally, yet smart toilet platforms face additional electromagnetic compatibility testing under FCC and CE marking regimes.
- Wall-Mounted:Concealed cistern compatibility maximizes spatial efficiency in premium hospitality bathrooms across Southeast Asian resort developments. German DIN specifications and healthcare procurement criteria in the United States are tightening around these units for reduced bacterial harboring zones.
- Smart Toilets:Sensor-integrated bidet functions require dual certification pathways combining water-efficiency validation with electrical safety testing. Japanese hospitality chains specify these at accelerating pace, while European luxury residential adoption climbs fastest.
- Floor-Mounted:Installation simplicity dominates emerging-market residential construction where rough-in dimensions align with existing infrastructure.
- Portable Toilets:Temporary sanitation deployments at outdoor events and construction sites drive intermittent demand with minimal regulatory overlay.
Floor-mounted units sit at the top of the volume ranking, with smart toilets climbing the fastest.
End User:
Cost tier separation between institutional specification and retail replacement channels determines margin capture and certification investment recovery.
- Commercial:Corporate office retrofits prioritize WaterSense-labeled units to meet federal procurement standards in the United States. Lease-cycle synchronization drives replacement timing in Class A buildings across Manhattan and Frankfurt.
- Hospitality:Southeast Asian luxury resort chains accelerate wall-mounted rimless procurement for spatial efficiency. EU Ecodesign mandates compress renovation timelines across Mediterranean and Alpine property portfolios.
- Residential:Premium bathroom renovation cycles shorten in Germany, Japan, and the United States as rimless hygiene claims penetrate consumer awareness.
- Healthcare:Hospital procurement criteria in Germany and the United States harden around antimicrobial surface claims and documented bacterial reduction.
Residential channels dominate absolute volume, though hospitality procurement is expanding most quickly.
Size:
Geographic variation in bathroom footprints and consumer preference stratifies demand across dimensional tiers.
- Compact:Urban apartment constraints in Tokyo and Singapore drive specification for sub-600mm projections. Japanese JIS dimensional standards constrain design flexibility.
- Standard:Volume base across North American and European replacement markets where existing rough-in dimensions govern selection.
- Luxury:German-speaking markets and Gulf state residential developments prioritize extended bowl geometries with premium glaze finishes.
- Oversized:Accessibility-focused institutional specification in the United States and Nordic countries accommodates mobility requirements.
Standard dimensions anchor volume, while compact segments gain share fastest in dense urban cores.
Distribution Channel:
Customer type and purchase scale determine channel selection, with specification-driven procurement displacing traditional distributor relationships.
- Direct Sales:Architectural firms and hospitality procurement teams engage manufacturers directly for large-scale renovation projects. German and Japanese commercial construction markets exhibit this pattern most visibly.
- Home Improvement Stores:Residential replacement volume concentrates in big-box retailers across the United States and European suburban markets.
- Specialty Retailers:Premium bathroom showrooms in Milan, London, and Shanghai serve design-conscious renovation clients.
- Online Retail:E-commerce penetration accelerates for standardized compact units with clear dimensional specifications.
Home improvement stores retain volume leadership, with direct sales channels expanding most rapidly in commercial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as ceramic producers migrate capacity toward jurisdictions with favorable water-efficiency compliance costs. Guangdong Province clusters now supply European distributors while Japanese engineering expertise commands premium positioning in North American specification channels.
United States
Federal procurement standards and hospitality renovation cycles drive specification of EPA WaterSense-certified rimless units. The EPA mandates sub-six-liter flush volumes for institutional buyers. Manufacturing specification teams in Chicago and Manhattan coordinate directly with architectural firms on large-scale retrofit projects.
Germany
DIN specifications and healthcare procurement criteria tighten around antimicrobial surface claims and documented bacterial reduction. The EU Ecodesign directive under the European Commission's sustainable products framework mandates fixture upgrades through 2030. Vitreous china engineering clusters in the Rhine-Ruhr region supply premium glaze formulations to German-speaking renovation markets.
Japan
Residential replacement velocity and hospitality specification accelerate demand for sensor-integrated bidet platforms. METI-aligned JIS standards create divergent approval pathways that extend product launch timelines. Engineering talent concentrated in Nagoya and Osaka sustains precision jet channel design capabilities.
China
Export order strength from European distributors rebalances Guangdong Province manufacturing capacity toward rimless bowl geometries. The country's national environmental regulator enforces tightening water-usage ceilings in urban building codes. Shenzhen and Foshan ceramic clusters now dominate mid-tier volume production for emerging-market residential construction.
Singapore
Urban apartment constraints and luxury hospitality development drive compact wall-mounted specification. The national water agency enforces strict efficiency mandates that exceed conventional six-liter benchmarks. Marina Bay and Sentosa resort procurement teams specify concealed cistern configurations to maximize spatial efficiency in premium bathroom footprints.
Global Rimless Toilets Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart fixture convergence and antimicrobial surface differentiation. The market structures around three tiers: integrated vitreous china manufacturers, specialized ceramic glaze engineers, and sensor-technology licensors. Dominant competitive moves include backward integration into kaolin supply and strategic partnerships with hospitality procurement platforms.
Within the integrated manufacturing tier, Toto Ltd. and Kohler Co. represent archetypal positions—Japanese engineering-driven premium positioning versus vertically controlled foundry operations sustaining margin capture. Duravit AG occupies a specialist position in surface engineering, exemplifying how patented ceramic glaze technologies shift specification criteria in regulated European markets.
| Leading Market Players |
|---|
| Toto Ltd. |
| Kohler Co. |
| Duravit AG |
| Grohe AG |
| Hindware Homes |
| Caroma Industries Limited |
| Enware Australia Pty Limited |
| Laufen Bathrooms AG |
| Villeroy & Boch AG |
| Others |
Supply Flow & Price Mechanics
Kaolin price volatility from Guangdong Province mining districts cascades through ceramic manufacturing clusters into three-tier pricing structures across premium vitreous china, standard glazed formulations, and economy-grade residential units. EPA WaterSense certification tiers and EU Ecodesign compliance levels stratify procurement costs for institutional buyers in the United States and Germany.
Pricing Analysis
Distributor margin compression in European specification channels intensifies price competition as architectural firms engage manufacturers directly for large-scale hospitality retrofits. Three-tier pricing structure across premium smart-toilet platforms, standard wall-mounted configurations, and economy floor-mounted units reflects certification grade and after-sales service bundling. Pricing pressure stems from concentrated kaolin supply exposure in Guangdong Province. Healthcare procurement teams in Germany and the United States exhibit lowest price sensitivity due to antimicrobial performance requirements.
Supply Chain Analysis
Specialized fluid dynamics engineering talent shortages in Nagoya and Osaka constrain precision jet channel production scaling for Japanese manufacturers. Ceramic manufacturing concentrates in China's Guangdong Province, Germany's Rhine-Ruhr region, and Japan's Nagoya-Osaka corridor. High-purity kaolin, vitreous china formulations, and sensor-integrated bidet components constitute critical input dependencies. Single-source vulnerability in Guangdong kaolin districts threatens margin stability. Distribution runs through direct manufacturer engagement for commercial specification and home improvement retail for residential replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
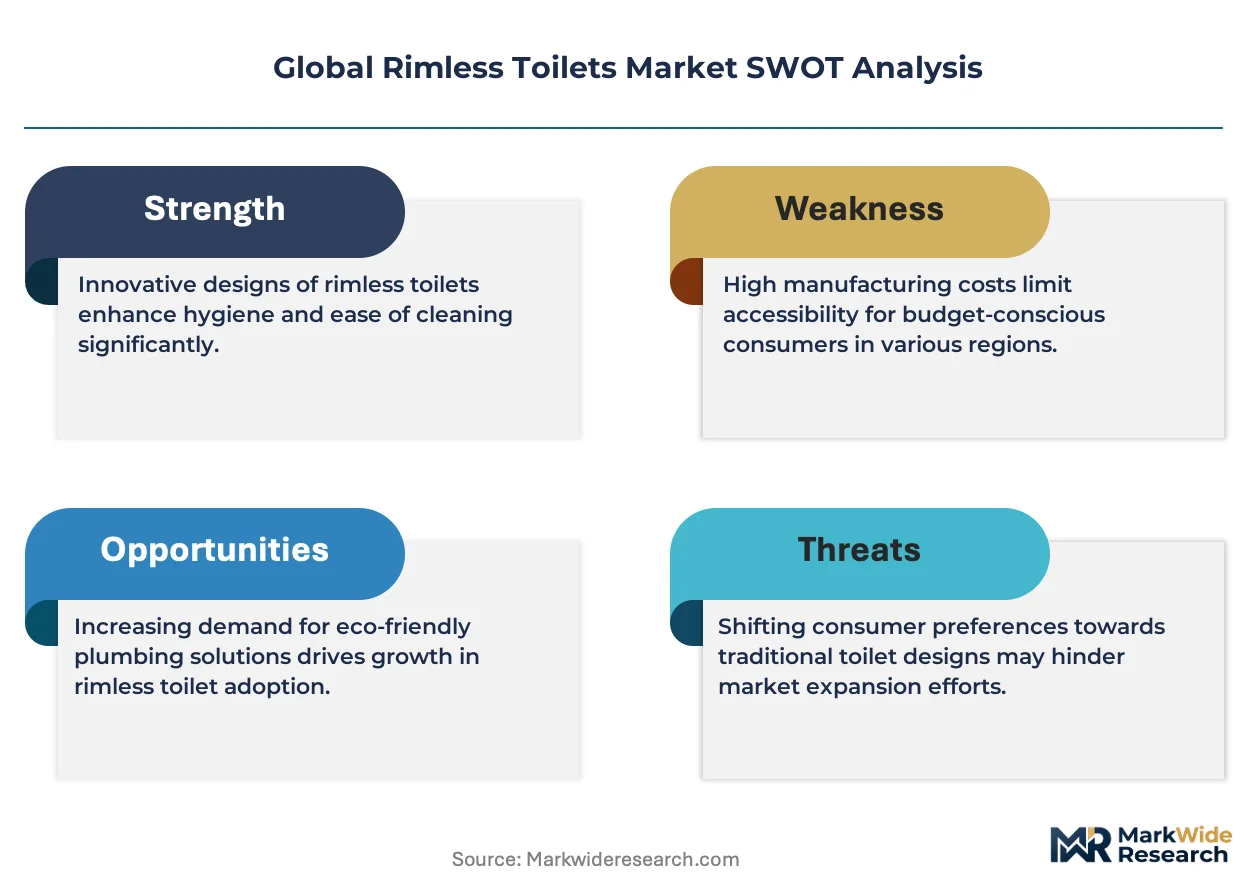
The Global Rimless Toilets Market functions as a stable compounder anchored by regulatory mandates from EPA WaterSense and EU Ecodesign that compress fixture replacement cycles across institutional building stock.
For Market Incumbents: Extend surface engineering differentiation through patented ceramic glaze investments that harden healthcare procurement criteria in Germany and the United States. Deepen backward integration into kaolin supply to defend margin structures against Guangdong Province input volatility. Certification investment in simultaneous EPA WaterSense and JIS compliance creates switching costs against emerging entrants.
For New Entrants and Emerging Players: Enter via compact wall-mounted configurations targeting Southeast Asian luxury hospitality procurement where spatial efficiency commands premium positioning. Smart toilet convergence in European residential segments offers penetrable white space. Direct engagement with architectural specification teams bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized ceramic glaze engineers possessing healthcare-validated antimicrobial claims. Long-term viability over a multi-year horizon rests on regulatory tightening trajectories in water-efficiency mandates. Watch EPA WaterSense threshold revisions and EU Ecodesign ceiling reductions as inflection signals for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Supply | Captive sourcing from Guangdong Province mining districts insulates margin structures from input volatility. |
| Smart Toilet Platform Convergence | Sensor-integrated bidet functions from Japanese origins penetrate European luxury hospitality specification channels. |
| Antimicrobial Surface Certification | Healthcare procurement criteria in Germany and the United States harden around documented bacterial reduction claims. |
| Direct Architectural Engagement | Specification-driven procurement in German and Japanese commercial construction displaces traditional distributor relationships. |
| Multi-Jurisdiction Compliance Investment | Simultaneous EPA WaterSense, EU Ecodesign, and JIS testing extends product launch timelines but creates competitive moats. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic manufacturing plant managers, hospitality procurement directors, architectural specification leads, and healthcare facility managers with secondary validation from EPA WaterSense certification databases, EU Ecodesign regulatory filings, JIS standards documentation, and customs trade records. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting across product type, end user, dimensional tier, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves incorporating regulatory mandate implementation timelines, renovation cycle compression patterns, and hospitality development pipelines. Water-efficiency threshold trajectories and antimicrobial surface claim validation requirements constituted industry-specific forecast inputs.
Inputs from EPA certification registries and EU regulatory filings were available through the study window; gaps in real-time hospitality procurement transaction data introduce uncertainty bands around commercial segment velocity. Forecasts reflect documented assumptions regarding regulatory implementation pacing and kaolin supply stability. Material deviation in EPA WaterSense threshold revisions or Guangdong Province mining output warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Hand Wash Station Market
Household Items
Robotic Pool Cleaner Market
Household Items
Home Scales Market
Household Items
Hydralight Lanterns Market
Household Items
Smart Fork Market
Household Items
Cutlery Steel Market
Household Items
Drinkware Market
Household Items
Mosquito Trap Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Remote Control Holder Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Toilet Deodorant Market