
 Industrial Vacuum Cleaner Market | 2026-2036
Industrial Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Vacuum Cleaner Market Outlook
Buyer concentration among large manufacturing conglomerates is hardening as facility consolidation accelerates across automotive and pharmaceutical campuses. Alfred Kärcher GmbH & Co. KG leverages its German engineering heritage to dominate premium centralized systems for European industrial parks. Nilfisk Group anchors its position through deep channel control in North American food processing plants. Tennant Company differentiates via robotics integration for autonomous cleaning workflows in warehouse environments.
An industrial vacuum cleaner is a motorized suction device engineered to remove particulates, liquids, and hazardous debris from commercial and manufacturing environments, typically operating at airflow rates exceeding 100 cubic feet per minute with sealed HEPA filtration to capture particles down to 0.3 microns. Its primary purpose is maintaining regulatory-compliant air quality, preventing combustible dust accumulation, and protecting sensitive production equipment from contamination. Portable units command the largest installed base due to their flexibility across construction and textile floors, though robotic systems represent the fastest-expanding margin pool as labor costs escalate. Wet-dry dual-motor configurations sustain premium pricing in hazardous waste applications where cross-contamination risks justify capital expenditure.
OSHA combustible dust standards and EPA National Emission Standards for Hazardous Air Pollutants shape equipment specifications, forcing upgrades to certified explosion-proof models in metalworking and chemical plants. The EU ATEX directives and ISO 14644 cleanroom classifications further segment procurement criteria across pharmaceutical and aerospace end users. Stakeholders must monitor divergence between regional certification regimes when scaling product platforms across multiple jurisdictions.
Market Dynamics
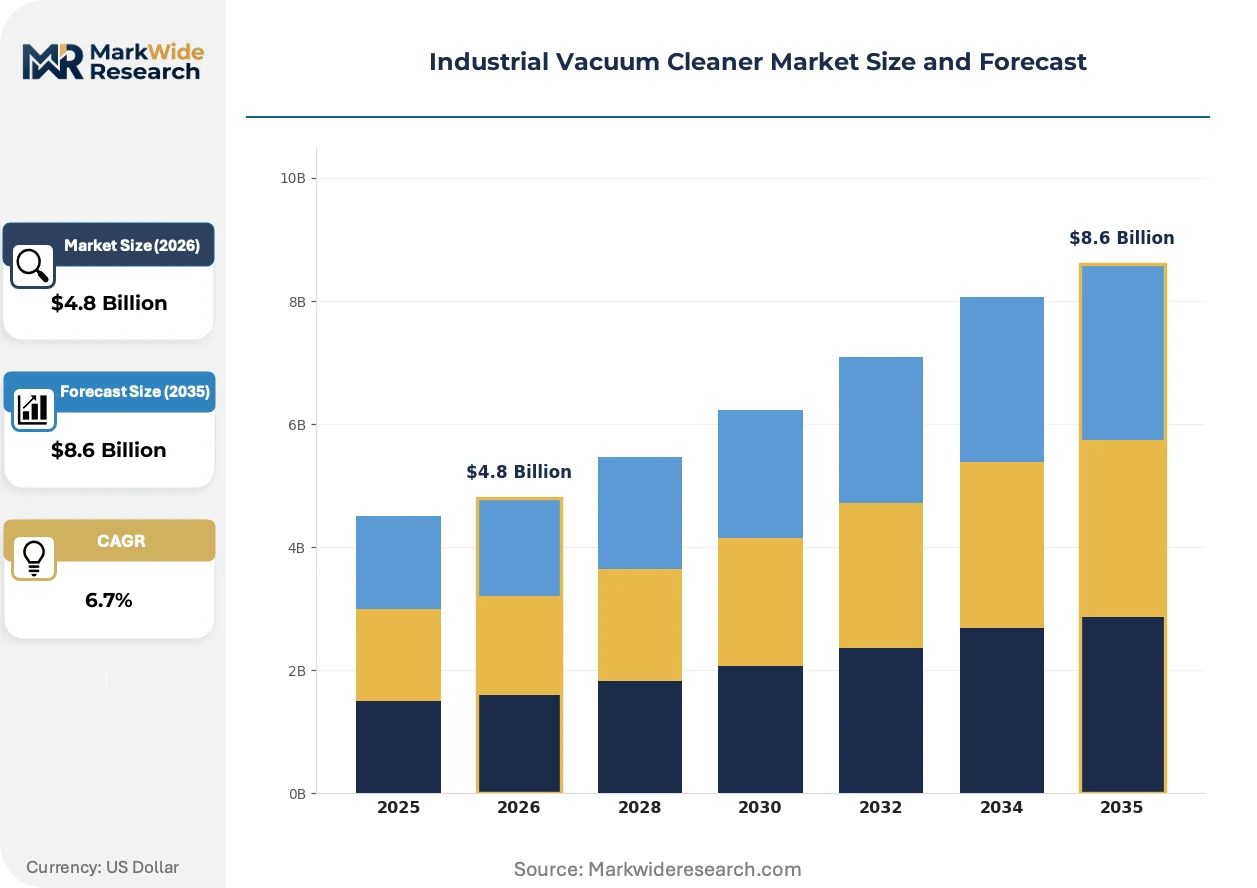
Facility consolidation across automotive and pharmaceutical campuses is hardening buyer concentration, forcing equipment vendors to restructure pricing and service models around fewer, larger procurement centers with centralized technical specifications.
Growth Catalysts
- OSHA Combustible Dust Standards:Metalworking plants in the United States must upgrade to certified explosion-proof extraction systems, creating mandatory replacement cycles for legacy equipment.
- Precision Engineering Clusters:German industrial parks drive premium equipment procurement as facility managers prioritize ATEX-compliant centralized systems for multi-tenant manufacturing zones.
- Sanitation Mandates:Food processing facilities are expanding fleet deployment of HEPA-sealed wet-dry units to satisfy USDA and FDA contamination control protocols.
Market Restraints
- High-Grade Motor Magnet Costs:Rare earth price volatility constrains margin flexibility for manufacturers dependent on neodymium permanent magnet motors.
- Regional Certification Fragmentation:Divergence between EU ATEX directives and US OSHA standards forces redundant testing and dual-SKU inventory strategies.
- Manual Cleaning Substitution:Low-wage jurisdictions retain labor-intensive sweeping protocols, delaying mechanized adoption in cost-sensitive textile and light assembly floors.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO cleanroom certification expansion creates demand for ISO 14644-compliant portable extraction units in emerging biologics clusters.
- Robotics Convergence:Autonomous navigation systems paired with industrial suction hardware enable overnight cleaning workflows in unmanned warehouse environments.
- Green Public Procurement:EU Green Deal criteria favor energy-efficient vacuum systems in municipal tender specifications across Netherlands and Denmark.
Industry Challenges
- ATEX Certification Timelines:Extended third-party validation periods delay product launches for explosion-proof configurations destined for chemical processing plants.
- Legacy System Integration:Retrofitting centralized vacuum networks into existing automotive paint shops requires custom ductwork engineering that compresses project margins.
- Specialized Technician Scarcity:Shortage of certified service engineers capable of HEPA seal integrity testing limits aftermarket expansion in remote industrial corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Vacuum Cleaner Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Centralized, Stationary, Robotic End User: Aerospace, Food Processing, Pharmaceuticals, Manufacturing Vacuum Technology: Wet, Dry, HEPA, Dual-Motor Application Area: Construction, Hazardous Waste, Automotive, Textile |
| Companies Covered | Alfred Kärcher GmbH & Co. KG, Nilfisk Group, Tennant Company, American Vacuum Company, Delfin Industrial Vacuums, Techtronic Industries, Pullman Ermator Inc., Ghibli & Wirbel SpA, NUMATIC INTERNATIONAL LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Vacuum Cleaner Market Strategic Shifts
Active filtration intelligence and autonomous mobility are compressing the boundary between environmental control equipment and connected facility infrastructure, reshaping how plant managers specify capital expenditure for contamination management.
HEPA-13 and ULPA filter media with embedded pressure-differential sensors are integrating real-time clog detection into centralized vacuum architectures. Pharmaceutical cleanroom operators in Switzerland and Singapore are specifying these configurations to eliminate unplanned downtime during batch production. The technology is integrating predictive maintenance protocols that trigger filter replacement before airflow degradation triggers ISO 14644 violations.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of vacuum bag and seal materials across European manufacturing supply chains. Equipment vendors must certify fluorine-free alternatives while maintaining particulate retention performance. Metalworking and chemical processing segments face the steepest compliance timelines as ECHA enforcement intensifies in Germany and Belgium.
Plant engineering departments are consolidating vendor relationships around full-service contracts that bundle equipment, consumables, and certification documentation. This behavior compresses the addressable market for standalone unit sales while expanding recurring revenue pools for integrated service providers. The shift is most pronounced in North American food processing and automotive assembly verticals where procurement teams prioritize single-source accountability for OSHA and EPA compliance documentation.
Industrial Vacuum Cleaner Market Segmentation
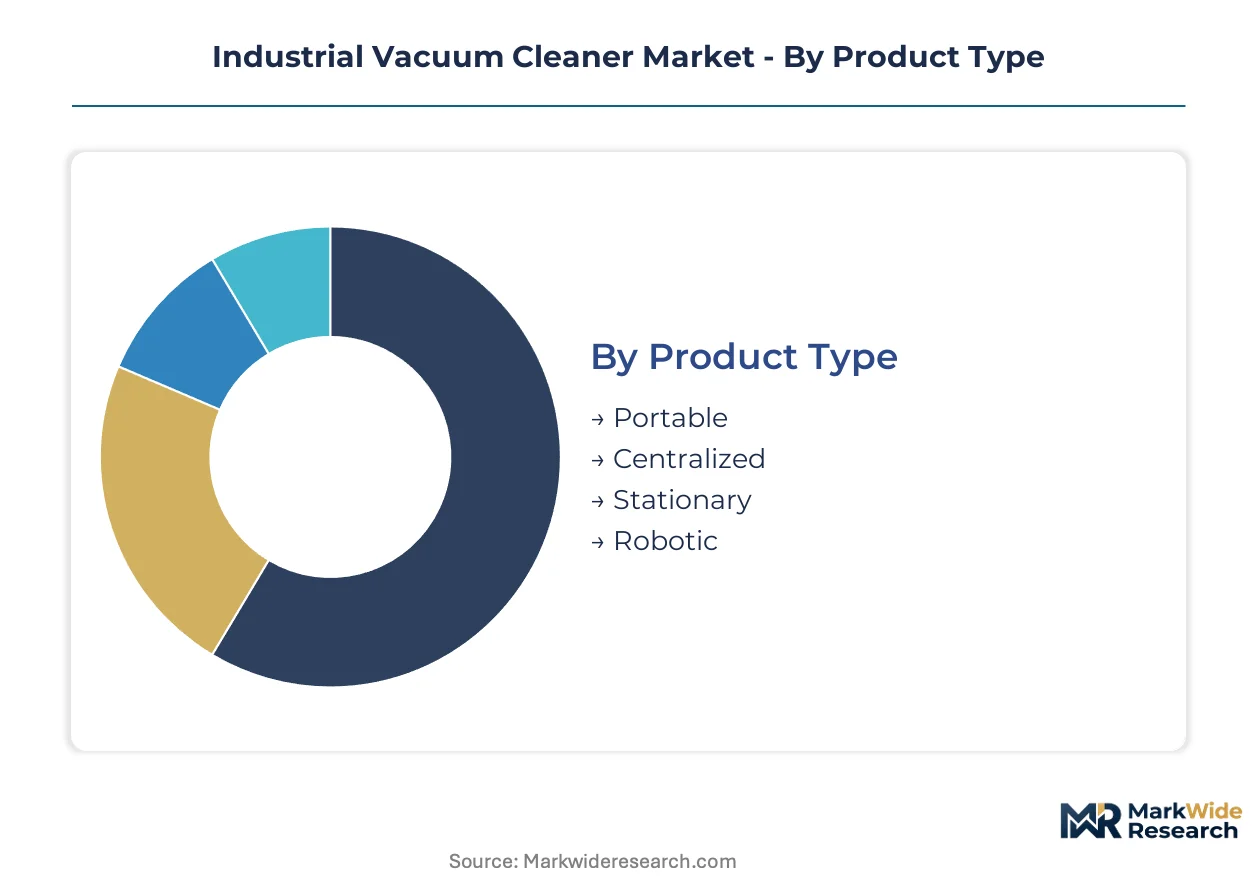
Industrial vacuum cleaner procurement patterns diverge sharply across facility types, with centralized architectures dominating consolidated manufacturing campuses while portable units retain primacy in fragmented construction environments. Specification requirements cascade differently through each segmentation axis—product configuration determines capital intensity, end-use dictates regulatory compliance tiers, and application area shapes contamination risk profiles.
Product Type:
Motor placement and ductwork architecture separate capital expenditure tiers across facility scales.
- Portable:Self-contained units with onboard collection canisters and caster-mounted mobility dominate construction sites and textile finishing floors. Demand concentrates in Germany's precision engineering clusters where multi-tenant workshops require flexible redeployment across production cells.
- Centralized:Fixed vacuum plants with networked ductwork and remote filtration stations serve consolidated automotive and pharmaceutical campuses. Buyer concentration among large manufacturing conglomerates hardens procurement leverage for these systems.
- Stationary:Fixed-position single-point extraction units anchor dedicated workstations in metalworking and chemical processing environments. OSHA combustible dust mandates drive replacement cycles in United States facilities.
- Robotic:Autonomous navigation platforms with integrated suction hardware enable overnight cleaning workflows in unmanned warehouse environments. Labor cost escalation in Netherlands and Denmark accelerates deployment.
Mature deployment sits with Portable units. Newer deployment is concentrated in Robotic systems.
End User:
Regulatory exposure and contamination sensitivity stratify procurement specifications across verticals.
- Food Processing:USDA and FDA sanitation protocols mandate HEPA-sealed wet-dry configurations with stainless steel contact surfaces. Fleet expansion accelerates across United States protein processing and dairy packaging facilities.
- Pharmaceuticals:ISO 14644 cleanroom classifications and EU ATEX directives specify ULPA filtration with real-time pressure differential monitoring. Swiss and Singaporean biologics manufacturers lead specification intensity.
- Aerospace:Composite dust extraction and solvent vapor recovery requirements drive explosion-proof configurations. Germany's industrial parks prioritize ATEX-compliant centralized architectures.
- Manufacturing:General metalworking and assembly operations balance capital constraints against OSHA combustible dust compliance. Manual cleaning substitution delays mechanization in cost-sensitive jurisdictions.
Capital intensity peaks in Pharmaceuticals. Volume throughput concentrates in Manufacturing.
Vacuum Technology:
Suction mechanism and filtration grade determine particulate capture capability and hazardous material handling authority.
- HEPA:High-efficiency particulate air filtration captures 99.97% of particles down to 0.3 microns through pleated glass fiber media. Pharmaceutical cleanroom operators in Switzerland specify embedded pressure-differential sensors for predictive maintenance protocols.
- Dual-Motor:Independent wet and dry suction pathways prevent cross-contamination in hazardous waste applications. Premium pricing sustains in chemical processing plants where ECHA enforcement intensifies.
- Dry:Single-path particulate extraction serves non-hazardous dust environments in construction and light assembly. Cost-sensitive textile floors in low-wage jurisdictions retain these configurations.
- Wet:Liquid recovery systems with corrosion-resistant wetted parts address spill containment and slurry extraction. Metalworking coolant recovery drives demand in automotive powertrain plants.
Regulatory compliance anchors HEPA specifications. Operational flexibility drives Dual-Motor adoption.
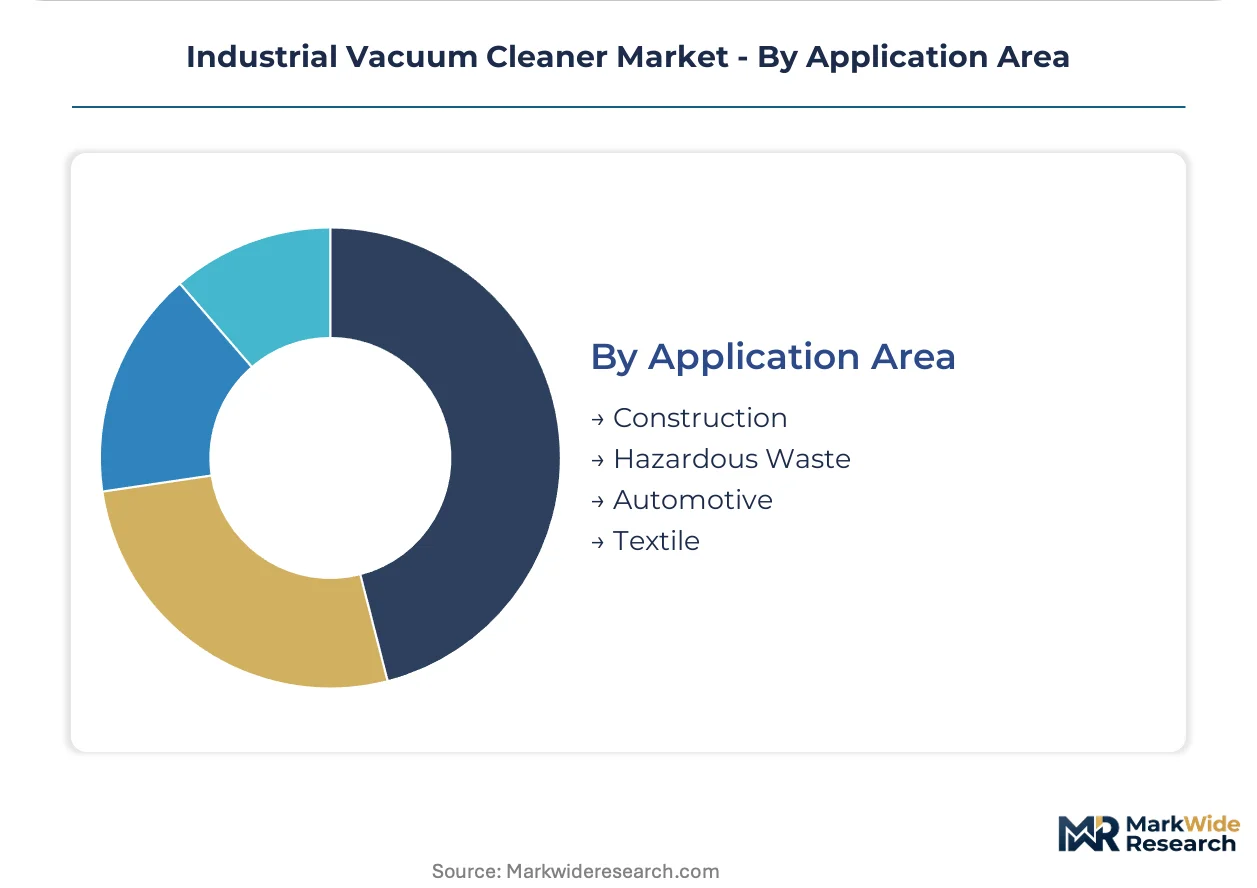
Application Area:
Contamination risk profile and debris composition shape equipment durability and certification requirements.
- Hazardous Waste:Certified configurations for toxic dust, asbestos, and chemical slurry handling require specialized drum liners and sealed disposal protocols. EPA National Emission Standards compel upgrades in United States chemical plants.
- Automotive:Paint overspray extraction and weld fume capture demand spark-resistant construction and high-volume airflow. Retrofitting centralized networks into existing paint shops compresses project margins.
- Construction:Ruggedized portable units with reinforced hoses and debris deflectors endure silica dust and demolition debris. OSHA silica standards drive specification upgrades across United States residential and commercial sites.
- Textile:Fiber and lint extraction with anti-static grounding prevents combustion risks in spinning and weaving operations. Manual sweeping protocols delay mechanized adoption in cost-sensitive production floors.
Certification burden concentrates in Hazardous Waste. Volume scale sits with Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet supply corridors from Inner Mongolia and Sichuan anchor motor production for vacuum equipment across Asia-Pacific manufacturing zones. Procurement patterns diverge sharply between jurisdictions with mature OSHA enforcement and emerging regulatory frameworks.
United States
Metalworking clusters in Michigan and Ohio drive explosion-proof system upgrades under OSHA combustible dust mandates. EPA National Emission Standards for Hazardous Air Pollutants compel chemical processors in Texas and Louisiana to retrofit extraction networks. Automotive paint shops in Detroit-Warren corridor face compressed margins from legacy ductwork integration challenges.
Germany
Precision engineering parks in Baden-Württemberg and Bavaria prioritize ATEX-compliant centralized architectures for multi-tenant manufacturing zones. ECHA enforcement intensifies REACH compliance timelines for fluorine-free seal materials. Stuttgart and Munich industrial corridors anchor premium equipment procurement for aerospace composite dust extraction.
China
MIIT industrial upgrading programs accelerate mechanized adoption in Yangtze River Delta textile corridors previously dependent on manual sweeping. GB standards for workplace dust exposure tighten specification requirements in Jiangsu and Zhejiang metalworking clusters. Shanghai and Suzhou biologics manufacturers import ISO 14644-compliant portable units for cleanroom operations.
India
CDSCO cleanroom certification expansion in Hyderabad and Bengaluru biologics clusters creates demand for HEPA-sealed portable extraction. FSSAI sanitation protocols drive fleet expansion in Maharashtra dairy packaging and Gujarat protein processing facilities. Cost-sensitive textile floors in Tamil Nadu and Gujarat retain labor-intensive protocols, delaying mechanization.
Switzerland
Swissmedic-regulated biologics manufacturers in Basel and Zürich specify ULPA filtration with embedded pressure-differential sensors for predictive maintenance. ISO 14644 cleanroom classifications anchor specification intensity exceeding neighboring jurisdictions. Precision pharmaceutical clusters prioritize real-time clog detection to eliminate unplanned batch production downtime.
Industrial Vacuum Cleaner Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue robotics convergence and autonomous navigation platforms. The vendor base stratifies across three capability clusters: German-engineered premium centralized systems, North American food-processing specialists with deep channel control, and robotics-integrated warehouse automation providers. Competitive moves concentrate on strategic partnerships for aftermarket service networks and portfolio diversification into predictive maintenance platforms.
Within the heritage-engineering tier, Alfred Kärcher GmbH & Co. KG exemplifies German fabrication dominance for European industrial parks. Nilfisk Group anchors Scandinavian design influence in North American food safety applications. Tennant Company represents the robotics-convergence archetype for autonomous warehouse workflows. These three occupy distinct positioning vectors without direct segment overlap.
| Leading Market Players |
|---|
| Alfred Kärcher GmbH & Co. KG |
| Nilfisk Group |
| Tennant Company |
| American Vacuum Company |
| Delfin Industrial Vacuums |
| Techtronic Industries |
| Pullman Ermator Inc. |
| Ghibli & Wirbel SpA |
| NUMATIC INTERNATIONAL LTD |
| Others |
Value Chain & Pricing Dynamics
Neodymium permanent magnet costs cascade through motor manufacturing tiers, compressing margins for explosion-proof configurations while premium ATEX-certified systems absorb input volatility through long-term service contracts with German automotive clusters.
Pricing Analysis
Extended warranty and filter-replacement bundling separates premium German-engineered centralized systems from unbundled portable units in construction applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—ATEX-compliant configurations command substantial premia over OSHA-baseline models, while after-sales service intensity drives price differentiation between food-processing specialists and warehouse automation providers. Cost compression in standard-tier portable units is intensifying because rare earth magnet volatility constrains margin flexibility. Small textile workshops in Tamil Nadu exhibit highest price sensitivity; Swiss biologics manufacturers demonstrate lowest sensitivity due to batch-downtime avoidance priorities.
Supply Chain Analysis
Dual-sourcing requirements for HEPA filter media mandate multi-supplier qualification across German glass-fiber producers and Japanese synthetic membrane specialists, constraining single-source dependence despite consolidation pressure. Motor production draws from China's Inner Mongolia rare earth corridors and South Korean permanent magnet fabricators, while stainless steel contact surfaces for food-processing units source from Indian and Italian mills. Single-source vulnerability concentrates in neodymium oxide refining. Distribution runs through authorized dealer networks for centralized systems and direct e-commerce channels for portable replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
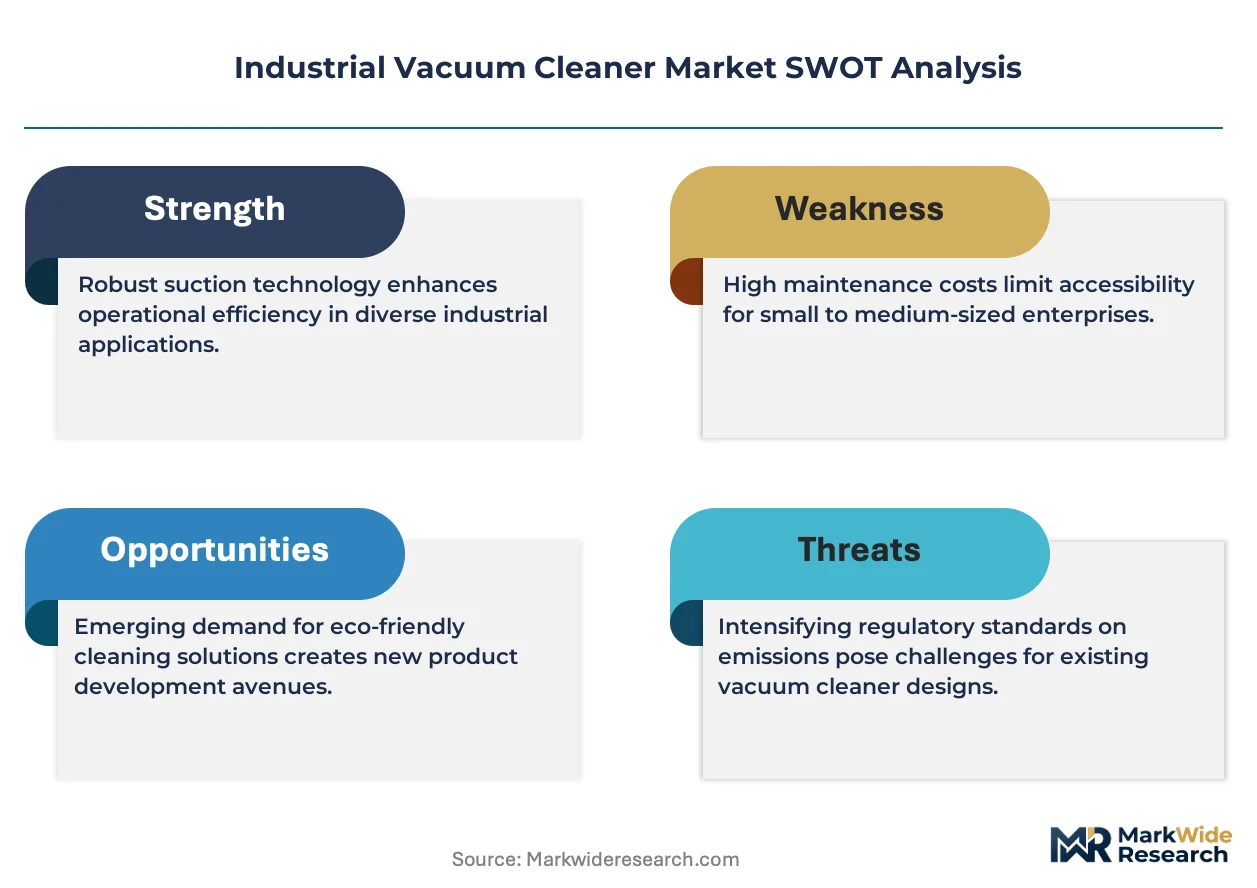
This market functions as a cost-of-compliance story where OSHA combustible dust mandates erect barrier-to-entry moats protecting certified incumbents from unqualified competitors.
For Market Incumbents: Deepen aftermarket service network density in remote industrial corridors to capture recurring filter-replacement revenue and lock out emerging robotics-integrated challengers. Expand captive supply of HEPA filter media through backward integration into glass-fiber pleating operations, insulating margin structures from REACH-driven material reformulation costs.
For New Entrants and Emerging Players: Direct-to-industrial-buyer digital platforms enable bypass of entrenched dealer networks controlling North American food-processing procurement. Target Indian pharmaceutical cleanroom certification expansion as the most penetrable geography, deploying ISO 14644-compliant portable units through CDSCO-registered distributor partnerships.
For Investors and Strategic Acquirers: CDSCO cleanroom certification timeline acceleration is the leading indicator that Indian biologics infrastructure investment has crossed threshold viability. Acquisition target archetype: mid-cap European manufacturers with ATEX certification portfolios and underutilized service technician capacity. Watch for robotics-convergence patent filing velocity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive HEPA glass-fiber supply insulates margins from REACH fluorine-free reformulation mandates in Germany. |
| Robotics Convergence Partnership | Autonomous navigation licensing from warehouse automation specialists accelerates overnight cleaning workflow deployment. |
| Long-term Service Contract Expansion | Full-service bundling with OEMs in North American automotive paint shops compresses standalone unit sales competition. |
| Regional Certification Pre-qualification | Dual ATEX-OSHA testing investment enables single-SKU scaling across EU and US pharmaceutical campuses. |
| Aftermarket Technician Training Program | Certified HEPA seal integrity testing capacity expansion addresses scarcity limiting remote corridor service penetration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. OSHA enforcement databases, EPA emission compliance reports, EU ATEX certification registries, and import-export manifests provided validation layers. Bottom-up facility-level equipment counts and top-down manufacturing value-added estimates were triangulated for market sizing.
Granularity-level modeling deployed product-type, end-user vertical, vacuum technology grade, and application-area hazard classification across the analysis window. CAGRs derived from regression against industrial capital expenditure indices and regulatory enforcement intensity metrics. Forecast inputs incorporated CDSCO certification expansion timelines and robotics adoption curves in warehouse automation.
The model holds under steady regulatory enforcement intensity; deviation in OSHA inspection frequency or ECHA REACH timeline acceleration would shift replacement cycle assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Household Scales Market
Household Items
Pet Safe Cleaners Market
Household Items
Residential Air Purifiers Market
Household Items
Party Balloon Market
Household Items
Smart Shower Market
Household Items
Smart Drying Racks Market
Household Items
Chest Freezers Market
Household Items
Leaf Blower Market
Household Items
Dryer Sheets Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Toilet Brush Market
Household Items
Global Buddhist Supplies Market
Household Items
Coin-Operated Laundries Market
Household Items
Titanium Thermos Cup Market
Household Items
US Air Fresheners Market
Household Items
US Air Purifier Market