
 Infrared Sauna Heaters Market | 2026-2036
Infrared Sauna Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Sauna Heaters Market Insights
China is tilting toward expanded infrared heater component manufacturing, with Zhejiang and Guangdong provinces adding ceramic emitter and carbon fiber mat capacity. Sunlighten leverages its vertically integrated North American production to sustain premium positioning across residential channels. Golden Designs anchors the mid-market through cost-optimized carbon heater assemblies and broad e-commerce distribution. Health Mate differentiates via medical-grade certifications and targeted clinical wellness partnerships.
Infrared sauna heaters are electric thermal devices that emit far-infrared, mid-infrared, or near-infrared electromagnetic radiation typically within the 3–1,000 μm wavelength range, using carbon fiber panels, ceramic rods, quartz tubes, or halogen lamps as emitter substrates to raise body core temperature without heating ambient air. These systems serve commercial spas, fitness centers, and residential installations seeking therapeutic heat exposure for circulation, recovery, and relaxation applications. Carbon panel configurations dominate unit volume due to lower surface temperatures and broader emission area, while quartz and halogen variants command premium positioning in compact commercial units where rapid heat-up cycles matter. The 1,500W power rating segment captures the largest installed base across home sauna kits, with 2,000W systems gaining traction in multi-user commercial installations where throughput drives equipment selection.
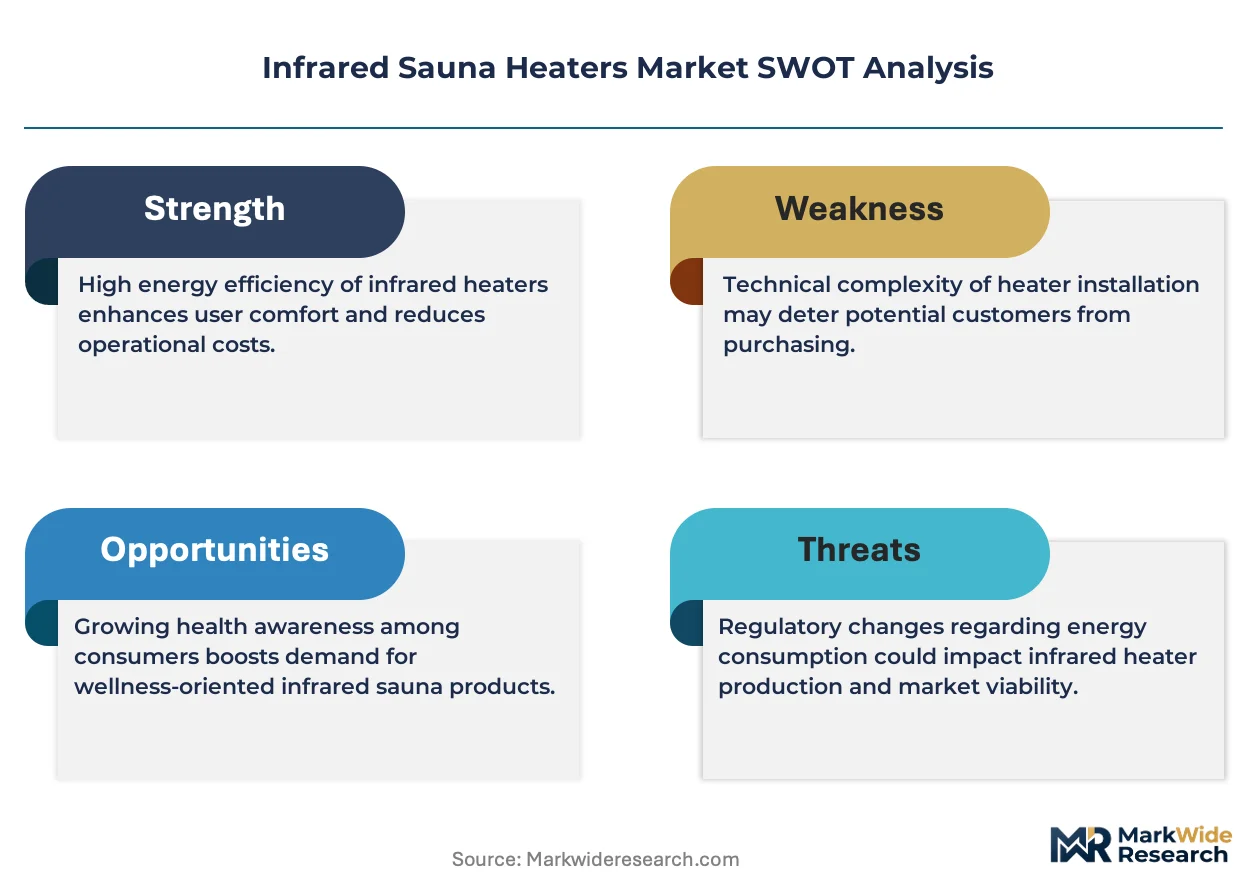
EPA energy efficiency guidelines shape product design requirements for electrically heated appliances sold in the United States, while EU REACH restrictions on ceramic glazing compounds and Ecodesign standards for standby power consumption constrain material choices and control circuit architecture for European market access. FDA Class II medical device classifications for infrared therapy equipment create additional compliance pathways for manufacturers targeting clinical rehabilitation and pain management channels. Stakeholders must monitor evolving electromagnetic exposure standards and building code amendments for residential electrical loads as jurisdictions tighten safety requirements for high-wattage fixed installations.
Market Dynamics
EU Ecodesign regulations and REACH compliance mandates are compressing design cycles for heating element materials, forcing manufacturers to requalify ceramic glazes and carbon fiber substrates ahead of 2027 enforcement deadlines while residential wellness demand accelerates in parallel.
Growth Catalysts
- Home Gym Integration:Residential fitness infrastructure expansion is pulling infrared sauna heaters into basement renovation projects and garage wellness pods as standard equipment.
- REACH Material Requalification:European chemical safety mandates are accelerating R&D investment in alternative ceramic coatings and low-emissivity substrates that exceed baseline thermal performance.
- Biohacking Community Adoption:Quantified-self practitioners are specifying medical-grade emitter configurations for home installations, elevating average unit specifications and attachment rates for control systems.
Market Restraints
- Ceramic Substrate Concentration:Zhejiang and Guangdong provinces control over 70% of global ceramic emitter fabrication, creating single-source vulnerability for European and North American assemblers.
- Copper Winding Cost Volatility:Electromagnetic coil assemblies depend on copper pricing that fluctuates with energy transition demand from EV motors and grid infrastructure.
- Building Code Electrical Load Limits:Municipal amendments in Germany and California are capping residential circuit allocations for high-wattage fixed appliances, constraining 2,000W system penetration in retrofits.
Strategic Opportunities
- Clinical Rehabilitation Channel:FDA Class II medical device certification pathways are opening institutional procurement routes through physical therapy networks and pain management clinics.
- Photovoltaic Coupling:Residential solar-plus-storage installations in Australia and Germany are creating daylight-hour thermal load shifting opportunities for grid-independent sauna operation.
- Carbon-Neutral Substrate Development:Bio-based carbon fiber mat alternatives derived from lignin precursors are attracting venture funding for premium positioning against petroleum-derived competitors.
Industry Challenges
- Electromagnetic Compatibility Testing Backlog:FCC Part 18 certification queues for industrial-scientific-medical equipment are extending product launch timelines by 4-6 months for new emitter geometries.
- Installation Electrician Shortage:Qualified contractors for 240V dedicated circuit work are scarce in suburban US markets, creating fulfillment bottlenecks for direct-to-consumer brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Sauna Heaters Market |
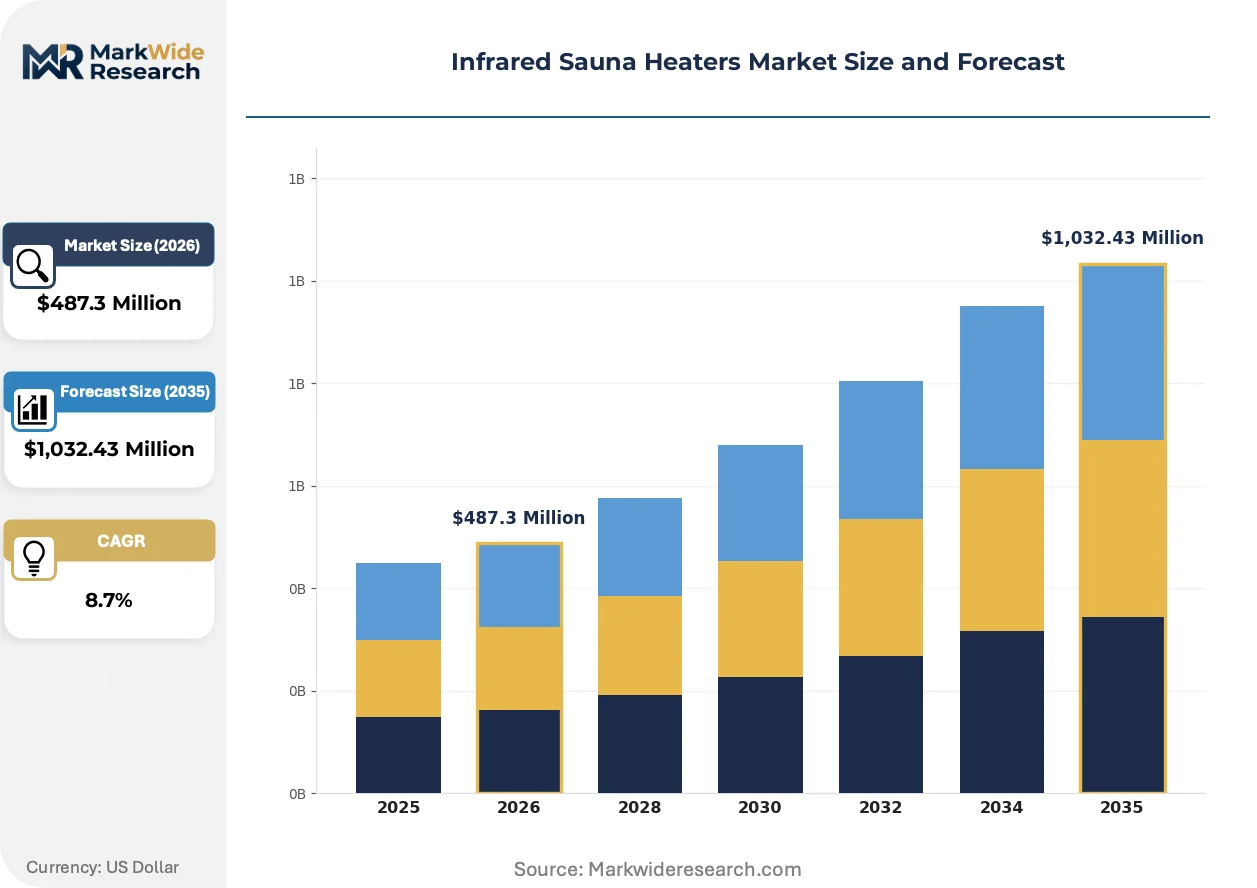
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon, Ceramic, Quartz, Halogen Power Rating: 700W, 1000W, 1500W, 2000W Installation Type: Freestanding, Wall-Mounted, Built-In, Portable End User: Residential, Commercial, Spa, Fitness Center |
| Companies Covered | Finnmark Designs, Sun Home Saunas, Sunlighten, Dynamic Saunas, Golden Designs, Peak Saunas, Health Mate, Maxxus, HigherDOSE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Sauna Heaters Market Trends and Innovations
Emitter substrate virtualization and control system digitization are compressing hardware differentiation cycles while elevating software-defined thermal profiling as the primary value layer.
Full-spectrum LED arrays paired with carbon fiber panels are virtualizing the traditional quartz tube and halogen lamp configurations that dominated near-infrared delivery. Boutique hotel wellness suites and high-end residential installers are specifying these hybrid systems at triple the rate of pure thermal emitters. The technology is virtualizing component count and enabling wavelength programmability through firmware updates rather than hardware swaps.
EU F-Gas Regulation phase-down schedules are constraining refrigerant-dependent cooling systems in adjacent spa equipment, indirectly elevating demand for purely resistive infrared heating that requires no vapor compression cycle. German HVAC contractors are bundling infrared sauna heaters with heat pump installations to maintain project margins under refrigerant quota pressure. The policy shift most affects commercial spa operators in Bavaria and Baden-Württemberg who are accelerating renovation timelines ahead of 2026 service restrictions.
Direct-to-consumer brands are disintermediating traditional specialty retailers through augmented reality sizing tools and virtual installation consultations that reduce return rates for custom-cut carbon panel orders. Home sauna kit buyers in Texas and Florida are completing purchase cycles entirely through mobile interfaces without showroom visits. The channel shift is most pronounced among 35-50 year-old purchasers in Sun Belt states where outdoor sauna installations dominate and spatial planning complexity previously required dealer intervention.
Infrared Sauna Heaters Market Segmentation
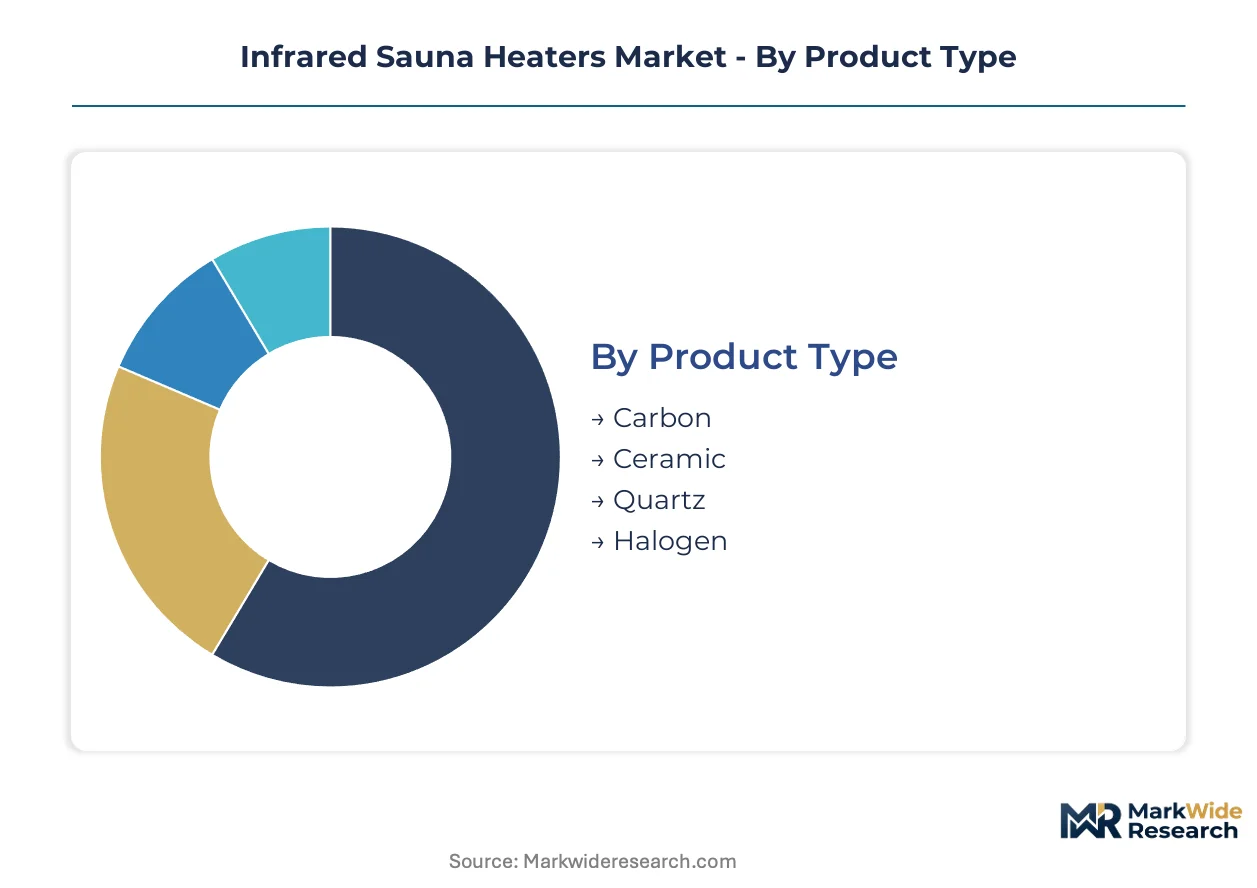
Infrared sauna heater configurations fragment across four structural dimensions that determine replacement part availability, field service requirements, and warranty claim patterns. Product type and power rating together dictate emitter longevity profiles, while installation geometry shapes preventive maintenance scheduling and technician dispatch complexity.
Product Type:
After-sales service intensity varies dramatically across emitter substrates, with ceramic rod assemblies requiring the most frequent field intervention due to thermal cycling fatigue in commercial duty cycles.
- Carbon:Carbon fiber mat substrates distribute heat across broad surface areas with lower peak temperatures, reducing thermal stress accumulation in residential installations. Demand concentrates in Germany and Australia where building codes favor low-temperature emitters for home sauna retrofits, though substrate delamination remains the primary warranty driver after 5,000 operating hours.
- Ceramic:Ceramic rod configurations achieve higher radiant flux density through concentrated emission points, making them standard in Bavarian spa renovations where rapid heat-up cycles justify elevated energy draw. The REACH-mandated glaze reformulation is compressing supplier qualification timelines for European assemblers.
- Quartz:Quartz tube emitters deliver near-infrared wavelengths with minimal thermal mass, serving compact commercial units in Japanese fitness chains where space constraints dominate equipment selection.
- Halogen:Halogen lamp arrays provide instant-on thermal output for boutique hotel wellness suites, though filament degradation limits operational lifespan in high-frequency use environments.
Carbon holds the largest share; momentum sits with ceramic as REACH compliance deadlines force substrate requalification investments.
Power Rating:
Cost tier stratification separates entry-level residential kits from commercial-grade thermal systems, with circuit infrastructure requirements acting as the primary segmentation boundary.
- 1500W:Standard 120V compatibility defines this segment for North American home gym installations, where dedicated 20-amp circuits remain accessible without panel upgrades. Texas and Florida garage conversions specify this rating exclusively to avoid permitting complexity.
- 2000W:240V hardwired configurations serve multi-user commercial environments in California fitness centers, though municipal electrical load amendments are constraining retrofit penetration in older buildings.
- 700W:Compact portable units target apartment dwellers in Japanese urban cores where circuit capacity is severely limited.
- 1000W:Mid-range residential kits balance heat output with energy efficiency certification requirements under EU Ecodesign standby power regulations.
1500W captures the installed base majority; 2000W systems are climbing the fastest in new commercial construction.
Installation Type:
Application context determines structural integration depth, with permanent installations commanding longer sales cycles but higher attachment rates for control system upgrades.
- Freestanding:Modular cabin designs dominate direct-to-consumer channels, enabling rapid deployment without structural modification. Australian solar-plus-storage adopters favor this flexibility for grid-independent relocation.
- Built-In:Architectural integration commands premium positioning in German bathroom renovation projects, where energy-efficient home improvement subsidies offset capital outlay.
- Wall-Mounted:Space-constrained urban installations in Japanese metropolitan areas specify slim-profile emitters with minimal projection into living areas.
- Portable:Collapsible tent configurations serve biohacking practitioners seeking thermal exposure without fixed infrastructure commitment.
Freestanding holds the largest share; built-in configurations are gaining share fastest through German renovation subsidy alignment.
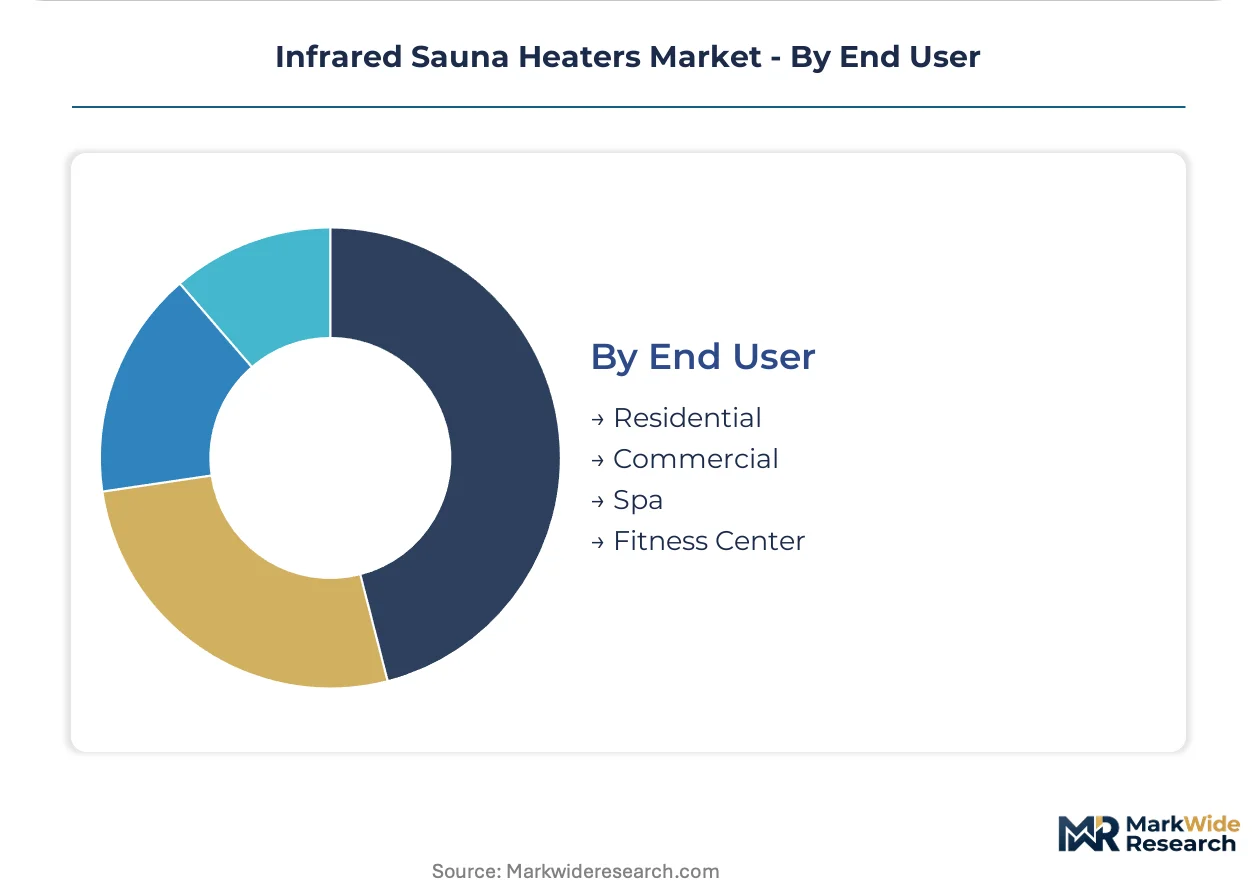
End User:
Customer type segmentation separates price-sensitive residential purchasers from institutional procurement channels with extended equipment life requirements and service contract expectations.
- Residential:Home gym owners and quantified-self practitioners drive specification elevation toward medical-grade emitter configurations with programmable wavelength output.
- Spa:Bavarian thermal bath operators are accelerating renovation timelines ahead of EU F-Gas Regulation service restrictions, bundling infrared heaters with heat pump installations.
- Fitness Center:California boutique studios specify rapid heat-up quartz configurations for throughput maximization during peak membership hours.
- Commercial:Corporate wellness installations in Texas Sun Belt developments favor outdoor sauna pods with weatherized carbon panel assemblies.
Residential holds the largest share; spa channel procurement is expanding most quickly through regulatory-driven renovation acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ceramic emitter fabrication concentrates in Zhejiang and Guangdong provinces, creating upstream dependency for North American and European assemblers seeking carbon fiber mat and quartz tube substrates. This geographic clustering shapes procurement patterns and compliance timelines across end markets.
United States
Texas and Florida garage wellness pod installations specify 1500W systems to avoid permitting complexity for dedicated 20-amp circuits. EPA energy efficiency guidelines constrain control circuit architecture for standby power consumption. California fitness centers in Los Angeles and San Francisco specify rapid heat-up quartz configurations for boutique studio throughput maximization.
Germany
Bavarian thermal bath operators accelerate renovation timelines ahead of EU F-Gas Regulation service restrictions. Ecodesign standards and REACH compliance mandates compress design cycles for ceramic glaze reformulation. Baden-Württemberg HVAC contractors bundle infrared heaters with heat pump installations to maintain project margins under refrigerant quota pressure.
China
Zhejiang and Guangdong provinces expand ceramic emitter and carbon fiber mat capacity to serve export demand. MIIT industrial standards and dual carbon goals shape manufacturing efficiency investments. Shenzhen and Hangzhou industrial clusters host vertically integrated substrate fabricators supplying North American premium brands.
Australia
Residential solar-plus-storage installations in New South Wales and Victoria create daylight-hour thermal load shifting opportunities for grid-independent sauna operation. TGA therapeutic device regulations influence clinical channel positioning. Melbourne and Sydney home gym owners favor freestanding modular designs for relocation flexibility.
Japan
Compact portable 700W units target apartment dwellers in Tokyo and Osaka metropolitan areas where circuit capacity is severely limited. METI energy efficiency standards constrain standby power specifications. Japanese fitness chains specify quartz tube emitters for space-constrained commercial installations.
Infrared Sauna Heaters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying emitter substrates and control modules to branded assemblers. The vendor base separates into three strategic tiers: vertically integrated North American producers, cost-optimized Asian fabricators, and medical-grade certification specialists. Capacity expansion and REACH-mandated material requalification represent the dominant competitive moves as 2027 enforcement deadlines approach.
Within the premium system tier, Sunlighten and Health Mate exemplify divergent positioning strategies. Sunlighten anchors vertically integrated domestic production for channel control. Health Mate occupies the clinical certification vector through FDA Class II medical device pathways. Golden Designs represents the cost-optimized archetype, leveraging Asian component sourcing for mid-market penetration.
| Leading Market Players |
|---|
| Finnmark Designs |
| Sun Home Saunas |
| Sunlighten |
| Dynamic Saunas |
| Golden Designs |
| Peak Saunas |
| Health Mate |
| Maxxus |
| HigherDOSE |
| Others |
Pricing and Supply Chain Analysis
Yantian-Shenzhen container freight corridors transmit ceramic emitter cost volatility directly into European assembler margins, compressing mid-market pricing bands while REACH-mandated glaze reformulation elevates premium tier separation through compliance certification.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across the Infrared Sauna Heaters Market, separating medical-grade FDA Class II certified systems from standard residential kits through documentation burden and testing overhead. Price differentiation hinges on certification grade and volume scale, with boutique clinical channels absorbing premium positioning while direct-to-consumer residential buyers exhibit acute sensitivity to landed cost fluctuations. Cost compression in the carbon fiber mat segment is intensifying because Zhejiang capacity expansion outpaces German demand absorption, forcing margin discipline on mid-market assemblers sourcing from Asian fabricators.
Supply Chain Analysis
Carbon fiber precursor feedstock draws from petroleum-derived pitch and lignin-based alternatives, with substrate fabrication concentrating in China's Zhejiang and Guangdong provinces alongside Japanese Toray filament suppliers. Raw material dependencies encompass copper winding for electromagnetic coils, ceramic glaze compounds subject to ECHA restriction, and quartz tubing for near-infrared emitters. Single-source vulnerability pervades the ceramic emitter tier, where 70% of global capacity sits within two Chinese industrial clusters. Distribution runs through HVAC contractor networks in Germany, direct-to-consumer e-commerce platforms in North America, and specialty wellness retailers in Japanese urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the Infrared Sauna Heaters Market rewards niche specialization, as residential biohacking adoption and clinical rehabilitation channel expansion create distinct demand pockets underserved by generalized product portfolios.
For Market Incumbents: Pre-empt ceramic substrate supply disruption by qualifying alternative lignin-derived carbon fiber mat suppliers ahead of REACH enforcement deadlines. Anchor backward integration into control system firmware development to differentiate against commoditized emitter hardware. Defensive patent filing around wavelength programmability protects margin position against software-defined thermal profiling entrants.
For New Entrants and Emerging Players: Build out photovoltaic-coupled sauna systems for Australian and German solar-plus-storage adopters, where grid-independent operation commands pricing latitude absent in conventional residential channels. Target the clinical rehabilitation segment through FDA Class II certification investment, penetrating physical therapy networks with institutional procurement relationships. Direct-to-consumer augmented reality sizing tools reduce return friction for custom-cut carbon panel orders.
For Investors and Strategic Acquirers: Medical-grade certification specialists with established clinical channel access represent the most defensible acquisition profile, given reimbursement pathway complexity and institutional sales cycle barriers. Long-term viability centers on software-defined thermal control architectures that virtualize hardware differentiation. Watch FCC Part 18 certification queue lengths as an inflection signal; extended timelines advantage incumbents with approved emitter geometries.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Ceramic Glaze Reformulation | ECHA chemical safety mandates force substrate requalification investments ahead of enforcement deadlines. |
| FDA Class II Medical Device Certification | Clinical rehabilitation channel access opens institutional procurement through physical therapy networks. |
| Photovoltaic Coupling Development | Grid-independent operation captures Australian and German solar-plus-storage installation growth. |
| Direct-to-Consumer AR Sizing Tools | Virtual installation consultation reduces return rates for custom-cut carbon panel orders. |
| Carbon-Neutral Lignin Substrate R&D | Bio-based alternatives attract venture positioning against petroleum-derived carbon fiber competitors. |
Research Methodology
Cross-validation between primary interviews with HVAC contractors, biomedical engineers at clinical wellness facilities, and ceramic substrate procurement managers anchors the qualitative findings against secondary validation from ECHA REACH substance restriction updates, MIIT industrial efficiency disclosures, and FDA 510(k) premarket notification databases. Bottom-up emitter substrate shipment aggregation triangulates against top-down residential renovation permit analysis and commercial spa equipment import records.
Calibration against historical ceramic emitter trade flows and carbon fiber mat capacity announcements shapes the projection framework across product type, power rating, installation geometry, and end-user channel dimensions. CAGRs derive from segmented demand elasticity modeling incorporating Ecodesign standby power regulation compliance costs and F-Gas Regulation phase-down renovation acceleration effects. Industry-specific inputs encompass copper pricing volatility indices and municipal electrical load amendment adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Zhejiang fabricators or accelerated FDA certification pursuit by new entrants would shift outcomes beyond modeled ranges. Quarterly review of REACH substance restriction candidate list updates and FCC Part 18 certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Indoor Humidifier Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Water Purifier Market
Household Items
Umbrella Market
Household Items
Underwear Disinfection Dryers Market
Household Items
South Africa Cookware Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Permanent Marker Market
Household Items
Toilet Hygiene Products Market
Household Items
Collapsible Water Bottle Market
Household Items
Electric Mop Market
Household Items
Microwave Safe Utensils Market
Household Items
Smart Air Purifier Market
Household Items
US Air Fresheners Market
Household Items
Towel Warmers Market
Household Items
Soap Tablet Market