
 Household Scales Market | 2026-2036
Household Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Household Scales Market Insights
The household scales category is pivoting on a widening split between premium connected devices and commodity weight-only units. Withings anchors the premium tier through medical-grade body composition sensors and FDA-cleared cardiovascular metrics. Etekcity competes at the mass-market level by leveraging direct-to-consumer channel control and aggressive platform pricing on Amazon.
Household scales are electromechanical instruments that measure body mass or composition using load cell or strain gauge transducers, converting mechanical deformation into electrical signals with typical resolutions of 0.1 kg or finer. Their primary commercial purpose spans personal health monitoring, clinical screening, and fitness tracking across consumer and light-medical settings. Smart scales with Bluetooth connectivity and BMI calculation represent the fastest-expanding segment, while mechanical and analog variants occupy a shrinking but residual base of price-sensitive rural markets. Digital scales using strain gauge technology sustain the largest installed base and margin pool due to manufacturing maturity and component availability.
FDA clearance requirements for scales claiming medical metrics shape product development timelines and limit market access for uncertified entrants. The EU's CE marking under the MDR and RoHS substance restrictions further constrain material choices and wireless emission standards. Stakeholders must monitor whether emerging biometrics such as segmental body fat analysis trigger reclassification into regulated medical devices.
Market Dynamics
The household scales market is splitting along a connectivity fault line, with Shenzhen's manufacturing cluster driving cost compression in basic digital units while FDA-cleared medical-grade sensors command premium positioning in North American and European channels.
Growth Catalysts
- EU Ecodesign Directive:Tightening energy-efficiency mandates for battery-powered electronics are accelerating replacement cycles of legacy mechanical scales across German and French retail channels.
- Body composition sensing:Bioelectrical impedance analysis sensors are penetrating mid-tier price bands as load cell manufacturing achieves greater economies in Chinese production hubs.
- Fitness tracking integration:Health-conscious consumers in South Korea and Australia are prioritizing Bluetooth-enabled scales that synchronize data with third-party wellness applications.
Market Restraints
- Strain gauge supply concentration:Precision load cell production clusters in Guangdong province create vulnerability to regional logistics disruptions and input material volatility.
- RoHS substance restrictions:European lead-free solder mandates constrain component sourcing for analog scale manufacturers with legacy supply relationships.
- Smartwatch substitution:Wrist-worn wearables with weight-estimation algorithms are capturing casual fitness tracking demand that previously flowed to standalone bathroom scales.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting contract assembly investment for export-oriented smart scale production.
- Telehealth reimbursement:Remote patient monitoring codes in US Medicare are creating institutional procurement channels for cellular-connected scales in chronic disease management.
- AI-driven coaching convergence:Machine learning algorithms analyzing longitudinal body composition data are opening subscription revenue models adjacent to hardware sales.
Industry Challenges
- FDA 510(k) timeline compression:Cardiovascular metric claims require clinical validation studies that extend product development cycles by 18-24 months versus consumer wellness positioning.
- Multi-protocol wireless integration:Fragmentation across Bluetooth, Wi-Fi, and proprietary low-power standards complicates firmware architecture and certification testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Scales Market |
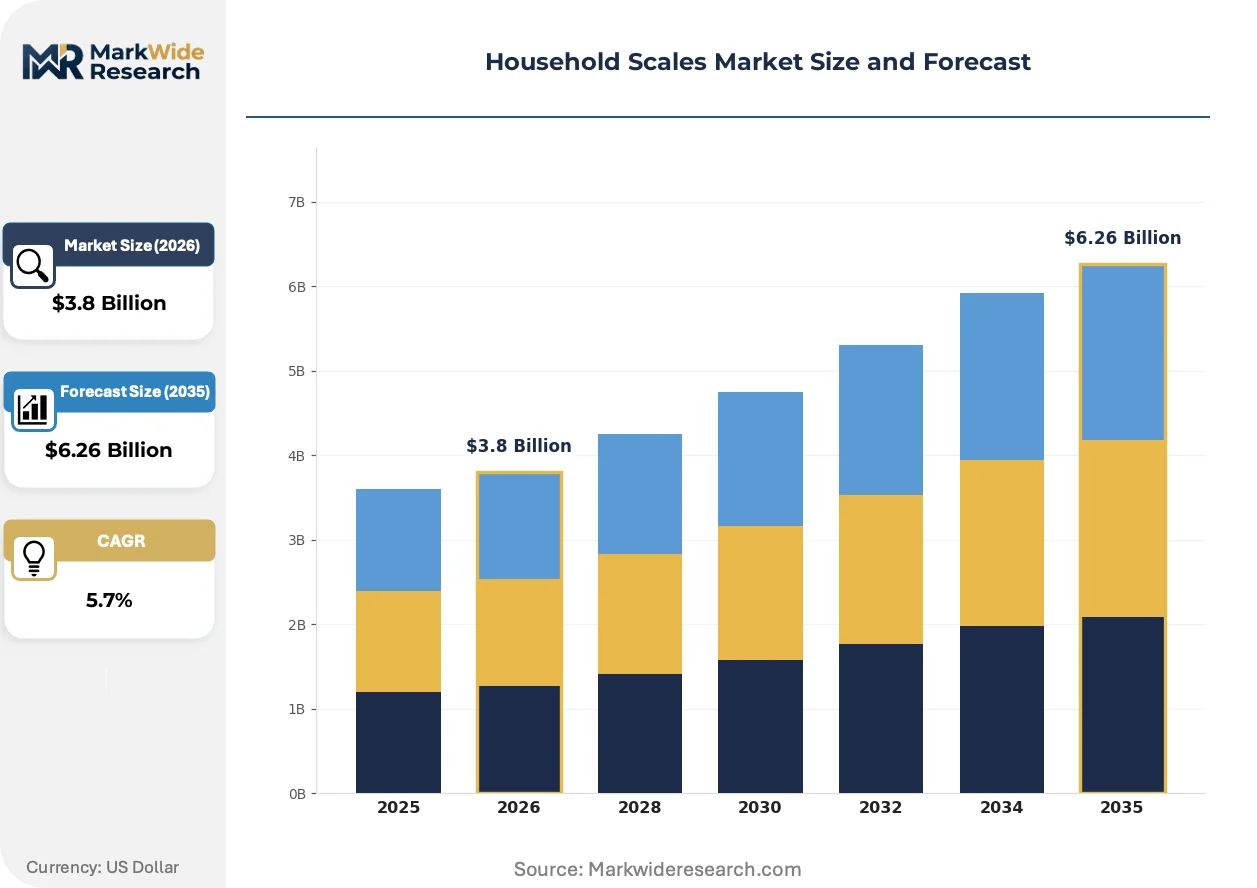
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Mechanical, Smart, Analog Technology: Load Cell, Strain Gauge, Piezoelectric, Capacitive Feature: BMI Calculator, Bluetooth Connectivity, Weight Tracking, Tare Function End User: Fitness Enthusiasts, Households, Medical Professionals, Nutritionists |
| Companies Covered | Guangdong Transtek Medical, Camry Scale, InBody, Anker Eufy, Omron Healthcare, Withings, Wyze, Renpho, Etekcity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Scales Market Trends and Innovations
Sensor miniaturization and cloud connectivity are dissolving the boundary between consumer wellness devices and clinical screening tools, with regulatory classification becoming the decisive market segmentation variable.
Bioelectrical impedance analysis is modularizing across price tiers as single-chip solutions from semiconductor suppliers reduce bill-of-materials complexity. Fitness chains and corporate wellness programs are adopting these streamlined body composition modules for member onboarding protocols. This architectural shift is compressing development timelines for mid-market entrants who previously lacked analog front-end design expertise.
MDR classification scrutiny in Europe is intensifying for scales advertising segmental fat analysis or metabolic health scores, with notified bodies requiring clinical evidence for algorithm-derived metrics. Manufacturers are responding by bifurcating product portfolios into regulated medical channels and unregulated consumer positioning. German and French distributors now demand CE technical documentation before listing connected scales with biometric claims.
Direct-to-consumer channel capture is reshaping go-to-market economics as Amazon's marketplace algorithms prioritize review velocity over traditional retail slotting fees. Chinese OEMs with Shenzhen logistics integration are bypassing regional distributors to serve price-sensitive segments in Brazil and Mexico. This disintermediation is most visible in Latin American e-commerce where local fulfillment infrastructure remains underdeveloped for bulky appliance categories.
Household Scales Market Segmentation
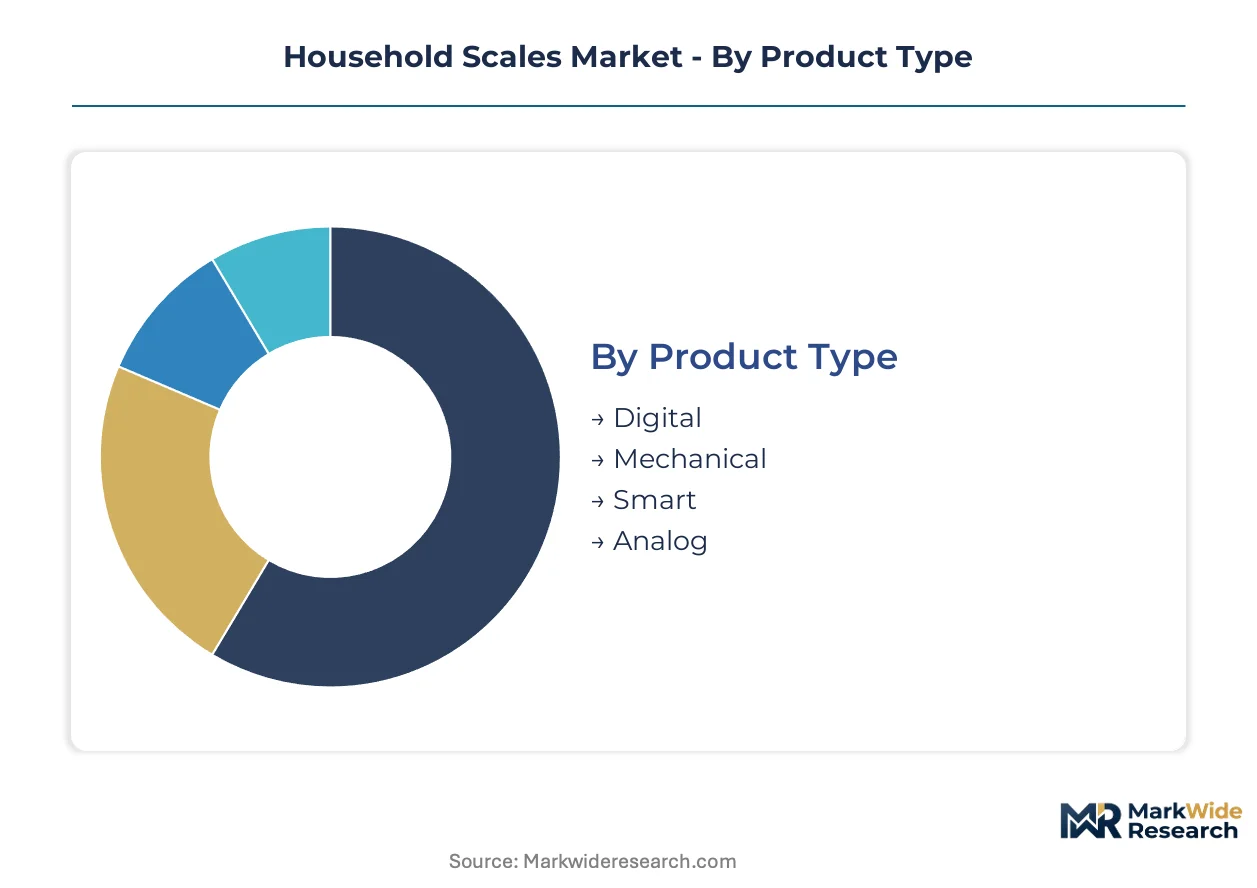
Household scales segment along four intersecting dimensions that determine margin structure, regulatory exposure, and channel economics. Product type and technology choices lock in manufacturing cost curves, while feature sets and end-user targeting dictate pricing power and replacement frequency.
Product Type:
Capital intensity varies sharply across product types, with smart scales requiring the heaviest upfront investment in firmware development, wireless certification, and cloud infrastructure.
- Digital:Strain gauge transducers paired with LCD displays dominate unit economics through mature Shenzhen supply chains. Households in Germany and France are replacing mechanical units ahead of EU Ecodesign Directive deadlines. Digital scales absorb the bulk of installed capacity; smart scales are expanding most quickly.
- Smart:Bluetooth-enabled devices with companion applications demand continuous software maintenance and API integration with third-party wellness platforms. Fitness enthusiasts in South Korea and Australia prioritize these for ecosystem synchronization.
- Mechanical:Spring-based platforms with rotating dial indicators retain residual demand in price-sensitive rural markets across India and Southeast Asia where electricity access remains unreliable.
- Analog:Passive mechanical designs without electronic components face shrinking distribution as RoHS compliance costs erode already-thin margins in European retail channels.
Smart scales command the highest bill-of-materials complexity; digital scales retain the largest manufacturing scale.
Technology:
Transducer selection determines resolution limits, calibration stability, and vulnerability to temperature drift in household environments.
- Load Cell:Bonded strain gauge configurations in aluminum or steel housings deliver 0.1 kg precision at scale. Guangdong province concentration creates supply vulnerability during regional logistics disruptions.
- Strain Gauge:Foil or semiconductor patterns deposited on elastic substrates remain the dominant sensing architecture across mid-tier and premium digital scales. Medical professionals in US clinical screening settings demand FDA-cleared implementations of this technology.
- Piezoelectric:Ceramic crystal elements generate charge under mechanical stress, enabling rapid response times in compact form factors for travel-scale applications.
- Capacitive:Electrode arrays measuring dielectric displacement offer alternative pathways for body composition estimation without direct electrical contact.
Strain gauge platforms anchor current production volumes; load cell integration is gaining share in connected device architectures.
Feature:
Feature bundling separates premium positioning from commodity competition, with software-enabled functions requiring ongoing development investment.
- BMI Calculator:Embedded algorithms converting mass and user-input height into body mass index readings. Nutritionists in Brazil and Mexico utilize these for client intake protocols in under-equipped clinical settings.
- Bluetooth Connectivity:Wireless data transmission to smartphones enables longitudinal tracking and third-party application integration. FCC certification requirements in the US and CE marking under EU radio equipment directives extend development timelines.
- Weight Tracking:On-device memory storing historical measurements without cloud dependency appeals to privacy-conscious consumers in Germany subject to GDPR scrutiny.
- Tare Function:Zero-offset capability for container weighing supports dual-use kitchen applications in Japanese households with space-constrained living environments.
Bluetooth connectivity drives the steepest feature adoption curve; tare functionality remains near-universal across price tiers.
End User:
End-user segmentation maps directly to regulatory classification risk and average selling price realization.
- Fitness Enthusiasts:Consumers prioritizing body composition trends over absolute mass measurement. Australia's corporate wellness programs are adopting segmental analysis scales for member onboarding despite TGA scrutiny of algorithm-derived metabolic claims.
- Households:General consumers seeking basic mass monitoring for personal health management. India's PLI scheme for electronics manufacturing is attracting contract assembly investment to serve this price-sensitive segment.
- Medical Professionals:Clinicians requiring FDA 510(k)-cleared devices for diagnostic or monitoring purposes. Medicare reimbursement codes for remote patient monitoring are opening institutional procurement channels in the US.
- Nutritionists:Dietary counselors tracking client progress through precise measurement protocols. French distributors now demand CE technical documentation under MDR before listing scales with biometric claims.
Households represent the broadest addressable base; medical professionals deliver the highest margin per unit despite certification overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors global smart scale manufacturing through its integrated electronics ecosystem, while demand concentrates in developed markets with aging populations and emerging economies with expanding fitness cultures. Regulatory divergence across major economies is fragmenting product specifications and certification pathways.
United States
Medicare reimbursement codes for remote patient monitoring are accelerating institutional procurement of cellular-connected scales in chronic disease management programs. FDA 510(k) clearance requirements for cardiovascular metric claims extend product development timelines for domestic and foreign manufacturers alike. Boston's health technology corridor hosts several firms specializing in clinical-grade body composition analytics for hospital networks.
Germany
The EU Ecodesign Directive is forcing replacement cycles of legacy mechanical scales ahead of tightening energy-efficiency mandates for battery-powered electronics. CE marking under the MDR now requires clinical evidence for algorithm-derived metabolic health scores before biometric claims receive distribution approval. Bavaria's precision engineering clusters supply load cell components to scale manufacturers across the continent.
China
Shenzhen's hardware ecosystem drives cost-competitive manufacturing of Bluetooth-enabled scales for export markets while domestic fitness enthusiasts adopt connected body composition analyzers faster than traditional weight-only devices. GB standards and MIIT wireless certification create parallel regulatory tracks distinct from FDA or CE pathways. Guangdong province concentration of strain gauge production creates vulnerability to regional logistics disruptions.
India
The PLI scheme for electronics manufacturing is attracting contract assembly investment for export-oriented smart scale production serving price-sensitive household segments. BIS certification requirements for imported electronic weighing devices are tightening quality thresholds for Chinese OEMs. Maharashtra's industrial corridors near Mumbai are emerging as preferred locations for electronics manufacturing services expansion.
Australia
Corporate wellness programs are adopting segmental analysis scales for member onboarding despite TGA scrutiny of algorithm-derived metabolic claims. Fitness enthusiasts prioritize Bluetooth-enabled devices that synchronize with third-party wellness applications. Sydney and Melbourne concentrate distribution infrastructure for Asia-Pacific market access.
Household Scales Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where medical-grade certification separates premium positioning from commodity competition. The vendor base splits between Shenzhen-integrated OEMs serving mass-market channels and specialized firms commanding clinical-grade price premiums. Three archetypes dominate: vertically integrated electronics conglomerates, precision sensor specialists, and direct-to-consumer platform natives. Competitive moves concentrate on M&A for FDA-cleared technology assets and strategic partnerships with telehealth platforms for institutional channel access.
Among Asia-Pacific fabricators, Guangdong Transtek Medical Co., Ltd. and Camry Scale occupy positions within the OEM supply tier, while Withings SA exemplifies the premium archetype through its medical-grade positioning in European and North American regulated channels.
| Leading Market Players |
|---|
| Guangdong Transtek Medical |
| Camry Scale |
| InBody |
| Anker Eufy |
| Omron Healthcare |
| Withings |
| Wyze |
| Renpho |
| Etekcity |
| Others |
Pricing and Supply Chain Analysis
Medicare reimbursement codes for remote patient monitoring in the United States are pulling cellular-connected scales into institutional procurement channels, forcing contract manufacturers in Shenzhen to qualify medical-grade production lines and compressing margins on consumer-tier units.
Pricing Analysis
FDA 510(k) clearance serves as the value-based pricing anchor in North American channels, with certified cardiovascular metric claims commanding substantial premiums over wellness-positioned alternatives. Three-tier pricing structure across medical-grade, connected-consumer, and basic-digital levels separates reimbursement-eligible devices from Bluetooth-enabled fitness trackers and commodity strain-gauge units. Pricing pressure stems from Amazon's algorithm-driven review velocity competition, which rewards aggressive platform discounting over brand equity. Household buyers in India and Southeast Asia exhibit the highest price sensitivity, while US hospital procurement committees prioritize clinical validation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German and French distributors now mandate CE technical documentation from at least two qualified strain-gauge suppliers, pressuring OEMs to diversify beyond Guangdong province. Manufacturing concentrates in China, Vietnam, and India, with Shenzhen anchoring firmware development and Ho Chi Minh City absorbing basic digital assembly. Aluminum load cell housings, Bluetooth SoC modules, and RoHS-compliant solder formulations constitute critical input dependencies. Single-source vulnerability concentrates in Guangdong's precision load cell foundries, where regional logistics disruptions ripple through global production schedules. Distribution runs through direct-to-consumer platforms and telehealth procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household scales market functions as a cost-of-compliance story where the EU's MDR classification scrutiny for algorithm-derived metabolic claims erects a barrier-to-entry moat that rewards early certification investment and punishes late entrants with extended validation timelines.
For Market Incumbents: Hedge against smartwatch substitution by deepening integration with third-party wellness platforms and securing FDA-cleared cardiovascular metric claims before algorithm-derived features trigger reclassification. Withings and Omron Healthcare have demonstrated that medical-grade positioning insulates premium pricing from Amazon's review-velocity competition. Capacity addition in India's PLI-subsidized electronics corridors offers cost-competitive export sourcing without Shenzhen's logistics concentration risk. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for contract assembly investment serving price-sensitive household segments in Brazil and Mexico where local fulfillment infrastructure remains underdeveloped. Telehealth reimbursement codes in the United States create the most penetrable institutional channel for cellular-connected scales in chronic disease management. A direct-to-consumer launch via Amazon's marketplace, bypassing regional distributor margin stacking, offers the clearest go-to-market angle for capital-constrained entrants. For Investors and Strategic Acquirers: The window for entry favors precision sensor specialists with existing FDA-cleared technology assets and firmware development capabilities. Long-term viability hinges on the convergence of consumer wellness and clinical screening categories, where regulatory classification becomes the decisive segmentation variable. The signal to watch is TGA scrutiny of segmental fat analysis claims in Australia, which presages broader MDR enforcement patterns across European notified bodies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Clinical validation studies extend development timelines but unlock Medicare reimbursement codes and hospital procurement channels. |
| CE Marking Under MDR | Notified bodies in Germany and France now demand clinical evidence for algorithm-derived metabolic health scores before distribution approval. |
| Telehealth Platform Partnership | Integration with chronic disease management programs creates institutional demand pull for cellular-connected remote patient monitoring scales. |
| Backward Integration into Load Cells | Captive supply of strain-gauge transducers insulates against Guangdong logistics disruptions and input material volatility. |
| Direct-to-Consumer Channel Capture | Amazon's algorithmic prioritization of review velocity rewards platform-native entrants over traditional retail-dependent incumbents. |
Research Methodology
Independent corroboration across FDA 510(k) filings, CE technical documentation databases, and Medicare reimbursement code records underwrites the qualitative findings in this study. Primary interviews with biomedical engineers at hospital purchasing committees, regulatory affairs leads at connected device manufacturers, and category buyers at German retail distributors were synthesized with secondary validation from customs records, GPO contracts, and MIIT wireless certification registries. Bottom-up triangulation across product-type segmentation and top-down cross-checks against regional demand aggregation ensured analytical consistency.
Rate-of-change decomposition across the analysis window isolates volume growth from price realization effects in smart versus digital versus mechanical product tiers. The modeling framework incorporates technology adoption curves, regulatory approval timelines, and channel shift dynamics across connectivity-enabled and traditional scale architectures. Segmentation dimensions include product type, transducer technology, feature bundling, and end-user classification spanning fitness enthusiasts, households, medical professionals, and nutritionists. CAGRs were derived from fitted adoption curves rather than linear extrapolation, with industry-specific inputs including Shenzhen manufacturing capacity utilization and RoHS compliance cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for bioelectrical impedance analysis miniaturization would alter the outlook for mid-tier body composition penetration. Forecasts reflect assumptions regarding MDR enforcement intensity, PLI scheme continuation in India, and Amazon marketplace algorithm stability. Deviation in FDA cardiovascular metric claim scrutiny would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Washing Machine Cleaner Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Commercial Lawnmower Market
Household Items
North America B2B Air Care Market
Household Items
Tablet Tissue Paper Market
Household Items
Brazil Cookware Market
Household Items
Hand Wash Station Market
Household Items
Kitchen Towel Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Scouring Pads Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Jet Hand Dryer Market
Household Items
Shoe Dryer Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Toilet Hygiene Products Market
Household Items
Thermos Bottle Market