
 South America Ready-To-Drink (RTD) Coffee Market | 2026-2036
South America Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ready-To-Drink (RTD) Coffee Market Analytics
Sourcing strategy among South American RTD coffee producers is shifting from single-source coffee bean procurement toward diversified multi-origin blends that mitigate climate risk. Nestlé leverages its vertically integrated supply chain across Brazilian Minas Gerais estates to secure arabica volumes. The Coca-Cola Company anchors its regional position through licensed production partnerships with local bottlers. PepsiCo competes via price-accessible formats targeting mass-market convenience channels.
Ready-to-drink coffee comprises brewed coffee extracts preserved through thermal processing or cold filtration, typically formulated with milk solids, sweeteners, and stabilizers to achieve shelf stability from four to twelve months. Its primary commercial purpose is to deliver café-equivalent caffeine delivery in ambient, chilled, or on-the-go consumption contexts without equipment dependency. Non-carbonated variants lead volume share given their alignment with traditional coffee consumption patterns, while cold brew segments command premium shelf positioning due to extended steeping protocols and smoother acidity profiles. Cans dominate packaging type selection for their recyclability and logistics efficiency across Andean distribution networks.
ANVISA governs food additive thresholds and caffeine disclosure requirements for Brazilian RTD coffee formulations, while Argentina's national food code enforces parallel labeling standards that shape cross-border product standardization. Peru's health ministry applies distinct pasteurization benchmarks that influence manufacturing line configurations for exporters serving multiple Andean markets. Stakeholders must monitor evolving front-of-pack warning label expansions and sugar taxation proposals that could reformulate portfolio architectures across Mercosur jurisdictions.
Market Dynamics
ANVISA's updated front-of-pack warning label mandates are forcing reformulation across Brazilian RTD coffee portfolios, compressing margins for sugar-dependent variants while accelerating clean-label R&D investment.
Growth Catalysts
- Cold Brew Processing:Extended steeping protocols at ambient temperature extract smoother flavor compounds without thermal degradation, attracting premium positioning in São Paulo and Bogotá convenience channels.
- ANVISA Nutritional Transparency:Brazil's clearer disclosure requirements on caffeine content and added sugars build consumer trust and reduce information asymmetry in retail purchase decisions.
- Andean Urbanization:Metropolitan corridor expansion along the Río de la Plata concentrates young professional populations with high mobility needs and limited home brewing capacity.
Market Restraints
- Arabica Price Volatility:Climate-induced harvest variability in Minas Gerais and Cerrado regions transmits directly to input cost structures for single-origin dependent producers.
- Cross-Border Regulatory Friction:Peru's distinct pasteurization benchmarks force manufacturing line reconfiguration for exporters serving multiple Andean markets, elevating compliance overhead.
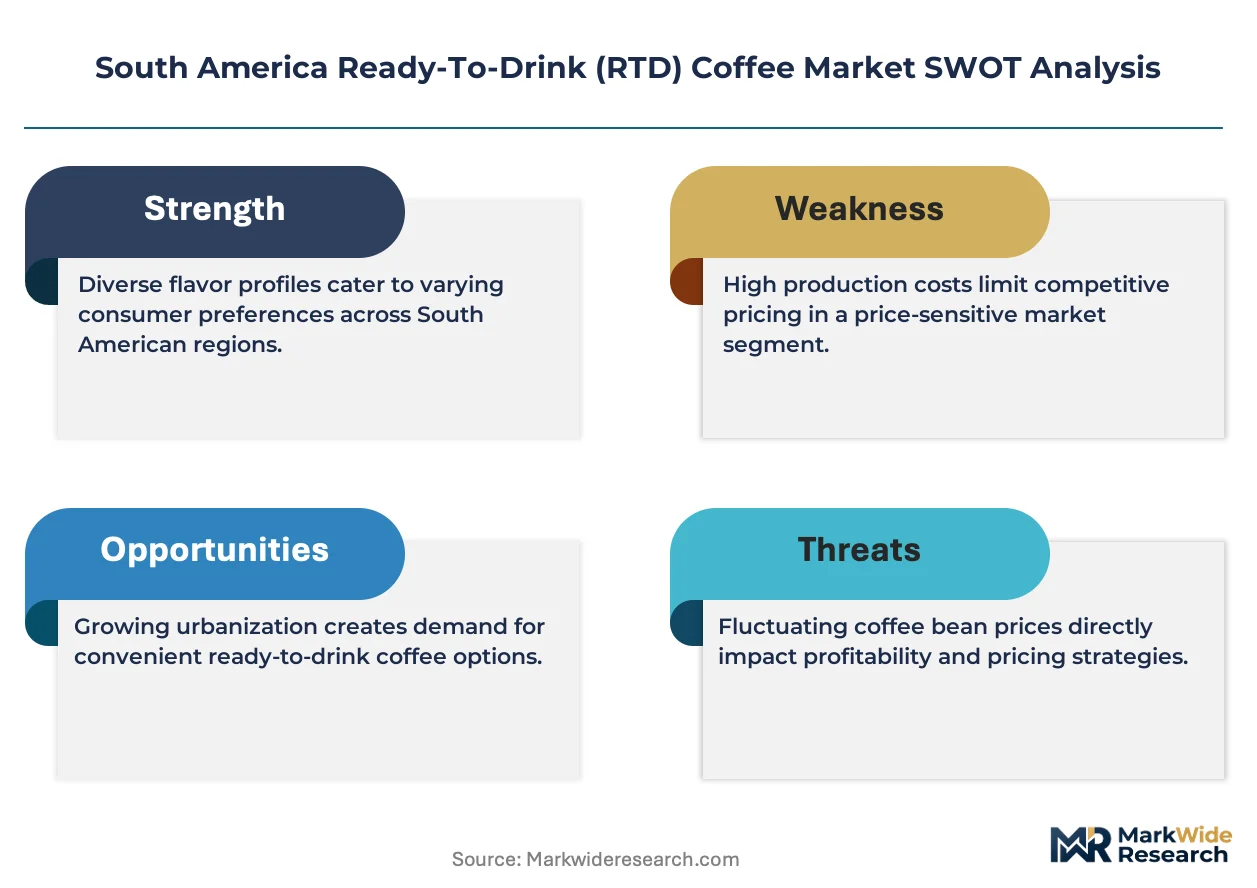
- Fresh Coffee Substitution:Third-wave café proliferation in Buenos Aires and Santiago offers experiential consumption that RTD formats cannot replicate, capping premium pricing elasticity.
Strategic Opportunities
- Ecuador Channel Penetration:Underdeveloped modern trade infrastructure in Quito and Guayaquil creates first-mover advantage for brands establishing direct-store-delivery networks ahead of competitor saturation.
- Carbonated RTD Innovation:Nitrogen-infused and sparkling coffee variants align with younger cohort refreshment preferences, opening occasions beyond traditional morning consumption.
- Mercosur Sugar Tax Alignment:Anticipated harmonization of sweetened beverage taxation across member states rewards early reformulators with portfolio-ready compliance.
Industry Challenges
- Thermal Process Engineering Talent:Scarce expertise in aseptic cold-fill bottling across South American technical institutes constrains capacity expansion timelines for emerging producers.
- Legacy Distributor Integration:Traditional beverage wholesalers lack cold-chain competency for chilled RTD variants, requiring parallel infrastructure investment or channel bypass strategies.
- Extended Shelf-Life Certification:ANVISA stability testing protocols demand 12-month validation cycles that delay product launches and compress innovation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ready-To-Drink (RTD) Coffee Market |
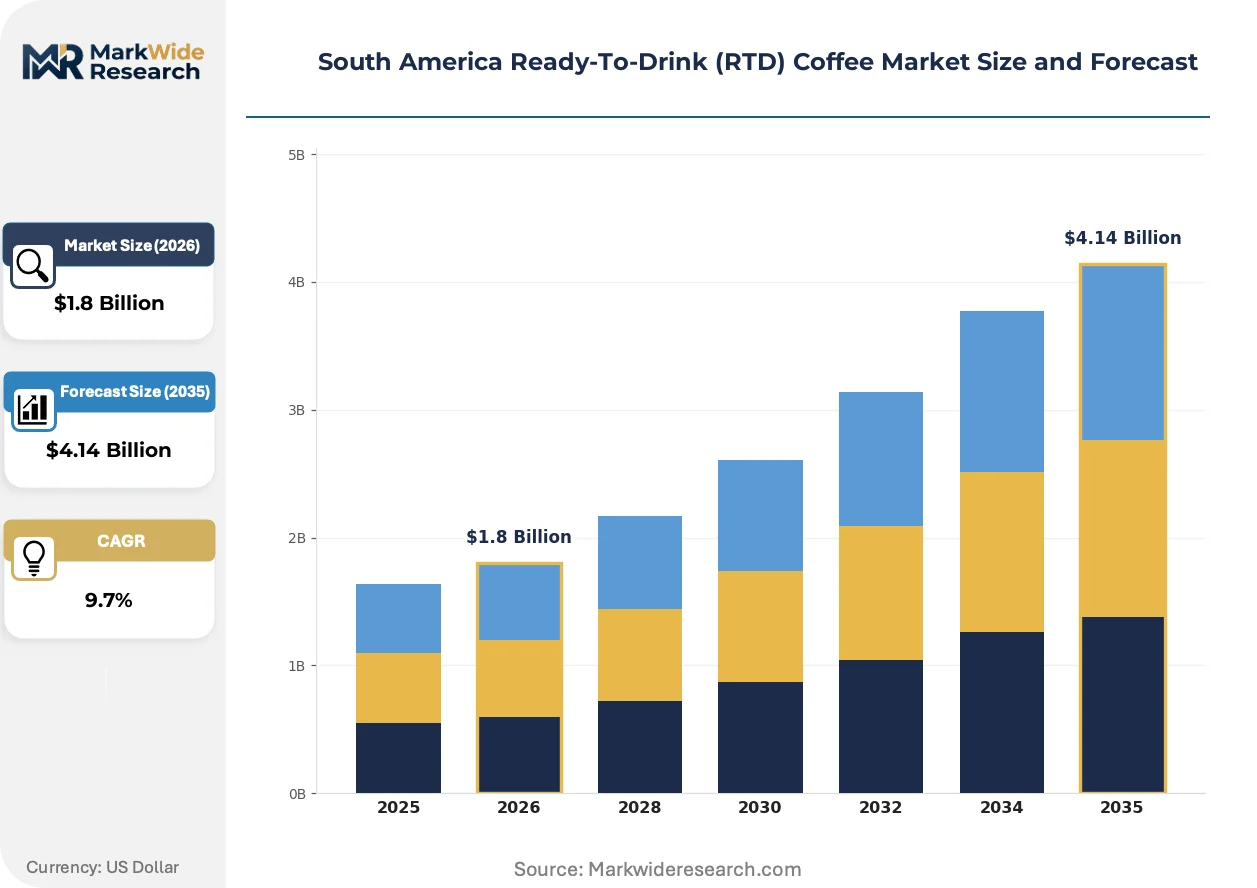
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Cold Brew, Espresso Flavor Profile: Vanilla, Mocha, Hazelnut, Original Packaging Type: Cans, Bottles, Tetra Paks, Pouches Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Cafes |
| Companies Covered | Nestlé, The Coca-Cola Company, PepsiCo, Starbucks Corporation, Jacobs Douwe Egberts, Lavazza, Illycaffè, Alpina Productos Alimenticios, Café do Brasil, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ready-To-Drink (RTD) Coffee Market Evolving Landscape
Processing automation and regulatory disclosure requirements are compressing product development cycles while reshaping competitive differentiation from formulation secrecy toward supply chain transparency and origin storytelling.
High-pressure processing technology is automating cold pasteurization for RTD coffee without thermal degradation, preserving volatile aromatic compounds. Brazilian co-manufacturers in São Paulo state are adopting HPP lines at accelerating pace to serve private-label demand. This automation is compressing the traditional 18-month stability validation window into 8-month commercialization cycles.
ANVISA's front-of-pack warning label expansion mandates octagonal sugar and caffeine alerts that occupy 20% of primary display panels. Industrial consequence includes accelerated reformulation toward zero-sugar stevia and monk fruit blends. Premium cold brew segments are responding fastest, leveraging naturally lower bitterness to reduce sweetener dependency without consumer rejection.
Subscription direct-to-home models are displacing traditional wholesale-dependent distribution for specialty RTD variants in metropolitan Brazil. Young professionals in Pinheiros and Vila Madalena neighborhoods are consolidating weekly coffee procurement into curated delivery boxes. This shift is most visible in São Paulo's zona sul districts where convenience store penetration remains below national averages.
South America Ready-To-Drink (RTD) Coffee Market Segmentation
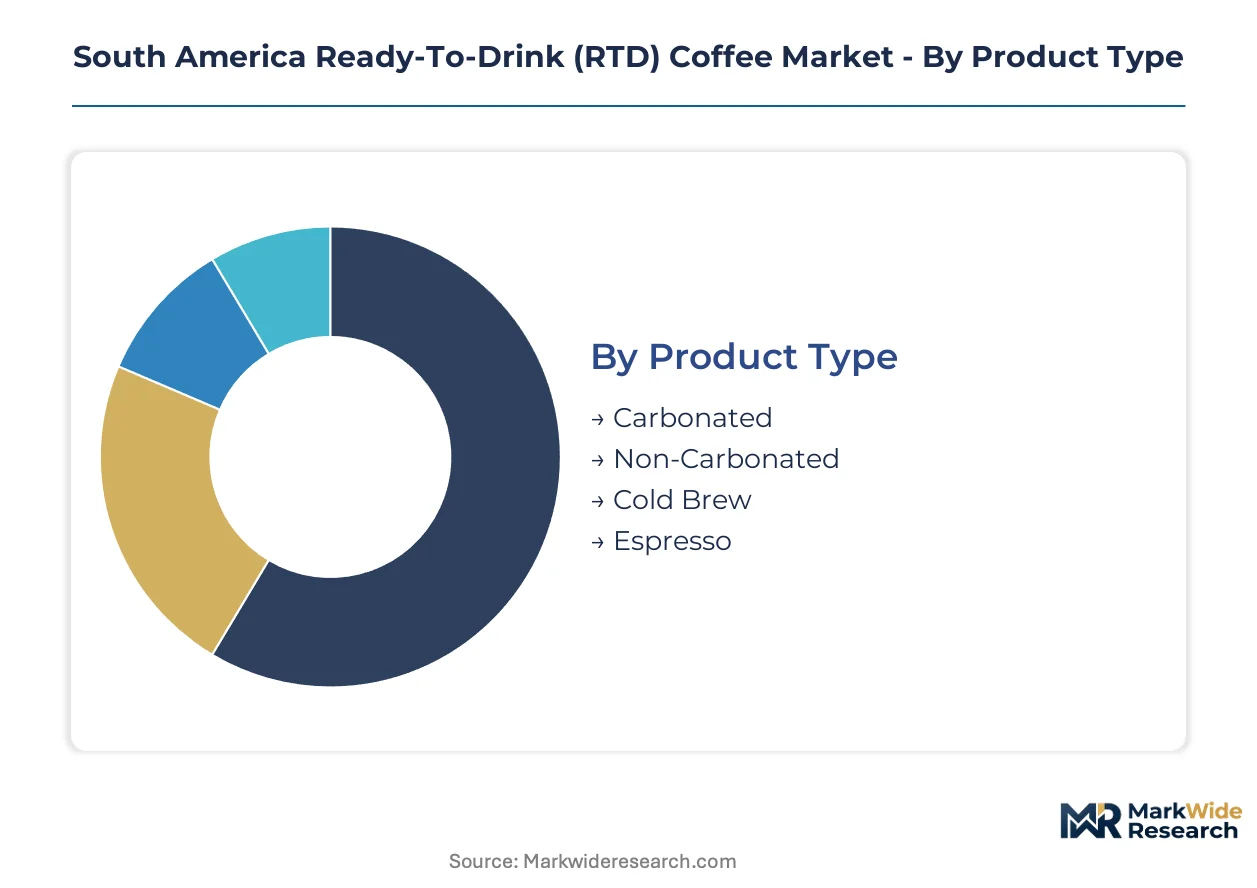
RTD coffee segmentation in South America reflects divergent capital requirements across processing technologies and channel infrastructures. Cold-fill aseptic lines demand higher upfront investment than hot-fill alternatives, while direct-store-delivery networks require distinct logistics capital versus traditional wholesale models.
Product Type:
Capital intensity varies sharply across processing protocols, with cold brew steeping infrastructure and nitrogen-infusion systems commanding premium equipment outlays compared to conventional thermal processing.
- Cold Brew:Extended ambient steeping at 12-24 hours extracts smoother phenolic compounds without thermal degradation. São Paulo's zona sul districts and Bogotá's Chapinero corridor concentrate demand among young professionals seeking café-equivalent quality without equipment dependency.
- Non-Carbonated:Traditional brewed coffee extracts stabilized through thermal processing or aseptic cold-fill, formulated with milk solids and sweeteners for four-to-twelve month shelf stability. Brazil's interior states and Argentina's Pampas region drive volume through convenience store channels where chilled distribution infrastructure remains limited.
- Carbonated:Nitrogen-infused variants requiring pressurized filling lines and specialized can handling equipment.
- Espresso:Concentrated coffee extracts standardized for consistent caffeine delivery across ambient distribution.
Most installed capacity flows through Non-Carbonated. Expansion is steepest in Cold Brew.
Flavor Profile:
Reformulation costs and clean-label R&D investments cluster around sugar-reduced variants as ANVISA warning label mandates reshape portfolio economics.
- Original:Unflavored coffee bases with minimal additive profiles, leveraging naturally lower bitterness in cold brew processing to reduce sweetener dependency. São Paulo's Pinheiros and Vila Madalena neighborhoods show concentrated subscription-model adoption for unsweetened variants.
- Vanilla:Natural and synthetic vanillin formulations requiring flavor stability testing across extended shelf-life protocols.
- Mocha:Cocoa-coffee blends with higher ingredient complexity and supply chain coordination requirements.
- Hazelnut:Nut-derived flavor systems facing allergen labeling requirements under Mercosur harmonization discussions.
Original commands the broadest production runs. Mocha carries the highest input cost volatility.
Packaging Type:
Equipment amortization timelines diverge substantially, with aluminum can lines achieving faster payback than aseptic carton systems given South America's recycling infrastructure concentration.
- Cans:Aluminum containers dominating Andean distribution networks for recyclability and logistics efficiency, with standard diameters optimizing palletization across Brazilian and Argentine trucking corridors. Cold-chain requirements are lower than chilled bottle alternatives.
- Bottles:PET and glass variants requiring chilled distribution infrastructure with higher capital intensity.
- Tetra Paks:Aseptic carton systems with extended shelf-life capabilities but specialized filling equipment requirements.
- Pouches:Flexible formats targeting on-the-go consumption with lower per-unit material costs.
Cans absorb the majority of capital deployment. Pouches are gaining share fastest in metropolitan convenience channels.
Distribution Channel:
Route-to-market investments separate capital-heavy direct-store-delivery systems from lower-touch wholesale-dependent models, with cold-chain requirements adding further infrastructure layers.
- Convenience Stores:Ambient and chilled RTD placement in São Paulo and Bogotá urban corridors, where young professional mobility needs concentrate purchase frequency. Direct-store-delivery networks require dedicated salesforce and refrigerated vehicle investment.
- Supermarkets:Modern trade shelf space commanding slotting fees and promotional investment, with centralized distribution reducing per-outlet logistics complexity.
- Online Retailers:E-commerce platforms and subscription direct-to-home models displacing traditional wholesale in specialty segments.
- Cafes:Foodservice placement requiring distinct cold-chain protocols and relationship-based account management.
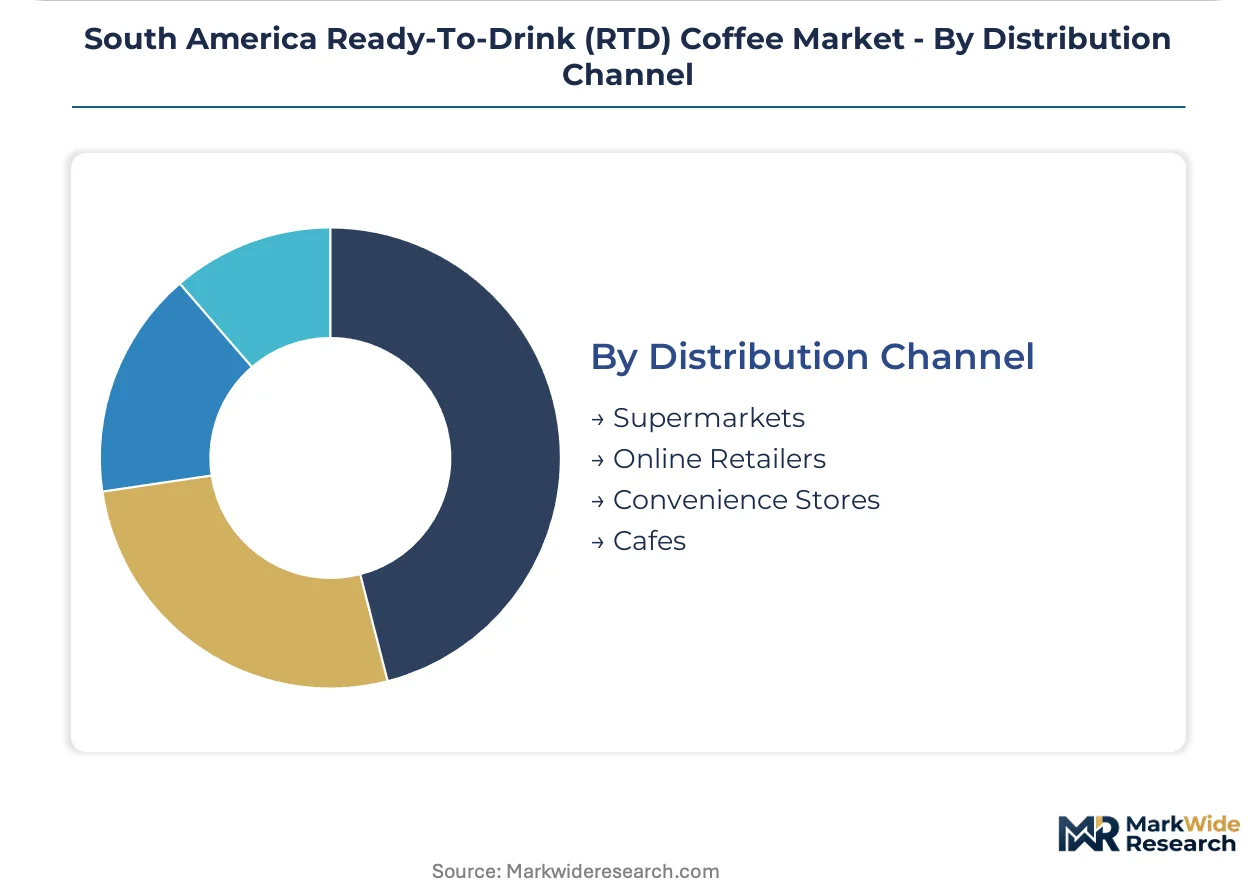
Supermarkets anchor current volume throughput. Online Retailers are climbing the fastest in São Paulo's zona sul districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minas Gerais coffee estates anchor arabica sourcing for South American RTD producers, with São Paulo's industrial corridor concentrating formulation and packaging capacity. Brazilian ANVISA regulations cascade across Mercosur, forcing cross-border standardization. Argentine and Colombian markets develop distinct cold-chain requirements.
Brazil
Young professionals in São Paulo's Pinheiros and Vila Madalena districts drive subscription-model adoption for unsweetened cold brew variants. ANVISA's front-of-pack warning label mandates occupy twenty percent of primary display panels, accelerating stevia reformulation. Minas Gerais estates supply arabica volumes to vertically integrated producers operating across São Paulo state.
Argentina
Buenos Aires third-wave café proliferation creates experiential substitution pressure on premium RTD positioning. The national food code enforces parallel labeling standards to Brazilian ANVISA requirements, enabling cross-border product standardization. The Río de la Plata corridor concentrates young professional populations with high mobility needs.
Colombia
Bogotá's Chapinero corridor channels demand for cold brew variants through convenience store networks. The national health ministry applies distinct pasteurization benchmarks influencing manufacturing configurations for exporters. Antioquia coffee regions supply differentiated origin stories for premium portfolio positioning.
Chile
Santiago metropolitan expansion concentrates demand for ambient-stable non-carbonated formats where chilled infrastructure remains limited. Mercosur sugar tax harmonization discussions shape reformulation timelines for cross-border portfolios. Valparaíso logistics hubs facilitate Andean distribution network efficiency.
Peru
Lima's emerging modern trade channels present first-mover opportunities for direct-store-delivery network establishment. Distinct pasteurization benchmarks from the health ministry force manufacturing line reconfiguration for multi-Andean exporters. Cusco and Cajamarca coffee regions develop specialty arabica sourcing relationships.
South America Ready-To-Drink (RTD) Coffee Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and subscription-model differentiation. Market structure consolidates around multinational beverage conglomerates with licensed production partnerships, while regional specialists anchor premium positioning through origin storytelling. Three archetypes dominate: vertically integrated agricultural conglomerates, licensed bottling networks, and specialty subscription direct-to-home operators. Competitive moves concentrate on reformulation R&D for ANVISA compliance and cold-chain infrastructure partnerships.
Among Swiss-based agricultural conglomerates, Nestlé exemplifies vertical supply chain control through Brazilian estate ownership. The Coca-Cola Company and PepsiCo represent licensed production archetypes leveraging regional bottler relationships for mass-market penetration. These three anchors illustrate divergent strategic postures: captive sourcing versus partnership-dependent scale versus price-accessible convenience channel dominance.
| Leading Market Players |
|---|
| Nestlé |
| The Coca-Cola Company |
| PepsiCo |
| Starbucks Corporation |
| Jacobs Douwe Egberts |
| Lavazza |
| Illycaffè |
| Alpina Productos Alimenticios |
| Café do Brasil |
| Others |
Value Network & Pricing Analysis
Young urban professionals in São Paulo and Bogotá concentrate purchasing power for premium cold brew variants, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects channel positioning and formulation complexity. This buyer archetype's willingness to pay for convenience and quality credentials shapes margin allocation across the value chain, with subscription direct-to-home models capturing recurring revenue premiums above traditional wholesale-dependent distribution.
Pricing Analysis
Arabica price volatility in Minas Gerais and Cerrado regions transmits directly to input cost structures, forcing producers to absorb margin compression or pass through via reformulation toward stevia and monk fruit blends. Price differentiation rests on clean-label certification status and cold-chain delivery capability, with ANVISA-compliant variants commanding shelf-space premiums. Pricing pressure stems from sugar taxation proposals across Mercosur jurisdictions, compressing margins for legacy sweetened portfolios. Mass-market convenience channels exhibit highest price sensitivity, while subscription-model subscribers in Pinheiros and Vila Madalena tolerate premium positioning for origin-storied variants.
Supply Chain Analysis
Dual-sourcing requirements from major buyers mandate multi-origin coffee bean qualification, with producers diversifying beyond single-source Minas Gerais estates toward Antioquia and Cajamarca regions to mitigate climate-induced harvest variability. Raw material dependencies center on arabica volumes, aseptic packaging substrates, and natural sweetener alternatives. Supply chain risk concentrates in single-source vulnerability for vertically integrated players with captive estate exposure. Distribution runs through licensed bottling partnerships for mass-market reach, parallel direct-store-delivery networks for chilled variants, and emerging e-commerce platforms for specialty subscription segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America RTD coffee market compounds steadily through urbanization-driven convenience demand, with metropolitan corridor expansion along the Río de la Plata sustaining per-capita consumption growth regardless of macroeconomic cycles.
For Market Incumbents: Anticipate ANVISA warning label expansion by accelerating zero-sugar reformulation R&D and securing stevia supply contracts ahead of competitor qualification. Defend shelf position through cold-chain infrastructure partnerships with convenience store networks in São Paulo's zona sul districts, where subscription-model displacement threatens traditional wholesale volumes. Prioritize backward integration into aseptic cold-fill bottling capacity to reduce co-manufacturer dependency as HPP automation compresses commercialization cycles. For New Entrants and Emerging Players: The price-point gap between premium cold brew and economy hot-fill variants creates white-space opportunity for mid-tier clean-label positioning. Target Ecuador's underdeveloped modern trade infrastructure in Quito and Guayaquil through direct-store-delivery network establishment ahead of competitor saturation. Pursue carbonated RTD innovation—nitrogen-infused and sparkling variants—to capture refreshment occasions beyond traditional morning consumption, leveraging younger cohort preferences in Bogotá's Chapinero corridor. For Investors and Strategic Acquirers: Beverage conglomerates with licensed production capabilities are the most active acquirer in this space, seeking regional bottling assets to anchor Mercosur distribution scale. Long-term viability favors targets with ANVISA-compliant portfolios and established cold-chain partnerships, given regulatory harmonization trajectories. Watch for sugar tax legislation progression across member states as the critical inflection signal—early reformulators with portfolio-ready compliance will command acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Sugar Reformulation Program | ANVISA warning label compliance protects shelf access across Brazilian retail networks. |
| Cold-Chain Infrastructure Partnership | Direct-store-delivery networks in São Paulo's zona sul districts displace wholesale-dependent competitors. |
| Multi-Origin Sourcing Diversification | Antioquia and Cajamarca volumes mitigate climate risk exposure in Minas Gerais estates. |
| HPP Line Investment | São Paulo state co-manufacturers compress stability validation from eighteen to eight months. |
| Subscription Platform Launch | Curated delivery boxes capture recurring revenue from Pinheiros and Vila Madalena professionals. |
Research Methodology
Multiple input streams—primary interviews with RTD coffee brand managers and category buyers at Brazilian retailers, supply chain planners at licensed bottlers, and regulatory affairs specialists tracking ANVISA developments—were reconciled against secondary validation from customs records, Nielsen retail audit data, and Mercosur trade flow databases. Bottom-up volume modeling across processing technology tiers and top-down macroeconomic anchoring ensured triangulation integrity.
Historical consumption patterns were cross-referenced against panel input from industry participants to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from trend extrapolation adjusted for ANVISA implementation timelines and urbanization projections, incorporating arabica price volatility assumptions and cold-chain infrastructure buildout rates as key forecast inputs.
Caveats apply where ANVISA warning label enforcement intensity or Mercosur sugar tax harmonization timing could materially shift the outlook. Deviation in arabica harvest yields across Minas Gerais and Cerrado regions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Drip Coffee Machine Market
Coffee
Coffee and Tea Capsule Market
Coffee
Coffee Grinder Market
Coffee
Ground Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
High Protein Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Butter Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Europe Coffee Market
Coffee
Encapsulated Caffeine Market
Coffee
Portable Espresso Machines Market
Coffee
Decaffeinated Coffee Market
Coffee
Tea and Coffee Bags Market
Coffee
China Ready-To-Drink (RTD) Coffee Market