
 US Securities Brokerage Market | 2026-2036
US Securities Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
US Securities Brokerage Market Outlook
Retail investor engagement through digital channels is broadening the addressable base for brokerage services. Charles Schwab leverages its branch-integrated digital platform to capture self-directed investors migrating from traditional advisory relationships. Fidelity Investments sustains dominance in workplace retirement plan rollovers, anchoring a sticky source of downstream brokerage assets. Robinhood Markets competes aggressively on user experience, occupying the mobile-native segment with streamlined options and cryptocurrency access.
US securities brokerage encompasses the execution, clearing, and custody of equity, fixed-income, and derivative transactions on behalf of retail and institutional clients, operating through proprietary trading platforms linked to exchanges and alternative trading systems. The sector functions as a critical intermediary layer in capital formation, earning revenue through commissions, net interest on client balances, payment for order flow, and asset management fees. Full-service brokerage retains premium pricing power among high-net-worth individuals seeking holistic wealth management, while robo-advisory segments expand fastest among millennials prioritizing low-cost automated allocation. Discount brokerage and no-commission structures have commoditized equity execution, compressing spreads and shifting margin pools toward ancillary services including margin lending and cash sweep programs.
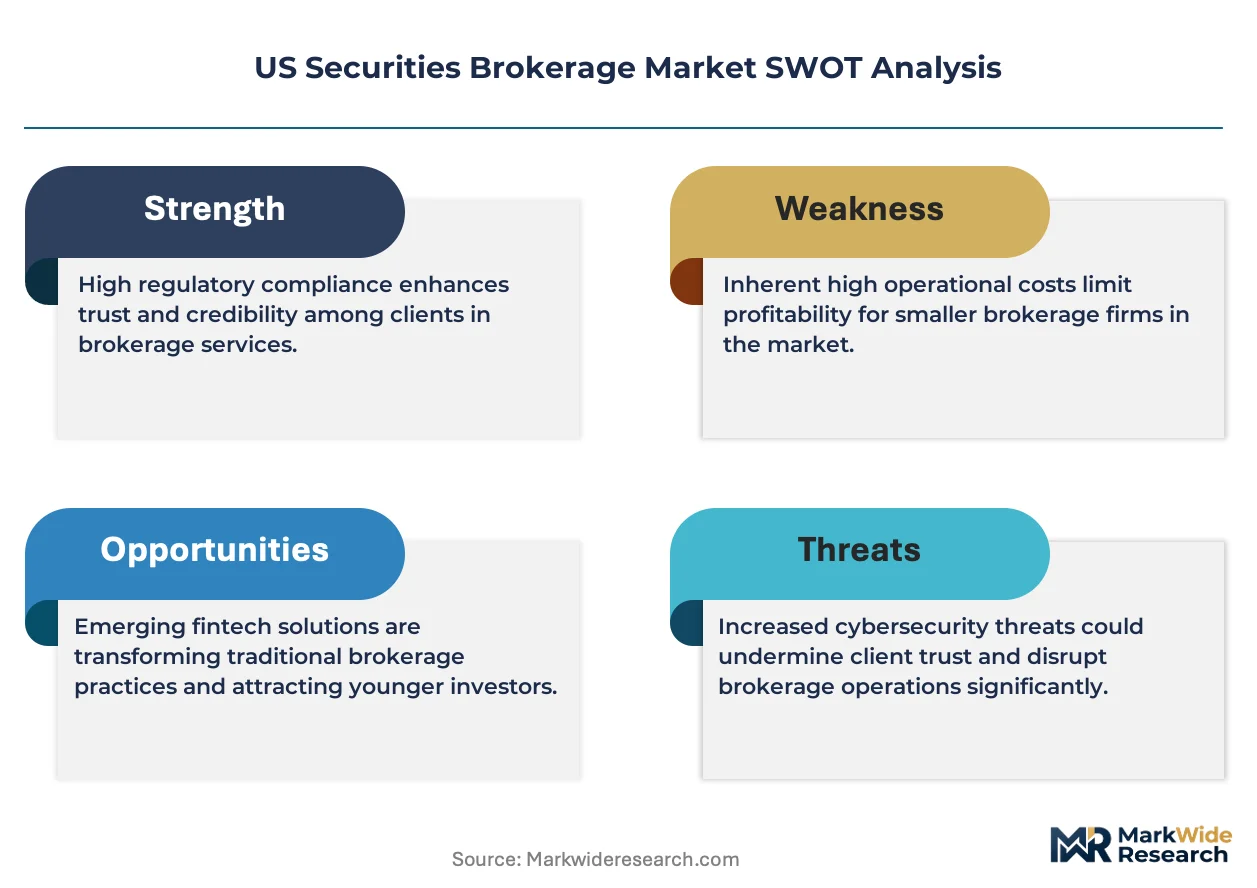
The SEC enforces Regulation Best Interest and Form CRS disclosure requirements, elevating compliance costs while restricting revenue from conflicted product recommendations. FINRA supervises broker-dealer conduct through examination and enforcement programs, shaping firm architecture around supervisory technology and registered representative training. State regulators in New York and California supplement federal standards with additional licensing and consumer protection mandates. Stakeholders must monitor evolving SEC proposals on predictive data analytics and gamification as these rulemakings threaten to constrain engagement tactics that currently drive account growth and trading velocity.
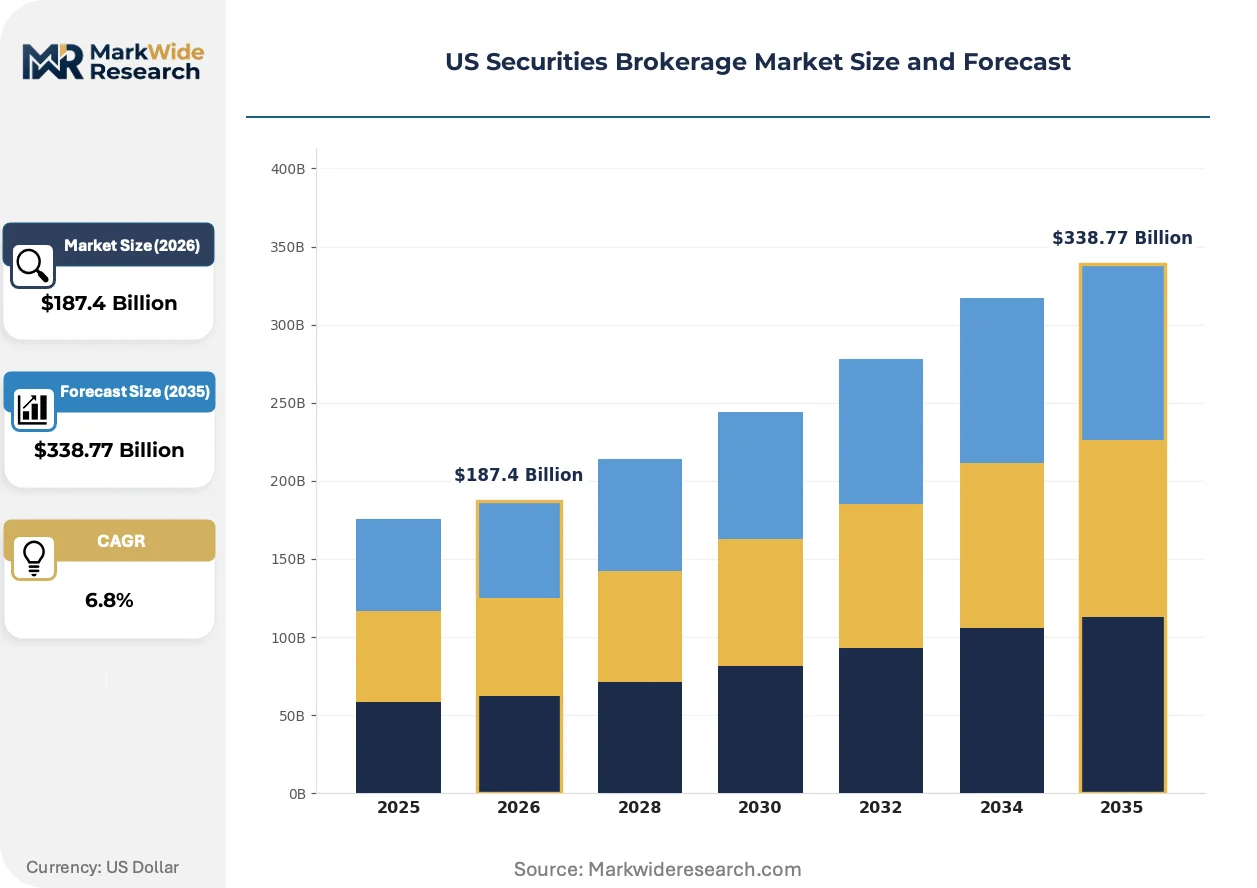
Market Dynamics
The US securities brokerage sector is undergoing structural compression as zero-commission trading commoditizes execution revenue and forces firms to monetize through ancillary services. SEC disclosure mandates and FINRA supervisory technology requirements are elevating fixed compliance costs while narrowing permissible revenue streams from conflicted recommendations.
Growth Catalysts
- Workplace retirement plan rollovers:Aging demographics are unlocking trillions in defined-contribution assets seeking self-directed brokerage accounts upon job changes or retirement.
- SEC Regulation Best Interest:The standard's implementation is accelerating consolidation among independent broker-dealers unable to absorb elevated compliance infrastructure costs.
- Texas and Florida migration:High-net-worth household relocation from California and New York to low-tax Sun Belt states is concentrating addressable wealth in branch-light markets.
Market Restraints
- Net interest margin compression:Federal Reserve rate volatility is eroding the spread income that replaced commission revenue at zero-commission platforms.
- Payment for order flow scrutiny:SEC proposals targeting this practice threaten a primary revenue model supporting no-commission retail trading.
- Clearing and custody concentration:Dependence on a limited set of bank-owned clearing firms creates systemic operational risk across the intermediary layer.
Strategic Opportunities
- RIA custody services:The breakaway broker trend is expanding demand for institutional-grade custody, reporting, and practice management platforms serving independent advisors.
- Cryptocurrency integration:Spot bitcoin ETF approvals and ether product launches are creating regulated on-ramps for digital asset exposure within traditional brokerage accounts.
- Embedded finance partnerships:Fintech platforms and consumer applications are white-labeling brokerage infrastructure to offer fractional share investing at point-of-sale.
Industry Challenges
- Registered representative licensing timelines:FINRA examination backlogs and state registration delays are constraining advisor headcount growth at expanding firms.
- Legacy core system integration:M&A-driven platform consolidation requires costly reconciliation of disparate account management and reporting architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Securities Brokerage Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Brokerage, Discount Brokerage, Online Trading, Robo-Advisory Client Type: Retail Investors, Institutional Investors, High Net Worth Individuals, Corporations Investment Strategy: Growth Investing, Value Investing, Income Investing, Day Trading Commission Structure: Flat Fee, Percentage of Trade Value, Tiered Pricing, No Commission |
| Companies Covered | JP Morgan, Robinhood Markets, Fidelity Investments, Morgan Stanley Wealth Management, E*TRADE, Charles Schwab, Interactive Brokers, LPL Financial, Vanguard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Securities Brokerage Market Strategic Shifts
Artificial intelligence and predictive analytics are reshaping how broker-dealers engage retail clients, triggering regulatory scrutiny of gamification tactics while enabling hyper-personalized portfolio construction. The competitive frontier is shifting from trade execution speed to holistic financial wellness platform integration.
Cloud-native core banking infrastructure is consolidating back-office functions across clearing, custody, and reporting operations. Mid-sized broker-dealers are migrating from on-premise legacy systems to API-connected platforms, compressing technology cost structures and enabling real-time client data aggregation. This consolidation is eliminating the scale advantages historically held by vertically integrated clearing banks.
FINRA's proposed rules on predictive data analytics and digital engagement practices are tightening supervision of algorithmic prompts driving trading behavior. The framework would mandate documentation of how behavioral prompts are tested and monitored, elevating compliance documentation burdens. Retail-facing platforms are responding by reengineering notification architectures to preemptively satisfy examination standards.
Self-directed investors are unbundling research and advisory services from execution, subscribing to independent research aggregators and social media communities while maintaining low-cost brokerage accounts. Traditional full-service relationships are fragmenting into component purchases across specialized providers, with fee compression most acute among mass-affluent segments in suburban Texas and Florida markets where advisor density lags household formation.
US Securities Brokerage Market Segmentation
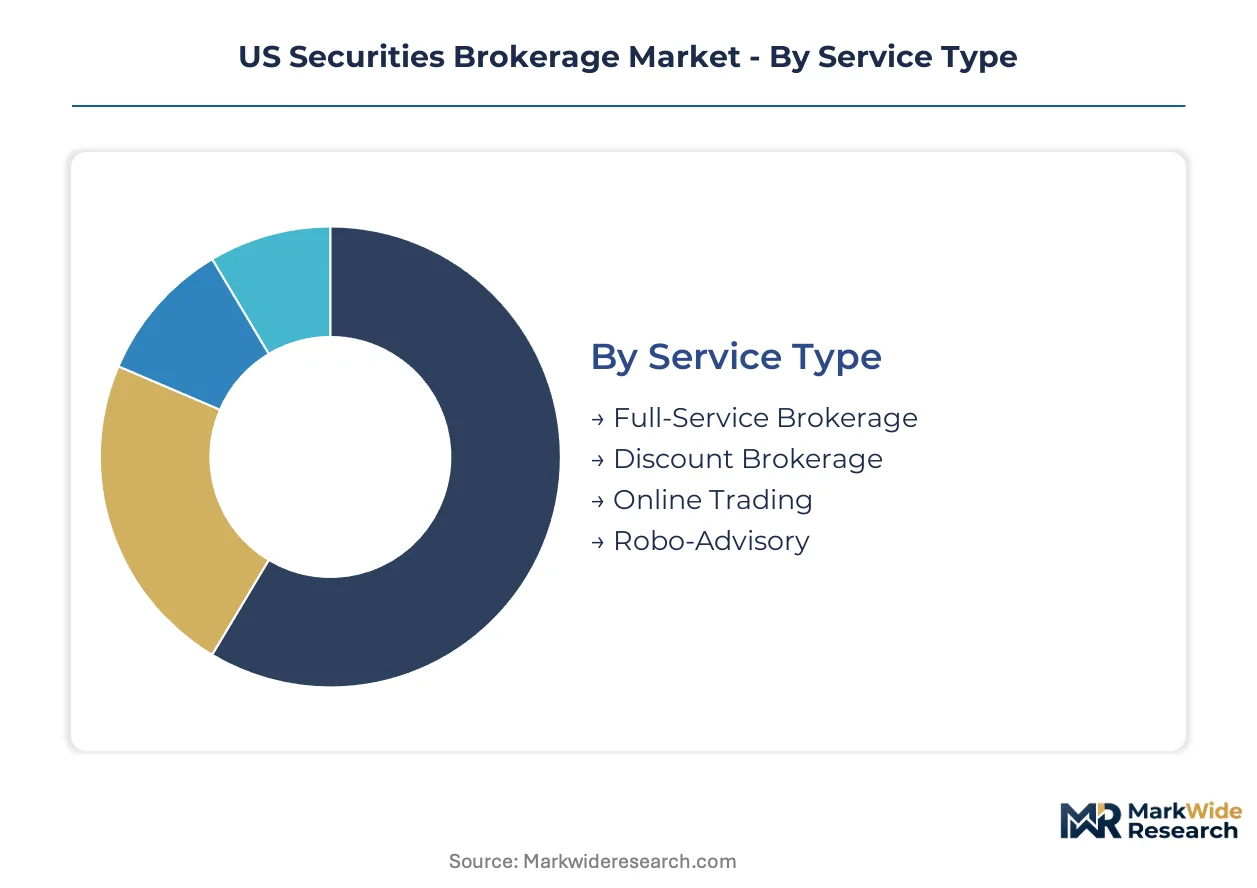
Segmentation reveals how regulatory burden and service intensity vary across brokerage models. SEC registration tiers, FINRA examination requirements, and state licensing mandates create distinct compliance cost structures that shape competitive positioning within each category.
Service Type:
FINRA Series 7 and Series 66 licensing requirements apply differentially across service tiers, with full-service models demanding the most extensive representative certification.
- Full-Service Brokerage:Comprehensive wealth management integrating estate planning, tax strategy, and dedicated advisor relationships. Demand concentrates among Texas and Florida transplants seeking holistic guidance after relocating from high-tax coastal states. SEC Regulation Best Interest elevates documentation burdens for personalized recommendations.
- Discount Brokerage:Execution-focused platforms with limited advisory access and self-directed research tools. Retail participation in suburban Sun Belt markets drives volume as cost-conscious investors unbundle advice from trading. FINRA supervisory technology requirements compress margins on low-ticket transactions.
- Online Trading:Browser and mobile-native platforms emphasizing real-time data and streamlined order entry.
- Robo-Advisory:Automated portfolio construction using algorithmic allocation across passive fund baskets.
Leading the category by volume: Discount Brokerage. Growing fastest: Robo-Advisory.
Client Type:
Account minimums and service customization scale directly with client sophistication, creating four distinct operational models.
- Retail Investors:Mass-market households with sub-$500,000 investable assets accessing standardized platforms. Mobile-native engagement in Florida and Texas suburbs accelerates as migration concentrates addressable households in branch-light territories. FINRA's digital engagement scrutiny targets behavioral prompts directed at this segment.
- High Net Worth Individuals:Households exceeding $1 million in investable assets requiring bespoke custody and concentrated position management. Texas and Florida estate tax advantages attract ultra-wealthy relocations from California and New York. SEC custody rule amendments impose enhanced safeguarding obligations.
- Institutional Investors:Pension funds, endowments, and asset managers executing block trades and accessing prime services.
- Corporations:Treasury departments managing cash positions, share repurchase programs, and employee stock plans.
Retail Investors dominate account volume. High Net Worth Individuals generate the steepest expansion trajectory in assets under management.
Investment Strategy:
Strategy selection determines trading velocity, margin utilization, and suitability documentation requirements under FINRA Rule 2111.
- Day Trading:High-frequency position turnover with leveraged account structures and pattern day trader minimums. Concentrated demand among mobile-native users in Florida's retirement-adjacent communities seeking supplemental income. SEC margin rule enforcement elevates risk disclosure obligations.
- Growth Investing:Long-duration equity positions targeting capital appreciation in expansion-stage companies. Texas technology corridor households favor this approach as regional wealth creation concentrates in equity compensation. FINRA suitability reviews scrutinize concentration risk in volatile sectors.
- Value Investing:Fundamental analysis-driven selection of underpriced securities with margin-of-safety disciplines.
- Income Investing:Yield-focused allocation across dividend equities, fixed income, and option-writing strategies.
Growth Investing leads in asset flows. Day Trading shows the fastest account growth velocity.
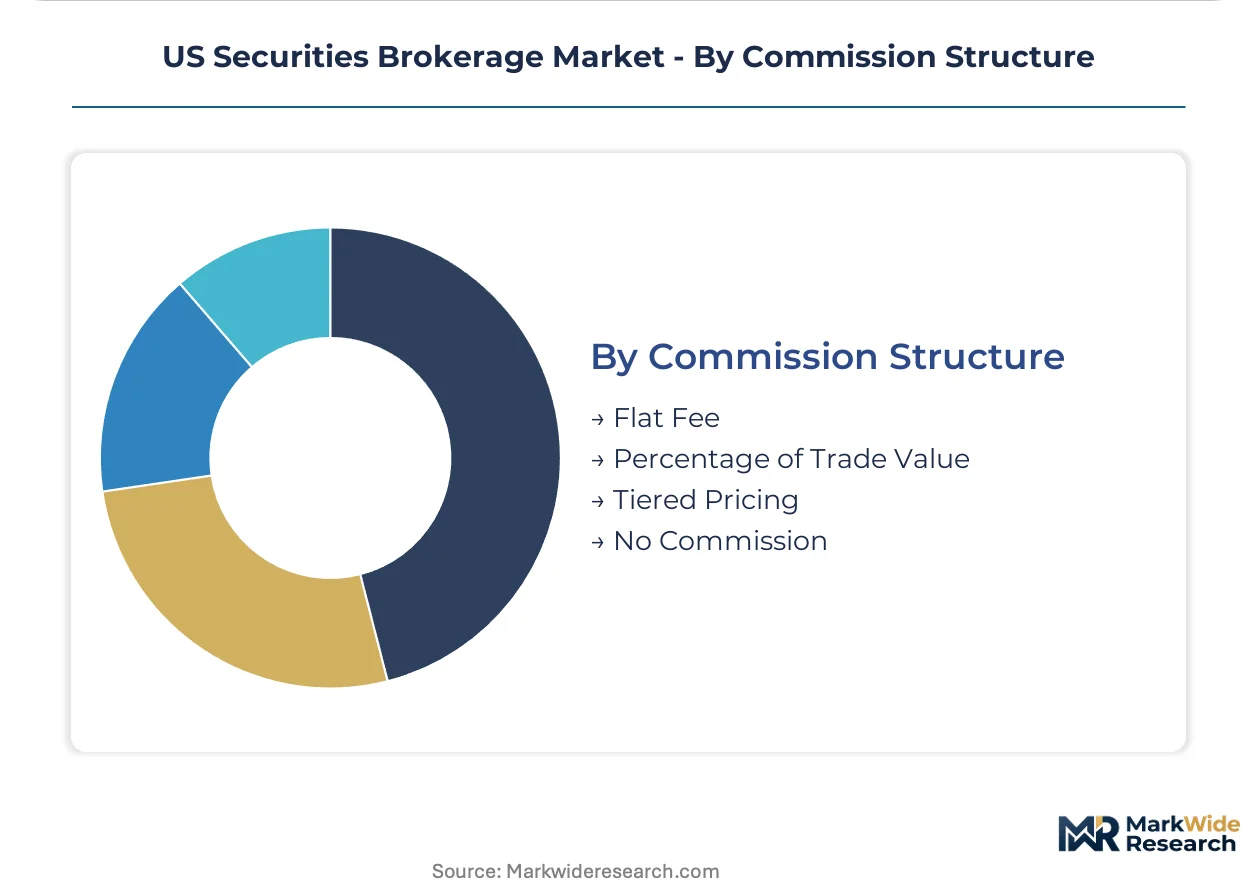
Commission Structure:
Revenue model selection determines regulatory exposure and competitive vulnerability to SEC payment-for-order-flow rulemaking.
- No Commission:Zero-execution-fee platforms monetizing through payment for order flow, securities lending, and net interest margin. Dominant among Texas and Florida millennials prioritizing accessibility over advisory depth. SEC proposals targeting order flow arrangements threaten core revenue architecture.
- Tiered Pricing:Volume-discounted schedules rewarding active traders with per-share or per-trade reductions. High-velocity retail segments in suburban Florida markets favor this structure for cost optimization. FINRA best execution obligations require ongoing price improvement documentation.
- Flat Fee:Fixed per-trade charges regardless of order size or security type.
- Percentage of Trade Value:Ad valorem commissions scaling with transaction notional amount.
No Commission structures dominate new account acquisition. Tiered Pricing retains the most profitable active trader relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and Florida are accelerating high-net-worth household concentration as coastal state tax refugees establish primary residences in low-tax jurisdictions. SEC Regulation Best Interest compliance costs are reshaping advisor distribution across state lines.
Texas
Austin and Dallas-Fort Worth corridors are absorbing technology sector equity compensation wealth as California transplants seek estate tax advantages. The Texas State Securities Board enforces registration requirements for breakaway brokers establishing independent practices. Houston's energy sector executive population is driving demand for concentrated position management and bespoke custody solutions.
Florida
South Florida's Palm Beach and Miami-Dade counties are experiencing ultra-high-net-worth migration from New York and Connecticut seeking income tax elimination. FINRA examination schedules in Florida are expanding to accommodate advisor headcount growth at relocating wirehouse branches. Tampa and Orlando suburbs are emerging as retirement-adjacent day trading hubs with mobile-native platform adoption.
California
Silicon Valley equity compensation vesting cycles continue generating brokerage asset inflows despite net household outmigration to Texas and Nevada. The California Department of Financial Protection and Innovation supplements SEC custody rules with state-level investment adviser examinations. Los Angeles and San Francisco remain concentration points for institutional prime brokerage services serving venture capital and private equity fund complexes.
New York
Manhattan retains institutional trading infrastructure density despite retail advisor migration to Florida. The New York State Department of Financial Services enforces enhanced cybersecurity standards for broker-dealers operating within state boundaries. Wall Street clearing and custody operations continue anchoring back-office employment in the metropolitan area.
Illinois
Chicago's derivatives exchange ecosystem sustains specialized futures commission merchant activity alongside traditional securities brokerage. The Illinois Secretary of State Securities Department coordinates with FINRA on branch office registration for advisors serving the Midwest agricultural wealth corridor. The city's commodity trading heritage supports sophisticated options and derivatives advisory practices.
US Securities Brokerage Market Competitive Environment
Top-tier vendors anchor full-service wealth management, while discount and mobile-native platforms compete on user experience and zero-commission structures. The market exhibits tiered consolidation with bank-owned broker-dealers, independent broker-dealers, and fintech disruptors occupying distinct competitive bands. Strategic archetypes include branch-integrated hybrid advisors, pure-play digital platforms, and RIA custody specialists. M&A activity is concentrating clearing and custody capabilities among scaled providers, while technology partnerships enable embedded finance distribution.
Within the full-service tier, Morgan Stanley Wealth Management and JP Morgan exemplify bank-anchored models combining lending and advisory relationships. Charles Schwab occupies a position bridging self-directed and advised segments through its branch-digital hybrid architecture. Robinhood Markets represents the mobile-native archetype competing on streamlined user experience and cryptocurrency access.
| Leading Market Players |
|---|
| JP Morgan |
| Robinhood Markets |
| Fidelity Investments |
| Morgan Stanley Wealth Management |
| E*TRADE |
| Charles Schwab |
| Interactive Brokers |
| LPL Financial |
| Vanguard |
| Others |
Value Chain & Pricing Dynamics
Cloud-native core banking infrastructure migration is compressing technology cost structures for mid-sized broker-dealers while simultaneously consolidating clearing and custody capabilities among scaled providers, reshaping both margin economics and supplier concentration across the intermediary layer.
Pricing Analysis
Short lead-time pricing premiums attach to real-time clearing and custody transitions as broker-dealers migrate from legacy on-premise systems to API-connected platforms. The dominant pricing structure is a hybrid model blending subscription-based platform access with per-transaction execution fees. Price differentiation rests on customization level and geographic delivery cost, with Sun Belt markets commanding modest premiums due to advisor scarcity. Cost compression in the no-commission tier is intensifying because SEC payment-for-order-flow scrutiny threatens core revenue architecture. Retail investors in suburban Texas and Florida markets exhibit the highest price sensitivity, while high-net-worth transplants from California and New York show the least.
Supply Chain Analysis
FINRA examination qualification and SEC custody rule compliance create gating requirements that concentrate technology vendor relationships among certified providers. Geographic supply concentration centers on the United States for core custody infrastructure, with Ireland and the United Kingdom hosting specialized regulatory reporting platforms. Raw material dependencies include cloud computing capacity from hyperscalers, cybersecurity software licenses, and specialized data feed subscriptions. Single-source vulnerability runs through the limited set of bank-owned clearing firms dominating back-office functions. Distribution runs through direct vendor relationships with broker-dealers and white-label partnerships with fintech platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US securities brokerage sector is navigating a technology-transition phase as artificial intelligence and predictive analytics displace legacy client engagement architectures, forcing firms to reengineer notification systems and portfolio construction methodologies simultaneously.
For Market Incumbents: Acquire cloud-native custody technology stacks to consolidate back-office infrastructure and compress fixed cost bases. Defensive consolidation moves include deepening API integration capabilities to preempt fintech platform competition and investing in FINRA-compliant supervisory technology to absorb examination documentation burdens. Payment-for-order-flow regulatory elimination poses the central threat to zero-commission revenue models. Vertical integration into securities lending and cash sweep programs offers margin protection. For New Entrants and Emerging Players: Begin with embedded finance partnerships targeting consumer applications and point-of-sale platforms seeking fractional share investing capabilities. White-space opportunities concentrate in RIA custody services for breakaway brokers establishing independent practices in Texas and Florida. The most penetrable segment is mobile-native retail investors in suburban Sun Belt markets where advisor density lags household formation. A direct-to-consumer go-to-market angle leveraging streamlined user experience and cryptocurrency access captures initial account velocity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by bank-owned broker-dealers seeking digital platform capabilities and geographic footprint expansion. Long-term viability favors firms with integrated advisory-custody technology stacks and established FINRA examination track records. Acquisition target archetypes include mid-sized independent broker-dealers with compliant infrastructure and established advisor networks in high-migration corridors. The signal to watch as inflection indicator is SEC final rulemaking on predictive data analytics and gamification restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| RIA Custody Platform Acquisition | Captures breakaway broker asset flows as independent advisor migration accelerates across Sun Belt states. |
| Cryptocurrency Integration Launch | Creates regulated digital asset on-ramps following spot bitcoin ETF approvals by the SEC. |
| Cloud-Native Core Migration | Compresses technology costs while enabling real-time client data aggregation for mid-sized broker-dealers. |
| Embedded Finance Partnership | Distributes fractional share investing through fintech platforms and consumer applications at point-of-sale. |
| FINRA Compliance Technology Investment | Preemptively satisfies examination standards for predictive analytics and digital engagement practices. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with broker-dealer operations executives, FINRA compliance officers, RIA practice managers, and fintech platform engineers. Secondary validation drew from SEC Form ADV filings, FINRA examination reports, SIFMA industry statistics, and clearing firm disclosure documents. Bottom-up account and asset aggregation was triangulated against top-down market sizing from regulatory aggregates.
Data-stream reconciliation across primary fieldwork and secondary databases shaped the analytical framework for projections across the analysis window. Segmentation dimensions modeled include service type, client sophistication tier, investment strategy orientation, and commission structure preference. CAGRs were derived from trend extrapolation of account growth, asset flow velocity, and revenue per account metrics. Industry-specific forecast inputs incorporated workplace retirement plan rollover velocity and high-net-worth household migration patterns between coastal and Sun Belt states.
Underlying measurement precision varies by segment; retail investor account volume carries tighter precision than ultra-high-net-worth asset concentration. Forecasts reflect assumptions regarding regulatory rulemaking timelines, interest rate trajectory stability, and technology adoption curves. A model refresh is warranted upon material change in SEC payment-for-order-flow rulemaking or FINRA predictive analytics enforcement standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market