
 Europe Capital Exchange Ecosystem Market | 2026-2036
Europe Capital Exchange Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Capital Exchange Ecosystem Market Insights
Asset-light exchange infrastructure and cloud-hosted matching engines are rewriting competitive entry barriers across European capital markets. Deutsche Börse leverages its vertical integration into clearing and settlement to sustain margin capture beyond pure trading fees. Euronext anchors its multi-country pan-European network, competing across Paris, Amsterdam, Brussels and Lisbon from a unified technology stack. London Stock Exchange Group differentiates through its LCH clearing arm and Refinitiv data services, extending its revenue model far beyond traditional listing fees.
The Europe Capital Exchange Ecosystem encompasses the integrated infrastructure of trading venues, clearinghouses, settlement systems, market data providers, and regulatory reporting platforms that enable capital formation and secondary market liquidity across the continent. Its primary commercial purpose is to reduce friction in price discovery, counterparty risk management, and asset ownership transfer for issuers and investors operating under EU and national securities frameworks. Equity listings and derivatives clearing represent the most mature margin pools, while debt origination platforms and real estate tokenization engines represent the fastest-growing structural segments as institutional investors seek yield alternatives. Transaction size stratification shows mid-cap listings gaining venue competition as Aquis Stock Exchange and regional bourses challenge incumbent pricing for growth companies.
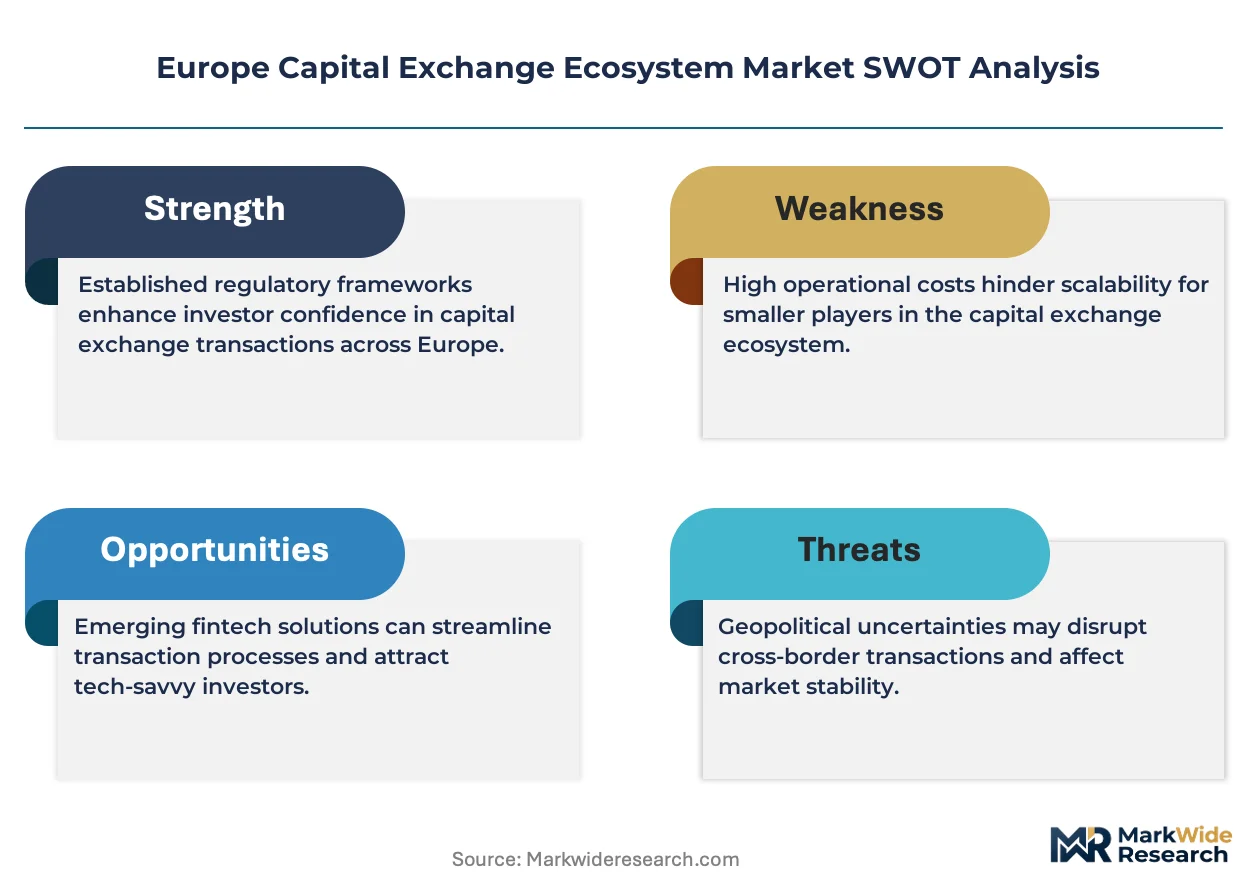
ESMA's oversight of MiFID II best execution rules and the EU's DLT Pilot Regime for market infrastructure reshape product standards and market access conditions for new trading technologies. The ECB's TARGET2-Securities settlement framework and national regulators including BaFin in Germany and the FCA in the United Kingdom enforce divergent custody and capital requirements that fragment cross-border operational design. Stakeholders must monitor how the EU's retail investment strategy and forthcoming consolidated tape mandates alter data monetization models and venue connectivity investments.
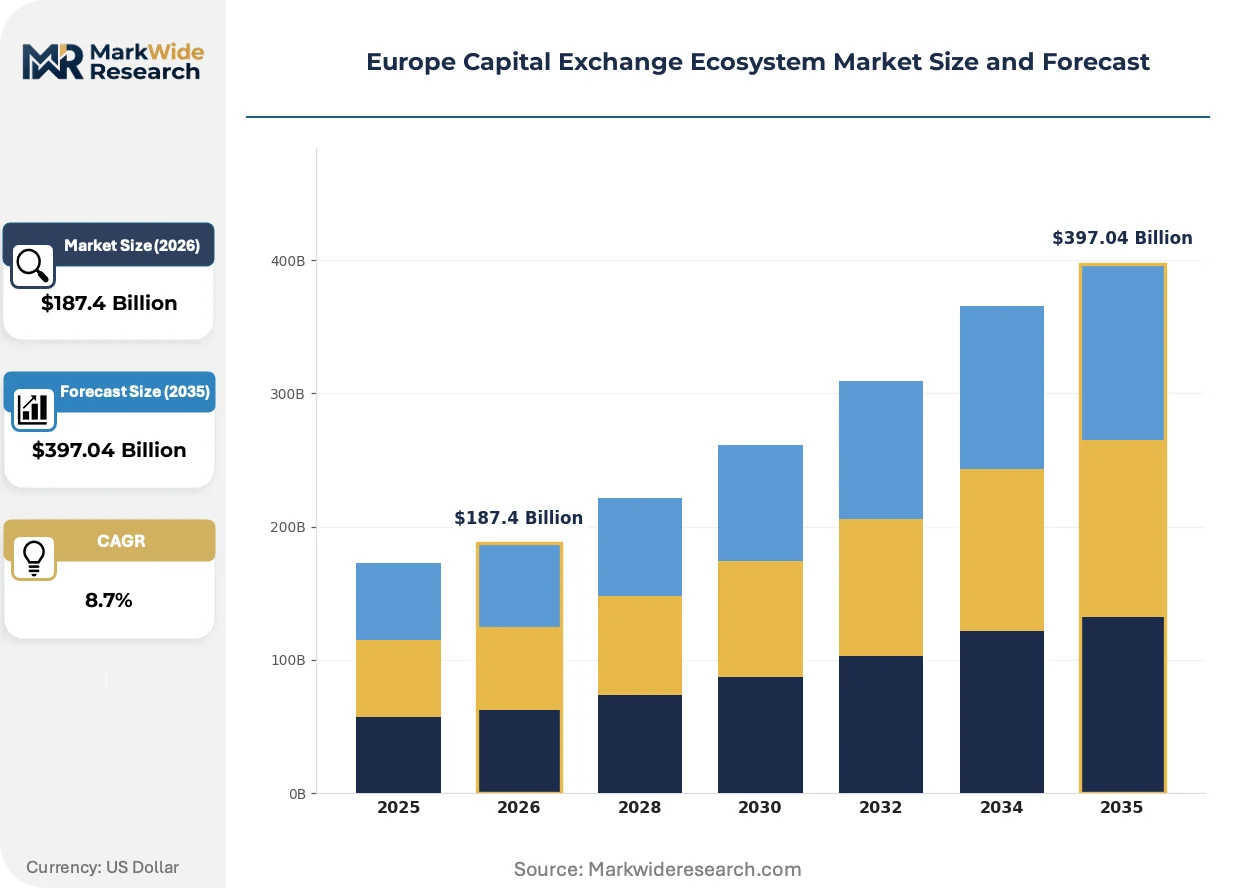
Market Dynamics
Asset-light exchange infrastructure and cloud-hosted matching engines are compressing competitive entry barriers across European capital markets, forcing incumbent venues to defend margin capture through clearing integration and data monetization rather than pure transaction fees.
Growth Catalysts
- MiFID II best execution mandates:Transparency requirements force trading venues to upgrade routing infrastructure, creating demand for smart order management systems across French and German broker-dealers.
- DLT Pilot Regime authorization:The EU's distributed ledger framework permits tokenized securities settlement, enabling blockchain-native clearing pilots in Luxembourg and the Netherlands.
- Fintech Series B concentration:Growth-stage capital formation in Frankfurt-Rhine-Main and Paris drives venue competition for mid-cap listings and secondary liquidity provision.
Market Restraints
- Clearing concentration risk:Euro-denominated derivatives processing depends on a limited pool of CCPs, creating systemic exposure to single-venue operational failures.
- TARGET2-Securities fixed costs:ECB settlement infrastructure imposes uniform connectivity fees that disadvantage smaller national bourses with lower transaction volumes.
- Regulatory fragmentation:Divergent custody rules between BaFin in Germany and the FCA in the United Kingdom force dual compliance architectures for cross-border trading firms.
Strategic Opportunities
- Nordic retail investment expansion:Sweden and Denmark show underpenetrated direct equity ownership rates, creating white space for low-cost fractional share platforms.
- CSRD disclosure convergence:Corporate sustainability reporting mandates generate demand for ESG-integrated market data feeds and green bond origination infrastructure.
- Real estate tokenization engines:Property-backed digital securities attract institutional yield seekers, with Luxembourg's securitization expertise supporting specialized issuance platforms.
Industry Challenges
- Quantitative trading talent scarcity:Matching engine optimization and latency arbitrage require specialized firmware engineers, with European universities producing insufficient pipeline.
- Legacy core banking integration:Tier-2 brokerages struggle to connect modern API-first trading stacks to COBOL-based custody systems, delaying platform modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Capital Exchange Ecosystem Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Series A, Series B, Series C Asset Class: Equity, Debt, Derivatives, Real Estate Transaction Size: Small Cap, Mid Cap, Large Cap, Mega Cap Client Type: Institutional Investors, Retail Investors, Family Offices, Hedge Funds |
| Companies Covered | Euronext, London Stock Exchange Group, Deutsche Börse, SIX Swiss Exchange, Nasdaq Nordic, Frankfurt Stock Exchange, Borsa Italiana, Oslo Stock Exchange, Aquis Stock Exchange, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Capital Exchange Ecosystem Market Trends and Innovations
European capital markets infrastructure is undergoing platform consolidation as cloud-native architectures displace on-premise matching engines, while regulatory technology investments accelerate to meet real-time reporting mandates.
Distributed ledger infrastructure for securities settlement is migrating from experimental pilots to production-grade deployment. Luxembourg's fund industry and Dutch pension administrators are testing tokenized bond settlement at scale. This migration from proof-of-concept to live clearing is compressing settlement cycles from T+2 toward T+0, forcing traditional custodians to reconfigure their operating models.
The EU's DLT Pilot Regime creates a controlled sandbox for market infrastructure operators to bypass certain MiFID II requirements when deploying blockchain-based trading systems. This regulatory carve-out permits testing of novel settlement finality mechanisms without full-scale rulebook rewrites. German and French CCPs are the primary applicants, seeking to anchor European standards before UK and Swiss competitors establish alternative frameworks.
Institutional procurement of market data is fragmenting across specialized alternative data providers rather than consolidating through incumbent terminals. Hedge funds and systematic managers in London and Amsterdam now source sentiment feeds, satellite imagery, and supply chain analytics through API subscriptions. This unbundling is most visible in quantitative equity strategies, where raw price data alone no longer commands premium pricing.
Europe Capital Exchange Ecosystem Market Segmentation
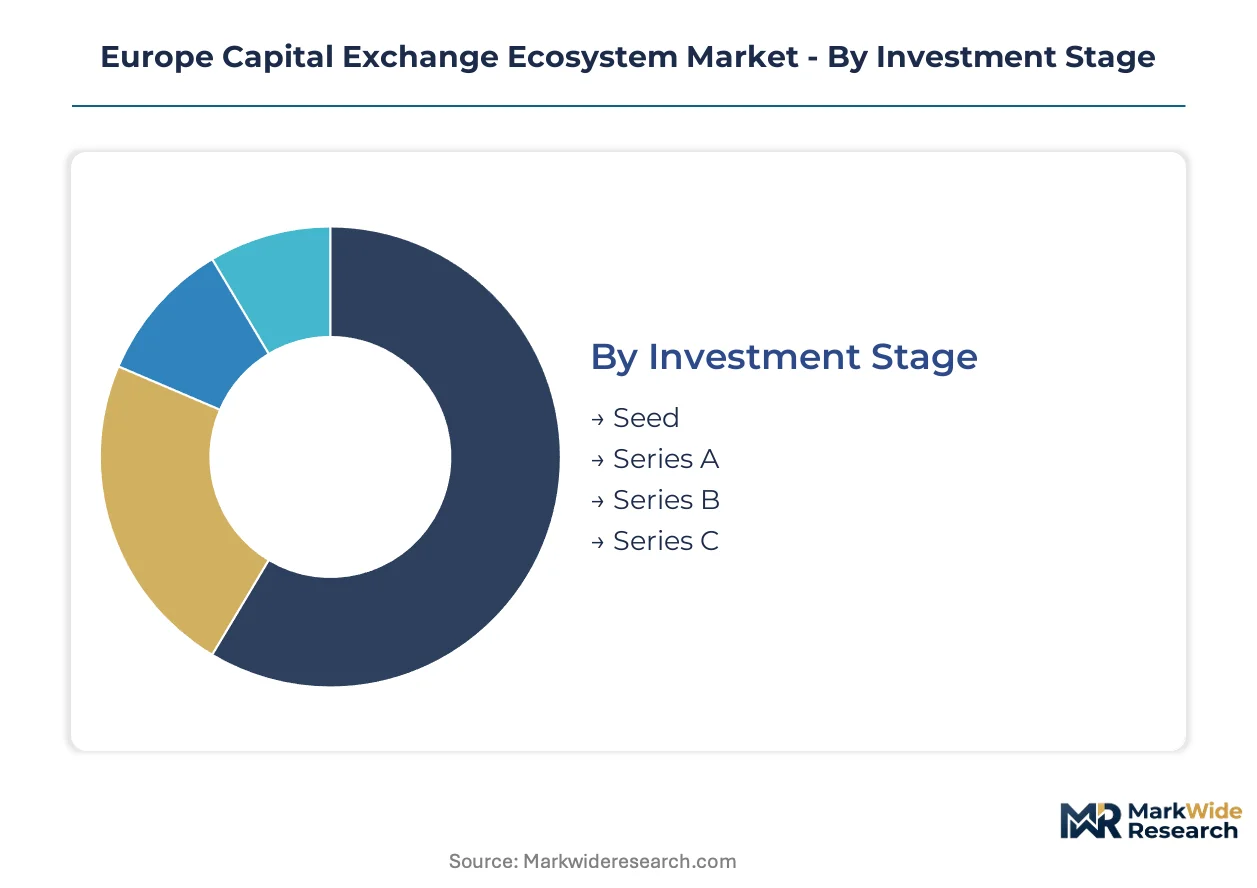
Segmentation in the Europe Capital Exchange Ecosystem reveals how capital formation velocity varies dramatically across funding stages, asset classes, and participant profiles. Understanding these structural divisions exposes where venue infrastructure investments concentrate and where margin capture differs most sharply.
Investment Stage:
Seed rounds turn over fastest with compressed fundraising cycles, while later stages lock capital for years as companies scale toward liquidity events.
- Seed:Pre-revenue ventures raise initial capital through angel syndicates and accelerators in Berlin and Stockholm. Founders in Amsterdam and Lisbon access EU innovation grants alongside private capital, though venue formalization remains minimal at this tier.
- Series A:Revenue-generating startups secure growth financing through specialized venture platforms. Paris-based SaaS companies and Munich hardware ventures drive concentrated demand for standardized term sheets and governance infrastructure.
- Series B:Scaling enterprises require deeper liquidity pathways and secondary transaction capabilities. Frankfurt-Rhine-Main fintech clusters anchor this segment's infrastructure requirements, with Euronext and regional bourses competing aggressively for listing mandates.
- Series C:Pre-IPO companies access pre-IPO private markets and specialized growth equity funds. London and Zurich family offices dominate capital deployment here, with settlement cycles extending to accommodate complex preference structures.
Series B anchors the volume base while Seed gains share at the steepest rate as accelerator networks proliferate across Eastern Europe.
Asset Class:
Cost tier stratification separates high-touch origination infrastructure from automated secondary trading platforms.
- Equity:Common and preferred share trading dominates transaction flow across Euronext and Deutsche Börse venues. German mid-cap listings and Dutch tech IPOs concentrate demand for transparent price discovery and T+2 settlement finality.
- Debt:Corporate bonds and green fixed-income instruments require specialized origination platforms and credit rating integration. Luxembourg's securitization expertise supports institutional yield portfolios seeking ESG-aligned coupon structures.
- Derivatives:Options, futures, and structured products demand centralized clearing through LCH and Eurex. Euro-denominated interest rate swaps concentrate systemic risk in a limited CCP pool, driving regulatory scrutiny of margin models.
- Real Estate:Property-backed securities and REITs trade through specialized settlement frameworks. Tokenization pilots in the Netherlands and Luxembourg compress ownership transfer cycles from months to days.
Equity commands the infrastructure investment priority while Real Estate expands most quickly through DLT authorization pathways.
Transaction Size:
Volume concentration patterns invert between retail-accessible small lots and institutionally dominated block trades.
- Small Cap:Companies below €500 million market capitalization access alternative venues and growth-focused broker networks. Aquis Stock Exchange and regional German bourses compete on fee structures for this issuer base.
- Mid Cap:Growth-stage listings between €500 million and €5 billion attract venue competition from Euronext and Deutsche Börse. French and German companies in this tier drive demand for research coverage and liquidity provision incentives.
- Large Cap:Established issuers above €5 billion dominate benchmark indices and passive fund flows. Amsterdam and Paris headquarters for pan-European corporations concentrate index rebalancing activity.
- Mega Cap:Multi-hundred-billion-euro market values command specialized block trading infrastructure. London and Frankfurt broker-dealers manage execution for sovereign wealth funds and global asset managers.
Large Cap anchors the volume base while Small Cap climbs the fastest as fractional share platforms democratize access.
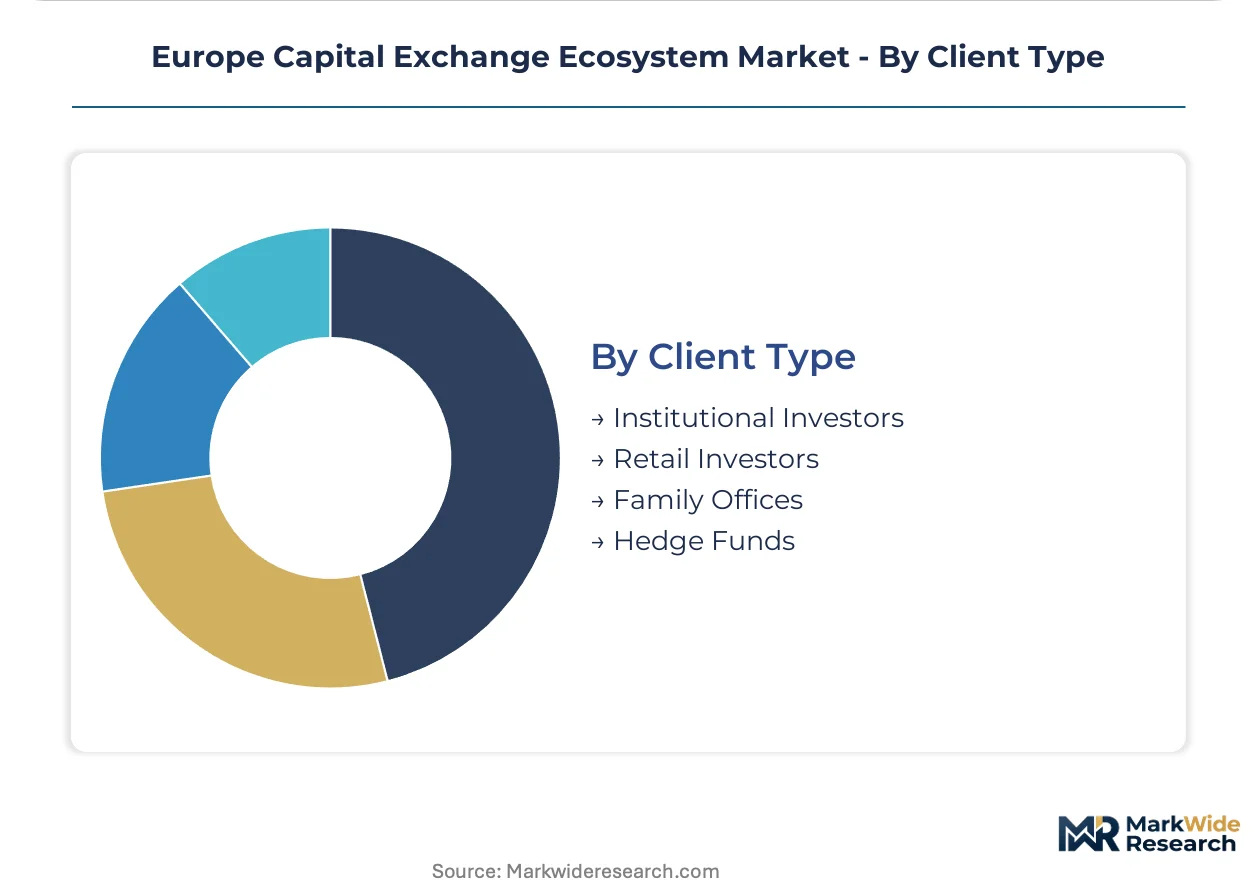
Client Type:
Margin capture potential separates price-sensitive retail flow from relationship-driven institutional mandates.
- Institutional Investors:Pension funds and insurance companies deploy long-horizon capital through segregated mandates. Dutch and Danish pension administrators drive demand for liability-matching fixed-income infrastructure.
- Retail Investors:Direct equity ownership concentrates in Nordic markets with underpenetrated participation rates. Swedish and Finnish mobile-first platforms compete on commission-free execution and educational content.
- Family Offices:Single and multi-family investment vehicles access co-investment structures and direct deal flow. Swiss and Luxembourg private wealth clusters demand bespoke reporting and alternative asset custody.
- Hedge Funds:Systematic and discretionary managers source alpha through quantitative strategies and event-driven positioning. London and Amsterdam quantitative funds drive demand for alternative data feeds and low-latency execution.
Institutional Investors anchor the volume base while Retail Investors gain share at the steepest rate through platform democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional investors and fintech growth companies concentrate demand across distinct national financial clusters, with regulatory divergence between EU member states and the United Kingdom fragmenting operational architectures for cross-border trading firms.
Germany
BaFin's custody rules and TARGET2-Securities connectivity requirements anchor infrastructure investment in the Frankfurt-Rhine-Main cluster. The ECB's settlement framework imposes uniform fees that disadvantage smaller bourses while concentrating euro-denominated derivatives clearing in Eurex. Deutsche Börse's vertical integration into clearing and settlement sustains margin capture beyond pure trading fees.
United Kingdom
FCA divergence from EU MiFID II implementation creates dual compliance burdens for cross-border broker-dealers. London Stock Exchange Group leverages LCH clearing and Refinitiv data services to extend revenue models beyond traditional listing fees. The capital's quantitative hedge fund community drives demand for alternative data feeds and low-latency execution infrastructure.
France
Euronext's unified technology stack anchors pan-European network competition from Paris across Amsterdam, Brussels and Lisbon. ESMA's best execution mandates force French broker-dealers to upgrade smart order management systems. The Île-de-France region concentrates SaaS venture activity that feeds Series A and B capital formation demand.
Netherlands
Dutch pension administrators test tokenized bond settlement at scale under the EU's DLT Pilot Regime authorization. Amsterdam's quantitative fund cluster sources sentiment feeds and satellite imagery through API subscriptions rather than incumbent terminals. The country's securitization expertise supports institutional yield portfolios seeking ESG-aligned structures.
Luxembourg
The fund industry's securitization specialization enables real estate tokenization engines for institutional yield seekers. CSSF oversight of DLT market infrastructure permits production-grade deployment of blockchain-native clearing pilots. The financial center's expertise in cross-border fund distribution attracts specialized issuance platforms for property-backed digital securities.
Europe Capital Exchange Ecosystem Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where incumbent exchanges defend position through clearing integration and data monetization rather than pure transaction fees. The vendor base stratifies between pan-European network operators, national incumbent bourses, and alternative venue challengers. Three archetypes dominate: vertically integrated clearing-and-settlement platforms, cloud-native matching engine specialists, and regional bourses competing on fee structures for mid-cap listings. M&A activity concentrates on data services acquisitions and technology stack consolidation, while strategic partnerships focus on API-first connectivity and alternative data feed distribution.
Among pan-European exchange operators, Euronext and London Stock Exchange Group exemplify the network-scale archetype through multi-country technology unification and clearing arm extension. Deutsche Börse anchors the vertically integrated tier with captive control over post-trade infrastructure. At the challenger end, Aquis Stock Exchange occupies a position competing on transparent pricing for growth-company listings outside incumbent fee structures.
| Leading Market Players |
|---|
| Euronext |
| London Stock Exchange Group |
| Deutsche Börse |
| SIX Swiss Exchange |
| Nasdaq Nordic |
| Frankfurt Stock Exchange |
| Borsa Italiana |
| Oslo Stock Exchange |
| Aquis Stock Exchange |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud-hosted matching engines across Frankfurt and London data centers compresses infrastructure margins while forcing vendors toward clearing-integration and data-monetization revenue models. Utilization rates below sixty percent in colocation facilities drive aggressive pricing for connectivity and co-location services, reshaping how venues recover fixed costs through tiered service bundling.
Pricing Analysis
Cost-plus contracts with ECB TARGET2-Securities fee indexation dominate settlement infrastructure procurement, locking national bourses into uniform connectivity charges regardless of transaction scale. Three-tier pricing structure across premium co-location, standard connectivity, and economy data-feed tiers separates latency-sensitive hedge funds from retail broker-dealers. Pricing pressure stems from Aquis Stock Exchange and regional challengers undercutting incumbent listing fees for mid-cap issuers. Retail broker-dealers exhibit highest price sensitivity, while systematic funds prioritize latency guarantees over cost minimization.
Supply Chain Analysis
Export-control restrictions on sub-10-nanometer chip fabrication equipment limit European access to advanced matching-engine processors, constraining domestic hardware sourcing. Supply concentration centers on Taiwan for semiconductor fabrication, Ireland for cloud infrastructure hosting, and Germany for specialized firmware engineering. Raw material dependencies include high-purity silicon wafers, low-latency fiber-optic cable, and liquid cooling systems. Single-source vulnerability to Taiwan Semiconductor Manufacturing concentration threatens matching-engine upgrade cycles. Distribution runs through tier-1 broker-dealers with direct venue connectivity, bypassing traditional hardware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European capital markets infrastructure sits at a platform-economics inflection where API-first connectivity standards and consolidated tape mandates are unbundling data monetization from execution services. Interoperability shifts toward T+0 settlement finality through DLT Pilot Regime authorization are rewiring competitive moats around clearing integration rather than matching-engine ownership.
For Market Incumbents: Entrench clearing-captive revenue streams through deeper Eurex and LCH margin pool control as cloud-native challengers erode pure transaction fees. Defend data-feed pricing power by embedding ESG analytics and alternative data into core subscriptions before consolidated tape mandates commoditize raw price data. Prioritize MiFID II best execution compliance infrastructure as a retention lever for broker-dealer clients facing ESMA scrutiny.
For New Entrants and Emerging Players: Nordic retail equity ownership gaps in Sweden and Denmark represent the most penetrable entry point for fractional-share platforms with mobile-native execution. Luxembourg's securitization expertise and CSSF DLT authorization create white space for real estate tokenization engines targeting institutional yield portfolios. A direct-to-investor go-to-market angle bypassing incumbent broker-dealer channels captures margin otherwise lost to distribution intermediaries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-hosted matching-engine deployments as software-defined infrastructure displaces proprietary hardware. Acquisition targets should emphasize vertically integrated clearing-and-settlement platforms with captive margin pools rather than pure-play trading venues. Monitor DLT Pilot Regime authorization velocity as the critical signal for which infrastructure operators will anchor European tokenized securities standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Clearing Integration Deepening | Eurex and LCH margin pool expansion captures post-trade revenue beyond execution fees. |
| Cloud-Native Matching Engine Deployment | Software-defined infrastructure reduces colocation dependency and compresses hardware capex cycles. |
| Alternative Data Feed Unbundling | API-first sentiment and satellite imagery distribution bypasses incumbent terminal monetization. |
| DLT Pilot Regime Authorization | Luxembourg and Dutch blockchain settlement pilots establish production-grade T+0 finality standards. |
| ESG-Integrated Market Data Launch | CSRD disclosure convergence creates demand for green bond origination and sustainability analytics infrastructure. |
Research Methodology
The analysis maps trading venue infrastructure, clearing and settlement systems, market data distribution, and regulatory technology sub-sectors, each validated through exchange technology officers, broker-dealer heads of execution, central counterparty risk managers, and buy-side trading desk leads. Primary interview intelligence triangulates against ESMA regulatory filings, ECB TARGET2-Securities connectivity disclosures, national exchange annual reports, and MiFID II transaction cost analysis datasets. Bottom-up segment sizing and top-down macroeconomic anchoring converge through iterative stakeholder calibration.
Assumptions held fixed include MiFID II regulatory framework continuity, TARGET2-Securities settlement infrastructure availability, and EU DLT Pilot Regime authorization scope. The analytical framework varies investment stage, asset class, transaction size, and client type segmentation dimensions across the projection horizon. CAGRs derive from historical volume trajectory analysis and forward-looking venue capacity expansion announcements. Forecast inputs incorporate fintech Series B financing velocity and institutional adoption rates for tokenized securities infrastructure.
Practitioners should monitor ECB settlement fee restructuring, ESMA consolidated tape implementation timing, and DLT Pilot Regime permanent authorization decisions for early signals of infrastructure revenue model disruption. Forecasts reflect these documented assumptions. Material shifts in EU retail investment strategy mandates or cross-channel regulatory divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market