
 Middle East and Africa ETF Market | 2026-2036
Middle East and Africa ETF Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa ETF Market Foresight
Passive index replication is hardening as the dominant cost architecture across the Middle East and Africa ETF landscape. BlackRock leverages its iShares platform scale to anchor liquidity in Gulf equity benchmarks. Al Bilad Capital specializes in Sharia-compliant fund construction, while HSBC Saudi competes through local custody and market-making infrastructure.
The Middle East and Africa ETF constitutes an exchange-traded fund that tracks specified indices, holds underlying securities in a creation basket structure, and trades on secondary markets with intraday pricing transparency. Its primary commercial purpose delivers low-cost, liquid exposure to regional equity, fixed income, commodity, and real estate asset classes for institutional and retail portfolios. Equity strategies dominate current asset flows given benchmark depth in Saudi and Emirati markets, while fixed income segments capture institutional demand for sukuk and sovereign debt duration. Distribution through brokerage and online platforms is accelerating as regulatory frameworks permit direct retail subscription without advisor intermediation.
The UAE Securities and Commodities Authority and Saudi Capital Market Authority shape fund registration, disclosure standards, and foreign ownership limits that determine which products access domestic exchanges. South Africa's Financial Sector Conduct Authority applies conduct standards and retail suitability frameworks that influence product design and distribution channel economics. Stakeholders must monitor how harmonization between Gulf Cooperation Council regulators and sub-Saharan African securities commissions evolves cross-listing protocols and primary market creation mechanics.
Market Dynamics
Passive index replication is hardening as the dominant cost architecture across the Middle East and Africa ETF landscape, compressing expense ratios and forcing active managers to defend fee structures through specialized exposures.
Growth Catalysts
- Sharia-Compliant Frameworks:The UAE's Securities and Commodities Authority has streamlined fund registration for Islamic finance structures, expanding addressable investor pools across sovereign wealth and pension schemes.
- Retail Access Liberalization:South Africa's Financial Sector Conduct Authority advances direct subscription rules that bypass advisor intermediation, accelerating brokerage and online platform distribution.
- Gulf Financial Center Concentration:Riyadh and Dubai anchor liquidity creation through local custody infrastructure and market-making depth in Saudi and Emirati equity benchmarks.
Market Restraints
- Foreign Ownership Limits:Saudi Capital Market Authority caps on non-resident equity exposure restrict benchmark replication accuracy for international fund structures.
- Sukuk Supply Concentration:Sovereign issuance from Gulf Cooperation Council members dominates fixed income ETF underlying baskets, creating duration mismatch risks.
- Creation Basket Complexity:In-kind transfer mechanics for Sharia-compliant securities require specialized legal frameworks unavailable across sub-Saharan African exchanges.
Strategic Opportunities
- Nigeria Exchange Modernization:The Securities and Exchange Commission's demutualization program enables ETF primary market infrastructure that currently lacks authorized participant networks.
- Commodity-Equity Hybrids:Blended structures tracking both regional equity indices and precious metals futures address inflation-hedge demand from institutional allocators.
- Cross-Listing Harmonization:Gulf Cooperation Council regulators are aligning disclosure standards to permit dual-listing of Saudi-domiciled funds on UAE exchanges.
Industry Challenges
- Islamic Finance Certification Timelines:Sharia board approval processes for new index methodologies extend product development cycles beyond conventional ETF launch windows.
- Authorized Participant Scarcity:Market-making capacity concentrates among banks with balance sheet scale to handle in-kind creation baskets across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa ETF Market |
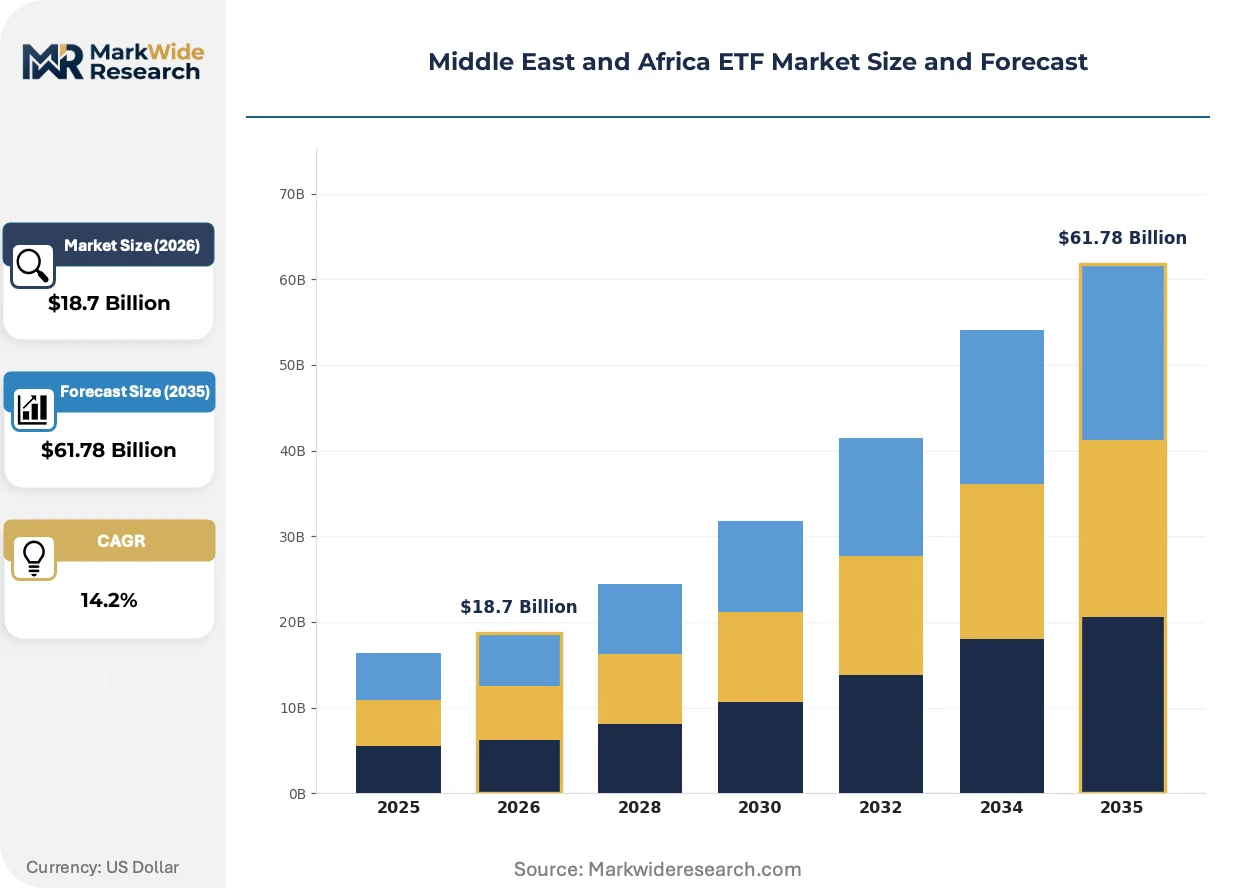
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Class: Equity, Fixed Income, Commodities, Real Estate Investment Strategy: Growth, Value, Income, Index Based Fund Size: Small Cap, Mid Cap, Large Cap, All Cap Distribution Channel: Brokerage, Online Platform, Financial Advisor, Direct Investment |
| Companies Covered | Al Bilad Capital, Alinma Investment, Al Rayan Qatar, HSBC Saudi, Alkhabeer Capital, BlackRock, Invesco, Franklin Templeton, Xtrackers, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa ETF Market Shifts & Advancements
Digital distribution infrastructure and regulatory harmonization are actively compressing the cost and complexity barriers that historically limited ETF penetration across fragmented African exchanges and Gulf secondary markets.
Blockchain-based settlement infrastructure is converging with traditional creation basket mechanics. The Dubai Financial Services Authority has approved pilot programs for tokenized fund units that settle same-day rather than T+2. This compression eliminates counterparty exposure windows that currently inflate collateral requirements for market makers.
Saudi Arabia's Capital Market Authority revised foreign investor disclosure thresholds in its 2024 ETF rulebook. The industrial consequence shifts benchmark composition authority toward domestic asset managers with real-time flow data. Fixed income segments face the most acute adjustment as sukuk liquidity reporting requirements tighten.
Institutional procurement of ETF exposures is fragmenting across specialized mandates rather than consolidating into broad regional indices. Pension schemes in South Africa now specify ESG screening overlays that exclude thermal coal and alcohol holdings. This unbundling forces index providers to maintain parallel calculation engines for conventional and screened variants.
Middle East and Africa ETF Market Segmentation
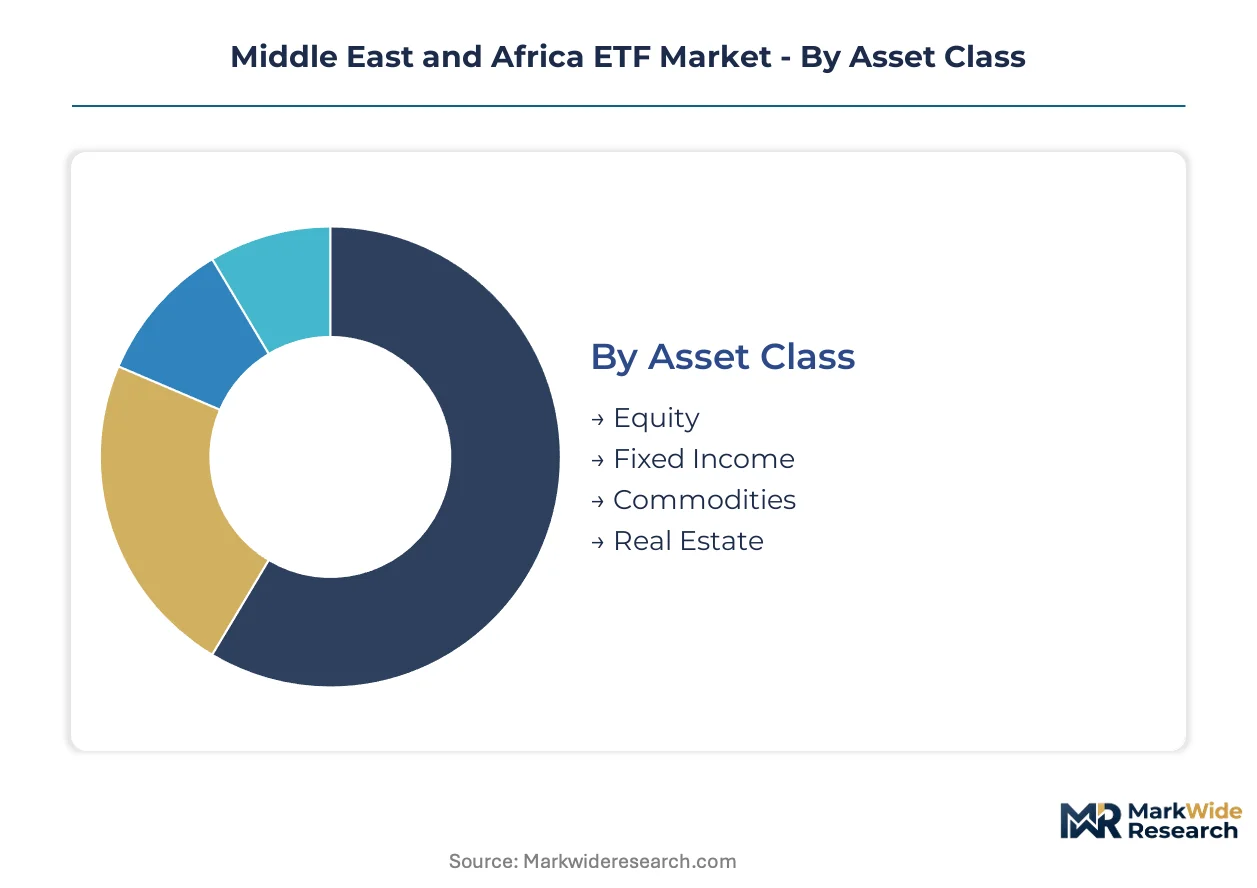
Segmentation in the Middle East and Africa ETF market reveals how investor mandates, regulatory constraints, and distribution economics fragment product design. Each dimension carries distinct cost structures and compliance burdens that determine which fund structures achieve scale.
Asset Class:
Institutional allocators select asset classes based on benchmark depth, Sharia certification availability, and local custody infrastructure maturity.
- Equity:Tracks regional benchmarks dominated by Saudi and Emirati listings, requiring authorized participants to manage foreign ownership limit complications. Saudi sovereign wealth funds and UAE pension schemes concentrate demand here, driven by Tadawul and DFM liquidity depth.
- Fixed Income:Holds sukuk and sovereign debt instruments with specialized in-kind creation mechanics for Sharia-compliant securities. Institutional demand from Gulf Cooperation Council pension schemes focuses on duration exposure, though sovereign issuance concentration creates rollover risk.
- Commodities:Provides exposure to precious metals and energy futures through swap-based or physically-backed structures.
- Real Estate:Captures REIT and property development equity exposure with concentration in Dubai and Riyadh commercial markets.
Volume sits with Equity; growth tilts toward Fixed Income.
Investment Strategy:
Strategy selection reflects fee compression pressure and the availability of specialized index methodologies.
- Growth:Targets companies with above-median earnings expansion, typically in Saudi technology and UAE logistics sectors. South African pension schemes with equity-heavy mandates drive demand, constrained by limited benchmark constituent depth outside Gulf markets.
- Value:Employs price-to-book and dividend yield screens across mature Saudi banking and South African mining equities. Institutional allocators seeking yield enhancement favor this approach, though Sharia compliance filters exclude conventional financials.
- Income:Prioritizes dividend sustainability and sukuk coupon streams.
- Index Based:Replicates broad regional benchmarks with minimal tracking error.
Index Based dominates current flows; Value is climbing the fastest as ESG overlays proliferate.
Fund Size:
Fund size segmentation determines authorized participant economics and primary market creation viability.
- Large Cap:Tracks the most liquid constituents of Saudi and Emirati benchmarks with tight bid-ask spreads. UAE brokerage platforms and Saudi institutional direct subscription channels concentrate demand here, supported by market-making capacity at major Gulf banks.
- Mid Cap:Captures secondary-tier liquidity in Tadawul and DFM listings with wider spreads requiring specialized market-making commitment. South African retail platforms expanding into Gulf exposure favor this segment, driven by relative valuation discounts to large-cap peers.
- Small Cap:Addresses frontier market exposure with limited creation basket liquidity.
- All Cap:Blends market capitalizations for comprehensive benchmark replication.
Large Cap commands institutional procurement; Mid Cap gains share fastest through retail platform expansion.
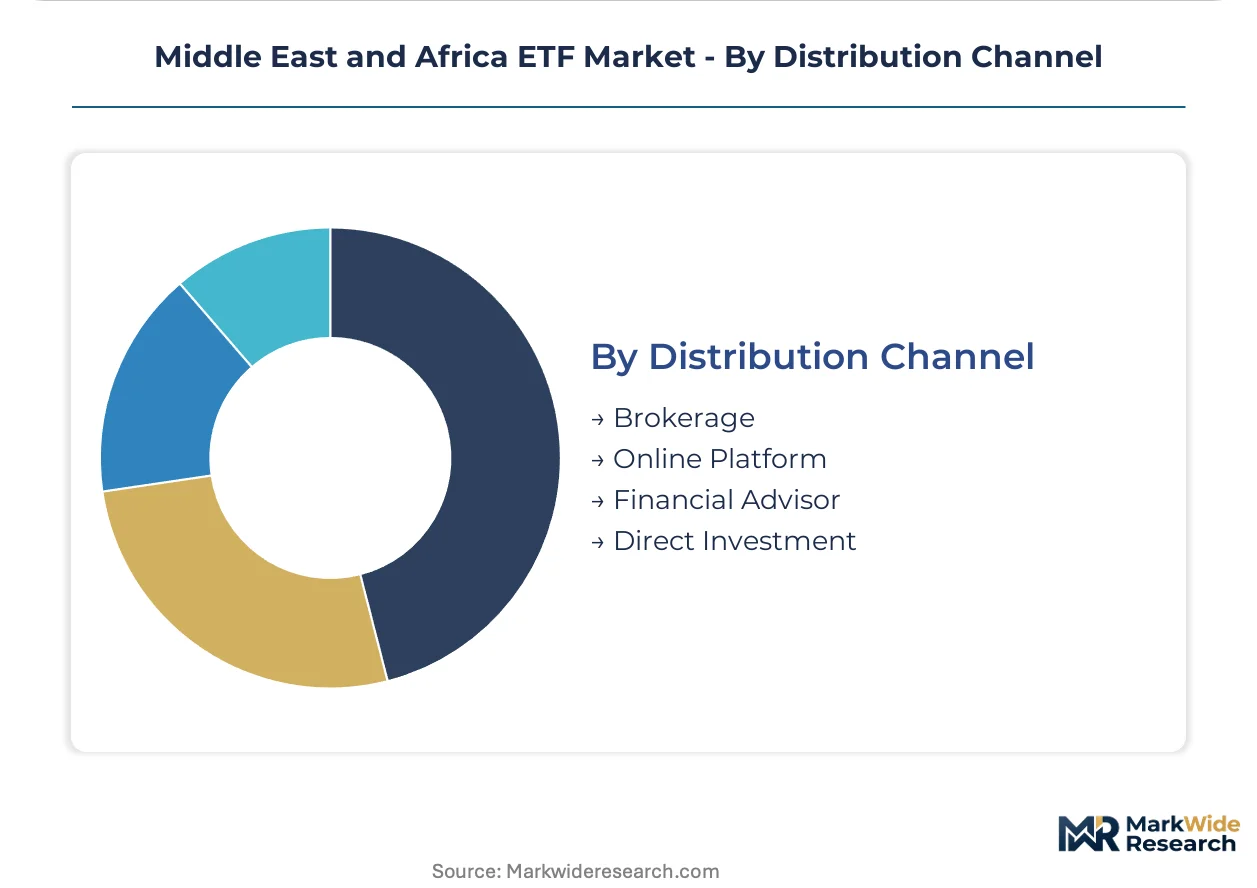
Distribution Channel:
Channel selection determines investor access economics and regulatory compliance scope.
- Brokerage:Executes exchange-traded transactions with intraday pricing transparency through licensed members of Tadawul, DFM, and Johannesburg Stock Exchange. UAE and Saudi retail investors concentrate here, driven by Securities and Commodities Authority and Capital Market Authority liberalization of direct market access.
- Online Platform:Enables direct subscription without advisor intermediation through mobile and web interfaces. South Africa's Financial Sector Conduct Authority retail access rule changes accelerate adoption, with Nigerian platforms piloting similar infrastructure.
- Financial Advisor:Provides suitability-screened recommendations with fee structures reflecting advice layers.
- Direct Investment:Permits institutional-sized creation unit transactions with authorized participants.
Brokerage handles current volume; Online Platform shows steepest expansion trajectory as regulatory frameworks permit direct retail subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign wealth funds and pension schemes across the Gulf Cooperation Council concentrate institutional demand for Sharia-compliant ETF structures, while South Africa's retail liberalization accelerates brokerage platform adoption. Regulatory harmonization between Riyadh, Dubai, and Johannesburg financial centers is reshaping cross-border fund distribution mechanics.
Saudi Arabia
Tadawul liquidity depth and domestic institutional asset growth drive equity ETF demand. The Capital Market Authority revised foreign investor disclosure thresholds in its 2024 ETF rulebook, shifting benchmark composition authority toward domestic managers. Riyadh anchors primary market creation through local custody infrastructure at major Gulf banks.
United Arab Emirates
UAE pension schemes and sovereign wealth vehicles concentrate demand for large-cap equity replication. The Securities and Commodities Authority streamlined fund registration frameworks for Islamic finance structures. Dubai International Financial Centre hosts market-making depth for Gulf equity benchmarks through authorized participant networks.
South Africa
Retail platform expansion and pension scheme ESG mandates fragment institutional procurement across screened index variants. The Financial Sector Conduct Authority advances direct subscription rules that bypass advisor intermediation. Johannesburg Stock Exchange liquidity supports mid-cap ETF creation for frontier market exposure.
Nigeria
Demutualization of exchange infrastructure and authorized participant network gaps constrain primary market development. The Securities and Exchange Commission's modernization program enables ETF primary market infrastructure currently lacking creation basket mechanics. Lagos financial district pilots digital distribution platforms for direct retail access.
Qatar
Sukuk supply concentration and sovereign issuance rollover risks shape fixed income ETF construction. The Qatar Financial Centre Regulatory Authority aligns disclosure standards with Gulf Cooperation Council harmonization initiatives. Doha commercial banking clusters develop Sharia-compliant creation basket legal frameworks for regional cross-listing.
Middle East and Africa ETF Market Competitive Landscape
Platform scale expansion dominates the current landscape as global asset managers anchor liquidity through iShares-type infrastructure while local specialists defend position through Sharia certification speed. The vendor base splits between consolidated global platforms with creation basket scale and fragmented domestic specialists with regulatory proximity. Three archetypes occupy distinct competitive positions: Gulf-based Islamic finance specialists, international index platform operators, and regional bank-affiliated custody providers. M&A activity concentrates among bank-affiliated asset managers seeking vertical integration into market-making infrastructure, while strategic partnerships between global index providers and local Sharia boards accelerate product development timelines.
Among Saudi-based specialists, Al Bilad Capital and Alinma Investment exemplify the Islamic finance archetype through proximity to Capital Market Authority certification processes. HSBC Saudi occupies a position bridging international custody infrastructure with local exchange access. BlackRock represents the global platform scale model, anchoring liquidity creation through authorized participant networks across multiple Gulf exchanges.
| Leading Market Players |
|---|
| Al Bilad Capital |
| Alinma Investment |
| Al Rayan Qatar |
| HSBC Saudi |
| Alkhabeer Capital |
| BlackRock |
| Invesco |
| Franklin Templeton |
| Xtrackers |
| Others |
Supply & Pricing Matrix
Institutional procurement consolidation among Gulf sovereign wealth funds and South African pension schemes is compressing expense ratio tolerances, forcing fund manufacturers to absorb creation basket costs or cede primary market share to competitors with deeper authorized participant networks.
Pricing Analysis
Volume concentrates in large-cap equity replication with razor-thin basis point spreads, while margin protection sits with specialized Sharia-compliant structures carrying certification premiums. Three-tier pricing separates institutional creation units from retail brokerage execution and direct platform subscription levels. Pricing pressure stems from iShares-type platform scale anchoring Gulf equity benchmark liquidity at sub-15 basis point expense ratios. Retail platforms show highest price sensitivity; sovereign wealth funds prioritize liquidity depth over fee minimization.
Supply Chain Analysis
Authorized participant capacity rests on balance sheet scale at Saudi National Bank, First Abu Dhabi Bank, and Standard Bank South Africa to handle multi-jurisdictional in-kind creation baskets. Critical inputs include Tadawul and DFM liquidity data feeds, Sharia board certification opinions, and local custody infrastructure at Riyadh and Dubai financial centers. Single-source vulnerability concentrates in Gulf bank market-making commitment for mid-cap and frontier exposure. Distribution runs through brokerage members of Tadawul, DFM, and Johannesburg Stock Exchange with emerging direct platform disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authorized participant scarcity props pricing power for banks with creation basket scale, ceding ground only to global platforms with cross-border liquidity anchoring capacity.
For Market Incumbents: Deepen Sharia certification speed advantages through exclusive advisory relationships with Riyadh and Dubai-based Sharia boards to outpace global platform product development timelines. Expand local custody infrastructure in Johannesburg and Lagos to preempt emerging market entrants from capturing frontier exposure creation economics. Vertical integration into digital distribution platforms defends against fintech disintermediation of retail subscription flows. For New Entrants and Emerging Players: South Africa's Financial Sector Conduct Authority direct subscription rule changes open a window for mobile-first platforms to bypass incumbent brokerage relationships and capture retail ETF procurement. Target Nigeria's demutualizing exchange infrastructure with authorized participant network partnerships that address current primary market gaps. Lead with ESG-screened index variants to differentiate from commodity Gulf equity replication saturated by incumbents. For Investors and Strategic Acquirers: The window for entry favors bank-affiliated asset managers with captive custody and market-making infrastructure across multiple Gulf exchanges. Long-term viability hinges on regulatory proximity to Capital Market Authority and Securities and Commodities Authority certification processes rather than scale alone. Watch for Sharia board approval timeline compression as signal of competitive moat erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Sharia Board Partnership Expansion | Exclusive advisory relationships with Riyadh and Dubai Sharia boards compress product development cycles below global platform benchmarks. |
| Cross-Border Authorized Participant Network | Multi-jurisdictional creation basket capacity at Saudi National Bank and First Abu Dhabi Bank anchors liquidity across Tadawul and DFM. |
| Digital Distribution Platform Launch | Direct retail subscription infrastructure bypasses Johannesburg Stock Exchange brokerage intermediation and captures South African platform shift. |
| ESG-Screened Index Development | Parallel calculation engines for thermal coal and alcohol exclusions meet South African pension scheme procurement fragmentation. |
| Nigeria Exchange Infrastructure Investment | Authorized participant network development addresses Securities and Exchange Commission demutualization program primary market gaps. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ETF product heads at Gulf bank asset managers, Sharia advisory board members, South African pension scheme investment officers, and Johannesburg Stock Exchange liquidity providers. Capital Market Authority rulebooks, Securities and Commodities Authority registration frameworks, and Financial Sector Conduct Authority conduct standards provided regulatory boundary conditions. Bottom-up asset flow analysis triangulated against top-down AUM estimates across the analysis window.
Segment-level modeling addressed asset class, investment strategy, fund size tier, and distribution channel dimensions with regional regulatory cluster differentiation between Gulf Cooperation Council and sub-Saharan African frameworks. CAGRs derived from trend extrapolation of institutional allocation shifts and retail platform adoption curves, cross-checked against sovereign wealth fund disclosure patterns and pension scheme mandate specifications.
The model assumes a particular technology adoption path; alternative pathways for blockchain-based settlement infrastructure would alter the outlook for collateral requirements and market-making economics. Forecasts reflect assumptions regarding Sharia certification timeline stability and Gulf bank balance sheet commitment to authorized participant functions. A small set of triggers—regulatory harmonization acceleration, fintech platform licensing, and sukuk supply disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Stockbroking Market