
 Aquarium Hydrometers Market | 2026-2036
Aquarium Hydrometers Market Size, Share, and Industry Trends Forecast 2026-2036
Aquarium Hydrometers Market Outlook
Bluetooth-enabled sensor miniaturization is fragmenting the traditional mechanical hydrometer landscape, pushing manufacturers toward hybrid digital-mechanical platforms. Tropical Marine Centre Ltd. leverages its UK manufacturing base to sustain premium analog exports across European specialty channels. Petco competes through vertical control over in-store water testing services that anchor repeat hydrometer purchases. American Marine differentiates via reef-specific calibration protocols that dominate North American saltwater hobbyist forums.
An aquarium hydrometer measures specific gravity and salinity in aquatic environments, typically employing a weighted glass float with a calibrated stem or digital conductivity sensors accurate to 0.001 specific gravity units; the instrument enables precise marine ecosystem management for coral viability and fish health. Digital and refractometer product types command the highest margin pools as hobbyists trade up from basic analog wands, while mechanical technology persists in entry-level segments where price sensitivity remains acute. Laboratory end users increasingly specify optical refractometers with automatic temperature compensation, creating a bifurcation between professional-grade accuracy demands and consumer convenience preferences.
The US Consumer Product Safety Commission and EPA influence material restrictions on lead-weighted glass designs, while the EU REACH framework governs chemical composition in devices sold across European distribution channels. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS calibration standards that shape import access for non-domestic manufacturers. Stakeholders must monitor evolving state-level aquarium trade regulations and decide whether to pursue multi-certification strategies or geographic specialization.
Market Dynamics
Bluetooth-enabled sensor miniaturization is fragmenting traditional mechanical hydrometer architectures, forcing manufacturers to rebuild product platforms around hybrid digital-mechanical designs while managing the cost compression these technologies impose on legacy analog margins.
Growth Catalysts
- Home reef-keeping sophistication:Hobbyist aquarists in the United States and Germany are upgrading from basic wands to digital conductivity sensors with automatic temperature compensation, expanding the addressable premium tier.
- REACH chemical compliance:The EU framework's material restrictions on lead-weighted glass designs are accelerating R&D investment in alternative calibration materials that command higher unit economics.
- JIS calibration standards:Japan's METI enforcement creates import barriers that protect domestic manufacturers while incentivizing foreign players to localize production for market access.
Market Restraints
- Silicon sensor cost volatility:Miniaturized digital components face input price instability from semiconductor foundry concentration in East Asia, compressing margins on mid-tier hybrid products.
- Lead-weighted glass phase-out:EPA and Consumer Product Safety Commission material restrictions force redesign of legacy mechanical hydrometers without equivalent low-cost substitutes.
- Refractometer substitution threat:Optical refractometers with automatic temperature compensation are capturing laboratory end-use specifications previously served by digital hydrometers.
Strategic Opportunities
- Underpenetrated Southeast Asian hobbyist markets:Singapore and Thailand exhibit rising marine aquarium ownership rates without established premium hydrometer distribution, creating first-mover channel openings.
- Subscription calibration services:Digital sensor drift creates recurring revenue potential through mail-in recalibration programs anchored to initial hardware sales.
- EU Green Deal circularity requirements:Upcoming battery and electronics disposal mandates favor modular sensor designs that manufacturers can position as future-compliant.
Industry Challenges
- Cross-platform firmware integration:Hybrid digital-mechanical products require software teams to maintain compatibility across iOS, Android, and proprietary aquarium controller ecosystems simultaneously.
- ISO 17025 laboratory accreditation timelines:Professional-grade optical refractometer manufacturers face 12-18 month certification delays that gate access to institutional procurement channels.
- Legacy analog inventory stranding:Distributors holding mechanical hydrometer stock face write-down pressure as Bluetooth-enabled alternatives capture shelf space in specialty retail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquarium Hydrometers Market |
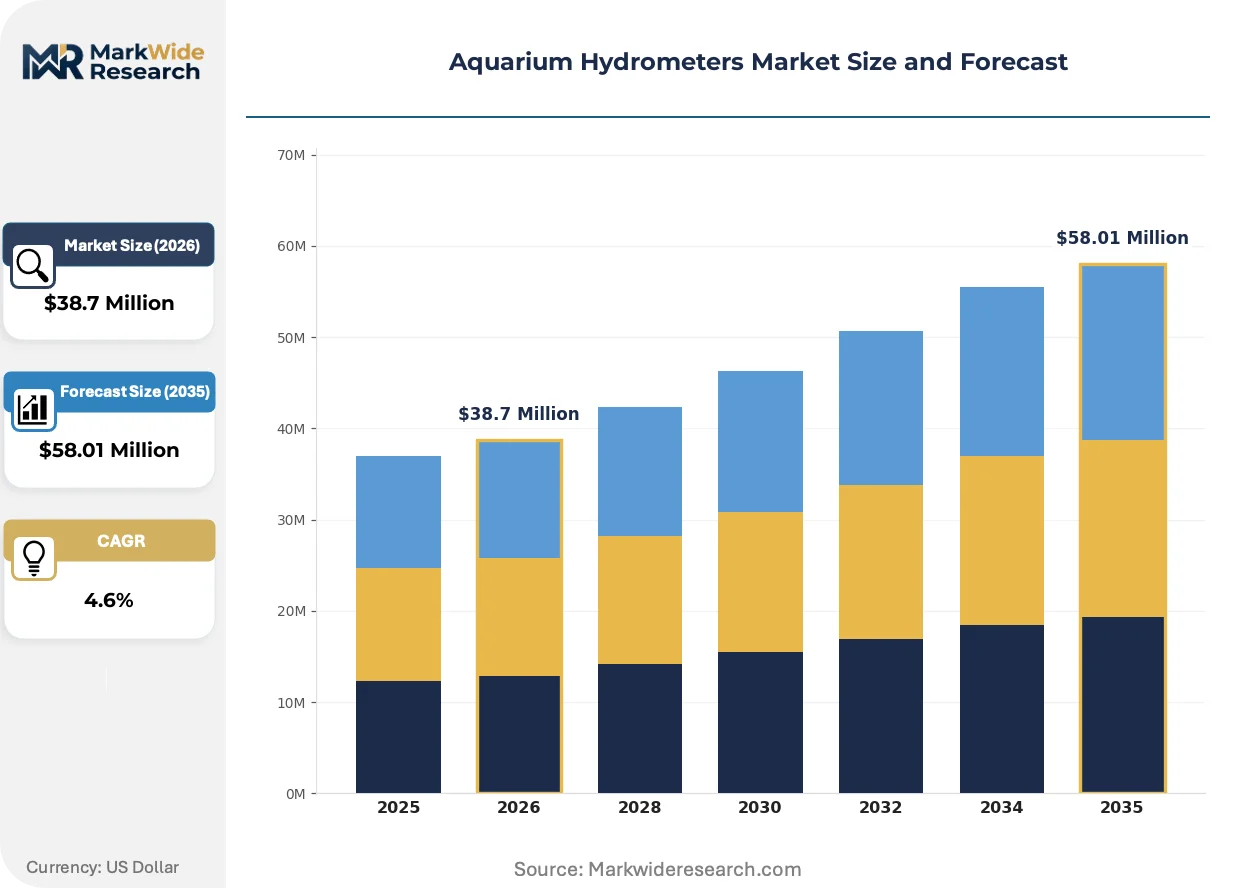
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $58.01 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Refractometer, Salinity Meter Technology: Optical, Electrical, Mechanical, Hybrid End User: Hobbyists, Commercial Aquariums, Laboratories, Research Institutions Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Tropical Marine Centre Ltd., PetSmart, Petco, Petland, Juwel Aquarium, Tetra, Tropic Marin, American Marine, Bulk Reef Supply, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquarium Hydrometers Market Strategic Shifts
Sensor fusion and connectivity protocols are redefining how aquarists monitor water chemistry, collapsing the distinction between standalone measurement tools and integrated ecosystem management platforms.
Conductivity-based microsensors with Bluetooth Low Energy transmission are digitizing the traditional hydrometer function into continuous data streams rather than discrete manual readings. Advanced hobbyists in North America and Japan are adopting these modules at accelerating rates, replacing weekly manual testing with smartphone-alerted threshold monitoring. This shift is digitizing product architecture away from standalone instruments toward distributed sensor networks that anchor recurring software subscriptions.
REACH Annex XVII restrictions on heavy metals in consumer products are forcing redesigns of traditional weighted-glass float mechanisms across European distribution channels. Manufacturers must substitute lead ballast with tungsten or composite materials that alter buoyancy calibration curves and require stem re-engineering. Saltwater hobbyist forums in Germany and the Netherlands are tracking which brands complete material transitions first, creating temporary competitive sorting.
Specialty retailers are unbundling water testing services from hardware sales, converting hydrometer purchases from transactional endpoint to relationship anchor. Petco's in-store testing stations and independent reef shops in Florida and California now use complimentary salinity verification to drive repeat traffic and capture email addresses for digital sensor upsell campaigns. This service-layer attachment is most visible in United States coastal metros where marine aquarium density supports standalone retail economics.
Aquarium Hydrometers Market Segmentation
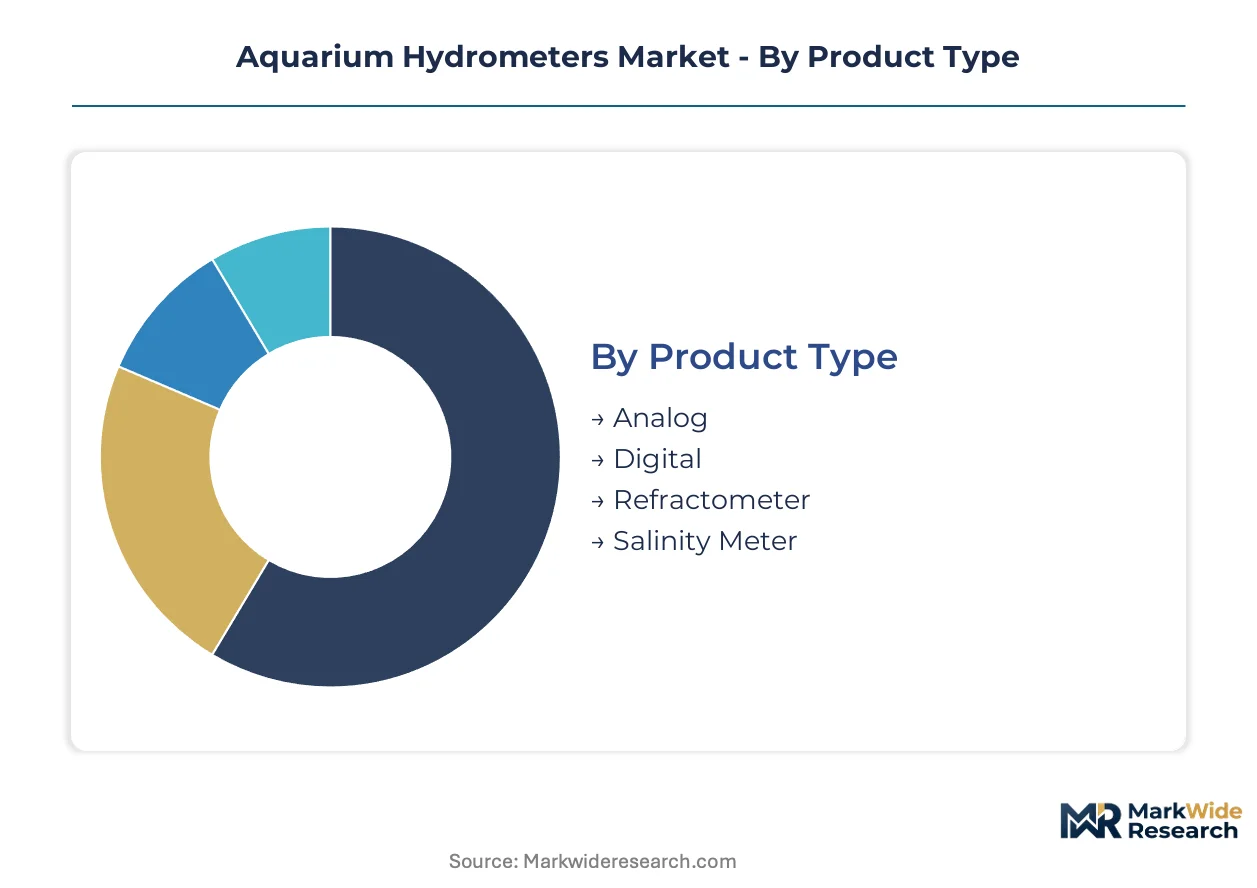
Aquarium hydrometer manufacturers must navigate divergent accuracy requirements and price sensitivities across buyer types. Product architecture choices—mechanical versus digital, standalone versus networked—determine margin structure and channel access.
Product Type:
The maturity spectrum spans legacy mechanical designs to emerging sensor platforms with embedded connectivity.
- Digital:Microsensor arrays with Bluetooth Low Energy transmission enable continuous salinity monitoring via smartphone dashboards. Demand concentrates among advanced reef-keepers in the United States and Japan who maintain SPS coral colonies requiring stability within 0.001 specific gravity units. Premium positioning supports hardware-plus-subscription revenue models.
- Refractometer:Optical instruments with automatic temperature compensation deliver laboratory-grade accuracy without calibration drift. Commercial aquariums in Germany and public institutions in Japan specify these for regulatory documentation requirements.
- Analog:Weighted glass float mechanisms serve entry-level hobbyists where price thresholds dominate purchase decisions.
- Salinity Meter:Handheld conductivity probes with digital readouts bridge casual and serious segments.
Digital retains volume leadership; refractometer holds the steepest expansion curve.
Technology:
Cost tier stratification separates precision instrumentation from mass-market tools.
- Hybrid:Dual-mode platforms combine mechanical redundancy with digital logging, appealing to serious hobbyists in coastal United States metros who demand backup verification during equipment failures. Saltwater aquarium forums in Florida and California actively debate hybrid reliability versus pure digital alternatives.
- Optical:Prism-based refractometry with ATC circuits commands professional-grade price points.
- Electrical:Conductivity cell designs face silicon foundry input volatility.
- Mechanical:Float-stem architectures confront EPA and REACH material restrictions on lead ballast.
Mechanical retains installed-base dominance; hybrid gains share fastest among replacement purchases.
End User:
Application intensity varies dramatically across customer types, from casual home tanks to institutional research systems.
- Hobbyists:The fastest-expanding buyer segment drives upgrade cycles from basic wands to connected sensors. German and United States aquarists increasingly demand smartphone integration and cloud-based parameter logging.
- Commercial Aquariums:Public institutions and large private collections require calibrated, documented accuracy for veterinary compliance and insurance purposes.
- Laboratories:Research facilities specify ISO 17025 traceable instruments with certificate of calibration.
- Research Institutions:Academic marine biology programs prioritize optical refractometers for publication-grade data integrity.
Hobbyists represent the steepest volume expansion; laboratories maintain the most rigid specification barriers.
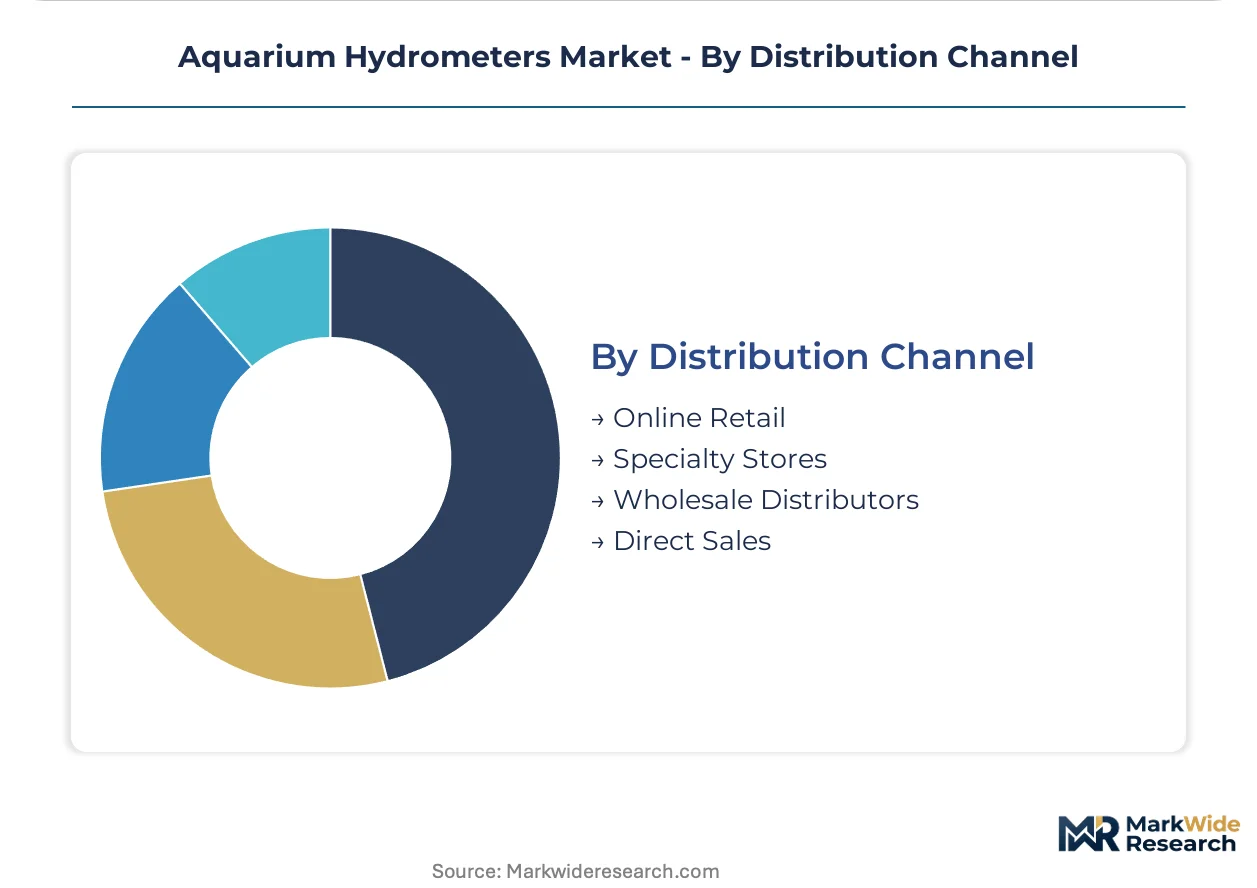
Distribution Channel:
Customer type determines channel preference, with digital-native buyers diverging from traditional retail patterns.
- Online Retail:Amazon and specialty aquarium e-commerce platforms capture sensor-savvy hobbyists who research specifications independently. United States and German buyers increasingly bypass brick-and-mortar for direct-to-consumer digital hydrometer brands.
- Specialty Stores:Independent reef shops in Florida and California anchor community relationships through complimentary water testing that drives hardware attachment.
- Wholesale Distributors:Bulk procurement channels serve commercial aquarium chains and institutional buyers with volume pricing.
- Direct Sales:Manufacturer-direct relationships dominate laboratory and research institution procurement.
Online retail captures the steepest growth trajectory; specialty stores retain loyalty-driven repeat purchase density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision analog hydrometers to hobbyist markets in the Netherlands and Scandinavia, while Japanese digital sensor producers supply North American reef-keeping specialists through direct e-commerce channels.
United States
Coastal metro aquarists in Florida and California drive premium digital sensor adoption for SPS coral maintenance. EPA material restrictions on lead-weighted glass accelerate domestic R&D into tungsten ballast alternatives. Miami and Los Angeles host the densest specialty retail networks where in-store water testing anchors hardware sales.
Germany
Advanced hobbyists in Hamburg and Berlin upgrade to optical refractometers with automatic temperature compensation for regulatory-grade documentation. REACH Annex XVII heavy metal restrictions force rapid redesign of traditional float mechanisms. The Ruhr industrial corridor concentrates precision glass engineering suppliers serving hydrometer calibration houses.
Japan
Tokyo and Osaka metropolitan aquarists demand smartphone-integrated conductivity sensors for continuous parameter monitoring. METI enforces JIS calibration standards that protect domestic manufacturers from import competition. Nagoya hosts specialized sensor foundries supplying miniaturized Bluetooth modules to regional hydrometer assemblers.
United Kingdom
Reef-keeping communities in London and Bristol transition from mechanical wands to hybrid digital-mechanical platforms for backup redundancy. The UK Environment Agency tracks aquarium trade compliance with waste electronics directives. Manchester specialty distributors serve the European export market from bonded warehousing facilities.
Singapore
Rising marine aquarium ownership in private residences and commercial display facilities creates first-mover opportunities for premium hydrometer distribution. The city-state's national environmental agency enforces strict import documentation for electronic water quality instruments. Jurong industrial estates host regional logistics hubs serving Southeast Asian hobbyist markets.
Aquarium Hydrometers Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market retailers leverage vertical control over in-store services to anchor repeat purchases, while engineering-focused manufacturers differentiate through calibration precision and reef-specific protocols. Three archetypes dominate: mass-market retailers with service-layer attachment, precision instrumentation specialists with laboratory accreditation, and digital-native entrants with subscription revenue models. Capacity expansion in sensor miniaturization and geographic licensing agreements represent the primary competitive vectors reshaping market boundaries.
Among UK-based precision manufacturers, Tropical Marine Centre Ltd. exemplifies the analog-specialist archetype sustained by premium export positioning across European specialty channels. American Marine occupies a position within the reef-specific calibration tier, anchoring North American saltwater hobbyist forum influence. Petco represents the channel-control archetype, leveraging in-store water testing infrastructure to drive repeat hydrometer purchases and digital sensor upsell campaigns.
| Leading Market Players |
|---|
| Tropical Marine Centre Ltd. |
| PetSmart |
| Petco |
| Petland |
| Juwel Aquarium |
| Tetra |
| Tropic Marin |
| American Marine |
| Bulk Reef Supply |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundry concentration in East Asia determines both pricing tier spreads and supply chain shape across the aquarium hydrometer market. Silicon sensor cost volatility compresses margins on mid-tier hybrid products while forcing manufacturers to absorb input fluctuations or pass them downstream.
Pricing Analysis
Next-generation Bluetooth-enabled sensors command hardware-plus-subscription premiums against prior-generation mechanical wands and current-generation hybrid platforms. Three-tier pricing structure across premium, standard, and economy levels separates digital conductivity arrays with cloud logging from entry-level analog floats. Price differentiation rests on calibration precision and smartphone integration depth. Cost compression in mid-tier hybrids is intensifying because silicon foundry utilization rates fluctuate. Entry-level hobbyists in Southeast Asia exhibit acute price sensitivity; research institutions in Japan show minimal elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for sensor-dependent manufacturers. Component sourcing concentrates in Taiwan, South Korea, and Japan for miniaturized conductivity cells and Bluetooth Low Energy modules. Raw material dependencies include tungsten ballast substitutes, precision glass tubing, and semiconductor-grade silicon wafers. Single-source vulnerability in East Asian foundry capacity threatens production continuity for digital product lines. Distribution runs through bonded warehousing in Manchester and direct e-commerce platforms serving coastal United States metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aquarium hydrometer market sits at a cyclical recovery phase driven by home reef-keeping sophistication rebounding post-pandemic. Upgrade cycles from basic wands to connected sensors justify capacity positioning ahead of demand inflection.
For Market Incumbents: Pre-empt refractometer substitution threats by accelerating hybrid platform certification under ISO 17025 laboratory standards. Anchor channel control through captive in-store water testing infrastructure that locks repeat purchase behavior. Deepen backward integration into precision glass engineering to secure tungsten ballast supply chains against REACH Annex XVII compliance deadlines. For New Entrants and Emerging Players: Singapore and Thailand hobbyist markets offer first-mover distribution openings without entrenched premium brand presence. Target commercial aquarium procurement channels in Southeast Asia where regulatory documentation requirements favor optical refractometer specifications. Pursue direct-to-consumer digital sensor launches via Amazon and specialty e-commerce platforms to bypass legacy retail gatekeepers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors digital-native entrants with recurring revenue models over analog-dependent legacy manufacturers. Long-term viability hinges on subscription calibration service attachment rates and firmware ecosystem integration breadth. Monitor Bluetooth sensor adoption velocity among SPS coral hobbyists in Florida and California as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Certification | ISO 17025 accreditation unlocks laboratory and institutional procurement channels previously gated. |
| Subscription Calibration Launch | Mail-in recalibration programs anchored to hardware sales generate recurring revenue streams. |
| Modular Sensor Design Transition | EU Green Deal circularity compliance positions manufacturers ahead of battery disposal mandates. |
| Southeast Asian Distribution Buildout | Singapore and Thailand channel openings capture rising marine aquarium ownership without incumbent saturation. |
| Tungsten Ballast R&D Investment | REACH Annex XVII material transition secures European market access against lead-weighted glass phase-out. |
Study Parameters
Initial hypotheses were tested against primary input from reef shop owners, aquarium equipment procurement managers, marine biology research coordinators, and specialty distributor sales directors and refined through secondary validation. Stakeholder interviews combined with customs trade data, EPA regulatory filings, JIS standard documentation, and aquarium hobbyist forum sentiment analysis enabled bottom-up and top-down triangulation across market sizing exercises.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, technology tier, end-user application intensity, and regional regulatory cluster. CAGRs were derived from installed-base replacement curves and upgrade-rate assumptions calibrated against historical analog-to-digital transitions. Forecast inputs incorporated semiconductor foundry capacity utilization projections and REACH compliance timeline probabilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native entrants with venture-backed capacity expansion would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Stick Vacuum Cleaner Market
Household Items
Germany Digital Showers Market
Household Items
Dryer Sheets Market
Household Items
Brush Cover Market
Household Items
Washing Machine Cleaner Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Smart Spin Mop Market
Household Items
Powered Lawn Mowers Market
Household Items
Global Humidifier Market
Household Items
Residential Air Purifiers Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Smart Bathroom Market
Household Items
Memory Foam Market
Household Items
Permanent Marker Market
Household Items
Multi Pocket Holders Market
Household Items
Fan Market