
 Digital Moisture Analyzer Market | 2026-2036
Digital Moisture Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Moisture Analyzer Market Insights
Buyer concentration in food processing is restructuring as multinational manufacturers consolidate quality control operations into centralized testing hubs. Mettler-Toledo International Inc. leverages its Swiss precision weighing heritage to dominate high-throughput laboratory installations. Sartorius AG anchors its position through deep integration with biopharmaceutical workflow automation. Thermo Fisher Scientific Inc. competes by bundling moisture analyzers with broader analytical instrument portfolios.
A digital moisture analyzer measures the water content of solids, liquids, and gases using thermal, electrical, or spectroscopic methods, typically achieving resolution of 0.001% moisture and operating across temperature ranges from 40°C to 200°C depending on the heating module. Its primary industrial purpose is ensuring product stability, preventing microbial growth, and maintaining compliance with shelf-life specifications in regulated manufacturing environments. Infrared analyzers lead the product type landscape due to their non-destructive testing capability and speed, while microwave analyzers represent the fastest-growing category in bulk material handling applications. Quality control applications generate the largest revenue pool, though production monitoring is gaining share as manufacturers shift from offline laboratory testing to in-line process integration.
FDA process analytical technology initiatives and EPA good laboratory practice standards shape instrument validation protocols and documentation requirements for moisture analyzers deployed in regulated US facilities. ISO 9001 quality management frameworks and EU REACH chemical safety regulations further constrain material compatibility and calibration traceability for equipment sold into European pharmaceutical and food sectors. Stakeholders must monitor evolving electromagnetic compatibility standards for wireless-enabled analyzers as factory digitization accelerates.
Market Dynamics
The transition from offline laboratory testing to in-line process integration is compressing equipment replacement cycles and forcing vendors to reconfigure service architectures around continuous monitoring rather than periodic calibration.
Growth Catalysts
- FDA Process Analytical Technology:Updated validation guidelines for real-time measurement systems are accelerating pharmaceutical manufacturer investment in in-line moisture analyzers for continuous process verification.
- Food processing automation:Multinational manufacturers are consolidating quality control operations into centralized testing hubs equipped with high-throughput thermal analysis systems.
- Biopharmaceutical workflow integration:Automated moisture testing is becoming embedded within sterile manufacturing lines to prevent microbial growth and ensure shelf-life compliance.
Market Restraints
- Heating module material costs:Ceramic and quartz infrared emitter supply concentrates in German and Japanese specialty component suppliers, creating input price volatility.
- Calibration traceability requirements:EU REACH chemical safety regulations constrain compatible materials for European pharmaceutical and food sector equipment, extending certification timelines.
- Electromagnetic compatibility compliance:Factory digitization is accelerating wireless-enabled analyzer deployment, yet evolving IEC standards for industrial wireless create pre-market validation friction.
Strategic Opportunities
- Bulk material handling applications:Microwave analyzer technology is penetrating mining and agricultural commodity processing in Australia and Brazil where rapid non-destructive testing reduces handling losses.
- EU Green Deal manufacturing incentives:Sustainability-linked capital equipment subsidies are redirecting pharmaceutical and food processor procurement toward energy-efficient thermal analysis systems.
- Spectroscopic-electrical convergence:Near-infrared and capacitance measurement fusion is enabling multi-parameter analyzers that simultaneously capture moisture, density, and composition data.
Industry Challenges
- Metrology technician scarcity:Pharmaceutical manufacturers in Germany's Rhine-Main corridor report difficulty recruiting personnel qualified for ISO 17025 calibration procedure execution.
- Legacy system integration:Food processors with existing SCADA architectures face protocol incompatibility when retrofitting wireless moisture sensors into brownfield production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Moisture Analyzer Market |
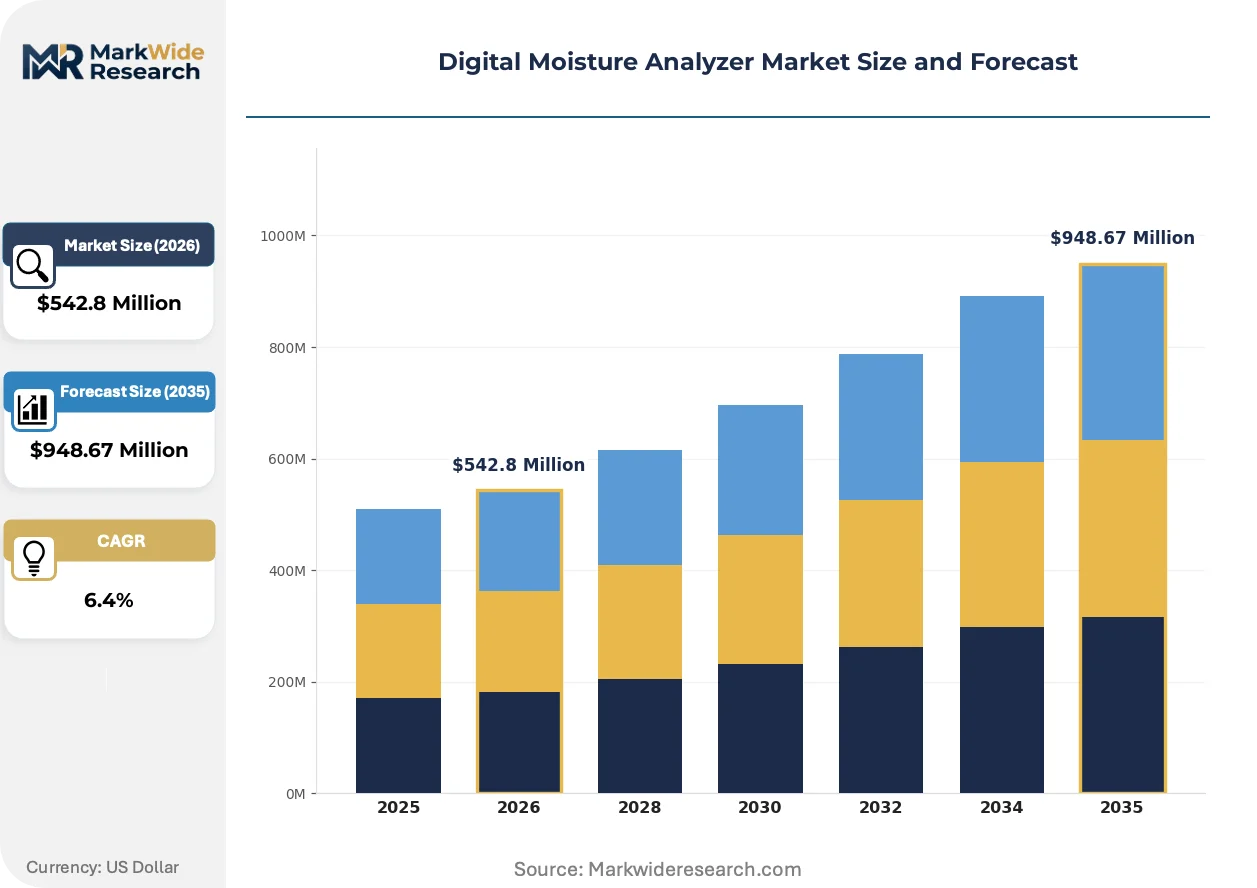
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $948.67 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitance Meters, Infrared Analyzers, Microwave Analyzers, Hygrometers End User: Agriculture, Food Processing, Pharmaceuticals, Wood Industry Technology: Digital, Analog, Wireless, Hybrid Application: Quality Control, R&D, Production Monitoring, Storage Management |
| Companies Covered | Mettler-Toledo International Inc., Sartorius AG, Thermo Fisher Scientific Inc., A&D Company, Shimadzu Corporation, Ametek Inc., Kett Electric Laboratory, Michell Instruments Inc., PCE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Moisture Analyzer Market Trends and Innovations
Equipment architecture is converging around modular platforms that separate measurement cores from application-specific sample handling, enabling faster reconfiguration across pharmaceutical, food, and chemical verticals without full system replacement.
Thermal-gravimetric analysis with integrated halogen heating is unifying precision laboratory workflows with production floor durability requirements. Pharmaceutical manufacturers in Switzerland and Germany are adopting these hybrid systems at accelerated pace. The technology is unifying previously separate R&D and quality control equipment procurement decisions into single-platform vendor relationships.
EU Medical Device Regulation (MDR) Article 10 technical documentation requirements are extending to process analytical equipment used in sterile drug manufacturing. This is forcing moisture analyzer vendors to establish notified body partnerships for conformity assessment. In-vitro diagnostic and biologic drug producers are responding by consolidating supplier qualification processes around MDR-certified equipment portfolios.
Service unbundling is separating hardware procurement from calibration and validation contracts. Pharmaceutical quality managers in the United States are negotiating standalone metrology service agreements with third-party ISO 17025 laboratories rather than captive vendor service plans. This pattern is most visible among mid-cap generic drug manufacturers seeking to reduce total cost of ownership for multi-site instrument fleets.
Digital Moisture Analyzer Market Segmentation
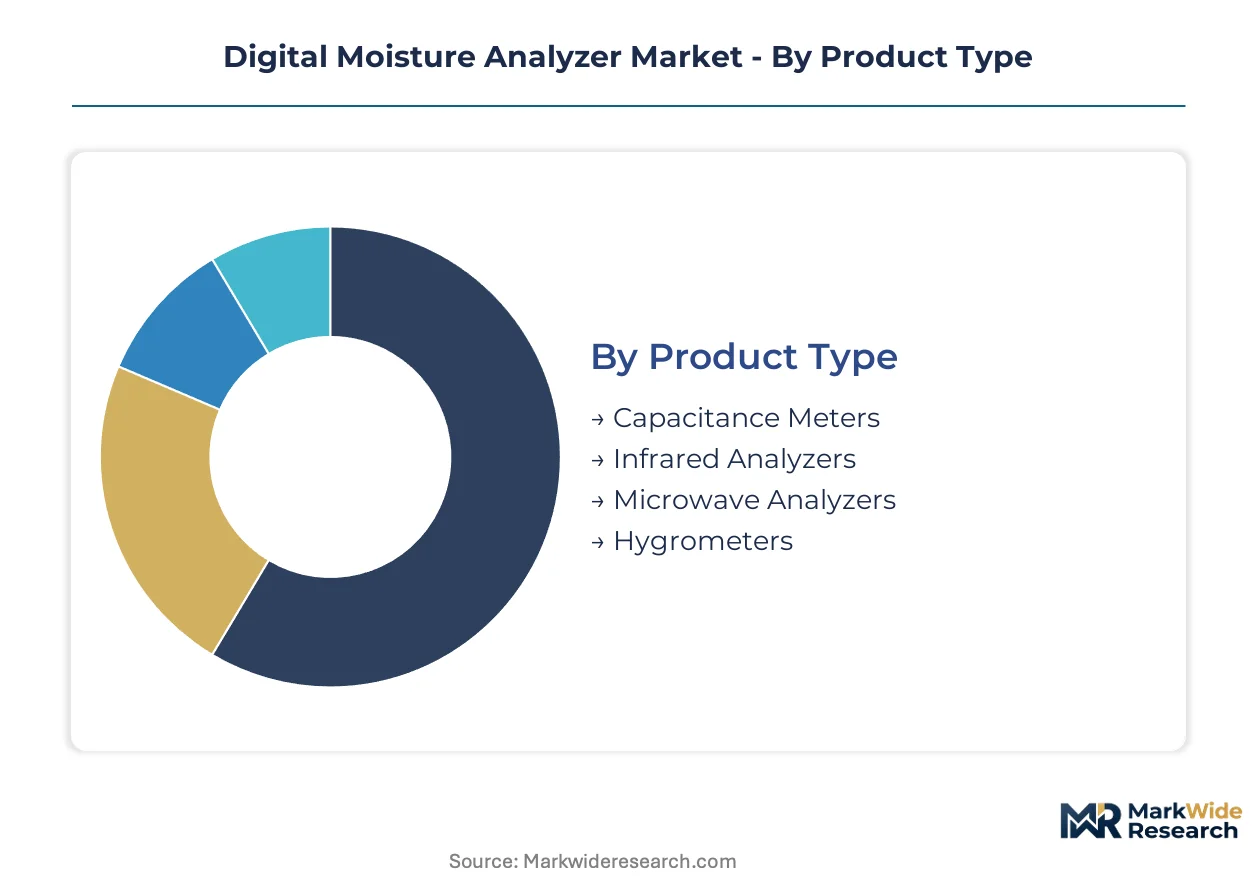
Equipment selection in moisture analysis hinges on material properties, throughput requirements, and regulatory compliance intensity. Buyers prioritize measurement precision against capital outlay, with pharmaceutical and food sectors driving specification divergence.
Product Type:
Cost tier determines procurement patterns, with premium thermal systems commanding laboratory budgets and portable units penetrating field applications.
- Infrared Analyzers:Non-destructive testing capability using halogen or ceramic emitter modules achieves resolution to 0.001% moisture. Demand concentrates in pharmaceutical quality control laboratories across Germany and Switzerland where FDA process analytical technology compliance mandates real-time verification.
- Microwave Analyzers:Bulk material penetration enables rapid testing of heterogeneous samples without grinding or preparation. Agricultural commodity processors in Brazil and Australia deploy these for grain intake monitoring to minimize handling losses and moisture spoilage.
- Capacitance Meters:Electrical property measurement suits continuous in-line installation with minimal maintenance requirements.
- Hygrometers:Relative humidity detection serves environmental monitoring in storage facilities and cleanroom operations.
Volume sits with Infrared Analyzers; growth tilts toward Microwave Analyzers.
End User:
Application maturity varies sharply, with regulated manufacturers demanding validation documentation that commodity processors often bypass.
- Pharmaceuticals:Sterile manufacturing lines require embedded moisture testing to prevent microbial growth and ensure shelf-life compliance. Rhine-Main corridor facilities around Frankfurt face ISO 17025 calibration technician scarcity that constrains deployment timelines.
- Food Processing:Centralized testing hubs at multinational manufacturers consolidate quality control operations with high-throughput thermal analysis systems. EU REACH chemical safety regulations constrain compatible materials, extending certification timelines for European installations.
- Agriculture:Grain elevators and commodity traders prioritize speed over precision for intake pricing and storage decisions.
- Wood Industry:Kiln drying operations and engineered panel manufacturing use moisture control to prevent warping and adhesive failure.
Revenue concentrates in Pharmaceuticals; expansion accelerates most quickly in Food Processing.
Technology:
Customer type shapes connectivity requirements, with large manufacturers driving digitization and smaller operators retaining basic functionality.
- Digital:Microprocessor-controlled measurement with automated calibration routines and data logging dominates new laboratory procurement. FDA validation protocols favor digital traceability for pharmaceutical submissions.
- Wireless:Factory digitization is accelerating deployment, yet evolving IEC electromagnetic compatibility standards create pre-market validation friction for industrial environments.
- Hybrid:Combined thermal-gravimetric and electrical measurement suits R&D laboratories requiring method flexibility.
- Analog:Basic pointer or display instruments persist in cost-sensitive agricultural and small wood processing operations.
Installed base favors Digital; Wireless gains share fastest among greenfield pharmaceutical facilities.
Application:
Margin structure differs by workflow integration depth, with continuous monitoring commanding service premiums over discrete testing.
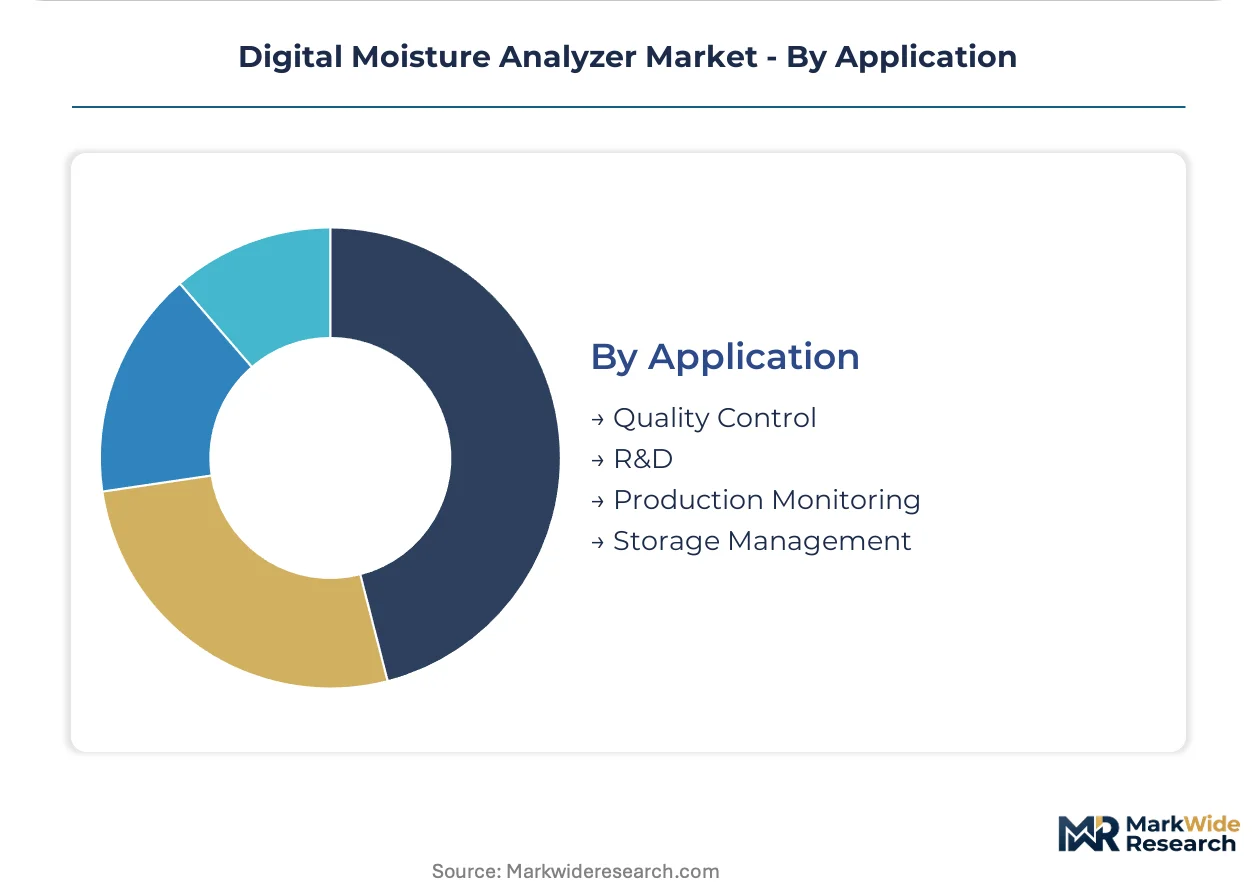
- Quality Control:Laboratory-based verification against release specifications generates the largest revenue pool. Mettler-Toledo and Sartorius dominate high-throughput installations with automated sample handling.
- Production Monitoring:In-line integration replaces offline testing, compressing equipment replacement cycles. Food processors with existing SCADA architectures face protocol incompatibility when retrofitting sensors into brownfield lines.
- R&D:Method development and formulation studies require multi-parameter capability including simultaneous density and composition capture.
- Storage Management:Warehouse environmental monitoring prevents moisture absorption during holding periods.
Quality Control holds volume; Production Monitoring exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese ceramic emitter suppliers anchor the upstream component base for thermal analysis equipment, while downstream demand clusters in pharmaceutical manufacturing corridors and agricultural commodity processing hubs across multiple continents.
United States
Pharmaceutical quality control laboratories in New Jersey and Massachusetts drive thermal-gravimetric analyzer procurement as FDA process analytical technology guidelines tighten validation requirements. EPA good laboratory practice standards shape instrument documentation protocols for regulated facilities. The Boston-Cambridge biotech corridor is consolidating multi-site instrument fleets under standalone metrology service agreements.
Germany
Rhine-Main pharmaceutical manufacturers around Frankfurt face acute ISO 17025 calibration technician scarcity that constrains deployment timelines for embedded moisture testing systems. EU REACH chemical safety regulations constrain compatible materials for equipment sold into food and pharmaceutical sectors. The Ludwigshafen chemical manufacturing cluster is redirecting procurement toward energy-efficient thermal analysis systems under EU Green Deal manufacturing incentives.
Switzerland
Precision weighing heritage supports high-throughput laboratory installations serving biopharmaceutical sterile manufacturing lines. Swissmedic oversight of sterile drug manufacturing extends EU MDR Article 10 technical documentation requirements to process analytical equipment. Basel pharmaceutical facilities are adopting hybrid thermal-gravimetric systems that unify R&D and quality control procurement decisions.
Brazil
Agricultural commodity processors deploy microwave analyzers for grain intake monitoring to minimize handling losses and moisture spoilage. ANVISA pharmaceutical regulations create parallel validation requirements for equipment serving domestic drug manufacturing. São Paulo-state grain elevators are prioritizing speed over precision for storage pricing decisions.
Australia
Mining and bulk material handling operations penetrate agricultural commodity processing with rapid non-destructive testing technology. TGA alignment with international pharmaceutical standards influences equipment qualification protocols for domestic drug manufacturing. Queensland agricultural processors are retrofitting wireless moisture sensors into existing SCADA architectures with protocol compatibility challenges.
Digital Moisture Analyzer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bulk material handling specialization and wireless-enabled factory digitization. The vendor base stratifies across Swiss-German precision instrument heritage, diversified analytical conglomerates, and Japanese electrical measurement specialists. Three archetypes dominate: precision weighing heritage firms leveraging laboratory automation, diversified life science conglomerates bundling moisture analyzers within broader portfolios, and electrical measurement specialists penetrating agricultural and industrial applications. Competitive moves concentrate on M&A for workflow automation capabilities and strategic partnerships for notified body conformity assessment under EU MDR.
Within the precision heritage tier, Mettler-Toledo International Inc. and Sartorius AG exemplify laboratory automation dominance through deep integration with biopharmaceutical workflows. Thermo Fisher Scientific Inc. occupies a diversified conglomerate position, bundling moisture analyzers within broader analytical instrument portfolios to capture integrated procurement decisions. These three anchors illustrate how competitive positioning depends on vertical scope choices between specialized precision measurement and diversified life science platforms.
| Leading Market Players |
|---|
| Mettler-Toledo International Inc. |
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| A&D Company |
| Shimadzu Corporation |
| Ametek Inc. |
| Kett Electric Laboratory |
| Michell Instruments Inc. |
| PCE Instruments |
| Others |
Pricing and Supply Chain Analysis
ISO 17025 calibration technician concentration in Germany's Rhine-Main corridor feeds directly into pricing-tier spreads, with labor-cost differentials between qualified metrology personnel and standard service technicians widening the gap between premium validation-inclusive systems and basic hardware-only procurement.
Pricing Analysis
Volume concentrates in mid-tier digital analyzers while margins accrue to premium thermal-gravimetric systems bundled with validation documentation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical equipment from food-sector standard systems and agricultural portable units. Cost compression in the standard tier intensifies because ceramic and quartz infrared emitter supply concentrates in German and Japanese specialty component suppliers. Generic drug manufacturers exhibit highest price sensitivity, while sterile biopharmaceutical producers prioritize compliance assurance over capital outlay.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical quality managers mandate multi-supplier qualification for halogen heating modules and ceramic emitter components, forcing vendors to maintain parallel relationships with German and Japanese specialty manufacturers. Upstream supply draws from Germany, Japan, and Switzerland for precision weighing sensors and thermal components. Raw material dependencies center on high-purity ceramics, quartz infrared emitters, and halogen lamp assemblies. Single-source vulnerability persists in ceramic emitter supply where two German suppliers control pharmaceutical-grade material certification. Distribution runs through direct vendor relationships for large laboratory installations and analytical instrument distributors for mid-market food processing equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU MDR Article 10 technical documentation requirements force smaller vendors without notified body partnerships toward exit or acquisition.
For Market Incumbents: Anticipate service unbundling trends by developing standalone ISO 17025 calibration capabilities independent of hardware sales, while acquiring workflow automation specialists to defend against Thermo Fisher's bundled portfolio approach. Deepen backward integration into ceramic emitter production to reduce exposure to German and Japanese supply concentration. For New Entrants and Emerging Players: Begin with microwave analyzer specialization for bulk material handling in Brazil and Australia, where agricultural commodity processors prioritize speed over precision and regulatory documentation requirements remain minimal. Target grain elevator networks with portable units through agricultural equipment distributors rather than analytical instrument channels. For Investors and Strategic Acquirers: The window for entry favors precision weighing heritage firms with existing notified body relationships and MDR-certified equipment portfolios. Mid-cap generic drug manufacturers' multi-site instrument fleets present consolidation targets for metrology service rollups. Watch FDA process analytical technology enforcement intensity as the signal for in-line analyzer demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Formation | EU MDR Article 10 compliance enables access to sterile drug manufacturing procurement. |
| Workflow Automation Acquisition | Biopharmaceutical integration requirements favor vendors with sample handling robotics. |
| Metrology Service Unbundling | Third-party ISO 17025 calibration contracts reduce total cost of ownership for generics manufacturers. |
| Bulk Material Handling Specialization | Microwave technology penetration in Brazil and Australia grain processing opens white-space expansion. |
| Hybrid Thermal-Gravimetric Platform Launch | Unified R&D and quality control procurement decisions consolidate vendor relationships in Switzerland and Germany. |
Research Methodology
Independent corroboration across plant engineers at pharmaceutical manufacturing facilities, quality control laboratory managers in food processing, procurement leads at analytical instrument distributors, and aftermarket service heads underwrites the qualitative findings. Primary interviews with biopharmaceutical workflow automation specialists and metrology technicians supplemented secondary validation through FDA process analytical technology guidance documents, EPA good laboratory practice standards, EU REACH chemical safety regulation filings, and ISO 17025 accreditation body records. Bottom-up equipment shipment analysis triangulates against top-down pharmaceutical and food sector capital expenditure patterns.
Comparable-period anchoring to historical thermal analyzer replacement cycles and laboratory automation investment waves structures the projection horizon across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, technology connectivity tier, and application workflow integration depth. CAGRs derive from equipment replacement cycle compression rates and in-line process integration adoption curves. Industry-specific forecast inputs incorporate FDA validation timeline data and EU MDR notified body certification backlog estimates.
Ceramic emitter supply disruption, ISO 17025 technician availability shocks, and FDA enforcement intensity variation are the dominant revision risks. Deviation in ceramic emitter supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Disintegration Analyzer Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Portable Infrared Digital Thermometer Market