
 Global Cashew Nutshell Liquid Market | 2026-2036
Global Cashew Nutshell Liquid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cashew Nutshell Liquid Market Foresight
Technical-grade refined liquid is collapsing the gap between industrial performance and bio-based compliance thresholds across European and North American coating formulations. Cardolite Corporation leverages its phenolic resin specialization to anchor premium pricing in automotive undercoating applications. Cat Loi Cashew Oil Production & Export Joint Stock Company dominates Vietnam's export pipeline through backward integration into shell collection networks. Palmer International differentiates via technical service depth in epoxy curing agent segments.
Cashew nutshell liquid is an anacardic acid-rich extract obtained through cold pressing or solvent extraction of cashew nut shells, typically containing 60-70% anacardic acid with cardol and cardanol as secondary phenolic constituents, serving primarily as a renewable feedstock for friction particles, epoxy modifiers, and surfactant synthesis. Refined liquid commands the deepest margin pools where polymer-grade purity enables substitution for bisphenol-A in can coatings and electrical laminates. Raw liquid retains volume leadership across Asian friction material producers who tolerate higher sediment content for brake pad applications. Concentrate grades are gaining traction in lubricant additive formulations where sulfur replacement drives reformulation mandates.
REACH restrictions on phenol-formaldehyde emissions and the EU Green Deal's bio-content thresholds are redirecting formulation R&D toward cardanol-derived novolacs across German and French coating clusters. EPA bio-preferred procurement standards and India's BIS eco-mark criteria are creating parallel compliance ladders for exporters serving multiple jurisdictions. Stakeholders must monitor feedstock security as cashew processing geography concentrates shell availability around Monrovia, Ho Chi Minh City, and Kollam corridor infrastructure.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's bio-content mandates are redirecting coating formulation R&D toward cardanol-derived novolacs, compressing the performance gap between petrochemical phenolics and renewable alternatives.
Growth Catalysts
- REACH phenol-formaldehyde restrictions:ECHA emission limits on conventional resins force German and French coating clusters to reformulate with cardanol-based novolacs for automotive undercoating compliance.
- Friction material sulfur replacement:Brake pad manufacturers in India and Vietnam adopt CNSL concentrate grades to meet tightening heavy metal content regulations without sacrificing thermal stability.
- Shell collection network density:Backward integration into Monrovia, Ho Chi Minh City, and Kollam corridor infrastructure secures raw material access for primary processors expanding refined liquid capacity.
Market Restraints
- Raw material geographic concentration:Over 70% of cashew shell supply concentrates around West African and South Asian processing clusters, exposing buyers to monsoon-driven collection disruptions.
- Polymer-grade purification cost:Achieving bisphenol-A substitution purity in can coatings requires multi-stage refining that doubles processing expense versus technical-grade output.
- Epoxy curing agent substitution threat:Bio-based polyamides from non-CNSL feedstocks compete for electrical laminate applications where color stability requirements are less stringent.
Strategic Opportunities
- Brazilian Northeast processing expansion:Underdeveloped shell collection infrastructure in Ceará and Rio Grande do Norte offers first-mover advantage for integrated refining investments.
- Lubricant additive sulfur mandates:IMO 2020 marine fuel regulations and EPA Tier 4 standards create reformulation pull for cardanol-derived friction modifiers in diesel engine oils.
- Direct-to-formulator digital channels:Specialty chemical platforms bypass traditional distributor markups for mid-volume buyers in North American epoxy modifier segments.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise bridging anacardic acid chemistry with automotive coating specifications concentrates at a handful of European and North American technical centers.
- Multi-jurisdiction certification timelines:Simultaneous EPA bio-preferred, EU Ecolabel, and BIS eco-mark approvals extend product launch cycles by 18-24 months for exporters serving multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cashew Nutshell Liquid Market |
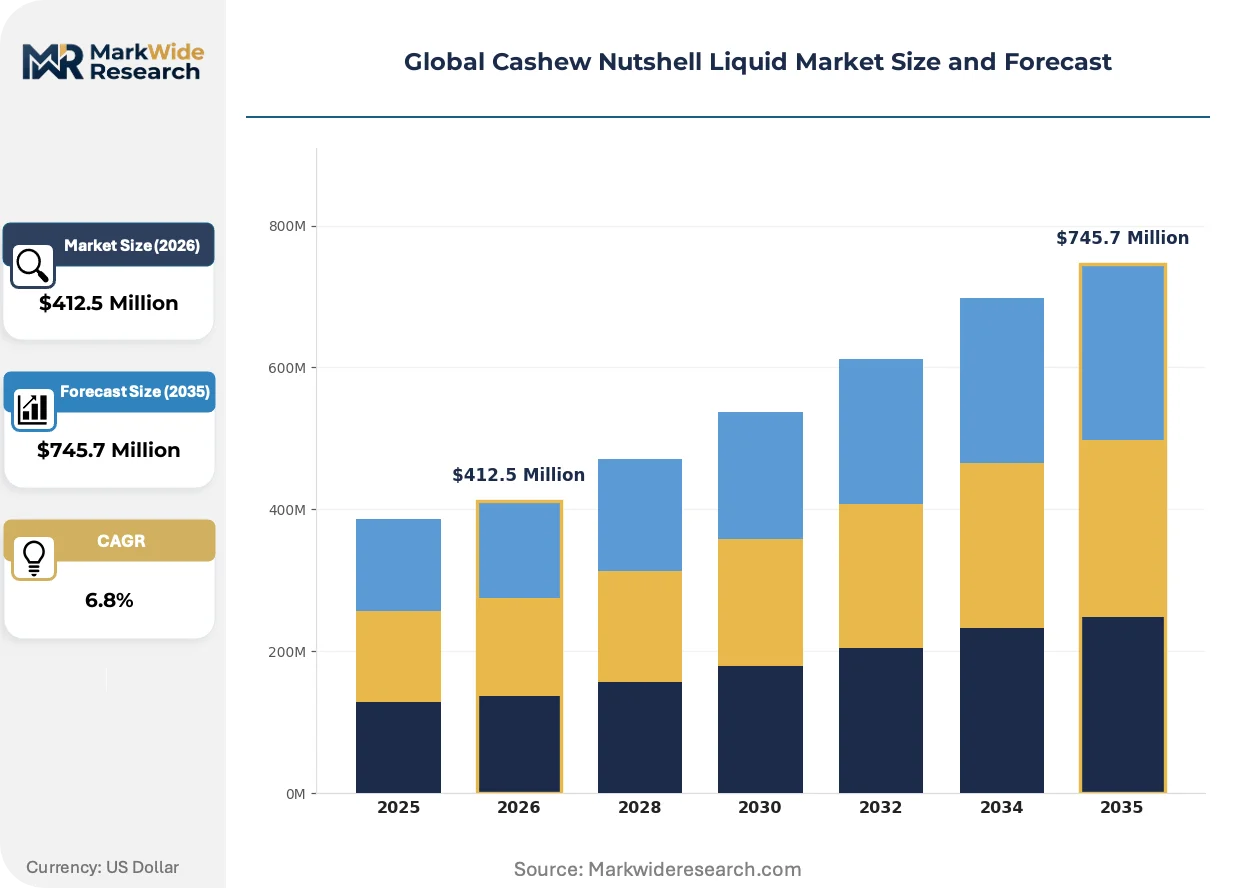
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Liquid, Refined Liquid, Semi-Refined Liquid, Concentrate, Others Application: Coatings, Adhesives, Resins, Inks, Insulation Materials, Lubricants End User Industry: Construction, Automotive Suppliers, Electronics Manufacturing, Paints & Varnishes, Chemical Processing, Textile Production Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers, Exporters |
| Companies Covered | GHW (Vietnam) Co., Ltd., LC Buffalo Co. Ltd., Cardolite Corporation, KIMMY COMPANY LIMITED, Zhejiang Wansheng Co., Ltd., Cat Loi Cashew Oil Production & Export Joint Stock Company, Palmer International, Sri Devi Group, Golden Cashew Products Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cashew Nutshell Liquid Market Shifts & Advancements
Enzymatic decarboxylation processes are unlocking polymer-grade cardanol yields from previously substandard shell lots, altering the economics of high-purity production.
Supercritical CO2 extraction systems are decomposing the traditional cold-press/solvent dichotomy in CNSL recovery. Tier-1 automotive suppliers in Germany pilot these units to secure REACH-compliant feedstock with traceable carbon intensity. The technology is decomposing the margin advantage previously held by established Vietnamese and Indian solvent-based refiners.
EPA bio-preferred procurement standards now mandate minimum renewable content thresholds for federal coating contracts. This redirects R&D budgets at US-based specialty chemical houses toward cardanol-epoxy hybrid curing agents. Defense and infrastructure segments show the fastest compliance-driven specification changes.
Specification-driven procurement now dominates mid-volume coating formulation purchases. Buyers unbundle technical service from material supply, sourcing CNSL derivatives through commodity platforms while retaining specialized laboratories for application support. This pattern is most visible among North American industrial maintenance coating purchasers managing multi-site standardization programs.
Global Cashew Nutshell Liquid Market Segmentation
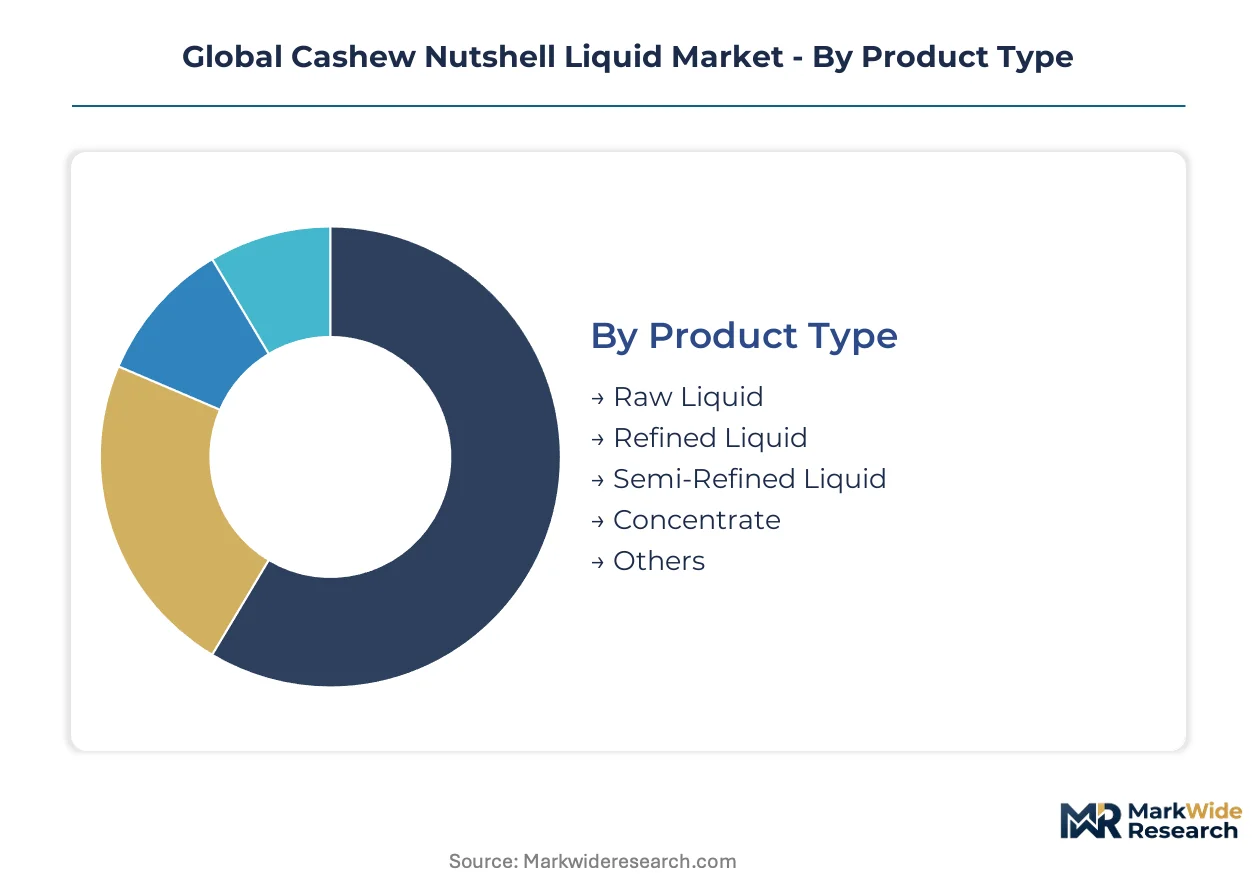
CNSL derivatives exhibit divergent margin profiles based on purification intensity and application specificity. Formulators segment procurement strategies around REACH compliance tiers, thermal performance thresholds, and supply security requirements rather than commodity pricing alone.
Product Type:
Refined liquid commands the deepest margin pools where polymer-grade purity enables premium substitution economics.
- Raw Liquid:Contains 60-70% anacardic acid with elevated sediment and moisture content. Asian friction material producers in Vietnam and India absorb volume leadership despite variability, tolerating quality inconsistency for brake pad cost targets.
- Refined Liquid:Achieves sub-1% moisture and controlled viscosity specifications through multi-stage filtration. German and French automotive undercoating formulators pay 40-60% premiums for REACH-compliant cardanol feedstock displacing bisphenol-A in can coatings.
- Semi-Refined Liquid:Intermediate purification meeting technical-grade coatings specifications without polymer-grade investment.
- Concentrate:High-cardanol fractions for lubricant additive reformulation under IMO 2020 sulfur restrictions.
- Others:Specialty fractions including decarboxylated cardanol for epoxy curing agent synthesis.
The dominant share belongs to Raw Liquid, while Refined Liquid is closing the gap fastest.
Application:
Coatings applications concentrate procurement volume, though lubricants are climbing fastest on regulatory reformulation mandates.
- Coatings:Cardanol-novolac resins serve automotive undercoating and industrial maintenance formulations. ECHA emission limits on phenol-formaldehyde drive German coating cluster uptake.
- Adhesives:Bio-based epoxy modifiers for construction and electronics bonding applications.
- Resins:Phenolic resin substitution in electrical laminates and friction particle binders.
- Inks:Surfactant-derived dispersants for printing applications.
- Insulation Materials:Thermal and electrical insulation compounds leveraging cardanol's phenolic structure.
- Lubricants:Friction modifiers and sulfur replacement additives. EPA Tier 4 and IMO 2020 standards force diesel engine oil reformulation, pulling concentrate grades into marine and heavy-duty segments.
Coatings maintains volume leadership, with Lubricants expanding most quickly on compliance-driven specification changes.
End User Industry:
Automotive suppliers and electronics manufacturers concentrate premium-grade demand, while construction absorbs technical-grade volume.
- Construction:Adhesive and coating applications in structural bonding and protective treatments.
- Automotive Suppliers:Undercoating, brake pads, and electrical component specifications. Tier-1 German suppliers pilot supercritical CO2-extracted feedstock for traceable carbon intensity.
- Electronics Manufacturing:Electrical laminates and insulation materials requiring polymer-grade purity.
- Paints & Varnishes:Decorative and industrial coating formulations.
- Chemical Processing:Intermediate production for surfactant and specialty chemical synthesis.
- Textile Production:Dye dispersants and fabric treatment chemicals.
Construction holds the largest volume position, though Electronics Manufacturing is gaining share fastest on bisphenol-A substitution demand.
Distribution Channel:
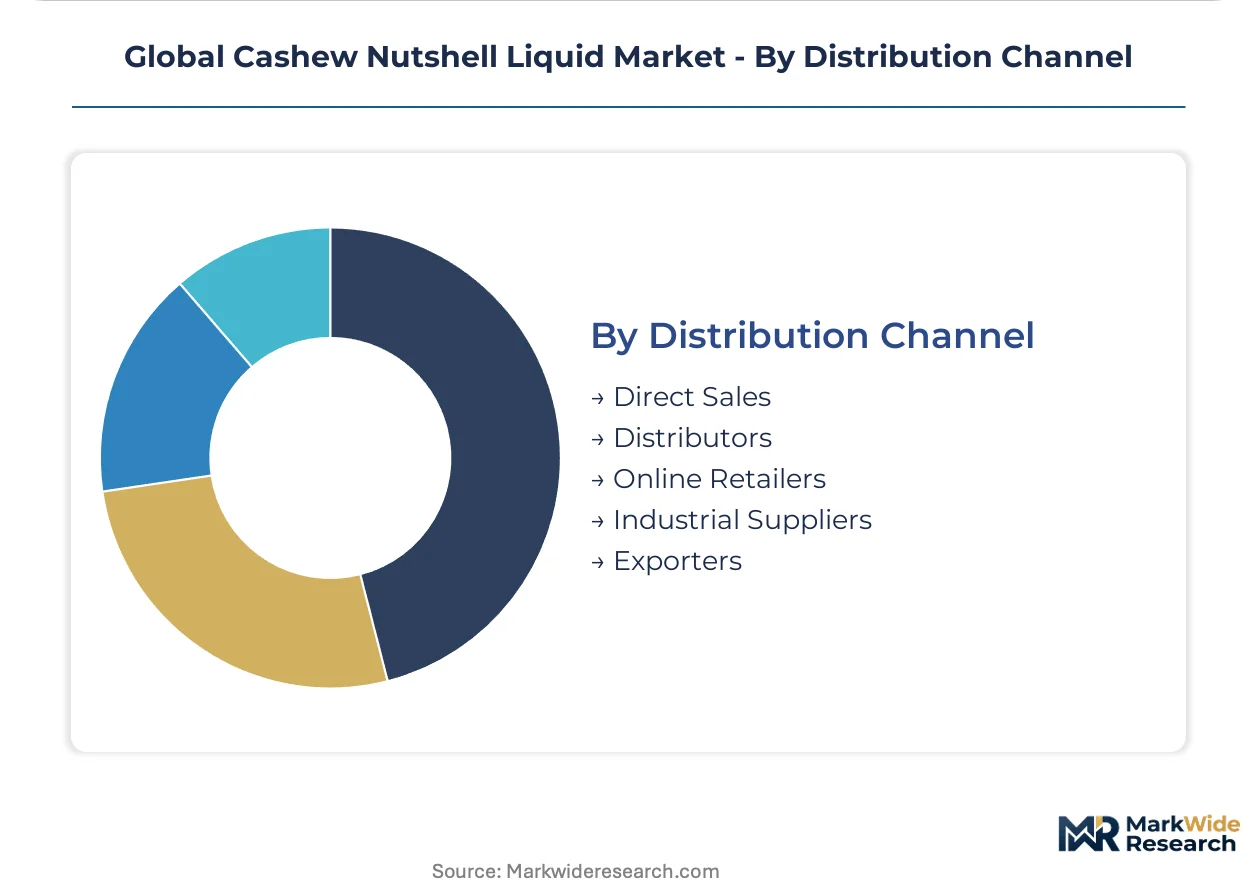
Direct sales capture premium-account relationships, while industrial suppliers fragment mid-volume procurement.
- Direct Sales:Long-term contracts between primary processors and tier-1 formulators. Cat Loi and Cardolite anchor automotive and electronics supply relationships through technical service integration.
- Distributors:Regional chemical distributors serving mid-volume coating houses with standard grades.
- Online Retailers:Emerging platforms for small-batch procurement and specification-driven unbundling.
- Industrial Suppliers:Maintenance-repair-operations channels for friction material producers.
- Exporters:Cross-border traders managing shell collection logistics from West African and South Asian processing clusters.
Direct Sales dominates value capture, while Online Retailers are climbing fastest on procurement digitization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over 70% of cashew shell supply clusters around West African and South Asian processing corridors, creating pronounced geographic dependencies for raw material access. Monsoon disruptions and infrastructure gaps in collection networks expose processors to seasonal volatility. Primary refining capacity concentrates in Vietnam, India, and Nigeria, with emerging investments diversifying supply geography.
Vietnam
Ho Chi Minh City anchors Southeast Asia's largest CNSL export pipeline through integrated shell collection networks. Vietnamese processors dominate technical-grade refined liquid output for Asian friction material producers. The Ministry of Industry and Trade's bio-chemical development incentives support capacity expansion in Dong Nai and Binh Phuoc provinces.
India
Kollam corridor infrastructure in Kerala state concentrates domestic shell processing and primary refining for electrical laminate applications. Indian formulators absorb volume leadership in raw liquid grades for brake pad manufacturing. BIS eco-mark criteria create compliance pathways for exporters serving EU and North American coating markets.
Germany
Rhineland coating clusters drive premium-grade cardanol demand for automotive undercoating reformulation. ECHA emission limits on phenol-formaldehyde resins force Tier-1 suppliers toward REACH-compliant cardanol-novolac alternatives. Supercritical CO2 extraction pilots in Bavaria seek traceable carbon intensity for defense and infrastructure coating contracts.
United States
EPA bio-preferred procurement standards mandate renewable content thresholds for federal coating contracts, redirecting R&D budgets toward cardanol-epoxy hybrid curing agents. Specialty chemical houses in Texas and Ohio concentrate formulation expertise for electrical laminate applications. Defense segment specification changes outpace commercial adoption timelines.
Brazil
Ceará and Rio Grande do Norte states offer underdeveloped shell collection infrastructure for integrated refining investments. Brazilian Northeast processing expansion targets Atlantic shipping routes to European coating formulators. ANVISA bio-based chemical registration pathways remain less mature than REACH or EPA frameworks, extending product launch cycles.
Global Cashew Nutshell Liquid Market Competitive Landscape
Concentration sits with vertically integrated processors commanding backward integration into shell collection networks. The market structures around three tiers: large-scale exporters with captive raw material access, mid-cap refiners serving regional coating clusters, and specialty chemical houses focusing on polymer-grade purity. Strategic moves center on collection network density expansion and multi-jurisdiction certification investments.
Among Vietnam-based integrated processors, Cat Loi Cashew Oil Production & Export Joint Stock Company exemplifies the collection-network archetype. Cardolite Corporation occupies a position representing phenolic resin specialization for premium automotive applications. Palmer International sits within the technical service depth tier for epoxy curing agent segments. Zhejiang Wansheng Co., Ltd. anchors Chinese-scale processing capacity for Asian friction material supply.
| Leading Market Players |
|---|
| GHW (Vietnam) Co., Ltd. |
| LC Buffalo Co. Ltd. |
| Cardolite Corporation |
| KIMMY COMPANY LIMITED |
| Zhejiang Wansheng Co., Ltd. |
| Cat Loi Cashew Oil Production & Export Joint Stock Company |
| Palmer International |
| Sri Devi Group |
| Golden Cashew Products Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles at Vietnamese primary processors signal how supply concentration in Monrovia, Ho Chi Minh City, and Kollam corridors translates directly into pricing leverage for backward-integrated refiners serving REACH-compliant coating formulators.
Pricing Analysis
REACH dictates the pricing tier structure across the European coating cluster, separating polymer-grade cardanol displacing bisphenol-A from technical-grade friction material feedstock. Price differentiation hinges on certification tier—ECHA-compliant versus BIS eco-mark pathways—and volume scale from long-term automotive supply contracts. Cost compression in raw liquid grades is intensifying because Asian brake pad manufacturers absorb higher sediment tolerance for cost targets. Mid-volume coating houses exhibit highest price sensitivity, while Tier-1 German automotive suppliers accept substantial premiums for traceable carbon intensity.
Supply Chain Analysis
Ninety-day inventory cycles expose processors to monsoon-driven collection disruptions across Vietnam, India, and Nigeria, where over seventy percent of cashew shell supply clusters. Raw material dependencies center on shell collection network density, solvent extraction capacity, and polymer-grade purification infrastructure. Single-source vulnerability concentrates in the Kollam corridor, where electrical laminate feedstock refining hinges on Kerala state infrastructure. Distribution runs through direct long-term contracts between primary processors and tier-1 formulators, with emerging commodity platforms fragmenting mid-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward specification-driven procurement consolidation among North American industrial maintenance coating purchasers managing multi-site standardization programs.
For Market Incumbents: Compound collection network density in Dong Nai and Binh Phuoc provinces to defend against supercritical CO2 extraction pilots threatening solvent-based margin structures. Prioritize simultaneous EPA bio-preferred and EU Ecolabel certification investments to compress multi-jurisdiction approval timelines for automotive undercoating supply relationships. For New Entrants and Emerging Players: Lead with underdeveloped shell collection infrastructure in Ceará and Rio Grande do Norte states, where Brazilian Northeast processing expansion offers first-mover advantage for Atlantic shipping routes to European coating formulators. Target lubricant additive reformulation under IMO 2020 sulfur restrictions through concentrate-grade positioning for marine diesel engine oil applications. For Investors and Strategic Acquirers: Long-term, this sits as a feedstock security play because cashew processing geography concentrates shell availability around infrastructure-constrained corridors. Acquisition targets should exhibit backward integration into collection networks or enzymatic decarboxylation capabilities unlocking polymer-grade yields. The signal to watch is supercritical CO2 extraction unit deployment rates among Tier-1 automotive suppliers seeking traceable carbon intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive shell collection networks in Vietnam and Nigeria secure raw material access against monsoon disruptions. |
| Green Manufacturing Transition | Enzymatic decarboxylation processes unlock polymer-grade cardanol yields from previously substandard shell lots. |
| Long-term Supply Agreement | Direct contracts with German Rhineland coating clusters anchor premium pricing for REACH-compliant automotive undercoating. |
| Joint Venture | Supercritical CO2 extraction partnerships with Bavarian pilot facilities decompose traditional cold-press refiner advantages. |
| Capacity Expansion | Dong Nai and Binh Phuoc province investments leverage Ministry of Industry and Trade bio-chemical development incentives. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with plant managers at Vietnamese and Indian primary processors, procurement leads at German automotive coating formulators, technical R&D directors at epoxy curing agent specialists, and distribution channel partners across Southeast Asian export corridors; alongside secondary validation through customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from specialty chemical houses, and ECHA regulatory disclosure databases. Bottom-up volume modeling triangulated against top-down market sizing across product grade, application, and end-use industry dimensions.
Across the projection horizon, analytical frameworks modeled segmentation across purification intensity tiers, coating versus lubricant application clusters, automotive and electronics end-use industries, and regional production hub configurations. CAGRs derived from elasticity-adjusted demand curves incorporating REACH compliance deadline phasing, EPA bio-preferred procurement threshold implementation, and cashew crop yield volatility patterns.
The analysis sits within stated boundaries; outcomes outside sustained ECHA emission limit enforcement or accelerated IMO sulfur restriction timelines would require recalibration. Forecasts reflect assumptions regarding shell collection network expansion rates and enzymatic process yield improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Macadamia Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
Pecans Market