
 Almond Kernels Market | 2026-2036
Almond Kernels Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Kernels Market Analysis
Asset-light leasing arrangements for orchard equipment and processing infrastructure is reconfiguring competitive entry barriers, allowing mid-scale operators to scale without land ownership. Blue Diamond Growers leverages its cooperative structure to sustain volume commitments across thousands of member growers. Wonderful Pistachios & Almonds anchors its position through backward integration into water rights and pollination services. Select Harvest competes by dominating Australian export channels into Asian food manufacturing.
Almond kernels are the edible seeds of Prunus dulcis, typically 25-30 mm in length with a lipid content exceeding 50% and protein concentrations around 21-25%, requiring controlled steam pasteurization to meet food safety standards for ready-to-eat applications. Raw kernel grades occupy the largest volume position in trade flows, while organic certification commands premium positioning in European retail channels. Snack and confectionery end-use segments represent the fastest-expanding demand pools, with dairy alternatives emerging as a structurally significant buyer category.
USDA grading standards and FDA Food Safety Modernization Act requirements shape product specifications and market access protocols for domestic and export-bound shipments. California's State Water Resources Control Board allocations directly constrain annual yield potential, forcing processors to navigate regulatory compliance across water, agricultural labor, and food safety frameworks. Stakeholders must monitor pollinator health regulations and groundwater basin sustainability plans as determinants of long-term supply reliability.
Market Dynamics
California's Sustainable Groundwater Management Act is forcing acreage retirement and forcing processors to secure alternative water portfolios through banking and transfers.
Growth Catalysts
- Snack Manufacturing Demand:Ready-to-eat almond products are displacing traditional nut mixes in North American convenience retail, with clean-label positioning driving formulation switches.
- USDA Grading Standardization:Uniform kernel size and defect classifications are reducing transaction friction between handlers and export buyers, accelerating containerized shipments to Asian food manufacturers.
- Controlled Steam Pasteurization:Non-thermal pathogen reduction technologies are preserving lipid integrity while satisfying FDA Food Safety Modernization Act requirements for ready-to-eat status.
Market Restraints
- Groundwater Basin Depletion:California's Central Valley aquifer overdraft is triggering mandatory pumping cuts under SGMA basin plans, constraining yield expansion regardless of price signals.
- Pollinator Dependence:Single-source reliance on migratory honeybee services creates catastrophic failure risk during bloom windows, with colony collapse disorder threatening contract coverage.
- Oat and Pea Protein Substitution:Dairy alternative formulators are blending almond bases with cheaper oilseed proteins, compressing kernel inclusion rates in finished beverages.
Strategic Opportunities
- Australian Export Channel Expansion:Select Harvest and other Australian operators are capturing premium positioning in Asian confectionery supply chains as California faces reliability concerns.
- Organic Certification Arbitrage:European retailers are mandating organic kernel sourcing under EU Green Deal farm-to-fork targets, creating price premiums for certified handlers.
- Asset-Light Leasing Models:Mid-scale operators are accessing processing infrastructure through cooperative equipment pools, reducing capital barriers to volume scaling.
Industry Challenges
- Multi-Jurisdictional Compliance Burden:Processors must simultaneously satisfy FDA pasteurization mandates, State Water Resources Control Board discharge permits, and Cal/OSHA agricultural labor standards.
- Integrated Pest Management Skill Gap:Navel orangeworm and hull rot control now requires precision entomology expertise that legacy field crews lack, forcing investment in technical training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Kernels Market |
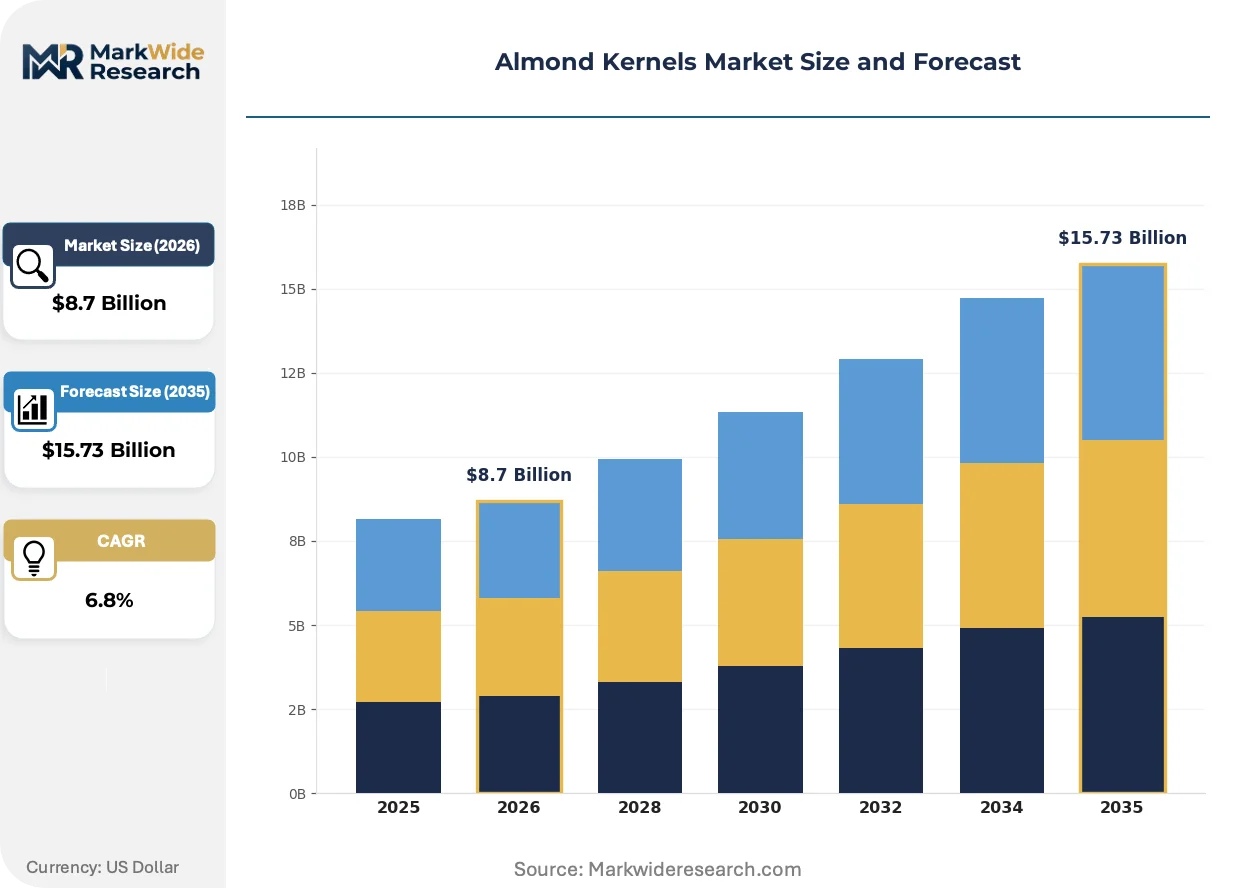
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Blanched, Sliced, Diced Grade: Inshell, Organic, Non-Organic, Gourmet End Use: Baking, Snacks, Confectionery, Dairy Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales |
| Companies Covered | Spycher Brothers, Mariani Nut Company, Blue Diamond Growers, Chico Nut Company, Waterford Nut Co., Wonderful Pistachios & Almonds, Select Harvest, Almexca, Panoche Creek Packing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Kernels Market Emerging Trajectories
Processing technology and regulatory compliance frameworks are compressing margins while opening premium positioning for operators with certified traceability systems.
Hyperspectral sorting is collapsing manual inspection labor requirements while improving defect detection accuracy. Large handlers are retrofitting existing lines with near-infrared kernel analyzers that classify internal damage in real time. This technology is collapsing quality-control headcount needs and enabling direct-to-manufacturer contracting that bypasses traditional commission merchants.
California's State Water Resources Control Board is implementing groundwater sustainability agency enforcement that limits new well drilling in critically overdrafted basins. SGMA basin plans now require measurable water budgets that tie pumping rights to historical use patterns. Handlers in the Tulare Lake and San Joaquin sub-basins are most affected, with some consolidating operations into better-watered districts.
Plant-based dairy formulators are unbundling ingredient sourcing from finished goods manufacturing, creating direct procurement relationships with kernel processors. Large beverage brands are establishing preferred supplier programs that specify origin, pasteurization method, and lipid profile. This shift is most visible in North American oat-almond blend products where kernel specifications now appear in master service agreements rather than spot market purchases.
Almond Kernels Market Segmentation
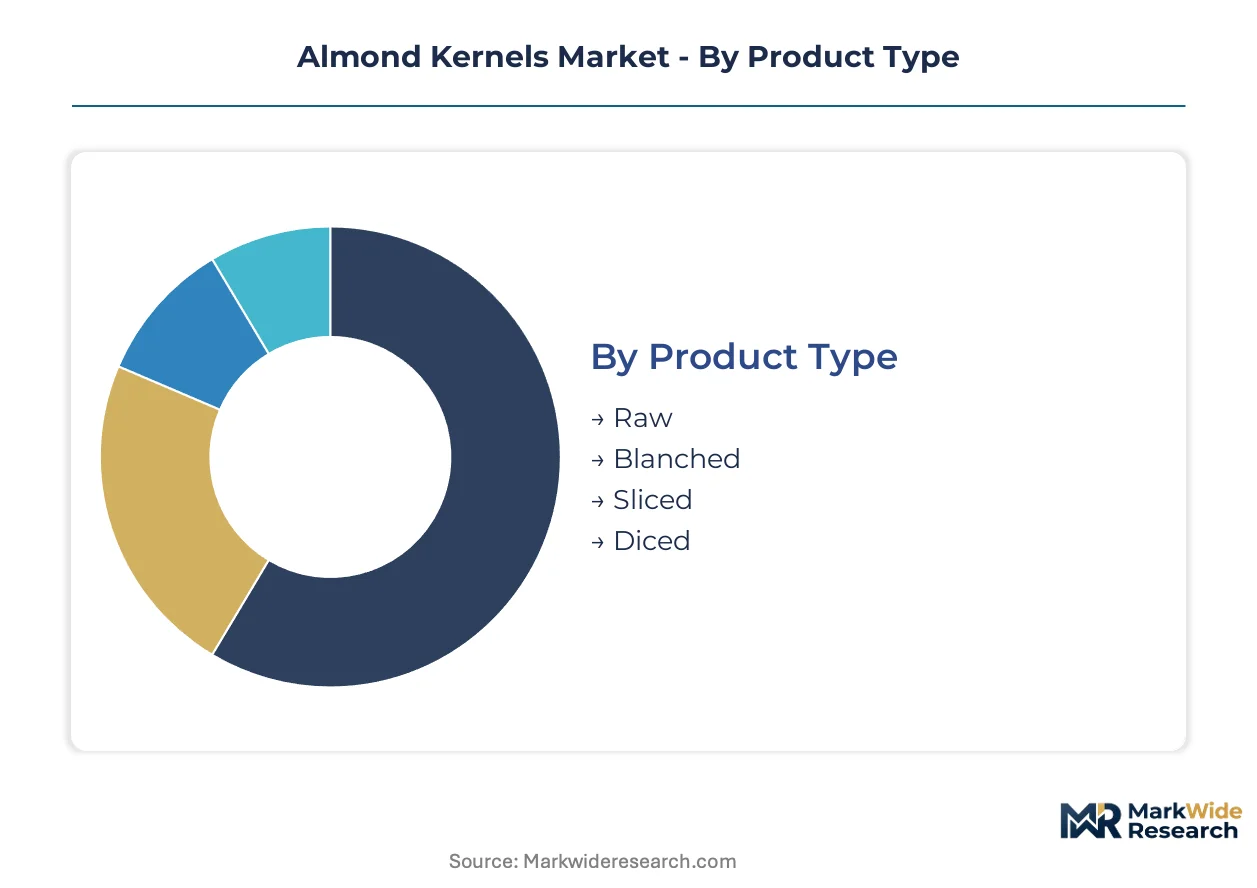
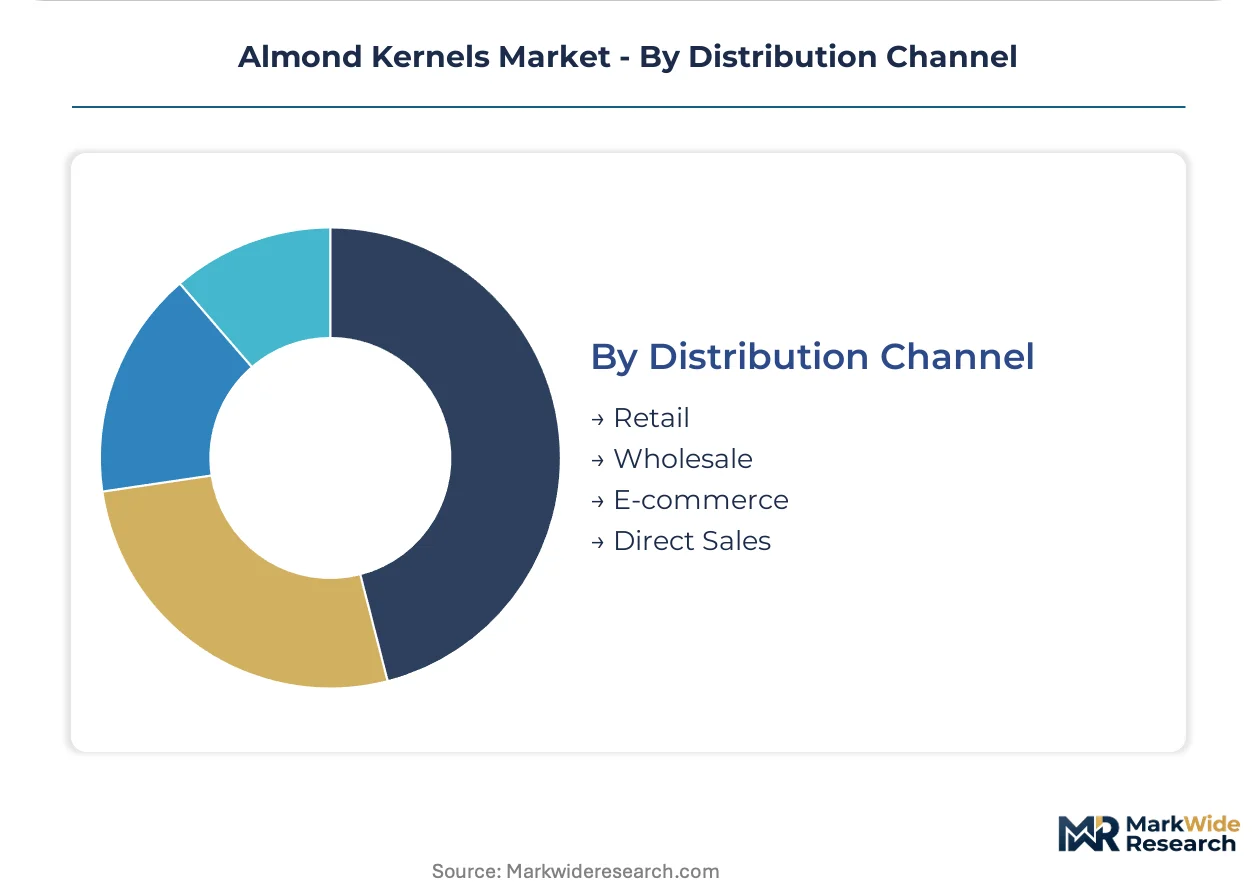
Kernel form factor and certification status create divergent margin profiles across the value chain. Distribution channel selection determines whether handlers capture premium positioning or compete on volume throughput.
Product Type:
Cost tier differentiation separates commodity bulk handlers from value-added processors commanding formulation premiums.
- Raw:Unprocessed kernels retain natural skin and lipid profile, serving as the input substrate for downstream pasteurization and further processing. California Central Valley bulk handlers dominate spot market liquidity, though water access constraints under SGMA are compressing annual availability.
- Blanched:Steam-treated kernels with removed skins deliver uniform color and softer texture for confectionery applications. European chocolate manufacturers specify blanched grades in master supply agreements to ensure batch consistency.
- Sliced:Thin-cut flakes provide surface coverage and textural contrast in bakery applications. Commercial bakeries specify slice thickness tolerances in procurement contracts.
- Diced:Cubed kernels integrate into energy bars and granola formulations requiring particle size uniformity. Snack manufacturers prize dice dimensions for controlled mouthfeel.
Raw kernels command the established base. The steepest expansion runs through blanched and sliced value-added forms.
Grade:
Certification tier and shell status segment buyers by quality tolerance and price sensitivity.
- Inshell:Kernels retained within protective hulls extend shelf life and reduce handling damage during transport. Seasonal gift pack assemblers and export markets with limited cold chain infrastructure concentrate demand here.
- Organic:Certified production under USDA National Organic Program or EU organic regulations commands price premiums in European retail channels. EU Green Deal farm-to-fork targets are mandating organic sourcing for private label lines.
- Non-Organic:Conventional cultivation dominates volume throughput, serving price-sensitive food manufacturing and ingredient blending applications. Processors achieve economies of scale through bulk handling infrastructure.
- Gourmet:Ultra-large kernels with minimal defects target premium snacking and artisanal confectionery segments. Direct-to-consumer brands specify gourmet grades for clean-label positioning.
Non-Organic grades anchor volume throughput. Organic certification is climbing the fastest as European procurement mandates tighten.
End Use:
Application-specific formulation requirements drive kernel specification divergence across downstream industries.
- Baking:Diced and sliced forms integrate into commercial bakery formulations where moisture retention and browning characteristics matter. Large-scale bakeries specify pasteurized grades to eliminate pathogen testing burdens.
- Snacks:Ready-to-eat roasted and flavored kernels displace traditional nut mixes in North American convenience retail. Clean-label positioning drives processors toward minimal ingredient declarations.
- Confectionery:Blanched whole kernels and precise dice dimensions serve chocolate enrobing and praline applications. Swiss and Belgian manufacturers enforce strict size grading for automated production lines.
- Dairy:Milled kernels and almond bases supply plant-based milk and yogurt alternatives. Beverage brands now specify origin and pasteurization method in preferred supplier programs.
Snacks and baking absorb the majority of raw kernel flow. Dairy alternatives are gaining share fastest as beverage formulators unbundle ingredient sourcing.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth for kernel handlers.
- Retail:Packaged consumer goods placement in grocery and specialty stores requires brand investment and slotting fee structures. Private label penetration is compressing branded margin space.
- Wholesale:Bulk shipments to food manufacturers and ingredient distributors dominate volume economics. Containerized exports to Asian food manufacturers flow through established commission merchant networks.
- E-commerce:Direct-to-consumer and B2B platform sales enable specialty grade access for smaller buyers. Traceability certification and origin storytelling support premium positioning.
- Direct Sales:Long-term supply agreements between processors and large end-users bypass intermediary margins. Master service agreements now specify lipid profiles and pasteurization protocols.
Wholesale channels handle the volume foundation. Direct sales relationships are expanding most quickly as beverage brands build captive supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reconfiguring sourcing patterns as water scarcity in California pushes buyers toward Australian and Spanish alternatives. Kernel trade flows now prioritize supply reliability over historical proximity advantages.
United States
Snack manufacturers and plant-based dairy formulators drive kernel procurement volumes from California's Central Valley. The State Water Resources Control Board enforces SGMA basin sustainability plans that cap groundwater pumping in Tulare Lake and San Joaquin sub-basins. Fresno County handlers are consolidating operations into better-watered districts to maintain throughput.
Australia
Asian confectionery manufacturers are redirecting procurement toward Australian exporters as California reliability concerns mount. The country's national agricultural regulator maintains phytosanitary protocols that satisfy Japanese and South Korean import requirements. Select Harvest dominates export channels from Victoria's Sunraysia region into Southeast Asian food manufacturing.
Spain
European retailers seeking organic certification arbitrage are expanding Spanish kernel sourcing under EU Green Deal farm-to-fork targets. EFSA traceability requirements shape handler compliance investments across Andalusia. The Lleida cluster in Catalonia is developing integrated processing infrastructure for blanched and sliced value-added forms.
Italy
Artisanal confectionery and premium snacking segments concentrate demand in northern processing hubs. REACH chemical safety standards govern pasteurization equipment and coating formulations entering EU distribution. The Torino-Alessandria corridor hosts specialized handlers serving Swiss and Belgian chocolate manufacturers.
China
Domestic almond consumption is climbing as bakery and snack manufacturers upgrade ingredient specifications. SAMR food safety licensing requirements restrict import channel access to handlers with certified pasteurization documentation. The Xinjiang production zone is expanding irrigated acreage under state agricultural development programs.
Almond Kernels Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in processing equipment and pollination services. The vendor base clusters around three archetypes: cooperative structures aggregating grower volumes, vertically integrated handlers controlling water and bee assets, and export-focused specialists dominating regional trade lanes. Competitive moves center on backward integration into captive water portfolios and preferred supplier program capture with beverage brands.
Among cooperative-structured handlers, Blue Diamond Growers exemplifies the member-grower aggregation model. Wonderful Pistachios & Almonds occupies a position reflecting integrated control over pollination services and groundwater assets. Select Harvest represents the export-channel specialist archetype with Australian base and Asian market concentration. These three anchors illustrate how scale formation now depends on asset control depth rather than processing capacity alone.
| Leading Market Players |
|---|
| Spycher Brothers |
| Mariani Nut Company |
| Blue Diamond Growers |
| Chico Nut Company |
| Waterford Nut Co. |
| Wonderful Pistachios & Almonds |
| Select Harvest |
| Almexca |
| Panoche Creek Packing |
| Others |
Supply Flow & Price Mechanics
Overcapacity in California's Central Valley processing infrastructure is forcing handlers into aggressive contract bidding for limited kernel supply, compressing margins while amplifying price volatility for spot market buyers. SGMA-mandated pumping cuts have transformed water access into the primary pricing determinant, with handlers in better-watered districts commanding premium positioning.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate volume procurement, with premium-mid-economy pricing differentiation separating organic-certified, conventional, and commodity grades. Price differentiation stems from certification tier and volume scale, with EU Green Deal procurement mandates tightening organic premiums. Pricing pressure stems from oat and pea protein substitution in dairy alternatives, compressing kernel inclusion rates. Snack manufacturers exhibit lowest price sensitivity due to clean-label positioning requirements, while bulk food manufacturers remain most cost-conscious.
Supply Chain Analysis
Pollinator dependence creates catastrophic single-source vulnerability during California's bloom window, with migratory honeybee contract coverage threatened by colony collapse disorder. Supply concentrates in the United States, Australia, and Spain, with raw material dependencies spanning groundwater allocations, migratory pollination services, and steam pasteurization equipment. Distribution runs through wholesale commission merchant networks for Asian exports, while direct sales relationships are expanding with North American beverage brands establishing captive procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large beverage brands unbundling ingredient sourcing, with preferred supplier programs now specifying origin and pasteurization protocols that bypass traditional spot markets.
For Market Incumbents: Harden water portfolio resilience through banking and transfer acquisitions in SGMA-compliant basins, while locking in multi-year pollination service contracts to secure bloom coverage. SGMA enforcement in Tulare Lake and San Joaquin sub-basins threatens stranded capacity; backward integration into certified organic acreage captures EU Green Deal procurement premiums.
For New Entrants and Emerging Players: Build out asset-light leasing arrangements for processing infrastructure, leveraging cooperative equipment pools to bypass capital barriers. Australian export channels into Southeast Asian confectionery manufacturing offer the most penetrable geography, with phytosanitary-compliant handlers capturing reliability premiums as California faces supply uncertainty.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among handlers with direct sales relationships to beverage brands, where master service agreements specify multi-year volume commitments. Long-term viability hinges on water rights depth and pollination service control; acquisition targets should demonstrate SGMA basin compliance and certified organic capacity expansion. Watch pollinator health regulation enforcement as the inflection indicator for supply reliability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Water Rights Portfolio Expansion | SGMA-compliant basin access in Fresno County secures processing throughput against pumping cuts. |
| Pollination Service Integration | In-house bee colony management reduces catastrophic failure risk during California bloom windows. |
| Organic Certification Scale-Up | EU Green Deal farm-to-fork targets mandate organic sourcing for European retail private label lines. |
| Direct Sales Relationship Development | Preferred supplier programs with beverage brands specify origin and pasteurization in multi-year agreements. |
| Hyperspectral Sorting Deployment | Near-infrared kernel analyzers collapse quality-control labor while enabling direct-to-manufacturer contracting. |
Methodological Framework
Operator-level perspectives from orchard managers, processing facility directors, pollination service contractors, and procurement leads at snack manufacturers anchored the qualitative base. Secondary validation drew from USDA crop reports, FDA Food Safety Modernization Act guidance documents, California State Water Resources Control Board basin plan filings, and customs export records. Bottom-up acreage and yield estimates triangulated against top-down handler throughput disclosures.
Scenario-bracketing across water availability, pollinator contract coverage, and protein substitution rates shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include kernel form factor, certification status, end-use application, and distribution channel. CAGRs were derived from volume trajectory analysis against price elasticity assumptions, with groundwater sustainability plan enforcement timelines and EU organic procurement mandates as key forecast inputs.
Stress conditions across SGMA pumping allocation severity, colony collapse disorder incidence, and oat-almond blend formulation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement pace and buyer substitution elasticity. Material shifts in California groundwater adjudication or pollinator health regulation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Peanuts Market