
 United States Cashew Market | 2026-2036
United States Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cashew Market Outlook
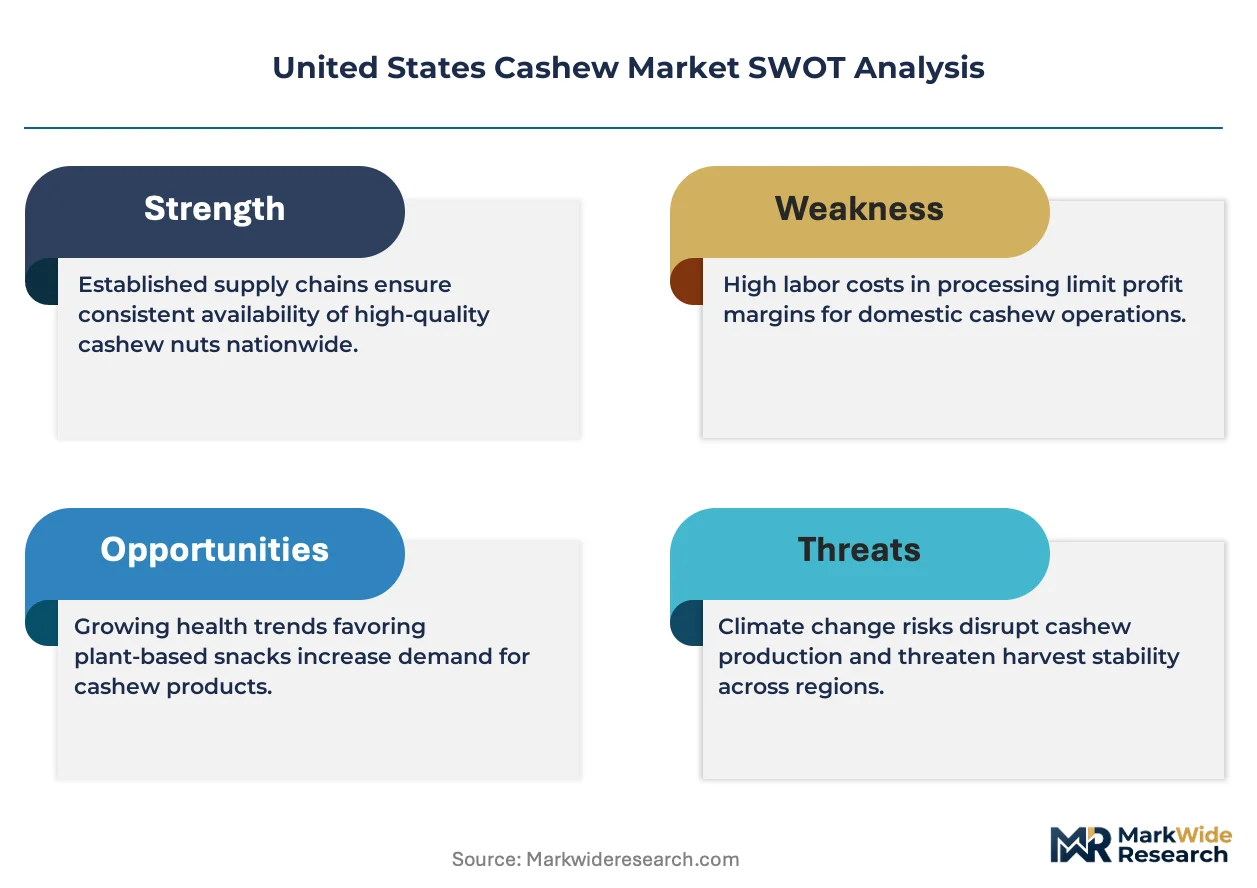
FDA nutrition labeling rules is realigning the cost-of-entry calculus for new cashew product entrants, forcing reformulation investments before shelf placement. The Wonderful Company leverages vertical integration from orchard to retail shelf, sustaining brand strength across premium nut assortments. Blue Diamond Growers dominates almond-cashew crossover portfolios, while Sahale Snacks specializes in flavored gourmet positioning that commands higher margin per ounce.
Cashews are kidney-shaped seeds of Anacardium occidentale, typically containing 18% protein and 44% fat by weight, with commercial grades defined by kernel size (W-240 through W-320) and whiteness index for confectionery use. The food and beverage segment anchors volume throughput through dairy-alternative milk formulations and butter spreads. Retail consumers represent the deepest margin pool, while nutraceutical applications exhibit the fastest trajectory as functional food brands incorporate cashew-derived ingredients into protein fortification systems.
USDA grading standards, FDA food safety modernization protocols, and California Department of Public Health processing permits collectively govern market access and product liability exposure for domestic handlers. These frameworks elevate compliance costs for smaller importers while creating structural advantages for operators with in-house laboratory testing and HACCP-certified facilities. Stakeholders must monitor how proposed updates to FDA tree nut allergen thresholds reshape labeling requirements and reformulation timelines across the supply base.
Market Dynamics
FDA nutrition labeling rules are tightening health-claim thresholds for tree nut products, forcing reformulation investments before shelf placement and elevating compliance costs for smaller importers. Snack manufacturers are expanding cashew SKUs as plant-based protein demand strengthens.
Growth Catalysts
- Plant-based protein demand:Snack manufacturers are expanding cashew SKUs into dairy-alternative milk formulations and butter spreads. This trend concentrates in California's food processing corridor.
- USDA grading standards:Standardized kernel sizing from W-240 through W-320 enables transparent quality differentiation. Confectionery buyers leverage whiteness index specifications for premium sourcing.
- Functional food integration:Nutraceutical applications incorporate cashew-derived ingredients into protein fortification systems. This end-use vertical exhibits the fastest trajectory within the market.
Market Restraints
- Input cost volatility:Raw cashew kernel prices fluctuate with West African and South Asian harvest cycles. Importers face margin compression during supply shocks.
- Regulatory friction:FDA food safety modernization protocols mandate HACCP-certified facilities. Smaller handlers lack capital for in-house laboratory testing infrastructure.
- Allergen labeling burden:Proposed updates to FDA tree nut allergen thresholds reshape labeling requirements. Reformulation timelines compress across the supply base.
Strategic Opportunities
- Texas distribution hubs:Demand is concentrating in Texas distribution hubs, creating logistics advantages for regional processors. Cold chain infrastructure investments unlock shelf-stable product expansion.
- Gourmet flavor positioning:Flavored nut portfolios command higher margin per ounce. Specialty retailers seek differentiated offerings beyond commodity kernel grades.
- California processing corridor:Vertical integration from orchard to retail shelf sustains brand strength. Captive supply chains insulate against import tariff volatility.
Industry Challenges
- HACCP certification timeline:California Department of Public Health processing permits require extended approval cycles. New entrants face 12-18 month facility qualification periods.
- Kernel grading expertise:Manual whiteness assessment and size classification demand skilled labor. Training programs for W-240 through W-320 grading standards remain underdeveloped domestically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cashew Market |
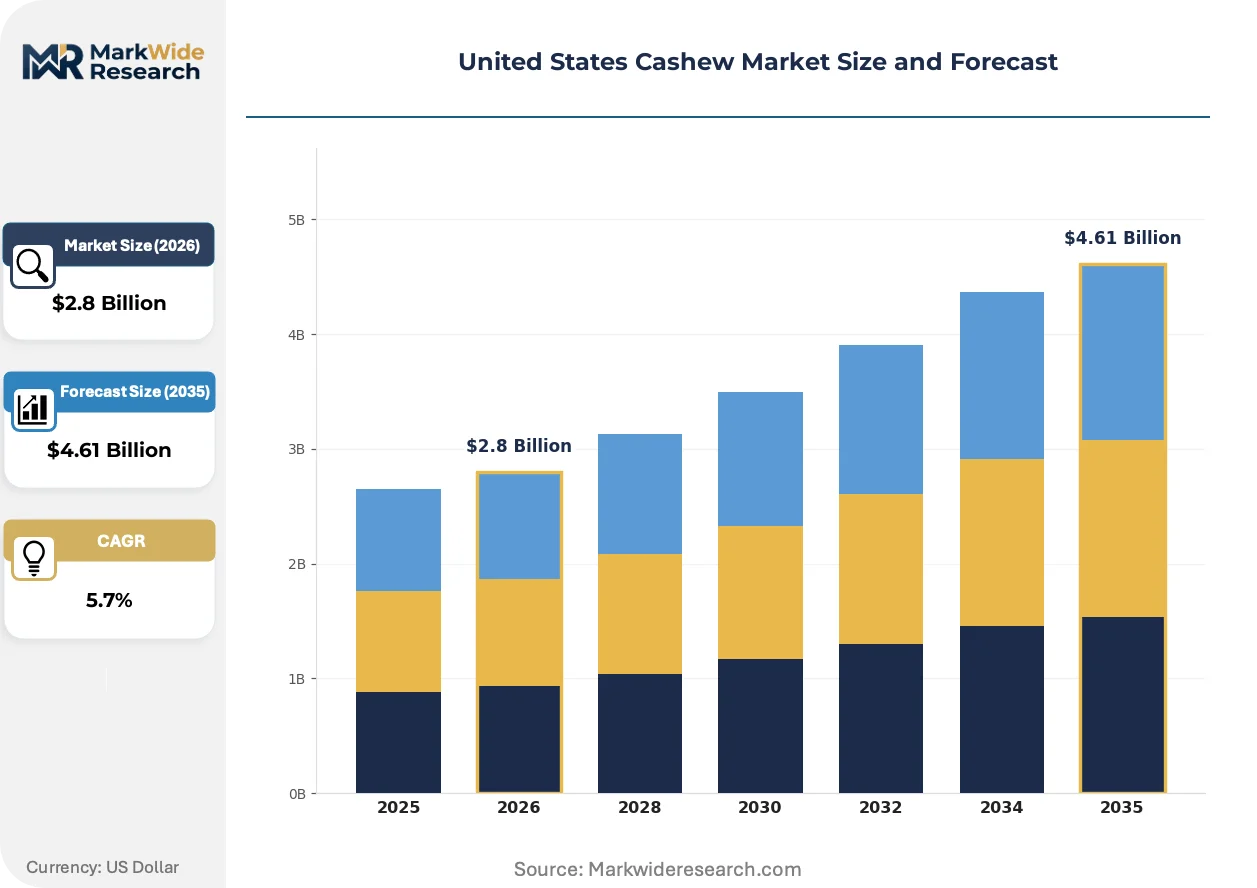
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashews, Roasted Cashews, Flavored Cashews, Salted Cashews Packaging Type: Bags, Boxes, Bulk Containers, Jars Customer Type: Retail Consumers, Food Service, Manufacturers, Exporters End Use Industry: Food & Beverage, Snacks, Confectionery, Nutraceuticals |
| Companies Covered | Archer Daniels Midland, The Wonderful Company, Kraft Heinz, PepsiCo, Sahale Snacks, Blue Diamond Growers, Emerald Nuts, Cargill, Planters, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cashew Market Strategic Shifts
Processing technology and regulatory precision are converging to reshape competitive positioning in cashew value chains. Three developments merit close monitoring.
Optical sorting systems are consolidating quality control workflows across kernel grading operations. California processing facilities deploy machine vision for whiteness index measurement and defect detection. Mid-scale handlers are adopting these systems to reduce manual labor dependency and compress inspection cycle times.
FDA nutrition labeling rules are tightening health-claim thresholds for tree nut products. This regulatory pressure forces reformulation investments before shelf placement. Snack manufacturers with in-house R&D capabilities are accelerating clean-label repositioning to maintain retail access.
Retail consumers are migrating toward transparent supply chain sourcing. E-commerce direct-to-consumer channels displace traditional wholesale distribution for specialty nut assortments. California-based brands leverage this channel shift to capture deeper margins through subscription model adoption.
United States Cashew Market Segmentation
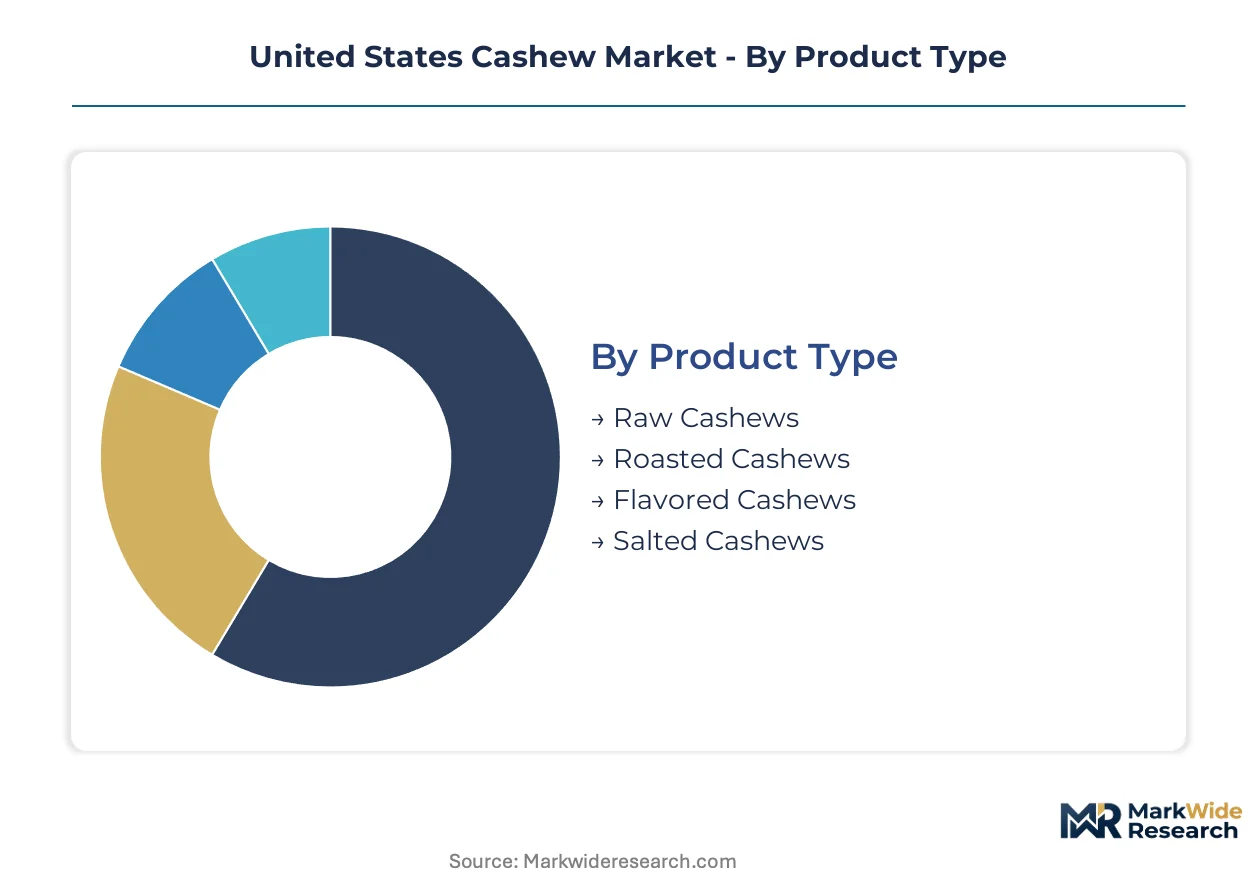
Kernel grade specifications and packaging formats fragment the United States Cashew Market into distinct margin tiers. Each segment demands specialized processing infrastructure and regulatory compliance protocols that reshape competitive positioning across the value chain.
Product Type:
Volume throughput concentrates in minimally processed formats, while premium capture flows through value-added treatments that command shelf-space differentiation.
- Raw Cashews:Unroasted kernels retain full oil content and enzymatic activity for industrial food processing. Demand clusters in California's food processing corridor where dairy-alternative milk manufacturers require unheated input stock for clean-label positioning.
- Roasted Cashews:Dry-heat or oil-roasted kernels achieve Maillard browning for flavor development and microbial reduction. Texas distribution hubs channel these SKUs into conventional retail and food service procurement systems seeking extended shelf stability.
- Flavored Cashews:Coated varieties with spice, sweet, or savory infusions target gourmet positioning. Specialty retailers in urban coastal markets drive this segment's margin premium per ounce.
- Salted Cashews:Sodium-enhanced variants serve price-sensitive mass retail channels. FDA sodium labeling thresholds pressure reformulation toward reduced-salt profiles.
Mature deployment sits with Raw Cashews. Newer deployment is concentrated in Flavored Cashews.
Packaging Type:
Channel requirements dictate format selection, with convenience retail favoring single-serve portability while industrial buyers prioritize freight efficiency.
- Bags:Flexible film pouches dominate grab-and-go retail with resealability features. Convenience store chains and airport concessionaires specify this format for impulse purchase environments.
- Boxes:Rigid paperboard containers support premium gift assortments and club-store multipacks. E-commerce direct-to-consumer brands leverage this format for subscription model differentiation and shipping protection.
- Bulk Containers:Food service sacks and ingredient totes serve industrial-scale users. California confectionery processors and Texas nut butter manufacturers pull kernel supply through this channel.
- Jars:Rigid plastic or glass vessels target pantry-stocking households and specialty retail. Gourmet positioning relies on transparent packaging to display kernel grade and color uniformity.
Established infrastructure supports Bulk Containers. Channel expansion is accelerating fastest for Bags.
Customer Type:
Margin depth varies sharply across buyer categories, with direct retail capturing value that dissipates through intermediary layers.
- Retail Consumers:Individual households purchasing through grocery, club, and e-commerce channels. California-based brands exploit this segment through subscription models and transparent sourcing narratives.
- Food Service:Restaurants, catering operations, and institutional feeders sourcing through broadline distributors. Menu innovation around plant-based protein drives cashew incorporation into dairy-free sauces and desserts.
- Manufacturers:Industrial processors of nut butters, alternative milks, and bakery inclusions. FDA nutrition labeling rules for tree nut health claims directly impact their procurement specifications.
- Exporters:Re-export handlers shipping processed kernels to Canada, Mexico, and Caribbean markets. Texas distribution hubs provide logistics advantages for this trade flow.
Volume concentration remains with Manufacturers. Steepest expansion trajectory belongs to Retail Consumers.
End Use Industry:
Application diversity stretches from commodity ingredient supply to functional food positioning with distinct regulatory and technical requirements.
- Food & Beverage:Dairy-alternative milk formulations and butter spreads anchor volume throughput. California processing facilities supply this segment with W-240 through W-320 graded kernels.
- Snacks:Ready-to-eat nut packs and trail mixes serve convenience-oriented consumption. Plant-based protein demand strengthens SKU expansion across salted and flavored variants.
- Confectionery:Chocolate enrobing and praline applications demand premium whiteness index specifications. Manual grading expertise for kernel color assessment creates supply bottlenecks.
- Nutraceuticals:Protein fortification systems and functional food ingredients incorporate cashew-derived components. This vertical climbs the fastest as wellness brands target amino acid profiles and healthy fat positioning.
Supply maturity centers on Food & Beverage. Nutraceuticals is gaining share fastest among end-use verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign-Trade Zone 183 in Dallas-Fort Worth accelerates cashew distribution concentration through deferred duty structures and expedited customs processing. Texas distribution hubs exploit this regulatory advantage to capture re-export flows toward Mexico and Caribbean markets. California's food processing corridor leverages complementary tax incentives under the California Competes Tax Credit program.
California
Plant-based protein demand drives dairy-alternative milk formulation growth across Los Angeles and Central Valley processing facilities. FDA nutrition labeling rules for tree nut health claims directly impact reformulation investments by manufacturers headquartered here. The Central Valley food processing corridor anchors captive supply chains from orchard through retail shelf, insulating operators against import tariff volatility.
Texas
Distribution infrastructure expansion concentrates in Dallas-Fort Worth and Houston metro areas serving cross-border trade flows. USDA grading standards enforcement through Texas Department of State Health Services permits elevates compliance costs for new entrants. Cold chain infrastructure investments across these hubs unlock shelf-stable product expansion into Mexican and Central American export markets.
New York Metro
Specialty retail and gourmet food service procurement drives flavored cashew SKU demand throughout Manhattan and Brooklyn distribution networks. FDA food safety modernization protocols mandate HACCP-certified facilities for handlers supplying this high-margin channel. Brooklyn-based direct-to-consumer brands leverage e-commerce subscription models to capture premium pricing from transparent sourcing narratives.
Illinois
Midwest manufacturing and food service institutional buyers anchor bulk container procurement through Chicago distribution terminals. Illinois Department of Agriculture processing permits require extended facility qualification cycles that disadvantage smaller importers. Chicago's rail and intermodal infrastructure positions handlers to serve Great Lakes region nut butter manufacturers and bakery inclusion processors.
United States Cashew Market Competitive Environment
California-based producers anchor the premium tier through captive orchard assets and vertical supply chain control; Texas distribution specialists hold logistics-advantaged positions in re-export and private-label supply. Market structure exhibits moderate consolidation with three distinct competitive archetypes: integrated orchard-to-retail operators, commodity-scale processors, and gourmet flavor specialists. Dominant competitive moves include backward integration into processing infrastructure and geographic expansion toward Texas distribution hubs to capture cross-border trade efficiencies.
Within the integrated operator archetype, The Wonderful Company and Blue Diamond Growers exemplify orchard-controlled supply chain positioning. Sahale Snacks occupies a specialist tier focused on flavored gourmet assortments. Archer Daniels Midland and Cargill represent commodity-scale processing and ingredient supply archetypes with broad industrial customer portfolios. These entities collectively illustrate the strategic segmentation between premium brand building and volume-driven ingredient supply.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| The Wonderful Company |
| Kraft Heinz |
| PepsiCo |
| Sahale Snacks |
| Blue Diamond Growers |
| Emerald Nuts |
| Cargill |
| Planters |
| Others |
Value Chain & Pricing Dynamics
FDA nutrition labeling rules tightening health-claim thresholds for tree nut products are forcing cashew manufacturers to absorb reformulation costs or pass them downstream, compressing margins for handlers lacking in-house R&D capabilities and reshaping procurement specifications across California's food processing corridor.
Pricing Analysis
Short lead-time premiums for W-240 through W-320 graded kernels command 15-25% markups over contract-of-take pricing as confectionery buyers rush to secure whiteness-index-compliant stock ahead of FDA enforcement deadlines. Three-tier pricing structure across premium confectionery-grade, standard retail-grade, and economy food-service-grade kernels stratifies the market, with California-based integrated operators capturing premium tiers while Texas distributors compete on spot volume. Cost compression in standard-grade segments is intensifying because West African harvest volatility feeds raw kernel price swings, and food-service buyers exhibit highest price sensitivity due to thin menu-margin economics.
Supply Chain Analysis
Freight cost differentials between containerized West African origin ports and California processing facilities versus Texas distribution hubs are driving procurement location decisions, with Vietnam, Ivory Coast, and India anchoring 85% of raw kernel supply. Domestic processing draws from steam-treated shelling outputs, roasted kernel inventories, and flavored coating inputs, with handlers resting on manual grading labor pools that face training bottlenecks. Single-source vulnerability concentrates in Vietnamese kernel supply during Tet holiday production shutdowns. Distribution runs through California's captive orchard-to-retail channels for premium SKUs and Texas re-export corridors for private-label volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around handlers with HACCP-certified facilities and in-house laboratory testing, as FDA food safety modernization protocols force capital-intensive compliance that weeds out smaller importers lacking facility qualification timelines.
For Market Incumbents: Extend backward integration into California processing infrastructure to insulate against import tariff volatility and capture premium-margins from transparent supply chain narratives that subscription-model retailers demand. Defend against emerging direct-to-consumer brands by locking exclusive kernel supply contracts with West African cooperatives before new entrants qualify for USDA grading standards. For New Entrants and Emerging Players: Begin with Texas distribution hub positioning to exploit Foreign-Trade Zone 183 deferred duty structures and serve underpenetrated Mexican and Caribbean re-export markets. Target nutraceutical applications as the most penetrable end-use vertical, leveraging clean-label protein fortification demand without requiring confectionery-grade whiteness expertise that incumbents dominate. For Investors and Strategic Acquirers: The window for entry favors mid-scale handlers with partial HACCP certification and established Texas logistics relationships that can scale through targeted facility investments rather than greenfield builds. Watch FDA tree nut allergen threshold updates as the signal for accelerated M&A activity, as labeling reformulation timelines compress cash reserves of sub-scale operators into distressed sale scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Facility Certification | FDA food safety modernization protocols mandate this credential for market access, elevating compliance costs for new entrants. |
| Backward Integration into Processing | California orchard-to-retail captive supply chains insulate operators against West African harvest volatility and tariff exposure. |
| Direct-to-Consumer Channel Launch | E-commerce subscription models enable California-based brands to capture deeper margins through transparent sourcing narratives. |
| Gourmet Flavor Portfolio Extension | Specialty retailers in urban coastal markets pay premium per-ounce pricing for differentiated offerings beyond commodity grades. |
| Texas Distribution Hub Expansion | Foreign-Trade Zone 183 deferred duty structures unlock re-export efficiencies toward Mexico and Caribbean markets. |
Study Parameters
USDA trade databases, FDA food safety modernization protocol filings, and California Department of Public Health processing permit records formed the secondary backbone of this analysis, cross-referenced with primary interviews conducted with kernel importers, HACCP-certified facility operators, and retail category buyers at California-based grocery chains. Bottom-up and top-down triangulation validated volume estimates across raw, roasted, and flavored product tiers.
Bottom-up modeling of kernel throughput by grade specification and packaging format converged with top-down value-chain analysis of California processing corridor capacity and Texas distribution hub flows across the projection horizon. Segmentation dimensions included product type, packaging format, customer category, and end-use industry vertical. CAGRs derived from historical trade flow patterns and projected plant-based protein demand absorption rates, with FDA regulatory timeline assumptions and West African harvest cycle variability as key forecast inputs.
Underlying measurement precision varies by segment; bulk container and manufacturer-level data carry tighter precision than flavored SKU and direct-to-consumer channel estimates due to fragmented e-commerce reporting. Forecasts reflect documented assumptions about regulatory enforcement pacing and input cost trajectories. Stakeholders should weight assumptions against their own operating context and facility qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
Macadamia Nut Market