
 Nut Based Spread Market | 2026-2036
Nut Based Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Nut Based Spread Market Analytics
Premium organic certification is collapsing the gap between artisan and mass-market positioning. Ferrero International leverages its hazelnut supply chain control to sustain margin advantage in European retail. The J.M. Smucker Company anchors the peanut butter segment through decades of brand equity in North American supermarkets. Once Again Nut Butter Collective differentiates through worker-owned cooperative structure and certified organic sourcing.
Nut based spread denotes a viscous food preparation manufactured by grinding roasted or raw nuts into a paste, typically containing between 85% and 99% nut solids with optional added oils, sweeteners, or emulsifiers to achieve spreadable consistency at ambient temperature. The primary commercial purpose centers on delivering plant-based protein and unsaturated fat content for bread spreads, baking ingredients, and smoothie formulations. Almond and cashew varieties command the fastest expansion as consumers migrate from peanut-dominant purchasing toward tree-nut alternatives perceived as more nutrient-dense. Glass jar packaging retains dominance in premium channels despite squeeze bottle formats gaining traction in convenience-oriented retail.
FDA nutrition labeling mandates and USDA organic certification requirements shape formulation transparency and ingredient sourcing across the United States market. EFSA allergen threshold regulations and EU Green Deal sustainable sourcing frameworks govern European market access and supply chain accountability. Stakeholders must monitor evolving clean-label expectations and dual-carbon supply chain pressures to determine whether backward integration into nut cultivation or partnership with certified growers offers superior risk-adjusted positioning.
Market Dynamics
Clean-label formulation mandates and dual-carbon supply chain accountability are compressing margins while forcing rapid ingredient sourcing reconfiguration across nut-based spread manufacturing.
Growth Catalysts
- FDA Nutrition Facts Revisions:Updated added-sugar disclosure requirements accelerate reduced-sugar recipe development and reformulation investments among domestic manufacturers.
- Almond Cultivation Expansion:California's Central Valley and Mediterranean growing regions scale tree-nut output to meet clean-label protein demand from natural grocery channels.
- Glass Jar Premium Positioning:Artisan positioning through transparent packaging sustains price premiums in specialty retail against polyethylene squeeze-bottle convenience formats.
Market Restraints
- Hazelnut Supply Concentration:Turkish and Italian growing regions control over 70% of global hazelnut output, exposing European manufacturers to climatic volatility and geopolitical risk.
- Tree-Nut Allergen Labeling:EFSA threshold regulations and FDA Food Allergen Labeling requirements impose costly segregation protocols and facility certification burdens.
- Peanut Butter Substitution Elasticity:Commodity peanut spreads retain price advantage in mass-market retail, limiting tree-nut premiumization in price-sensitive household segments.
Strategic Opportunities
- EU Green Deal Sourcing Incentives:Carbon-border adjustment mechanisms and sustainable agriculture certifications reward deforestation-free hazelnut and cashew procurement from certified cooperatives.
- Smoothie Bowl Application Expansion:Foodservice channels and home-blending consumers adopt nut spreads as protein-dense topping alternatives to traditional dairy options.
- Direct-to-Consumer Subscription Models:Specialty roasters bypass conventional retail slotting fees through recurring delivery platforms targeting health-conscious urban households.
Industry Challenges
- Organic Certification Timeline Compression:USDA three-year transition requirements for conventional orchard conversion strain working capital for growers seeking premium pricing.
- Emulsifier Reformulation Complexity:Clean-label expectations eliminate palm oil and hydrogenated fat stabilizers, requiring costly texture engineering through mechanical processing innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nut Based Spread Market |
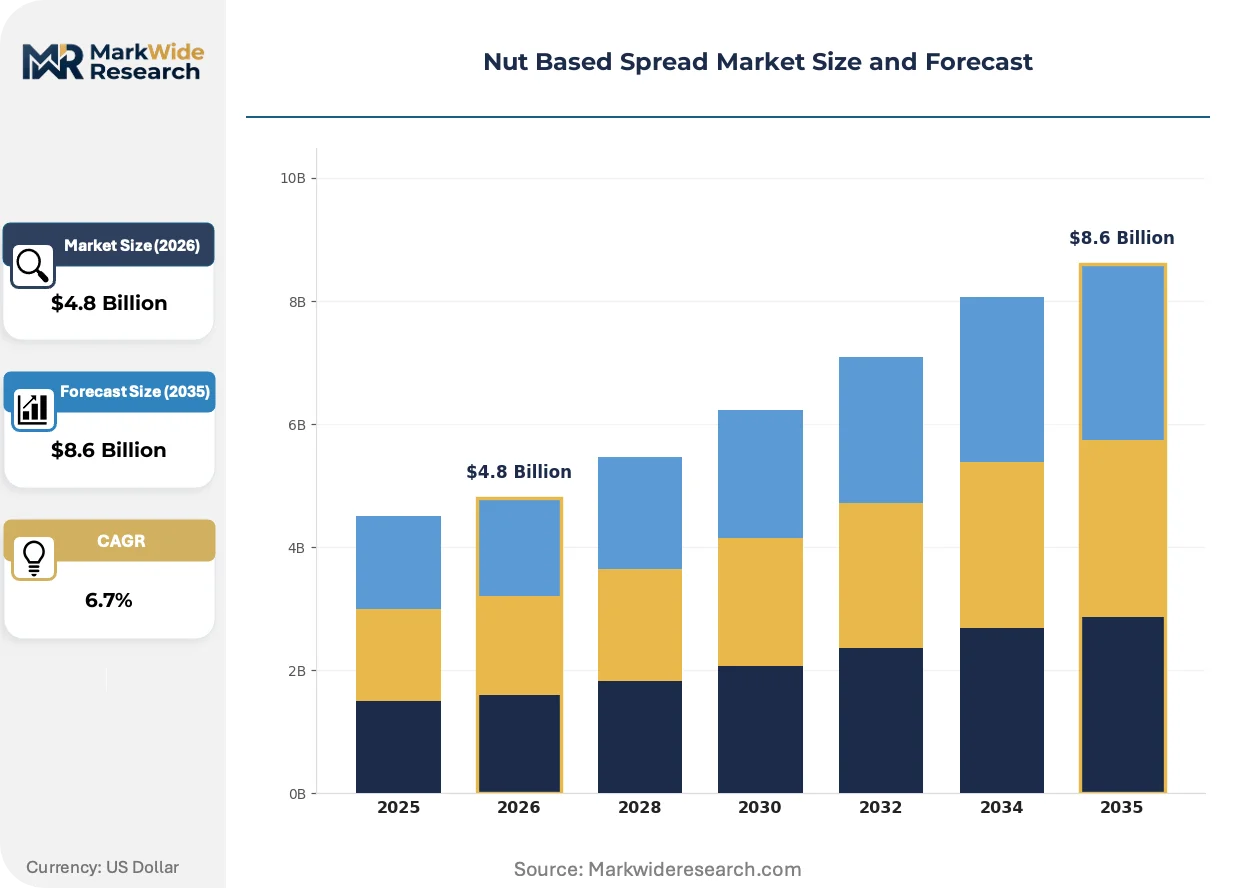
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond, Cashew, Peanut, Hazelnut Texture: Smooth, Crunchy, Creamy, Chunky Flavor: Chocolate, Vanilla, Maple, Spicy Packaging Type: Glass Jar, Plastic Tub, Squeeze Bottle, Pouch |
| Companies Covered | Ferrero International, Nestlé S.A., The J.M. Smucker Company, The Hain Celestial Group, Inc., Unilever Plc, The Kraft Heinz Company, Hormel Foods Corporation, Once Again Nut Butter Collective, Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nut Based Spread Market Evolving Landscape
Formulation transparency and mechanical processing advances are collapsing the traditional trade-off between shelf stability and ingredient simplicity in nut spread manufacturing.
High-pressure processing technology is supplanting thermal pasteurization in organic almond butter production. Premium private-label suppliers and cooperative processors adopt cold-pressure systems to preserve enzyme activity and raw-food positioning claims. This shift is compressing the shelf-life gap between conventional and raw-labeled products while commanding 15-30% retail premiums in natural channel placements.
EU Green Deal sustainable sourcing frameworks now mandate deforestation-free supply chain documentation for hazelnut and cashew imports entering European retail. Manufacturers must implement satellite-verified traceability systems and supplier audit protocols to maintain market access. Small-to-midscale producers face disproportionate compliance costs, accelerating partnership structures with certified grower cooperatives in Turkey and Vietnam.
Certification-driven purchasing patterns now dominate natural grocery channel assortment decisions. Retail buyers prioritize USDA Organic and Non-GMO Project verified SKUs over conventional alternatives, compressing shelf space for unverified mass-market brands. This behavioral shift concentrates volume in certified supply chains across Pacific Northwest and Northeast metropolitan markets where household penetration of specialty spreads exceeds national averages.
Nut Based Spread Market Segmentation
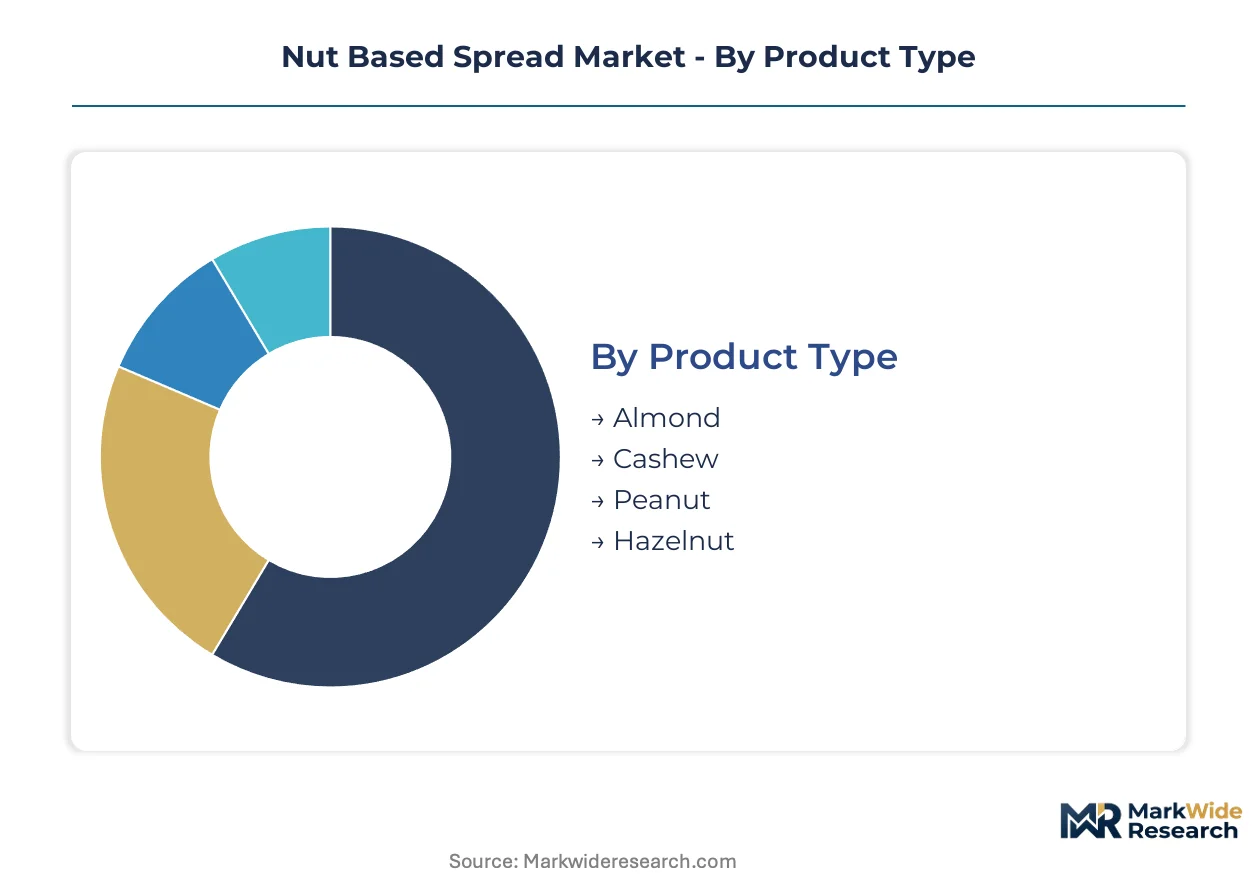
Nut spread manufacturers configure product portfolios across four intersecting dimensions. Substitution dynamics vary sharply by base nut and texture profile, dictating which segments defend margin against private-label encroachment.
Product Type:
Peanut spreads face the most intense substitution pressure from tree-nut alternatives in premium retail channels, while commodity positioning limits price elasticity in mass-market grocery.
- Almond:Ground from blanched or raw California almonds with 90-95% nut solids content and minimal added oil. Demand concentrates in Pacific Coast metropolitan natural grocery channels where clean-label protein sourcing drives household penetration.
- Cashew:Higher fat composition (46-50% by weight) yields silkier mouthfeel without emulsifier addition. European specialty retailers and US coastal urban markets absorb volume as consumers migrate from dairy-based spreads.
- Peanut:Roasted runner and Virginia varieties dominate volume production with 25-30% protein content. Price anchoring in conventional supermarkets resists tree-nut premiumization in heartland household segments.
- Hazelnut:Turkish and Italian origin nuts supply European chocolate-hazelnut formulations and artisan single-origin spreads. EFSA allergen labeling and EU Green Deal traceability requirements constrain supply chain flexibility.
Peanut anchors the volume base while almond gains share at the steepest rate.
Texture:
Processing intensity separates cost tiers, with mechanical grinding energy and particle-size control determining margin structure across manufacturing scale.
- Smooth:Homogenized particle size below 20 microns through multi-stage milling and high-shear mixing. Foodservice baking applications and child-oriented household purchases concentrate demand.
- Crunchy:3-8mm nut fragment inclusion provides tactile differentiation with minimal formulation change. Adult snacking occasions and texture-seeking natural channel consumers sustain 15-20% price premiums.
- Creamy:Intermediate particle distribution (50-100 microns) with added oil for pourable consistency. Breakfast and smoothie bowl applications in urban direct-to-consumer channels absorb volume.
- Chunky:Irregular fragment sizing from single-stage grinding preserves artisan positioning. Specialty cooperative processors and small-batch roasters dominate supply.
Smooth texture commands the volume base while crunchy climbs the fastest in premium channel placements.
Flavor:
Flavor adjacency determines whether spreads compete with confectionery, breakfast condiments, or savory cooking ingredients for shelf space and household budget allocation.
- Chocolate:Cocoa powder or chocolate liquor incorporation at 8-15% by weight creates dessert-spread hybrid positioning. European retail and North American natural channels drive formulation innovation.
- Vanilla:Natural extract or vanillin addition targets breakfast and baking applications. Clean-label expectations pressure manufacturers toward Madagascar or Tahitian origin specifications.
- Maple:Pure syrup or maple-flavored sweetener inclusion anchors regional identity in Northeast US and Canadian markets. Seasonal purchasing patterns concentrate volume in Q4 retail periods.
- Spicy:Chili flake, cayenne, or hot sauce infusion creates savory cooking ingredient positioning. Foodservice condiment channels and adventurous home cooks absorb limited but high-margin volume.
Chocolate flavoring anchors the volume base while spicy variants expand most quickly in experimental urban demographics.
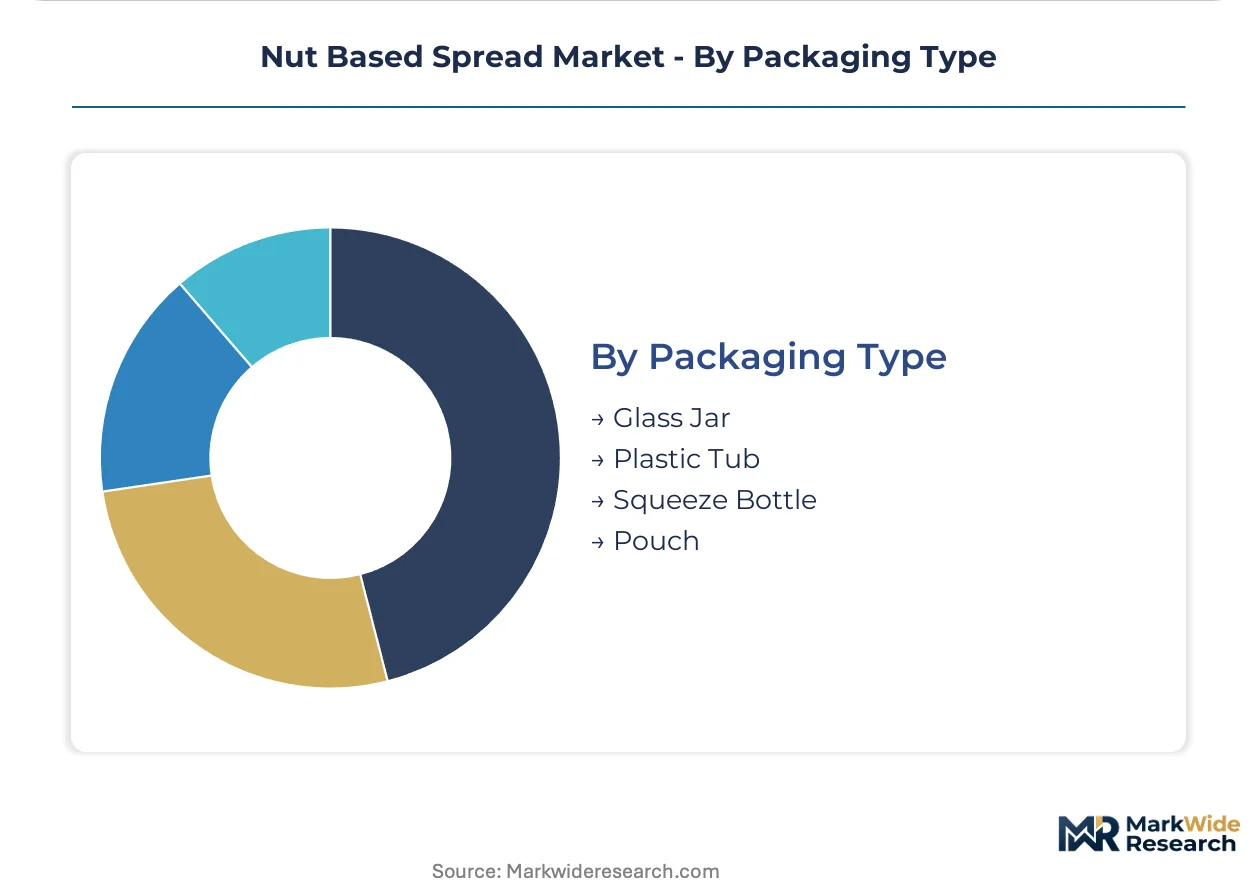
Packaging Type:
Material and format decisions lock in channel placement and price tier, with sustainability credentials increasingly influencing retail buyer assortment decisions.
- Glass Jar:Transparent 12-16oz containers with metal lug caps dominate premium natural channel placement. California and Northeast US specialty retailers mandate recyclable packaging for shelf access.
- Plastic Tub:Polypropylene wide-mouth containers optimize scoopability and shipping density. Mass-market club stores and conventional grocery value tiers absorb high-volume production.
- Squeeze Bottle:Flexible polyethylene with flip-top dispensing targets convenience-oriented household and foodservice single-serve applications. On-the-go consumption occasions drive format adoption.
- Pouch:Flexible film with spout or tear-notch configuration minimizes material weight and shipping cost. Direct-to-consumer subscription models and outdoor recreation channels test viability.
Glass jar packaging holds the volume base in premium channels while squeeze bottles gain fastest in convenience-oriented retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey ships hazelnuts to Italian and German chocolate manufacturers while California almonds flow to natural grocery channels across Japan and South Korea. These trade corridors concentrate value capture in origin-processing clusters and destination-market branding.
United States
Clean-label protein demand from Pacific Coast metropolitan households drives almond butter expansion. FDA updated Nutrition Facts labeling for added sugars accelerates reduced-sugar recipe reformulation. California's Central Valley dominates almond cultivation, with Sacramento and Fresno processing clusters supplying private-label and branded manufacturers.
Germany
EU Green Deal sustainable sourcing frameworks reshape hazelnut procurement for chocolate-hazelnut spreads. EFSA allergen threshold regulations impose facility segregation costs across Baden-Württemberg processing plants. Hamburg and Frankfurt natural grocery channels concentrate demand for certified organic cashew and almond varieties.
Italy
Piedmont hazelnut cultivation supplies domestic gianduja production and export-oriented spread manufacturing. EU deforestation-free supply chain documentation requirements mandate satellite-verified traceability from Turkish and Italian growers. Turin anchors artisan spread production, with regional cooperatives scaling output for European retail placement.
Japan
Health-conscious urban households in Tokyo and Osaka adopt almond and cashew spreads as dairy alternatives. METI food labeling standards govern allergen disclosure and organic claim verification. Kanto region distribution centers handle import volume from California and Vietnam, supplying convenience store and specialty retail channels.
Canada
Maple-flavored spread variants anchor regional identity in Quebec and Ontario breakfast markets. Health Canada nutrition labeling regulations align with FDA added-sugar disclosure frameworks. Toronto and Vancouver natural grocery channels absorb volume from US Pacific Northwest processors, with cross-border supply chains optimizing for organic certification parity.
Nut Based Spread Market Competitive Landscape
Listed leaders compete with private specialists across supply chain control and channel access. Ferrero International and Nestlé S.A. anchor the consolidated tier through captive hazelnut sourcing and European retail dominance, while cooperative structures and regional private-label suppliers fragment the organic and specialty segments. Strategic archetypes separate vertically integrated confectionery conglomerates from certified-organic cooperatives and commodity peanut butter processors. Competitive moves concentrate on backward integration into nut cultivation and direct-to-consumer subscription platform development.
Within the cooperative archetype, Once Again Nut Butter Collective exemplifies worker-owned governance and certified organic sourcing. Among listed conglomerates, Ferrero International and Nestlé S.A. occupy positions defined by hazelnut supply chain control and European retail shelf access. The J.M. Smucker Company anchors the North American mass-market tier through decades of peanut butter brand equity in conventional supermarket channels.
| Leading Market Players |
|---|
| Ferrero International |
| Nestlé S.A. |
| The J.M. Smucker Company |
| The Hain Celestial Group, Inc. |
| Unilever Plc |
| The Kraft Heinz Company |
| Hormel Foods Corporation |
| Once Again Nut Butter Collective |
| Conagra Brands, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between California almond processors and natural grocery distributors lock in both supply access and price visibility for certified organic SKUs, compressing margin volatility for vertically integrated handlers while exposing spot-market buyers to harvest-driven price swings.
Pricing Analysis
Mechanical processing generation gaps separate raw-labeled premiums from conventional thermal pasteurization tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA organic certification, with glass jar artisan positioning commanding shelf-space premiums over polyethylene convenience formats. Cost compression in mass-market peanut spreads intensifies because commodity input costs resist tree-nut premiumization. Price-sensitive heartland households in conventional supermarkets exhibit highest elasticity, while Pacific Coast metropolitan natural channel buyers show least sensitivity to organic certification premiums.
Supply Chain Analysis
Turkish Strait transit chokepoints expose European hazelnut-dependent manufacturers to geopolitical disruption and climatic volatility in concentrated growing regions. California, Turkey, and Vietnam anchor global nut supply, with almond cultivation drawing from Central Valley water districts, hazelnut sourcing resting on Black Sea coastal orchards, and cashew processing feeding from Mekong Delta cooperatives. Single-source vulnerability concentrates in Turkish hazelnut origination, where over 70% of European chocolate-hazelnut formulation inputs hinge on concentrated growing geography. Distribution runs through Sacramento and Fresno processing clusters for North American natural channel placement, with Hamburg and Rotterdam handling European import consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a clean-label recovery phase, with FDA added-sugar disclosure mandates and EU Green Deal traceability requirements acting as the cyclical catalyst forcing rapid formulation and sourcing reconfiguration.
For Market Incumbents: Shield margin position by securing backward integration into California almond cultivation or Turkish hazelnut orchards before organic certification timelines compress further. Invest in high-pressure processing capacity to defend raw-labeled price premiums against emerging cooperative processors. Channel control through direct-to-consumer subscription platforms offers defensive positioning against retail slotting fee escalation.
For New Entrants and Emerging Players: Lead with spicy flavor variants and smoothie bowl application positioning to capture experimental urban demographics underserved by legacy peanut butter brands. White space concentrates in direct-to-consumer subscription models targeting health-conscious households in Northeast US metropolitan markets. Go-to-market execution should emphasize certified organic sourcing transparency and worker-owned cooperative governance narratives.
For Investors and Strategic Acquirers: Certified-organic cooperative processors with established grower partnerships in Vietnam and Turkey represent the most attractive acquisition archetype for long-term positioning across the 5-10 year horizon. Signal to monitor: EU carbon-border adjustment mechanism implementation timeline and deforestation-free supply chain documentation enforcement intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nut Cultivation | Captive almond and hazelnut supply secures margin against California drought cycles and Turkish geopolitical risk. |
| High-Pressure Processing Capacity Addition | Cold-pressure systems preserve enzyme activity for raw-label premiums in natural channel placement. |
| Direct-to-Consumer Subscription Launch | Recurring delivery platforms bypass conventional retail slotting fees targeting urban health-conscious households. |
| EU Green Deal Certification Investment | Satellite-verified traceability systems maintain European market access under deforestation-free mandates. |
| Reduced-Sugar Recipe Reformulation | FDA Nutrition Facts compliance positions SKUs for natural grocery channel assortment priority. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with natural grocery category buyers, almond processing plant managers, cooperative grower representatives, and foodservice distribution procurement leads. Secondary validation drew from FDA labeling guidance documents, USDA organic certification databases, EU Green Deal regulatory filings, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category expenditure analysis.
Across the analysis window, projections incorporated nut type segmentation, texture profile tiers, flavor adjacency positioning, and packaging format channel placement. CAGRs were derived from historical volume trajectories adjusted for clean-label substitution elasticity and regulatory compliance cost pass-through. Forecast inputs included California almond bearing acreage expansion rates and EU carbon-border adjustment mechanism implementation schedules.
Underlying assumptions cover sustained clean-label protein demand growth and stable Turkish hazelnut origination, with deviation risk concentrated in California water policy shifts and EU deforestation-free enforcement intensity. Practitioners should keep alternative scenarios live as regulatory compliance timelines and climate volatility patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Fruit Kernel Products Market