
 Europe Nut-Based Spreads Market | 2026-2036
Europe Nut-Based Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nut-Based Spreads Market Foresight
Spain is fragmenting its nut-processing base as new regional co-operatives enter the spreads segment. Ferrero International S.A. anchors its European supply chain through established hazelnut sourcing networks in Italy. The J.M. Smucker Company competes through peanut butter variants tailored to continental taste profiles. Kraft Heinz Co. leverages its distribution scale to occupy shelf space across multiple sales channels.
Europe nut-based spreads comprise ground, roasted nut pastes with fat contents typically ranging from 45% to 60%, emulsified with oils, sweeteners, and stabilizers to achieve spreadable viscosity for direct consumption or foodservice incorporation. Hazelnut spread and almond spread command the widest household penetration, while cashew butter captures premium positioning in health food stores. Glass jars retain dominance in gift and premium segments, though pouches gain traction in convenience-oriented channels.
EFSA governs allergen labeling and nutritional claims under EU Regulation 1169/2011, while ECHA enforces REACH compliance for food-contact packaging materials. These frameworks elevate reformulation costs for entrants but protect established brands with compliant supply chains. Stakeholders must monitor evolving EU Green Deal packaging mandates and shifting procurement criteria from supermarket buyers prioritizing recyclable formats.
Market Dynamics
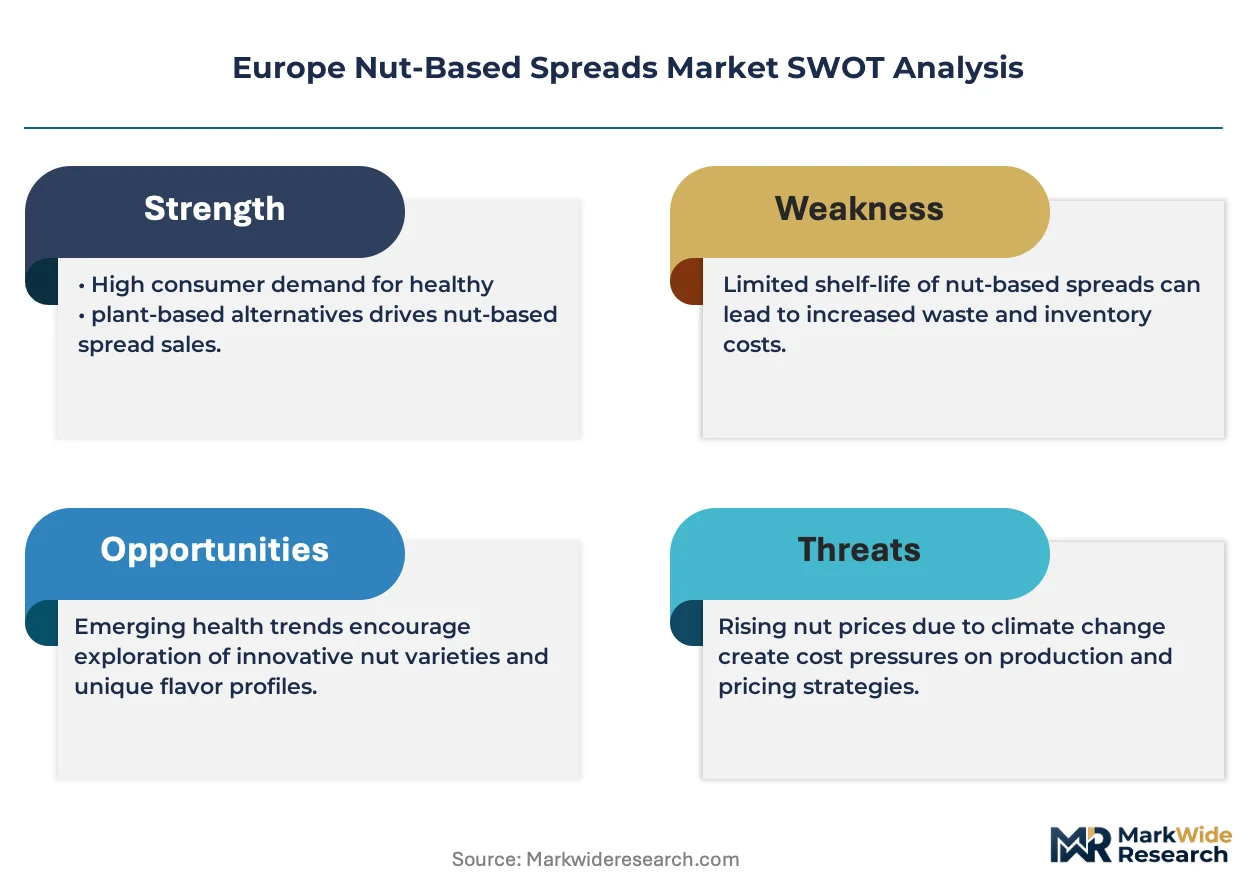
EFSA allergen labeling mandates under EU Regulation 1169/2011 are compressing formulation flexibility while supermarket buyers demand recyclable packaging formats, forcing simultaneous compliance investment across R&D and supply chain operations.
Growth Catalysts
- Clean-label reformulation:German households are rejecting palm oil and artificial emulsifiers, pulling manufacturers toward minimal-ingredient hazelnut and almond spreads with transparent supply chains.
- EU Green Deal packaging mandates:The framework's 2030 recyclability targets are accelerating glass-to-paper transitions in premium gift segments, creating first-mover advantages for compliant suppliers.
- Urban premiumization:Paris and Milan consumers are paying price premiums for single-origin nut spreads with provenance documentation, expanding addressable market in metropolitan retail.
Market Restraints
- Hazelnut supply concentration:Turkish and Italian growers control over 70% of European hazelnut supply, exposing processors to climate-driven crop volatility and currency fluctuations.
- EFSA nutritional claim restrictions:The regulation's strict health-claim verification is blocking "high protein" and "low sugar" positioning for reformulated spreads, limiting marketing differentiation.
- Seed butter substitution:Sunflower and pumpkin seed spreads are capturing allergen-avoidant households, particularly in UK and Nordic markets with high diagnosed nut sensitivity rates.
Strategic Opportunities
- Portuguese hazelnut expansion:The country's underdeveloped processing infrastructure offers greenfield entry for integrated roasting and milling operations serving Iberian markets.
- Foodservice portion control:Single-serve 20g sachets for hotel breakfast buffets and airline catering remain underpenetrated, with pouch technology enabling shelf-stable distribution.
- ECHA bio-based packaging incentives:REACH-compliant compostable films are receiving regulatory preference in public procurement, opening institutional channels for certified sustainable brands.
Industry Challenges
- Allergen cross-contamination protocols:Dedicated production lines for nut-free facilities require capital-intensive facility segregation, squeezing mid-scale processors.
- EFSA novel food approval timelines:Unconventional nut sources like tigernut and watermelon seed face 18-24 month safety assessment delays, blocking innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nut-Based Spreads Market |
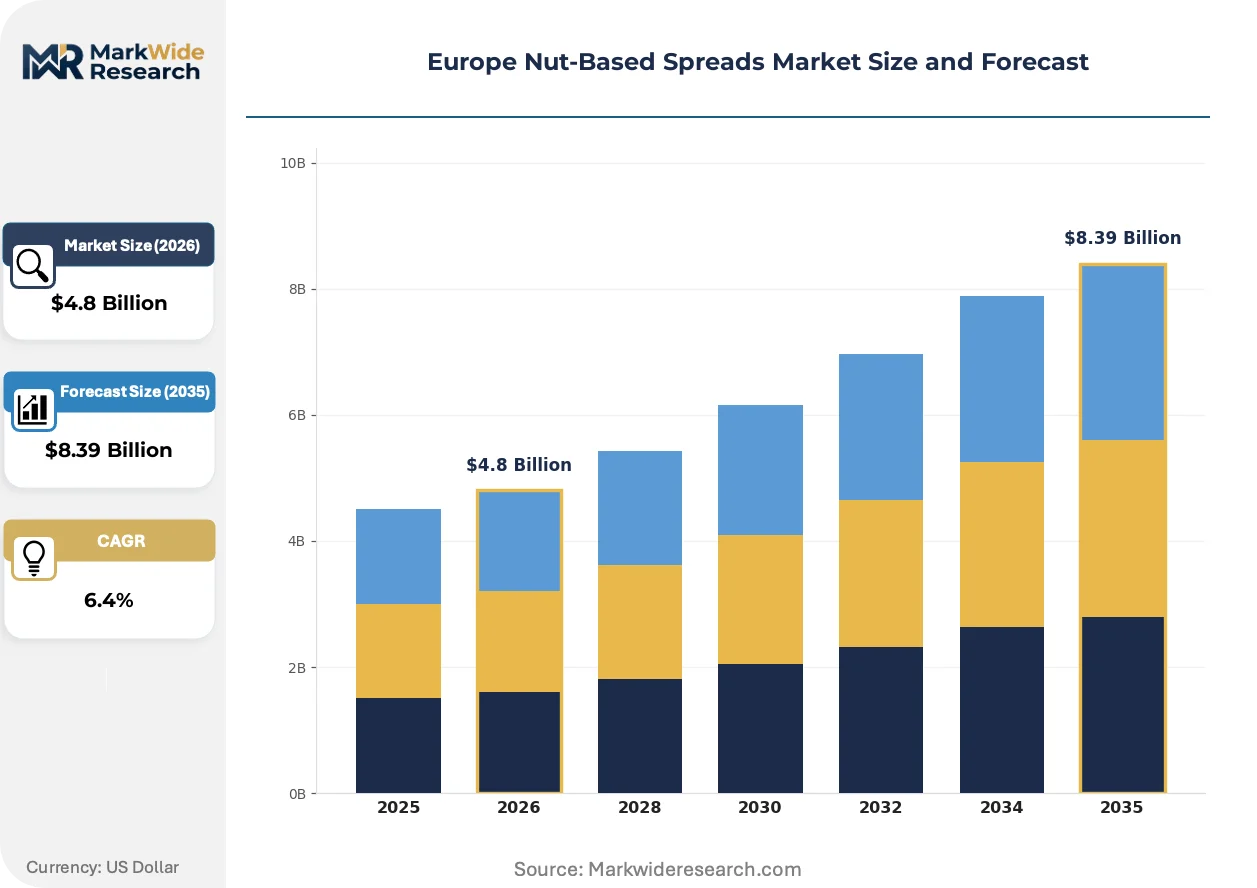
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Spread, Peanut Butter, Cashew Butter, Hazelnut Spread Packaging Type: Glass Jars, Plastic Containers, Pouches, Tubes End User: Households, Restaurants, Bakeries, Cafés Sales Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Grocers |
| Companies Covered | PIP & NUT LTD., The J.M. Smucker Company, The Hershey Company, Kraft Heinz Co., Ferrero International S.A., Unilever PLC, The Hain Celestial Group, Inc., Mondelez International Inc., SHS Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nut-Based Spreads Market Shifts & Advancements
High-pressure processing and cold-grind technologies are preserving volatile aromatic compounds while extending shelf life, reshaping quality benchmarks across the premium segment.
Cold-press oil extraction is rendering obsolete conventional roasted-paste production for raw-labeled spreads. Health-food retailers in Amsterdam and Copenhagen are prioritizing these SKUs, compressing margins for heat-treated alternatives and forcing legacy Italian processors to retool grinding lines.
EU Regulation 1169/2011's 2023 amendments tightened precautionary allergen labeling requirements. Manufacturers must now declare "may contain" traces at stricter thresholds, increasing reformulation costs but protecting compliant brands from liability exposure in German and French retail.
Direct-to-subscription models are bypassing traditional grocery wholesale in UK and Dutch markets. Specialty roasters in London and Rotterdam are capturing recurring revenue through curated quarterly shipments, displacing supermarket loyalty programs among affluent urban households.
Europe Nut-Based Spreads Market Segmentation
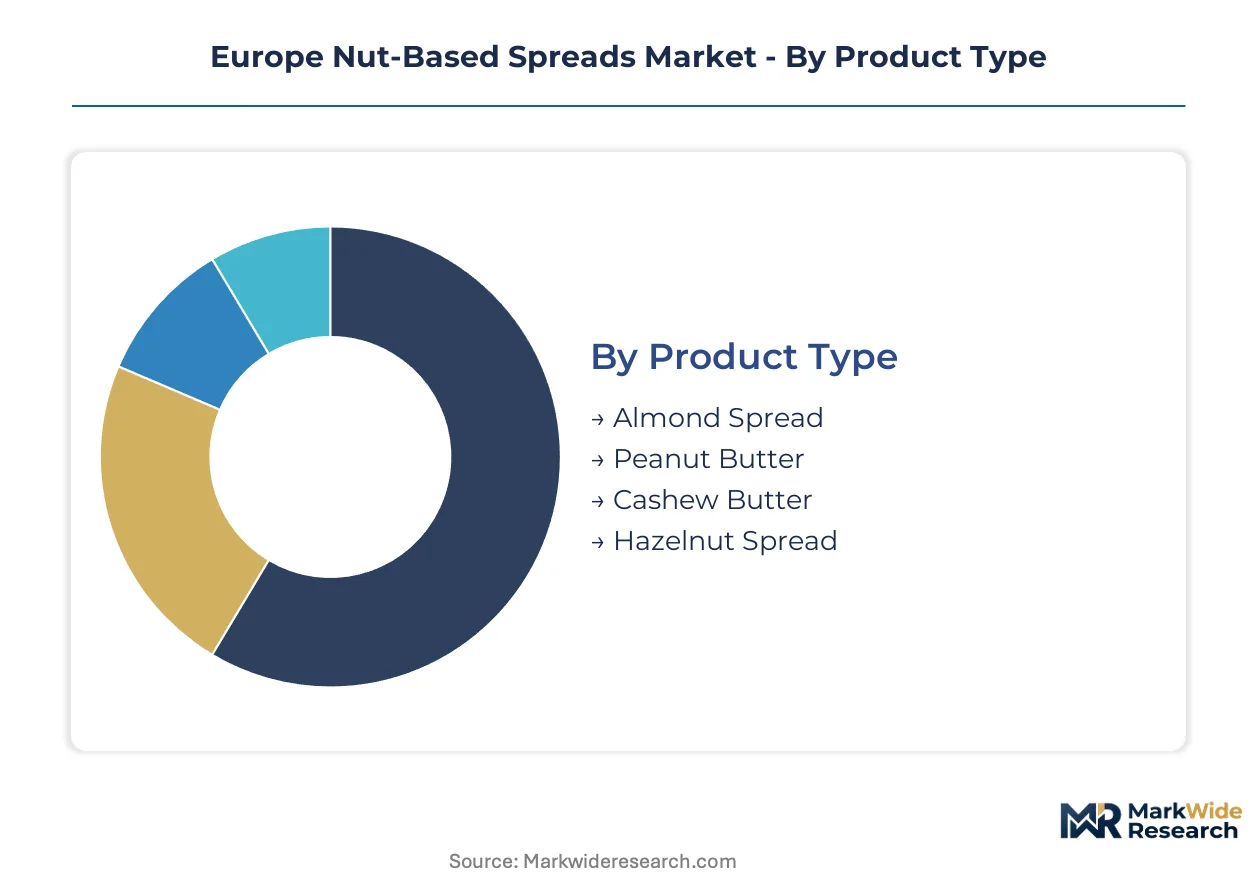
Segmentation in the Europe nut-based spreads market reveals distinct velocity profiles across product formats and channels. Cycle times vary dramatically: pouches turn in weeks while glass jars sit for months, forcing manufacturers to balance working capital against margin capture.
Product Type:
Cycle times compress from peanut butter's mass-market velocity to cashew butter's artisanal scarcity, with hazelnut and almond spreads occupying intermediate replenishment rhythms.
- Hazelnut Spread:Emulsified roasted hazelnut paste with 45-55% fat content, stabilized with lecithin and vegetable oils for shelf-stable viscosity. German and Italian households drive volume through breakfast ritual consumption, though palm oil scrutiny under EFSA labeling mandates is accelerating clean-label reformulation costs. Hazelnut spread anchors the volume base while cashew butter gains share at the steepest rate.
- Almond Spread:Single-origin or blended almond pastes with lower saturated fat profiles than hazelnut alternatives, positioned for health-conscious urban consumers. Paris and Milan retail clusters concentrate demand for transparent supply chain documentation, with EFSA allergen thresholds forcing dedicated production line investments.
- Peanut Butter:Roasted legume paste with established household penetration across UK and Dutch markets, competing on price-per-kilogram against tree-nut alternatives.
- Cashew Butter:Premium-positioned paste with creamy mouthfeel and lower allergen incidence, capturing health food store distribution in Amsterdam and Copenhagen clusters.
Margin structures stratify sharply: peanut butter competes on scale economics while cashew butter commands triple-digit price premiums per unit weight.
Packaging Type:
Cost tiers separate gift-oriented glass from convenience-driven flexible formats, with EU Green Deal recyclability mandates reshaping procurement criteria across supermarket buyers.
- Glass Jars:Premium and gift-segment staple with inert barrier properties preserving volatile aromatic compounds across 18-24 month shelf life. Italian and French urban centers concentrate demand for embossed and labeled variants, though ECHA REACH compliance for food-contact coatings elevates unit costs. Glass jars dominate value capture while pouches expand volume fastest.
- Pouches:Flexible laminated films with spout or tear-notch configurations, enabling single-serve portioning and reduced shipping cube. German discount retail and UK meal-kit channels are accelerating adoption, driven by EU packaging waste directive pressure on lightweighting targets.
- Plastic Containers:Polypropylene tubs with snap-fit lids, occupying mid-market peanut butter positioning through cost efficiency.
- Tubes:Aluminum or plastic laminate squeeze formats, capturing foodservice and travel retail convenience applications with portion-controlled dispensing.
Shelf presence fragments: glass commands visual authority in premium gifting, pouches penetrate convenience channels most aggressively.
End User:
Application intensity varies from household pantry stocking to foodservice just-in-time replenishment, with bakeries and cafés demanding technical specifications absent from retail formats.
- Households:Direct consumption segment with pantry replenishment cycles driving baseline production scheduling. German households exhibit strongest clean-label rejection of palm oil and artificial emulsifiers, pulling formulation standards upward across private-label suppliers.
- Restaurants:Foodservice incorporation for breakfast buffets and dessert applications, requiring ambient-stable bulk formats with consistent spreadability across temperature variation.
- Bakeries:Ingredient-input demand for viennoiserie filling and cake layering, specifying precise viscosity and fat crystallization behavior.
- Cafés:Artisan coffee shop segment sourcing single-origin nut spreads for toast and pastry pairing, with provenance documentation requirements matching specialty coffee sourcing standards.
Procurement concentration diverges: households fragment across retail channels while bakeries consolidate purchasing through wholesale distributors.
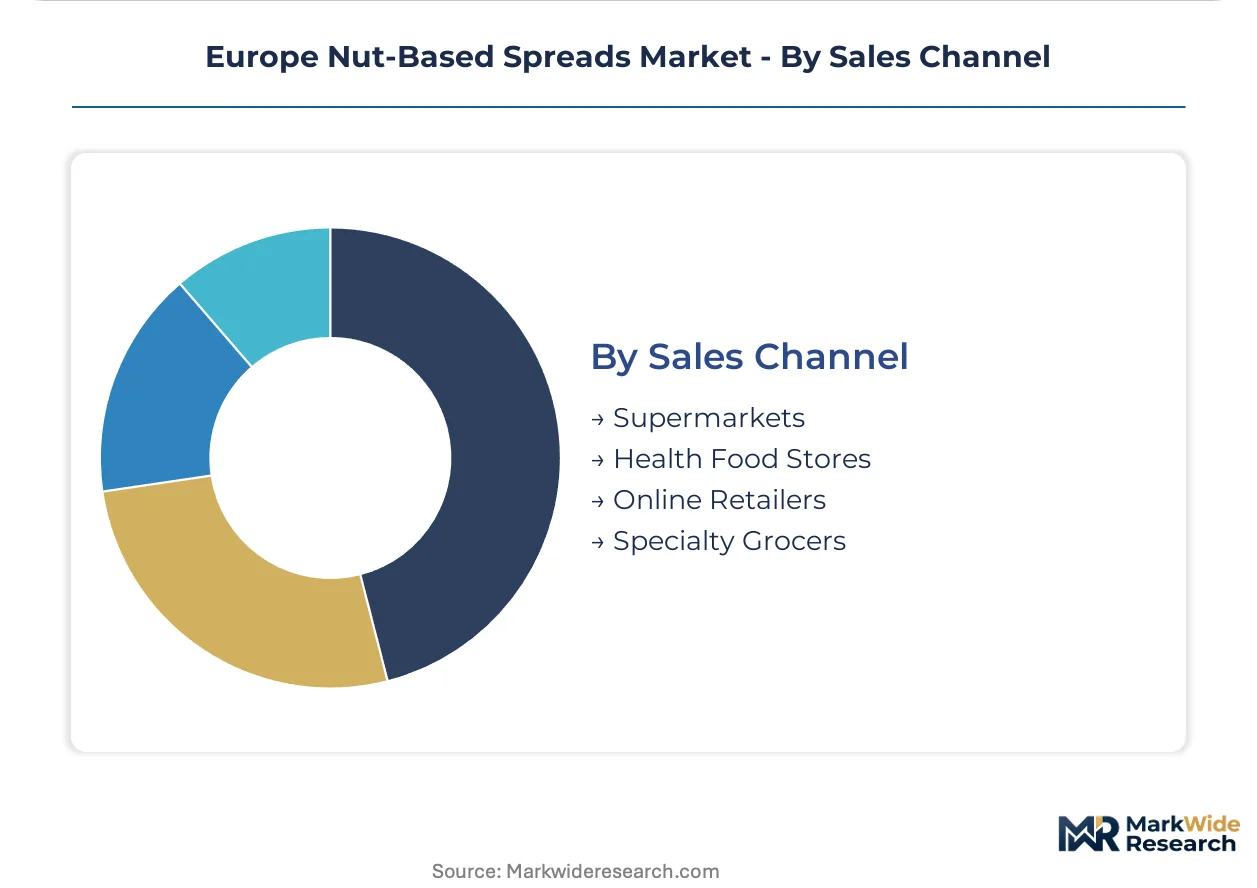
Sales Channel:
Customer type stratification separates mass-market supermarket velocity from specialty channel margin extraction, with online retail compressing geographic access constraints.
- Supermarkets:Mass-market volume engine with shelf-space competition driving slotting fee structures and promotional calendar dependency. French and German hypermarket chains are prioritizing recyclable packaging formats in buyer criteria, filtering supplier qualification.
- Health Food Stores:Curated assortment channel with certified organic and raw-labeled spread concentration, capturing Amsterdam and Copenhagen consumer clusters.
- Online Retailers:Direct-to-consumer and marketplace platforms enabling subscription models and geographic reach beyond physical retail footprint, with UK and Dutch markets showing strongest recurring shipment adoption.
- Specialty Grocers:Premium independent retail with localized assortment and staff-guided purchasing, concentrating single-origin and small-batch spread distribution in urban centers.
Channel momentum shifts: supermarkets defend volume dominance while online retail climbs fastest in recurring revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA governs allergen disclosure and nutritional claims across the European market, establishing baseline compliance costs that filter smaller processors from retail channels. National regulators layer additional requirements onto this framework, creating differentiated entry barriers across member states.
Germany
German households reject palm oil and artificial emulsifiers, pulling formulation standards toward minimal-ingredient hazelnut and almond spreads. The Federal Ministry of Food and Agriculture enforces strict implementation of EU Regulation 1169/2011 through state-level food inspection offices. Berlin and Hamburg retail clusters concentrate demand for transparent supply chain documentation, with discount chains prioritizing recyclable packaging formats in procurement criteria.
France
Paris consumers pay price premiums for single-origin nut spreads with provenance documentation, expanding addressable market in metropolitan retail. ANSM enforces pre-market notification requirements for novel food ingredients entering the French market. Île-de-France and Provence-Alpes-Côte d'Azur urban centers host specialty grocers curating small-batch spread assortments, displacing supermarket loyalty programs among affluent households.
Italy
Piedmont's hazelnut processing infrastructure anchors European supply chains for emulsified spreads, with Turin-based clusters maintaining roasting and milling operations. The Ministry of Health coordinates with EFSA on allergen threshold enforcement through regional veterinary services. Lombardy and Emilia-Romagna concentrate artisanal spread production, with Milan retailers demanding cold-grind technology for volatile aromatic preservation.
United Kingdom
UK consumers show strongest adoption of direct-to-subscription models, with specialty roasters capturing recurring revenue through curated quarterly shipments. The Food Standards Agency maintains precautionary allergen labeling requirements that exceed baseline EU thresholds. London and Rotterdam-adjacent distribution hubs facilitate cross-channel e-commerce fulfillment, bypassing traditional grocery wholesale.
Spain
Regional co-operatives are fragmenting Spain's nut-processing base as new entrants enter the spreads segment. The Spanish Agency for Food Safety and Nutrition enforces EFSA-aligned labeling through autonomous community inspection networks. Catalonia and Andalusia concentrate emerging processing capacity, with Barcelona logistics clusters serving Iberian markets.
Europe Nut-Based Spreads Market Competitive Landscape
Vertically integrated multinationals and specialist artisans split the market into distinct competitive spheres with minimal overlap in customer targeting. Consolidation pressures concentrate around hazelnut supply access and clean-label formulation capabilities. Three archetypes dominate: heritage confectionery houses with captive agricultural networks, diversified FMCG conglomerates leveraging distribution scale, and craft specialists exploiting subscription and specialty retail channels. Competitive moves center on backward integration into Turkish and Italian hazelnut sourcing, plus rapid portfolio diversification into seed butter alternatives for allergen-avoidant segments.
Within the heritage confectionery tier, Ferrero International S.A. and The Hershey Company exemplify supply chain anchoring through established agricultural relationships. Kraft Heinz Co. occupies a position among diversified conglomerates exploiting multi-channel distribution scale across European retail. The J.M. Smucker Company represents the specialist-adjacent archetype, with peanut butter variants tailored to continental taste profiles filtering through health food and conventional retail simultaneously.
| Leading Market Players |
|---|
| PIP & NUT LTD. |
| The J.M. Smucker Company |
| The Hershey Company |
| Kraft Heinz Co. |
| Ferrero International S.A. |
| Unilever PLC |
| The Hain Celestial Group, Inc. |
| Mondelez International Inc. |
| SHS Group |
| Others |
Supply & Pricing Matrix
Piedmont's roasting and milling clusters anchor European hazelnut paste supply, with Turin-based processors leveraging captive agricultural networks to command premium pricing in downstream emulsified spreads. This geographic concentration enables integrated operators to defend margin structures while forcing independent brands toward contract-manufacturing arrangements with less pricing leverage.
Pricing Analysis
Paris and Milan retail clusters exhibit 40-60% price premiums over German discount channels for equivalent hazelnut spread formulations, reflecting urban provenance documentation requirements and specialty grocer distribution costs. Three-tier pricing structure across premium single-origin, standard blended, and economy private-label levels stratifies the market, with clean-label certification and transparent supply chain documentation as the primary differentiation drivers. Cost compression in the mid-tier is intensifying because EFSA allergen labeling mandates are elevating reformulation expenses across all processors. Discounter channels in Germany and Spain show highest price sensitivity, while Amsterdam and Copenhagen health food stores absorb triple-digit premiums for raw-labeled and cold-grind alternatives.
Supply Chain Analysis
Italian and Turkish contract processors hold dominant roasting and milling capacity for European hazelnut spreads, with Ferrero's captive supply networks and independent Piedmont co-operatives serving distinct customer tiers. Raw material inputs draw from Turkish and Italian hazelnut orchards, vegetable oil refineries in Rotterdam and Hamburg, and lecithin suppliers concentrated in Benelux chemical clusters. Single-source vulnerability in Turkish hazelnut supply exposes processors to climate-driven crop volatility and lira-denominated procurement cost swings. Distribution runs through supermarket central warehouses in France and Germany, health food store regional distributors in Netherlands and Denmark, and direct-to-subscription fulfillment centers serving UK urban households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates and EFSA allergen disclosure tightening are reshaping competitive positioning, creating first-mover advantages for compliant suppliers while squeezing mid-scale processors with simultaneous R&D and facility investment requirements.
For Market Incumbents: Pre-empt seed butter substitution threats by accelerating clean-label reformulation pipelines and securing backward integration into Portuguese hazelnut expansion zones before Turkish supply volatility escalates. Lock in recyclable packaging supplier agreements now to capture supermarket buyer preference shifts ahead of 2030 compliance deadlines. Prioritize dedicated production line segregation for allergen-free facilities to defend shelf space in UK and Nordic markets with elevated sensitivity rates. For New Entrants and Emerging Players: Portuguese hazelnut processing infrastructure represents the most penetrable entry point for integrated roasting and milling operations serving undersupplied Iberian markets. Foodservice portion control through single-serve sachet formats for hotel breakfast buffets and airline catering remains structurally underpenetrated, with pouch technology enabling shelf-stable distribution without legacy glass jar capital requirements. Direct-to-subscription models in UK and Dutch urban clusters offer recurring revenue capture with lower slotting fee burdens than supermarket wholesale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors craft specialists with cold-grind capabilities and established subscription customer bases over diversified conglomerates facing margin compression in conventional retail channels. Long-term viability rests on defensible agricultural sourcing relationships and regulatory compliance infrastructure rather than brand equity alone. Watch EFSA novel food approval timelines for unconventional nut sources as the signal indicating innovation pipeline unlock and category expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA allergen labeling mandates are pulling German and French households toward minimal-ingredient hazelnut and almond spreads with transparent supply chains. |
| Portuguese Hazelnut Expansion | Greenfield roasting and milling operations in underdeveloped Iberian processing infrastructure bypass Turkish supply concentration risks. |
| Foodservice Sachet Launch | Single-serve 20g pouch formats for hotel breakfast buffets and airline catering exploit underpenetrated portion control demand. |
| Subscription Model Buildout | Direct-to-consumer quarterly shipments in UK and Dutch markets displace supermarket loyalty programs among affluent urban households. |
| Recyclable Packaging Transition | EU Green Deal 2030 targets are accelerating glass-to-paper transitions in premium gift segments with first-mover procurement advantages. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA regulatory filings, EU trade customs records, and Nielsen retail audit data covering French, German, Italian, and UK supermarket channels. Interviews with category buyers at hypermarket chains, procurement directors at nut processing co-operatives, brand managers at heritage confectionery houses, and supply planners at flexible packaging suppliers informed demand and cost structure assumptions. Bottom-up volume builds across product type, packaging format, and sales channel segments were triangulated against top-down macro consumption trends.
Forecast inputs span clean-label adoption rates, EU packaging waste directive implementation timelines, and hazelnut crop yield volatility patterns across the projection horizon. Segmentation dimensions modeled include nut source type, processing technology tier, end-user application intensity, and regional regulatory cluster. CAGRs were derived from regression analysis of historical consumption velocity against demographic and regulatory driver indices, with cross-validation against processor capacity expansion announcements and supermarket buyer procurement criteria shifts.
Macroeconomic conditions sit as an overlay; deviation in eurozone consumer confidence indices, Turkish lira exchange rates, and energy costs for roasting operations would shift the trajectory. Quarterly review of EFSA novel food approval pipelines, EU Green Deal packaging mandate enforcement schedules, and hazelnut futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Macadamia Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Thailand Fox Nuts Market