
 Asia-Pacific Cashew Market | 2026-2036
Asia-Pacific Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cashew Market Outlook
Processing labor availability in Vietnam's Mekong Delta is collapsing as younger workers migrate to manufacturing hubs. Olam International leverages its integrated supply chain from African sourcing to Asian processing to sustain volume leadership. Vietcaj Co., Ltd. anchors its position through specialized raw cashew procurement networks in Cambodia and Laos.
Cashews are the kidney-shaped seeds of Anacardium occidentale, typically containing 47% fat and 18% protein by weight, with kernels extracted through steam roasting and shelling before grading by wholesome count per pound. The kernels serve as premium ingredients in confectionery, dairy alternatives, and plant-based protein formulations. Processed cashews dominate value capture as snack producers and confectionery manufacturers drive premiumization for roasted and flavored variants. Raw cashew nuts retain structural importance as upstream feedstock, with margin pools concentrating among processors with direct farmgate relationships in Binh Phuoc and Mangaluru.
FSSAI in India enforces stringent aflatoxin limits for imported nuts, while Vietnam's Ministry of Agriculture and Rural Development monitors pesticide residue protocols for export-bound kernels. China's SAMR and GB standards govern labeling and food additive rules for cashew products entering mainland distribution. Stakeholders must track evolving phytosanitary barriers between ASEAN members and monitor carbon accounting requirements that could reshape processing energy choices.
Market Dynamics
Labor migration from Vietnam's Mekong Delta processing hubs toward manufacturing zones is compressing kernel shelling capacity and forcing automation investments across Binh Phuoc province.
Growth Catalysts
- Plant-based protein expansion:Confectionery and dairy-alternative manufacturers across Southeast Asia are formulating cashew derivatives into premium ingredient streams.
- FSSAI aflatoxin enforcement:India's tightened import thresholds are filtering out non-compliant suppliers and rewarding processors with certified laboratory infrastructure.
- Binh Phuoc processing corridor:Vietnamese kernel grading and steam roasting clusters concentrate technical expertise and farmgate relationships that lower procurement friction.
Market Restraints
- Raw nut price volatility:African and Cambodian farmgate supply swings expose margin compression for processors lacking backward integration into orchards.
- Single-region labor dependency:Mekong Delta workforce attrition threatens seasonal shelling throughput without mechanized alternatives.
- Pesticide residue protocols:Vietnam's Ministry of Agriculture and Rural Development testing regimes disqualify batches from export-bound certification.
Strategic Opportunities
- Laos and Cambodia farmgate networks:Underdeveloped raw cashew collection infrastructure in these upstream markets offers first-mover procurement partnerships.
- Carbon accounting alignment:Emerging energy-use disclosure requirements favor processors investing in solar thermal roasting systems.
- China GB standards compliance:SAMR labeling and additive rules create a certification moat for Vietnamese exporters mastering documentation complexity.
Industry Challenges
- Steam roasting technician scarcity:Traditional kernel extraction skills are not transferring to younger workers migrating toward urban manufacturing.
- Grading automation capex:Wholesome-count-per-pound optical sorting systems require capital deployment that mid-scale processors struggle to finance.
- Phytosanitary documentation latency:ASEAN cross-border certificate harmonization delays are extending shipment clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cashew Market |
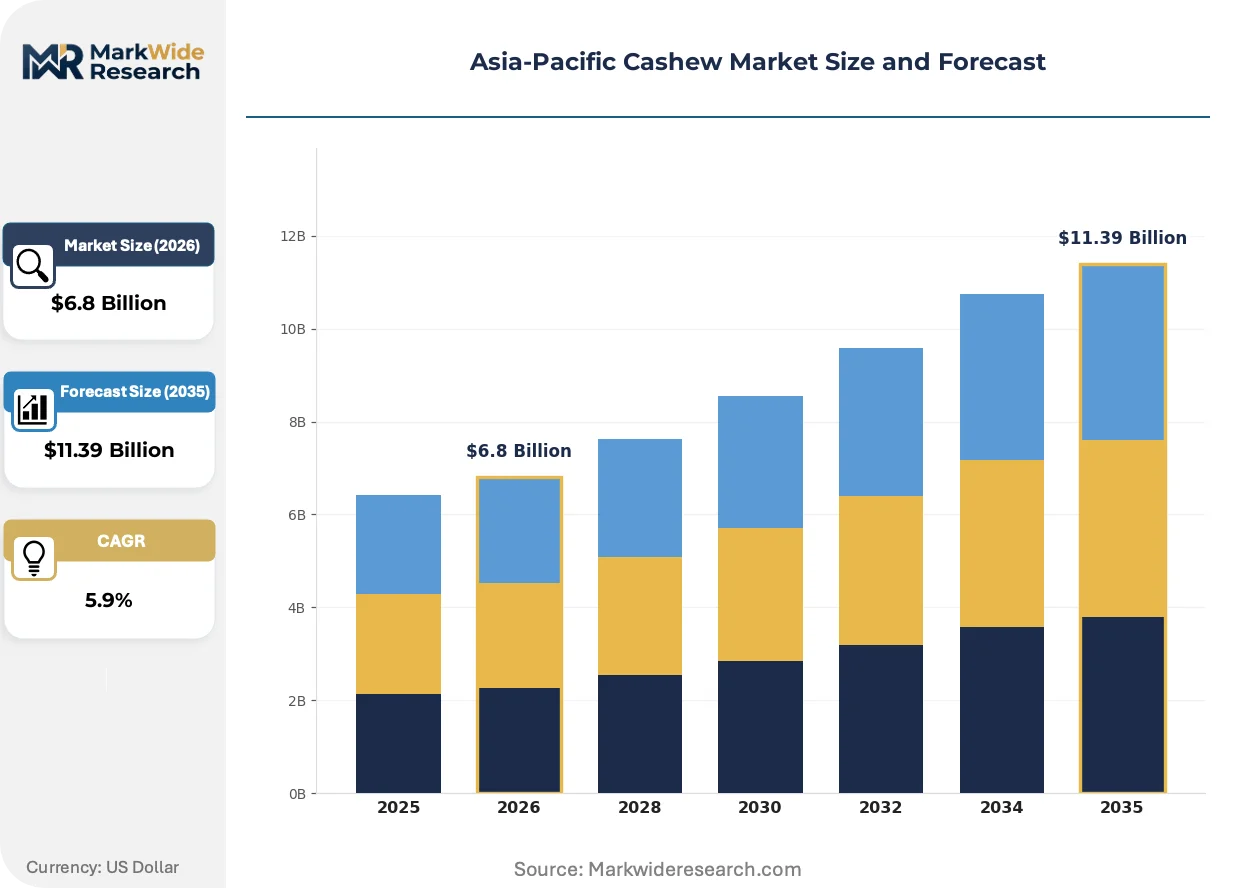
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashews, Processed Cashews, Cashew Butter, Cashew Milk End User: Food Industry, Snack Producers, Bakery Sector, Confectionery Manufacturers Distribution Channel: Online Retail, Supermarkets, Restaurants, Wholesale Packaging Type: Bags, Boxes, Vacuum Sealed, Bulk Packaging |
| Companies Covered | Olam International, Vietcaj Co., Ltd., Mangaluru Cashew Manufacturers, Charoen Pokphand Foods PCL, Agrocel Industries Pvt Ltd, Achal Cashew, Shivam Cashew Industry, Petrow Food Group, PAN Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cashew Market Strategic Shifts
Processing technology and regulatory compliance frameworks are converging to reshape competitive positioning across the Asia-Pacific cashew value chain.
Optical kernel grading systems are replacing manual wholesome-count assessment with machine vision that sorts by size, color, and defect density. Mid-scale processors in Binh Phuoc are piloting these units to offset labor shortages. The technology is miniaturizing capital requirements for automated quality control, enabling smaller facilities to achieve export-grade certification previously reserved for integrated multinationals.
FSSAI's tightened aflatoxin B1 and total aflatoxin limits for imported nuts are forcing laboratory infrastructure investments at port-of-entry inspection points. Indian customs authorities are rejecting containers lacking third-party certified pre-shipment analysis. Vietnamese exporters with in-house HPLC testing capabilities are capturing displaced volume from processors dependent on external laboratory turnaround.
Snack manufacturers are consolidating supplier relationships around processors offering integrated roasting, flavoring, and retail packaging services. This specification compression is displacing raw kernel traders who previously supplied commodity-grade inputs to brand-owning confectioners. Thailand and Indonesia represent the strongest adoption geography, where private-label snack producers are sourcing finished retail packs rather than bulk kernels.
Asia-Pacific Cashew Market Segmentation
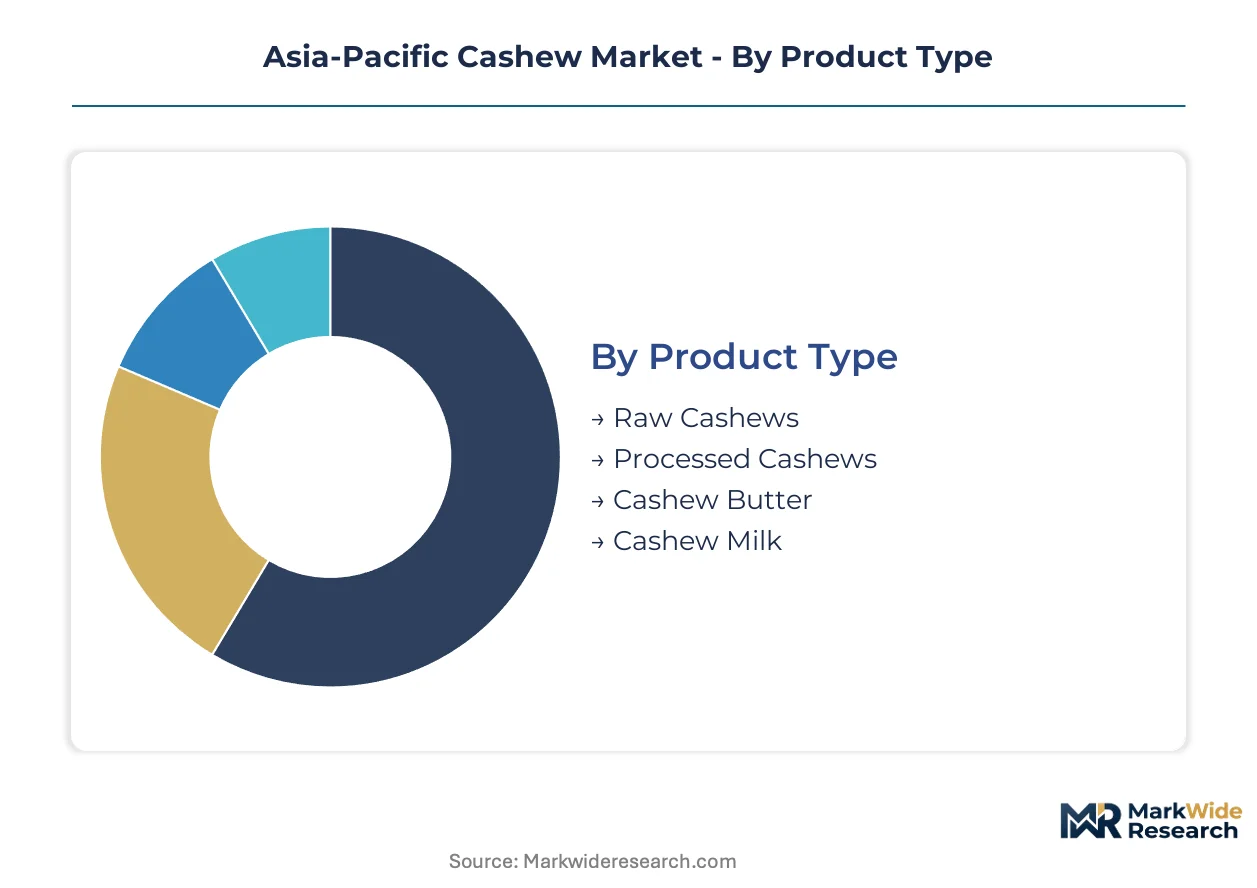
Segmentation in the Asia-Pacific cashew market reveals how regulatory differentiation, processing depth, and channel control determine margin capture across Vietnam, India, and Southeast Asian demand centers. Product form and distribution pathway directly shape compliance burden and pricing power for processors navigating FSSAI, SAMR, and ASEAN phytosanitary frameworks.
Product Type:
FSSAI aflatoxin thresholds and SAMR additive rules create divergent compliance costs across processed versus raw forms, with certified laboratory infrastructure becoming a segmentation-defining capability.
- Processed Cashews:Steam-roasted and shelled kernels graded by wholesome count per pound carry premium positioning in confectionery and snack applications. Vietnam's Binh Phuoc processors with in-house HPLC testing are displacing commodity traders as Indian customs reject containers lacking certified pre-shipment analysis.
- Raw Cashews:Unprocessed nuts with intact shells serve as upstream feedstock for integrated processors with direct farmgate relationships in Cambodia and Laos. Margin pools concentrate among operators controlling collection infrastructure in underdeveloped sourcing regions.
- Cashew Butter:Ground paste formulations targeting dairy-alternative and plant-based protein manufacturers require sanitary processing certification under Vietnam's Ministry of Agriculture and Rural Development protocols.
- Cashew Milk:Beverage-grade extracts formulated for retail distribution face China's GB standards governing labeling and food additive disclosure requirements.
Processed cashews handle the majority of throughput; cashew butter is expanding most quickly on share as dairy-alternative manufacturers consolidate supplier relationships.
End User:
Customer type determines specification compression, with snack producers and confectionery manufacturers driving integrated roasting, flavoring, and packaging services that displace raw kernel traders.
- Snack Producers:Thailand and Indonesia private-label manufacturers are sourcing finished retail packs rather than bulk kernels, consolidating procurement around processors offering complete specification delivery. This demand profile rewards Vietnamese exporters mastering SAMR documentation complexity for China-bound shipments.
- Confectionery Manufacturers:Premium ingredient streams for chocolate and confectionery applications require defect-free kernel grades with certified aflatoxin compliance. FSSAI enforcement is filtering supplier bases toward processors with backward integration into Cambodian and Laotian farmgate networks.
- Food Industry:Broad-spectrum food service procurement spans bakery, dairy-alternative, and ingredient applications with varying tolerance for cosmetic kernel defects.
- Bakery Sector:Ingredient-grade cashew pieces and meal for baked goods applications prioritize cost position over whole-kernel presentation.
Snack producers represent the dominant volume anchor; confectionery manufacturers are gaining share fastest as premiumization accelerates certified-grade procurement.
Distribution Channel:
Channel selection dictates phytosanitary documentation burden and carbon accounting exposure, with cross-border wholesale facing ASEAN certificate harmonization delays.
- Supermarkets:Modern retail chains in Vietnam, Thailand, and Indonesia require finished retail packaging with full traceability documentation and compliance labeling for shelf-stable nut products.
- Online Retail:E-commerce platforms serving Chinese consumers demand SAMR-compliant labeling and additive disclosure with streamlined customs clearance protocols.
- Wholesale:Bulk kernel shipments to Indian processing and re-export hubs face FSSAI port-of-entry inspection with third-party certified pre-shipment analysis requirements.
- Restaurants:Food service distribution channels prioritize cost-efficient bulk supply with lower specification stringency than retail-facing channels.
Supermarkets handle the majority of branded product throughput; online retail is climbing the fastest as direct-to-consumer penetration accelerates in China.
Packaging Type:
Packaging configuration aligns with distribution channel requirements and shelf-life specifications, with vacuum-sealed formats commanding premium positioning in climate-stressed storage environments.
- Vacuum Sealed:Oxygen-barrier packaging extends shelf stability for export-bound kernels facing extended shipping timelines through ASEAN cross-border corridors.
- Bulk Packaging:Industrial-scale containers for food manufacturing procurement minimize per-unit handling costs but require immediate processing upon receipt to manage aflatoxin risk.
- Bags:Consumer-facing flexible packaging dominates supermarket and online retail channels with portion-controlled and resealable configurations.
- Boxes:Rigid secondary packaging supports premium gift and specialty retail positioning in urban Vietnamese and Thai markets.
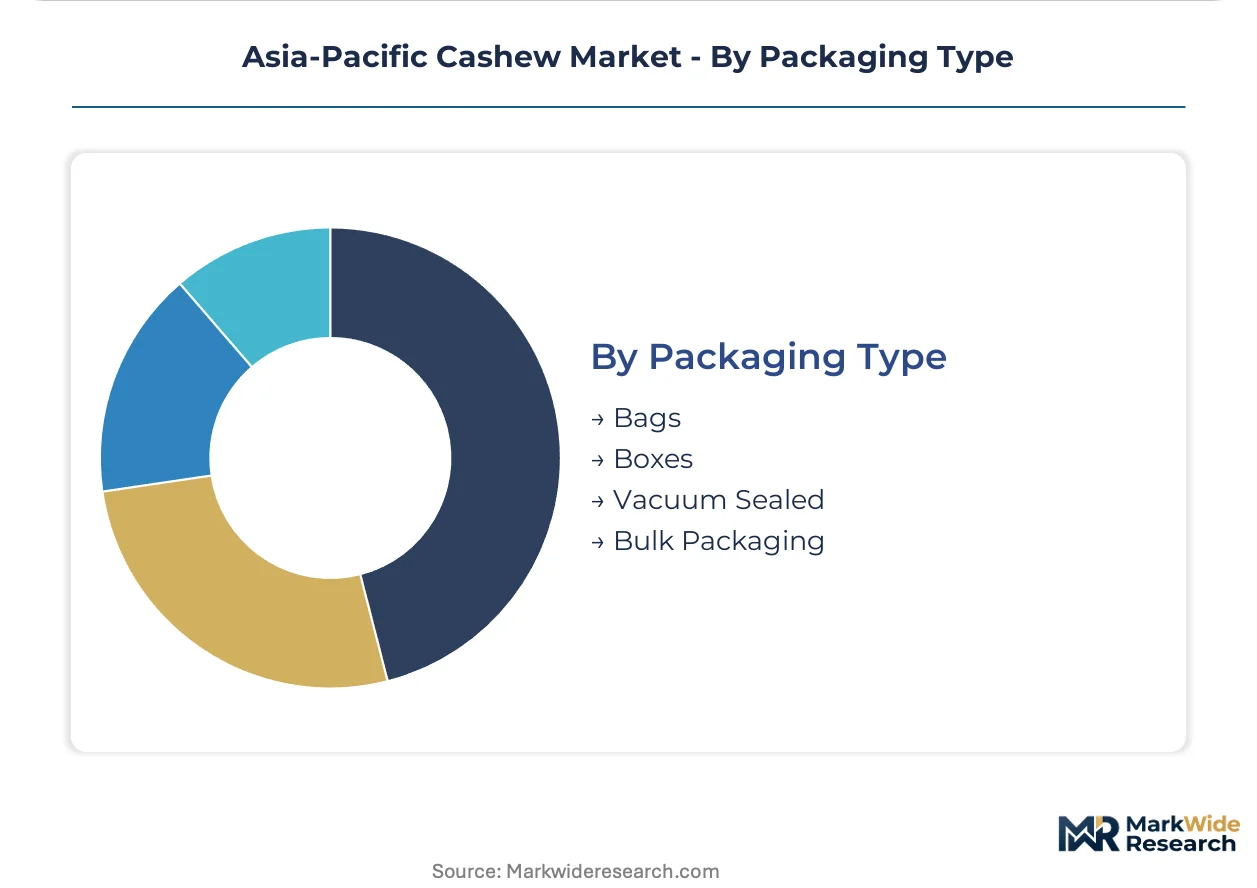
Bulk packaging handles the majority of raw kernel throughput; vacuum sealed is gaining share fastest as export certification standards tighten residue and contamination thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam processes kernels for export while India consumes domestically and re-exports; Thailand and Indonesia source finished retail packs rather than bulk inputs. This consumption-mix differential shapes procurement patterns across the region.
Vietnam
Binh Phuoc province hosts the densest concentration of steam-roasting and kernel-grading facilities serving export markets. FSSAI's tightened aflatoxin thresholds for Indian-bound shipments favor processors with in-house HPLC testing capabilities. Labor migration from the Mekong Delta toward manufacturing hubs is compressing shelling capacity and accelerating automation investments.
India
Mangaluru anchors domestic processing with farmgate networks in Karnataka and Kerala supplying raw feedstock. FSSAI mandates third-party certified pre-shipment analysis for all imported nuts, filtering supplier bases toward compliant Vietnamese exporters. Port-of-entry inspection infrastructure at Mumbai and Chennai is expanding laboratory capacity to handle rejection volumes.
Thailand
Private-label snack producers in Bangkok and Chonburi are consolidating procurement around processors offering integrated roasting, flavoring, and retail packaging. The country's national food safety regulator enforces pesticide residue protocols aligned with ASEAN harmonization efforts. E-commerce platforms serving urban consumers demand vacuum-sealed formats with full traceability documentation.
Indonesia
Java-based confectionery manufacturers drive premium-grade kernel demand for chocolate and bakery applications. Import licensing requirements from the national agricultural quarantine agency govern cross-border shipments from Vietnamese suppliers. Surabaya and Jakarta processing clusters are upgrading optical grading systems to meet export certification standards.
China
SAMR labeling and GB standards additive disclosure rules create documentation complexity for Vietnamese exporters accessing mainland distribution. Yangtze River Delta and Pearl River Delta retail channels prioritize SAMR-compliant finished packs over bulk kernel imports. Online retail penetration is climbing fastest as direct-to-consumer platforms streamline customs clearance protocols.
Asia-Pacific Cashew Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating among operators controlling African and Cambodian farmgate sourcing. The upper tier captures margin through backward integration into orchards and captive laboratory infrastructure. Mid-scale processors compete on specialized procurement networks and regional certification mastery. Dominant competitive moves include automation investments to offset labor attrition and strategic partnerships with Laotian and Cambodian collection cooperatives.
Among integrated supply chain operators, Olam International exemplifies the scale-driven archetype spanning sourcing to processing. Vietcaj Co., Ltd. occupies a position within the specialized procurement tier, anchoring regional presence through upstream relationships in Cambodia and Laos. Charoen Pokphand Foods PCL represents the diversified food conglomerate model, leveraging existing distribution infrastructure to capture snack and confectionery channel access.
| Leading Market Players |
|---|
| Olam International |
| Vietcaj Co., Ltd. |
| Mangaluru Cashew Manufacturers |
| Charoen Pokphand Foods PCL |
| Agrocel Industries Pvt Ltd |
| Achal Cashew |
| Shivam Cashew Industry |
| Petrow Food Group |
| PAN Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Vietnamese processors and Indian confectionery manufacturers lock in both supply access and price visibility, insulating buyers from African farmgate volatility while securing throughput for Binh Phuoc facilities facing labor attrition. These arrangements concentrate pricing power among integrated operators with captive laboratory infrastructure, leaving spot-market participants exposed to FSSAI rejection risk and margin compression.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Vietnamese exporters and Indian importers, with price differentiation driven by FSSAI certification tier and volume scale. Premium-grade kernels with pre-shipment HPLC analysis command substantial premiums over uncertified commodity grades. Cost compression in mid-tier processing is intensifying because Mekong Delta labor shortages force automation capex without immediate throughput recovery. Snack producers in Thailand and Indonesia show least price sensitivity due to specification compression toward integrated roasting and packaging services, while bakery sector buyers prioritize cost position over certification grade.
Supply Chain Analysis
Vietnam and India anchor kernel processing and consumption respectively, with Cambodia and Laos feeding raw nut supply into Binh Phuoc facilities. The chain draws from African farmgate sources, Cambodian collection cooperatives, and Vietnamese steam-roasting clusters. Single-source vulnerability concentrates in Mekong Delta shelling capacity where workforce migration threatens seasonal throughput. Distribution runs through ASEAN cross-border wholesale corridors facing phytosanitary documentation latency, with finished retail packs increasingly bypassing bulk kernel traders to reach supermarket and online retail channels directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific cashew market is cycling through a recovery phase as FSSAI enforcement filters non-compliant suppliers and rewards certified infrastructure investment. Raw nut price volatility and labor attrition create temporary margin pressure that favors operators with backward integration and automation deployment.
For Market Incumbents: Fortify procurement control through direct farmgate partnerships in Cambodia and Laos, securing upstream supply before collection infrastructure formalizes. Invest in optical grading and solar thermal roasting systems to offset Mekong Delta technician scarcity and align with emerging carbon accounting requirements. Defensive consolidation around laboratory certification capabilities will filter out commodity traders as FSSAI thresholds tighten further. For New Entrants and Emerging Players: Anchor in Laotian raw cashew collection networks where infrastructure gaps offer first-mover procurement partnerships before incumbent processors extend upstream. Target cashew butter and dairy-alternative ingredient streams where sanitary processing certification creates barrier entry against commodity kernel traders. A go-to-market angle mastering Vietnam's Ministry of Agriculture and Rural Development protocols for export-bound certification will unlock access to Thai and Indonesian private-label snack producers. For Investors and Strategic Acquirers: Specialized mid-scale processors with regional certification mastery and Cambodian farmgate relationships represent the most viable acquisition archetype for portfolio exposure to premiumization trends. Long-term viability hinges on automation deployment pace and carbon accounting alignment across the projection horizon. The signal to watch is ASEAN phytosanitary certificate harmonization progress, which would compress clearance timelines and reward processors with pre-positioned documentation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cambodian Farmgate Networks | Captures raw nut supply before collection infrastructure formalizes and prices escalate. |
| HPLC Laboratory Infrastructure Deployment | Enables FSSAI pre-shipment certification that displaces commodity traders at Indian ports. |
| Optical Grading Automation Investment | Offsets Mekong Delta labor attrition while achieving export-grade kernel classification. |
| Solar Thermal Roasting System Adoption | Aligns processing energy profiles with emerging carbon accounting disclosure requirements. |
| SAMR Documentation Compliance Program | Unlocks China-bound distribution through GB standards mastery for labeling and additive rules. |
Study Parameters
A spread of perspectives from Vietnamese processing plant managers, Indian customs laboratory directors, Thai private-label snack procurement leads, and Cambodian farmgate collection coordinators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from Vietnam's Ministry of Agriculture and Rural Development export statistics, FSSAI import rejection databases, ASEAN trade flow records, and SAMR regulatory filings. Bottom-up volume modeling from processor throughput data and top-down demand estimation from end-user procurement patterns were triangulated to constrain forecast variance.
Segmentation dimensions modeled include product form hierarchy, end-user specification intensity, distribution channel documentation burden, and packaging type shelf-life requirements across the projection horizon. CAGRs were derived from trend extrapolation of historical trade flows adjusted for regulatory enforcement intensity and labor force transition dynamics. Industry-specific forecast inputs incorporated FSSAI laboratory capacity expansion timelines and Mekong Delta migration patterns affecting shelling throughput.
Material uncertainties — African farmgate supply shocks, ASEAN phytosanitary harmonization delays, and carbon accounting mandate timing — sit outside the modeled envelope and could revise trajectory assumptions substantially. Recalibration cycles align with material shifts in FSSAI enforcement intensity and Vietnamese automation deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Brazil Nuts Market