
 United Kingdom Mattress Market | 2026-2036
United Kingdom Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Mattress Market Analytics
Online retail is tilting the United Kingdom mattress distribution map as direct-to-consumer logistics compress delivery windows and erode showroom dependence. Simba Sleep leverages data-driven product iteration to sustain repeat engagement in a low-frequency purchase category. Harrison Spinks anchors its competitive position through vertical wool farming and in-house spring manufacturing in Yorkshire. Silentnight Group dominates mass-market volume through supermarket and big-box partnerships that compete aggressively on price.
A mattress is a textile-based sleep support system comprising a core of steel coils, polyurethane foam, latex, or layered combinations encased in fabric ticking, engineered to distribute body weight and maintain spinal alignment over repeated compression cycles. Its primary commercial purpose is to deliver restorative sleep surfaces for residential bedrooms, hotels, care facilities, and student accommodations. Hybrid constructions now lead product type innovation as consumers seek pressure relief without the heat retention of all-foam designs. The hospitality sector within customer type captures disproportionate margin pools due to bulk contract pricing and brand specification requirements. King and Super King sizes command premium positioning as UK residential floor plans expand and co-sleeping configurations gain preference.
The UK's Furniture and Furnishings (Fire) (Safety) Regulations enforced by local trading standards offices mandate ignition resistance testing that elevates compliance costs for foam suppliers and favors domestic manufacturers with established certification pathways. REACH compliance administered by the Health and Safety Executive restricts certain chemical flame retardants, pushing material innovation toward natural fiber barriers and wool-based fire protection. BSI Kitemark certification for mattresses provides voluntary quality signaling that retailers increasingly demand for shelf placement. Stakeholders must monitor evolving fire safety consultations and chemical restriction proposals to anticipate reformulation timelines and inventory transition costs.
Market Dynamics
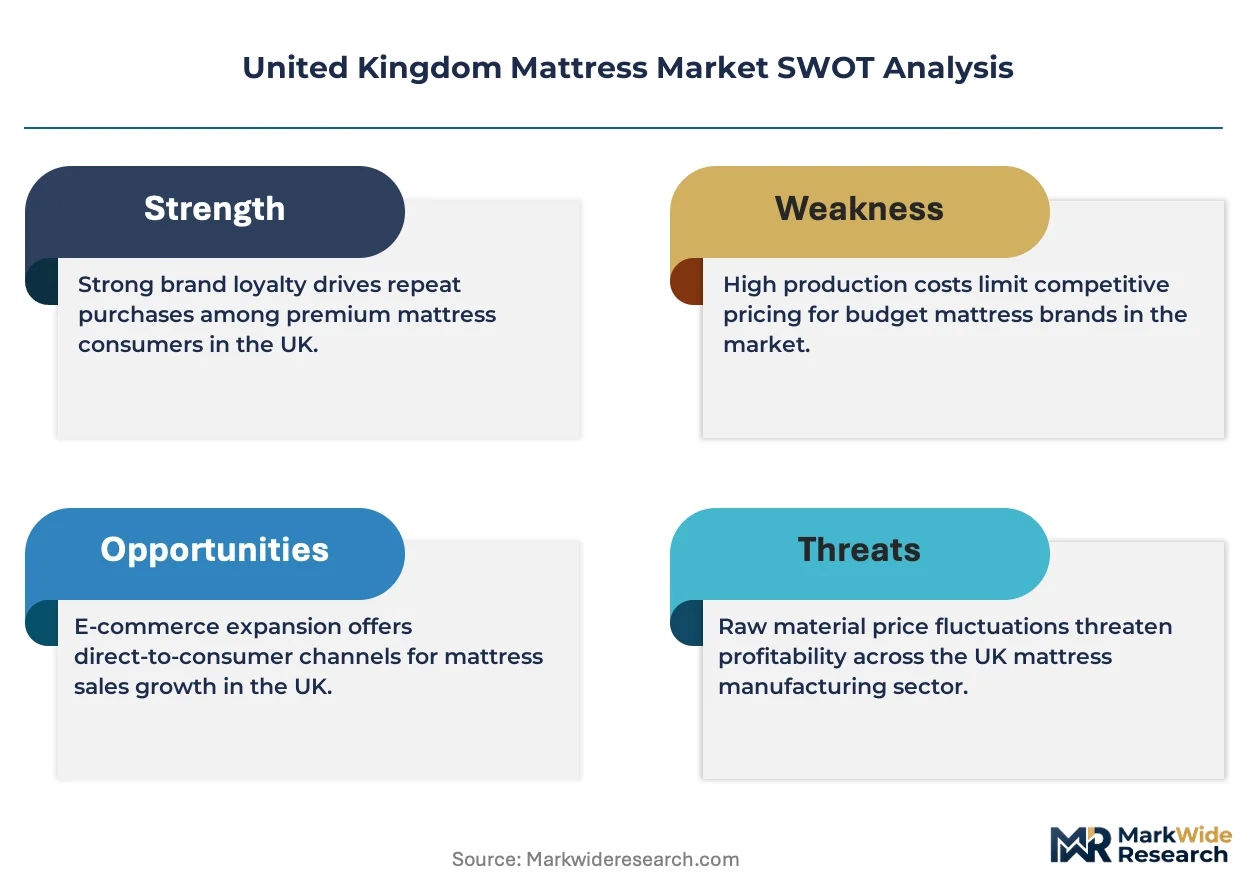
The Furniture and Furnishings (Fire) (Safety) Regulations are compressing foam formulation choices and elevating compliance costs, forcing domestic manufacturers toward natural fiber fire barriers while squeezing import competitiveness.
Growth Catalysts
- Hospitality refurbishment cycles:UK hotel chains are upgrading guest room standards with premium sleep products, creating sustained bulk procurement demand.
- REACH chemical restrictions:The Health and Safety Executive's flame retardant limitations are accelerating material innovation toward wool-based and natural fiber barriers.
- Hybrid construction adoption:Layered coil-foam combinations are capturing consumer preference as pressure relief without heat retention becomes the dominant purchase criterion.
Market Restraints
- Petrochemical input volatility:Polyurethane foam producers face margin compression from crude oil derivative price swings that resist downstream pass-through.
- Domestic manufacturing concentration:Yorkshire and Lancashire anchor spring and natural fiber supply, creating geographic vulnerability to regional labor shortages.
- Ignition resistance testing costs:Trading standards enforcement elevates per-SKU certification burdens that disproportionately burden smaller importers.
Strategic Opportunities
- Care facility specification:NHS procurement frameworks and private care home chains present underpenetrated volume for pressure-relief and antimicrobial constructions.
- Direct-to-consumer logistics:Compressed delivery windows and trial-period guarantees are eroding showroom dependence and enabling margin recapture.
- BSI Kitemark differentiation:Voluntary quality certification is becoming a retailer shelf-placement requirement, creating signaling value for compliant manufacturers.
Industry Challenges
- Reformulation timeline compression:Pending fire safety consultations force inventory transition planning with incomplete regulatory certainty.
- Skilled upholstery labor scarcity:Traditional hand-tufting and pocket spring assembly expertise concentrates in aging workforce demographics without replacement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Mattress Market |
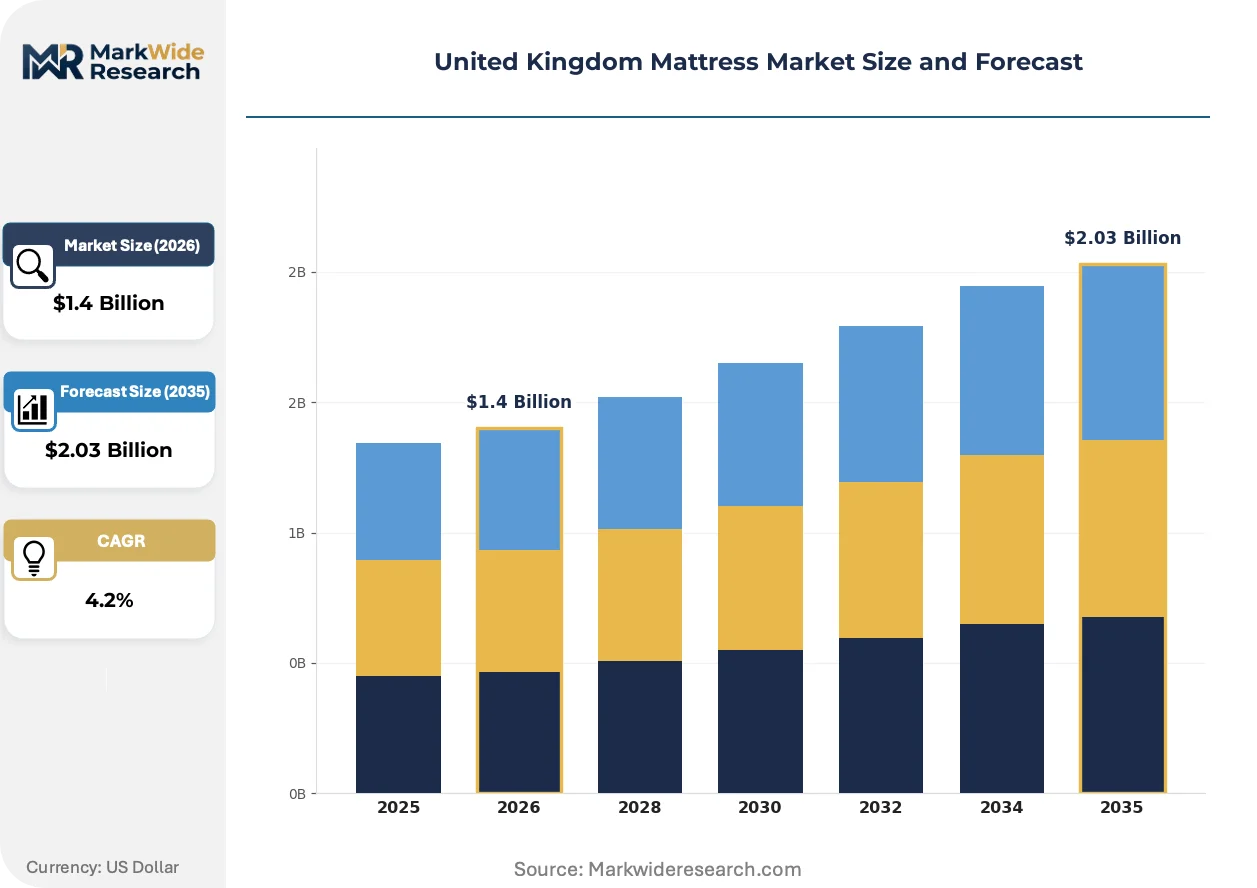
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Hybrid, Latex Customer Type: Retail Buyers, B2B Buyers, E-commerce Shoppers, Hospitality Sector Size: Single, Double, King, Super King Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Emma – The Sleep Company, Harrison Spinks, Dreams, Hypnos Beds, Sleepeezee, Silentnight Group, Simba Sleep, Eve Sleep, Tempur Sealy UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Mattress Market Evolving Landscape
Material virtualization, regulatory chemistry constraints, and channel disintermediation are converging to reshape how mattresses are engineered, certified, and delivered to UK households and institutions.
Sensor-embedded sleep tracking is virtualizing the mattress from passive support surface to active wellness device. Hospitality procurement teams in London and Edinburgh are piloting these systems for guest experience differentiation. The technology is compressing replacement cycle predictability and enabling subscription-based refresh models.
The UK's Furniture and Furnishings (Fire) (Safety) Regulations continue tightening chemical flame retardant allowances through trading standards enforcement. Foam suppliers are reformulating toward reactive phosphorus compounds and intumescent barriers that satisfy ignition resistance without restricted substances. Domestic manufacturers with established certification pathways capture shelf space as import compliance timelines lengthen.
Consumer purchase behavior is fragmenting across channel types as showroom visits decline and mobile-first discovery rises. Younger buyers in Greater Manchester and Birmingham are completing transactions through augmented reality visualization tools that reduce return rates. This pattern concentrates in urban rental markets where mattress replacement follows tenancy turnover rather than durability failure.
United Kingdom Mattress Market Segmentation
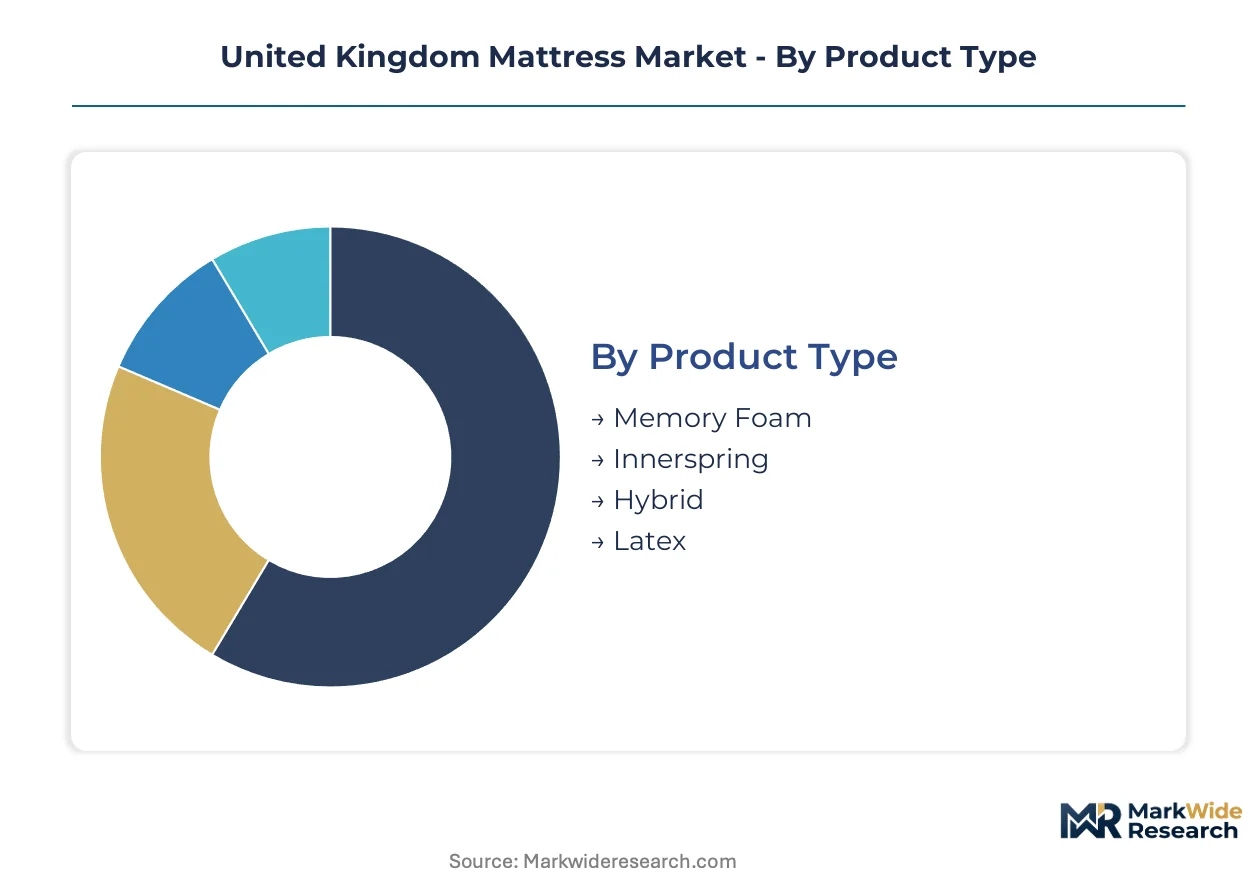
Cycle time variation across mattress segments creates divergent inventory strategies for UK manufacturers and retailers. Replacement intervals stretch from under three years in rental housing to over a decade in owner-occupied homes, fragmenting demand patterns by segment.
Product Type:
Replacement velocity splits sharply across construction technologies, with foam-dominant designs compressing faster than coil-based alternatives.
- Memory Foam:Viscoelastic polyurethane construction conforms to body contours through heat-activated softening. Rental markets in Greater London drive volume as landlords prioritize low upfront cost over longevity. REACH chemical restrictions are forcing reformulation toward water-based blowing agents and reduced volatile organic compound emissions.
- Hybrid:Layered pocket spring cores with memory foam or latex comfort layers balance pressure relief with airflow. Consumer preference is concentrating here as heat retention complaints against all-foam designs mount. Yorkshire manufacturers with captive spring production capture margin advantages unavailable to pure foam importers.
- Innerspring:Traditional Bonnell or offset coil systems with minimal comfort layering dominate budget hospitality procurement. Durability testing under BS EN 1957 standards separates domestic producers from import reliability failures.
- Latex:Natural rubber derived or synthetic polymer cores offer resilience and temperature neutrality at premium price points. Demand concentrates in eco-conscious households and private care facilities seeking antimicrobial surfaces without chemical treatments.
Innerspring anchors the volume base through mass-market penetration while Hybrid gains share at the steepest rate as consumers reject single-material compromises.
Customer Type:
Procurement authority and volume scale separate fragmented residential purchasing from concentrated institutional contracting.
- Retail Buyers:Individual consumers selecting mattresses through physical showrooms or online platforms for personal residential use. South East housing completions sustain replacement cycles tied to property transactions rather than product failure.
- Hospitality Sector:Hotel chains, serviced apartments, and boutique accommodations procuring bulk specifications with brand compliance requirements. London and Edinburgh property upgrades are driving premium sleep product standardization across three-star and above properties.
- B2B Buyers:Landlords, property management firms, and student housing operators purchasing standardized units for multi-unit residential portfolios. Volume discounts compress per-unit margins while ensuring predictable replacement scheduling.
- E-commerce Shoppers:Digital-native purchasers completing transactions through direct-to-consumer platforms with compressed delivery windows. Trial-period guarantees and hassle-free returns are eroding traditional showroom dependence in Greater Manchester and Birmingham urban cores.
Retail Buyers sustain absolute volume throughput while Hospitality Sector contracts expand most quickly as UK hotel chains compete on sleep quality differentiation.
Size:
Floor plan constraints and co-sleeping preferences are shifting dimensional demand toward larger formats.
- Double:Standard 135cm width configuration serving single occupants and compact bedrooms. Urban rental stock with restricted square footage maintains this segment's baseline volume.
- King:150cm width format gaining preference among couples seeking individual sleep space without super-premium pricing. New-build residential developments in the South East increasingly specify king-compatible bedroom dimensions.
- Super King:180cm luxury width commanding highest per-unit margins and specialized logistics requirements. Affluent suburban households and premium hospitality suites drive concentrated demand.
- Single:90cm width standard for children's rooms, guest accommodations, and institutional bunk configurations. Student housing and care facility procurement sustains predictable replacement cycles.
Double formats anchor volume through rental market penetration while King dimensions climb the fastest as residential floor plans expand.
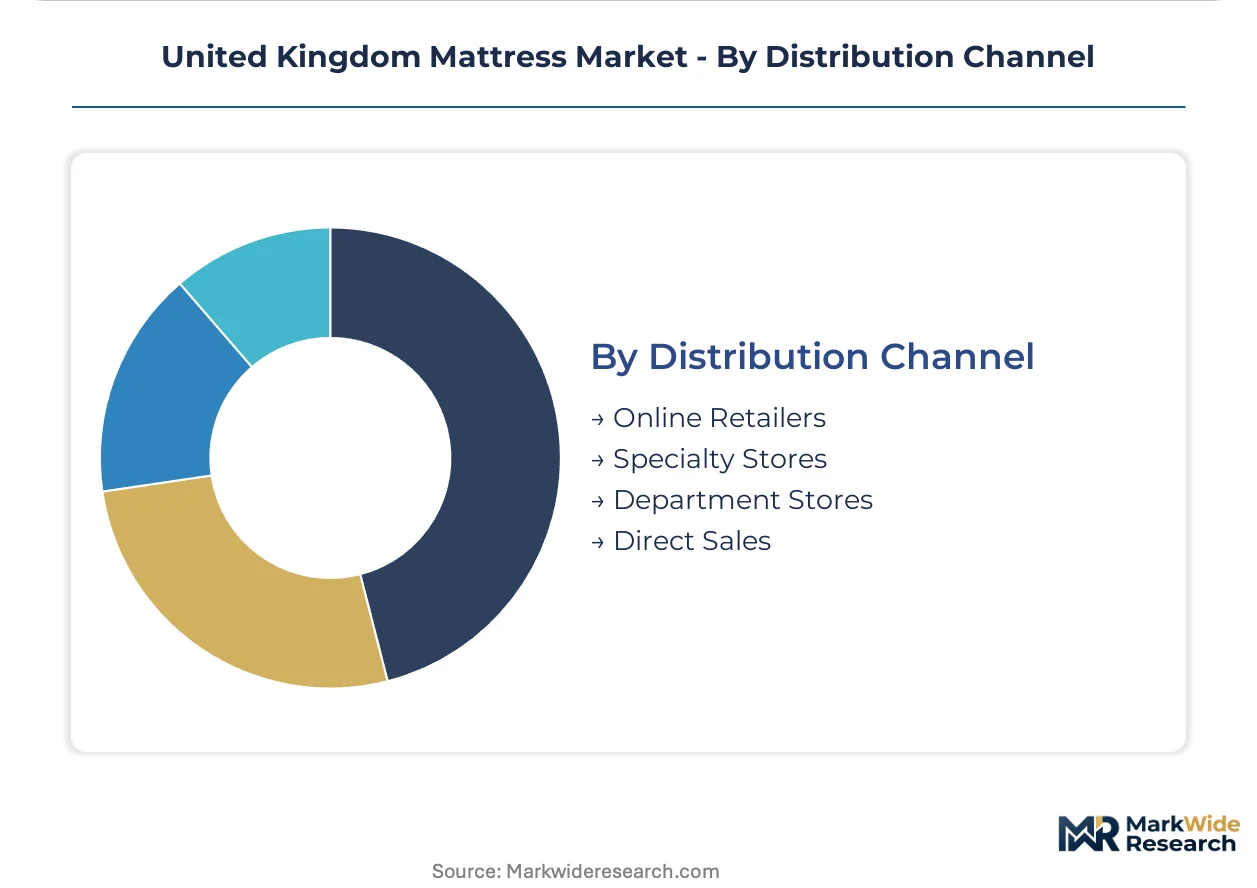
Distribution Channel:
Channel economics are fragmenting as logistics innovation compresses delivery windows and erodes showroom-dependent purchase patterns.
- Online Retailers:Platform-based and direct-to-consumer digital channels offering compressed delivery and trial guarantees. Mattress-in-a-box logistics have reduced freight costs and enabled margin recapture previously captured by physical retail.
- Specialty Stores:Dedicated mattress and bedding retailers providing tactile evaluation and sleep consultation services. High street presence concentrates in affluent suburban corridors where experiential purchasing persists.
- Department Stores:General merchandise retailers integrating mattress galleries within broader home furnishings offerings. Foot traffic dependency creates vulnerability to urban retail decline.
- Direct Sales:Manufacturer-owned showrooms and factory outlet channels controlling brand presentation and margin capture. Harrison Spinks and similar vertically integrated producers leverage Yorkshire manufacturing proximity for same-day delivery commitments.
Specialty Stores maintain the volume foundation through tactile purchase requirements while Online Retailers show the steepest expansion trajectory as logistics reliability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M1 motorway corridor and Felixstowe port infrastructure anchor England's mattress distribution network, enabling compressed delivery windows that sustain direct-to-consumer logistics across the island.
London and South East
New-build residential completions and rental turnover in Greater London drive replacement cycles tied to property transactions rather than product failure. Trading standards offices in the capital enforce Furniture and Furnishings (Fire) (Safety) Regulations through rigorous ignition resistance testing. Croydon and Dartford distribution hubs concentrate mattress-in-a-box fulfillment operations serving the densest UK population corridor.
Yorkshire and North England
Vertical wool farming and captive spring manufacturing in Leeds and Bradford supply domestic producers with natural fiber fire barriers compliant with REACH chemical restrictions. The Health and Safety Executive's regional enforcement accelerates material innovation away from restricted flame retardants. Sheffield's traditional upholstery workforce anchors hand-tufting expertise for premium pocket spring assembly.
Midlands
Birmingham and Leicester manufacturing clusters serve mass-market volume through supermarket and big-box retail partnerships. Local trading standards offices administer compliance certification that favors established domestic producers with testing infrastructure. Coventry's logistics positioning enables same-day delivery commitments to London and Manchester markets.
Scotland
Edinburgh hotel chains and Glasgow student housing sustain institutional procurement for standardized mattress specifications. Scotland's devolved environmental regulations align with UK-wide REACH implementation while maintaining distinct waste disposal frameworks for end-of-life mattress recycling. Aberdeen's energy sector workforce generates premium residential demand for king and super king formats.
Wales
South Wales manufacturing facilities leverage lower operational costs to supply budget-tier hospitality contracts across England. Welsh trading standards participate in UK-wide fire safety enforcement while regional development agencies support natural fiber processing investments. Newport's port access facilitates latex and foam raw material imports for hybrid construction producers.
United Kingdom Mattress Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated domestic producers and direct-to-consumer digital natives, with mass-market retail partnerships sustaining a fragmented middle tier. Three strategic archetypes dominate: Yorkshire-based manufacturers with captive natural fiber supply, data-driven sleep technology platforms, and supermarket-affiliated volume players competing on price compression. Competitive moves center on backward integration into wool farming and spring manufacturing, plus compressed logistics networks that erode showroom dependence.
Within the vertically integrated tier, Harrison Spinks anchors natural fiber mattress production through Yorkshire-based wool farming and in-house spring manufacturing. Simba Sleep occupies the data-driven platform position, leveraging iterative product development and direct-to-consumer logistics. Silentnight Group exemplifies mass-market scale, dominating volume through big-box retail partnerships that prioritize price accessibility over margin capture.
| Leading Market Players |
|---|
| Emma – The Sleep Company |
| Harrison Spinks |
| Dreams |
| Hypnos Beds |
| Sleepeezee |
| Silentnight Group |
| Simba Sleep |
| Eve Sleep |
| Tempur Sealy UK |
| Others |
Value Network & Pricing Analysis
Yorkshire's captive wool farming and spring manufacturing clusters concentrate upstream capacity, translating material control into pricing power for domestic producers facing REACH compliance costs that import competitors struggle to absorb. The Furniture and Furnishings (Fire) (Safety) Regulations enforce ignition resistance testing through local trading standards offices, elevating certification burdens that favor established manufacturers with in-house fire barrier production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BSI Kitemark-certified hybrid constructions from mass-market innerspring and budget foam imports. Price differentiation hinges on certification grade and volume scale, with hospitality bulk contracts commanding steepest discounts. Cost compression in the economy tier is intensifying because petrochemical input volatility resists downstream pass-through. Student housing operators and B2B landlords exhibit highest price sensitivity, while private care facilities and premium hotel chains prioritize performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates post-Brexit logistics planning for foam raw material flows. Geographic supply concentration centers on Belgium and the Netherlands for polyurethane chemical precursors, Turkey for natural latex, and domestic Yorkshire wool operations. The supply chain rests on steel coil dependencies from European foundries and petrochemical derivatives from Benelux refineries. Single-source vulnerability concentrates in specialty fire barrier textiles. Distribution runs through Felixstowe port infrastructure and M1 motorway corridors serving mattress-in-a-box fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: domestic manufacturers with established Furniture and Furnishings (Fire) (Safety) Regulations certification pathways capture shelf space as import compliance timelines lengthen.
For Market Incumbents: Pre-empt margin erosion from direct-to-consumer entrants by securing captive wool supply through Yorkshire farming partnerships and accelerating BSI Kitemark certification across hybrid product lines. Trading standards enforcement tightening on chemical flame retardants threatens import-heavy competitors lacking natural fiber fire barrier capabilities. Channel control through same-day delivery commitments from Midlands logistics positioning reinforces showroom-independent purchase capture. For New Entrants and Emerging Players: Wales and South Wales manufacturing corridors offer underpenetrated white-space for budget-tier hospitality contracts serving English hotel chains. Care facility procurement frameworks present the most penetrable institutional segment given NHS pressure-relief specifications and antimicrobial construction requirements. A direct-to-consumer launch targeting Birmingham and Greater Manchester urban rental markets with compressed trial-period guarantees bypasses established retail gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and skilled upholstery labor scarcity concentrate viable targets among vertically integrated domestic producers with captive spring manufacturing. Acquisition target archetype: mid-cap Yorkshire manufacturers combining wool farming operations with established trading standards relationships. Monitor pending fire safety consultations for reformulation timeline signals that would accelerate inventory transition costs and strain undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wool Farming | Yorkshire sheep farming secures natural fiber fire barriers compliant with REACH chemical restrictions. |
| BSI Kitemark Certification Investment | Voluntary quality signaling becomes mandatory for retailer shelf placement in premium channels. |
| Direct-to-Consumer Logistics Expansion | Compressed delivery windows from Croydon and Dartford hubs erode showroom-dependent purchase patterns. |
| Hybrid Construction R&D Acceleration | Layered coil-foam combinations capture consumer preference as heat retention complaints mount against all-foam designs. |
| Care Facility Specification Partnership | NHS procurement frameworks and private care home chains present underpenetrated volume for pressure-relief constructions. |
Research Methodology
Initial hypotheses were tested against primary input from mattress manufacturing executives, hospitality procurement directors, care facility operations managers, and trading standards enforcement officers and refined through secondary validation against UK customs records, Furniture and Furnishings (Fire) (Safety) Regulations consultation documents, Health and Safety Executive REACH guidance, and British Standards Institution certification databases. Bottom-up demand modeling across product type, customer segment, size configuration, and distribution channel dimensions was triangulated with top-down market sizing from housing completion data and hospitality refurbishment cycle indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning construction technology, procurement authority, dimensional format, and channel economics. CAGRs were derived from replacement cycle velocity differentials between rental housing and owner-occupied segments, cross-referenced with regional housing transaction data and institutional procurement pipeline tracking. Industry-specific forecast inputs included petrochemical derivative price indices and trading standards enforcement intensity metrics.
Practitioners should monitor pending fire safety consultation outcomes, REACH chemical restriction amendments, and skilled upholstery labor demographic shifts for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Foam Mattress Market