
 United States Gutter Guards Market | 2026-2036
United States Gutter Guards Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gutter Guards Market Analytics
EPA stormwater regulations are decoupling basic hardware from compliant gutter protection systems. LeafFilter dominates the professional installation channel through its dealer network density. Amerimax leverages its big-box retail presence to control the DIY segment. Gutter Helmet sustains brand recognition among replacement-driven homeowners in the Southeast.
United States gutter guards are mechanical filtration devices installed over roof drainage channels to block debris while permitting water flow, typically fabricated from perforated aluminum, woven stainless steel mesh, or engineered polymer foams with aperture sizes ranging from 50 to 500 microns. Their primary purpose is preventing gutter clogging, basement flooding, and fascia board rot while reducing ladder-related homeowner injuries. Mesh products command the largest volume share due to proven performance across pine needle and oak leaf environments, while reverse curve designs capture premium pricing through self-cleaning geometry that reduces maintenance frequency. The professional installation segment generates the highest margin pools because labor bundling obscures component costs and enables upselling of seamless gutter replacements.
FEMA floodplain mapping updates, OSHA fall-protection standards for roofing contractors, and the International Plumbing Code adopted by state building departments collectively shape product specifications and contractor certification requirements. These frameworks push municipalities toward specifying debris-free drainage as a condition of building occupancy permits. Stakeholders must monitor how state-level adoption of stricter stormwater ordinances redirects demand toward integrated gutter-guard-and-drainage systems rather than standalone retrofits.
Market Dynamics
Stormwater compliance mandates from the EPA are forcing residential property owners to upgrade from basic hardware to certified gutter protection systems, creating a bifurcation between commodity retrofits and code-compliant installations.
Growth Catalysts
- EPA NPDES enforcement:Municipal stormwater ordinances now require debris-free drainage as a condition of building occupancy permits in flood-prone jurisdictions.
- Aging housing stock concentration:Florida, Texas, and California combine high rainfall intensity with decades-old gutter infrastructure requiring replacement.
- Mesh material performance validation:Woven stainless steel aperture designs proven effective against pine needles and oak leaves are displacing foam alternatives in professional channels.
Market Restraints
- Aluminum input cost volatility:Perforated aluminum sheet prices fluctuate with primary metal markets, compressing margins for mid-tier fabricators.
- DIY channel price anchoring:Big-box retail presence of Amerimax and similar brands establishes consumer price expectations that professional installers struggle to overcome.
- Reverse curve technical limitations:Self-cleaning geometry performs poorly in regions with fine debris like redwood duff, restricting geographic applicability.
Strategic Opportunities
- Integrated gutter-guard-and-drainage systems:State-level adoption of stricter stormwater ordinances redirects demand toward bundled solutions rather than standalone retrofits.
- Rainwater harvesting convergence:Gutter guards are integrating with cistern and greywater systems as California's Title 24 water efficiency standards tighten.
- Insurance premium incentives:FEMA floodplain mapping updates enable carriers to offer rate reductions for properties with compliant debris protection.
Industry Challenges
- OSHA fall-protection compliance:Roofing contractors face elevated certification requirements under 29 CFR 1926 Subpart M, constraining installer labor pools.
- Seamless gutter integration complexity:On-site roll-forming equipment requires capital investment that fragments contractor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gutter Guards Market |
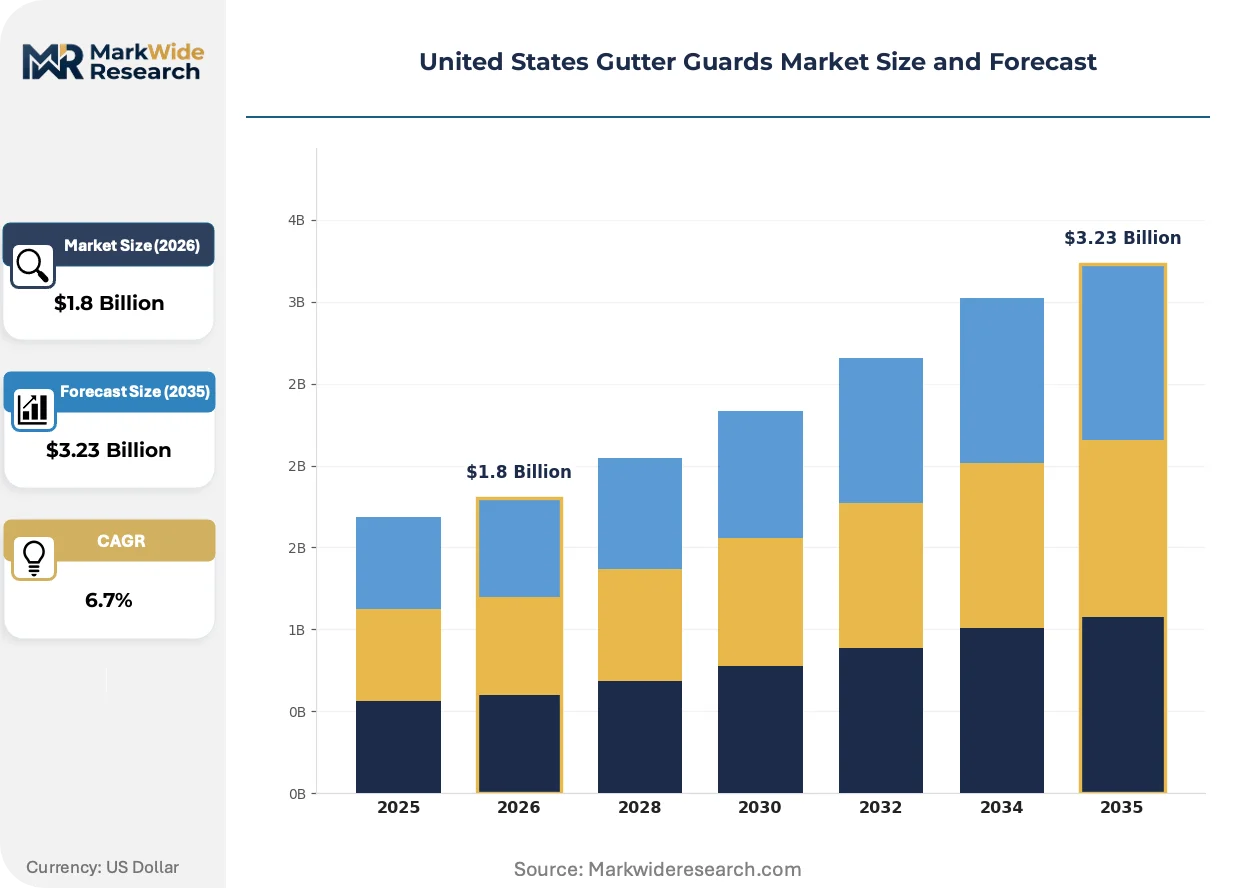
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh, Foam, Reverse Curve, Surface Tension Material: Aluminum, Vinyl, Stainless Steel, Copper Installation Type: DIY, Professional, Integrated, Standalone End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Raptor, MasterShield, Gutterglove, All American Gutter Protection, HomeCraft Gutter Protection, LeafFilter, Amerimax, Gutter Helmet, LeafGuard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gutter Guards Market Evolving Landscape
Material science advances and installation automation are compressing the gap between professional-grade performance and accessible price points. Regulatory pressure on stormwater management is accelerating product certification requirements.
Micro-mesh filtration technology is integrating nanocoating surface treatments that shed organic matter through hydrophobic action. High-end residential builders in hurricane-exposed counties are specifying these systems at triple the rate of conventional designs. The technology is integrating with smart home monitoring platforms that alert homeowners to gutter saturation events.
The EPA's National Pollutant Discharge Elimination System permit renewal cycle is mandating municipal separate storm sewer system operators to document debris reduction from residential drainage. This industrial consequence forces building departments to reference International Plumbing Code provisions in occupancy inspections. Florida counties with combined sewer overflow histories are responding fastest, embedding gutter guard specifications into site plan approvals.
Homeowner buying patterns are compressing replacement cycles as insurance carriers tie policy renewals to documented maintenance. The professional installation channel is capturing share from DIY as bundling with seamless gutter replacement obscures component costs. This shift concentrates most visibly in Southeast markets where LeafFilter's dealer density enables same-day quoting.
United States Gutter Guards Market Segmentation
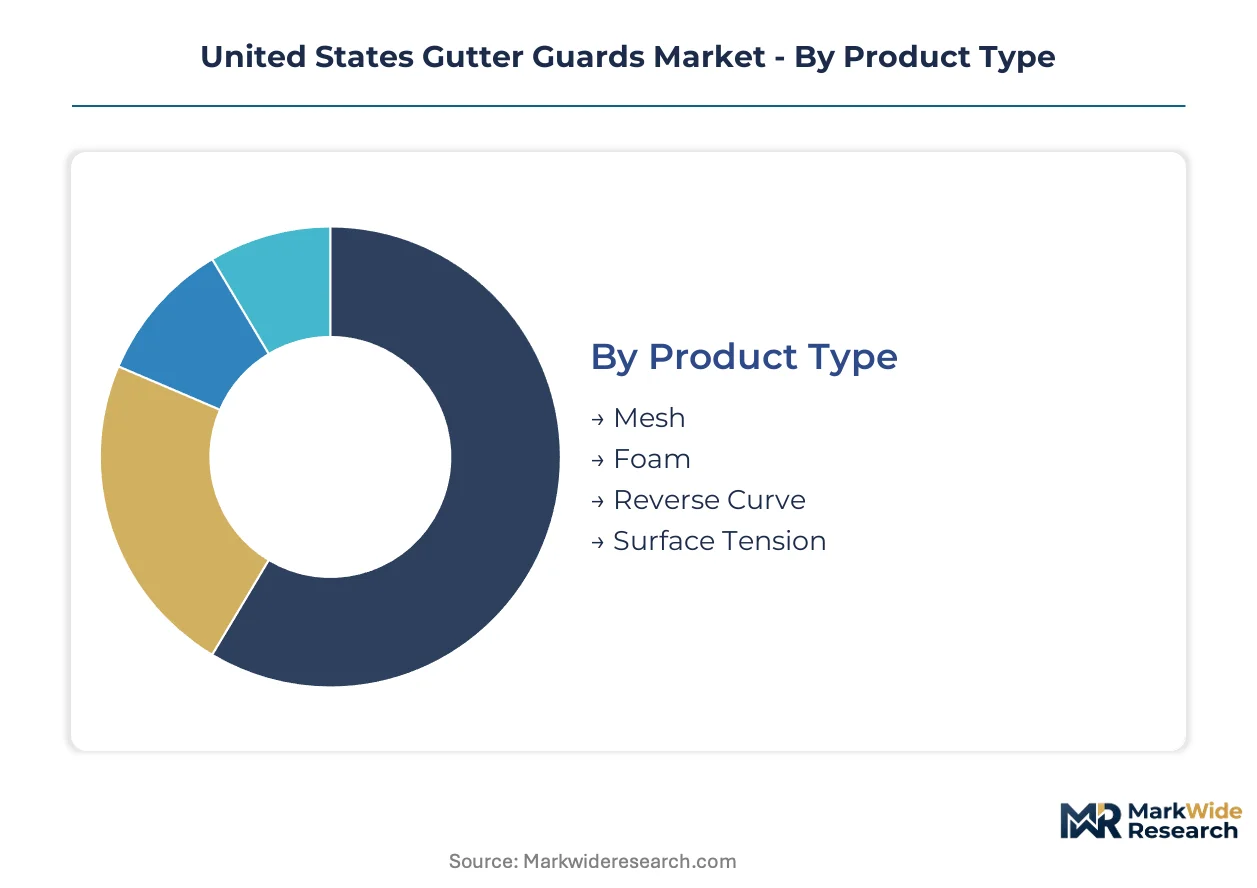
Gutter guard purchasing decisions split between performance requirements and installation economics. Product type determines debris-handling capability while installation channel shapes margin capture and customer lifetime value.
Product Type:
Mesh products dominate volume shipments while reverse curve designs extract premium pricing through reduced maintenance claims.
- Mesh:Woven stainless steel or perforated aluminum screens with 50-500 micron apertures block pine needles and oak leaves. Demand concentrates in Florida and Georgia where year-round foliage shedding creates recurring clog risks for homeowners.
- Reverse Curve:Self-cleaning geometry uses water adhesion to separate debris from flow. Texas and California builders specify these for upscale subdivisions where ladder-access restrictions elevate maintenance-free claims.
- Foam:Open-cell polyurethane inserts filter through porosity rather than aperture. Budget-conscious DIY buyers in big-box retail channels favor these for their tool-free installation.
- Surface Tension:Micro-perforated metal sheets exploit water cohesion to draw flow through narrow slots. Coastal Carolina markets with fine pollen and seed debris show selective adoption.
Mature deployment sits with mesh products. Newer deployment is concentrated in reverse curve systems.
Material:
Cost tiering separates commodity metals from architectural-grade finishes that command specification in custom residential builds.
- Aluminum:Perforated sheet dominates professional channels due to corrosion resistance and roll-forming compatibility. Florida coastal counties specify marine-grade alloys to withstand salt-air exposure.
- Stainless Steel:Woven mesh variants with 316-grade composition resist organic acid degradation from decomposing leaf matter. Pacific Northwest markets with heavy conifer needle loads drive specification.
- Vinyl:Injection-molded components serve price-sensitive retrofit applications where color matching to existing gutters matters less than upfront cost.
- Copper:Architectural metal matches high-end gutter systems in historic districts and luxury construction. Northeastern markets with preservation ordinances sustain niche demand.
Volume concentration favors aluminum. Margin expansion sits with stainless steel and copper.
Installation Type:
Channel structure determines whether component costs remain visible or become bundled into project pricing.
- Professional:Dealer networks perform on-site measurements and seamless gutter integration. Southeast markets with LeafFilter density enable same-day quoting and installation scheduling.
- DIY:Big-box retail placement of Amerimax and similar brands establishes consumer price anchors. Texas and Arizona homeowners with single-story ranch construction favor self-installation.
- Integrated:Bundled gutter-guard-and-drainage systems address California Title 24 stormwater compliance. Municipal permit offices in flood-prone counties increasingly mandate this configuration.
- Standalone:Retrofit-only guard installation without gutter replacement serves aging housing stock where fascia boards remain sound. Midwest markets with post-war subdivision housing sustain this segment.
Revenue growth is fastest in integrated installations. Volume share remains with professional channel deployment.
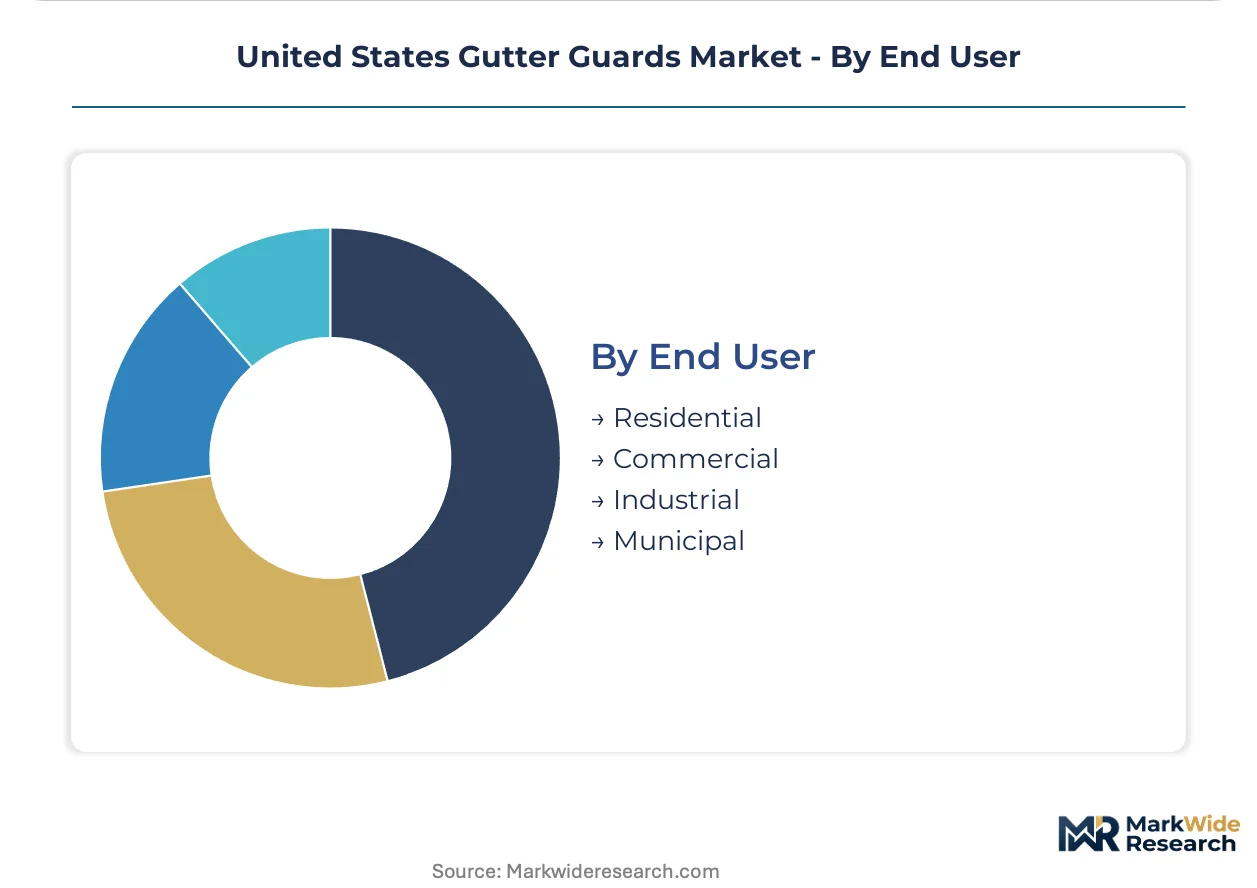
End User:
Property type dictates compliance pressure and maintenance resource availability.
- Residential:Single-family homeowners respond to insurance policy renewal requirements for documented debris protection. Florida and California account for disproportionate demand concentration.
- Commercial:Multi-tenant buildings and retail properties face premises liability exposure from ladder-access maintenance. Professional installation with warranty transferability dominates.
- Industrial:Manufacturing facilities with large roof footprints specify heavy-duty systems compatible with roof access safety protocols. OSHA fall-protection compliance elevates contractor certification requirements.
- Municipal:Public buildings and stormwater infrastructure projects reference EPA NPDES permit conditions. Combined sewer overflow counties embed specifications into site plan approvals.
Residential captures volume leadership. Municipal represents the steepest expansion trajectory as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Florida, Texas, and California where rainfall intensity and aging housing stock intersect. The EPA's National Pollutant Discharge Elimination System is reshaping installation requirements across these high-precipitation zones. Residential property owners represent the fastest-expanding buyer segment as stormwater management compliance tightens.
Florida
Year-round foliage shedding from pine and oak canopies creates recurring clog risks for homeowners in Tampa Bay and Orlando metros. The state's Department of Environmental Protection enforces municipal separate storm sewer system documentation under EPA NPDES permit conditions. Miami-Dade and Broward counties embed gutter guard specifications into site plan approvals for combined sewer overflow mitigation.
Texas
Upscale subdivisions in Dallas-Fort Worth and Houston specify reverse curve designs where ladder-access restrictions elevate maintenance-free claims. The Texas Commission on Environmental Quality coordinates with FEMA floodplain mapping updates to tie debris protection to building occupancy permits. Austin's Title 24-equivalent water efficiency standards accelerate rainwater harvesting convergence with gutter guard systems.
California
Marine-grade aluminum alloys dominate coastal county specifications to withstand salt-air exposure from San Diego to the Bay Area. The state's Title 24 water efficiency standards mandate integrated gutter-guard-and-drainage systems for new construction compliance. Los Angeles and Sacramento metropolitan permit offices increasingly require bundled solutions rather than standalone retrofits.
Southeast Atlantic
Georgia and the Carolinas sustain mesh product demand through heavy conifer needle loads and pollen debris environments. OSHA fall-protection standards for roofing contractors elevate professional installation channel capture in Atlanta and Charlotte metro areas. Coastal Carolina markets with fine seed debris show selective adoption of surface tension micro-perforated designs.
Pacific Northwest
Woven stainless steel mesh with 316-grade composition resists organic acid degradation from decomposing leaf matter in Seattle and Portland markets. The region's heavy rainfall intensity intersects with decades-old gutter infrastructure requiring replacement. Oregon and Washington building departments reference International Plumbing Code provisions in occupancy inspections for debris-free drainage.
United States Gutter Guards Market Competitive Landscape
Southeast producers anchor one tier; Midwest fabricators hold manufacturing scale advantages. The vendor base splits between dealer-network-dependent installers and big-box retail distributors. Three archetypes dominate: professional installation specialists, DIY channel suppliers, and integrated system bundlers. Competitive moves concentrate on geographic dealer density expansion and seamless gutter integration capabilities.
Within the professional installation tier, LeafFilter and Gutter Helmet occupy positions defined by dealer network reach and brand recognition velocity. Amerimax exemplifies the DIY channel archetype through big-box retail presence that establishes consumer price anchors. Gutterglove represents the technology-forward segment with mesh material performance validation driving specification in professional channels.
| Leading Market Players |
|---|
| Raptor |
| MasterShield |
| Gutterglove |
| All American Gutter Protection |
| HomeCraft Gutter Protection |
| LeafFilter |
| Amerimax |
| Gutter Helmet |
| LeafGuard |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up installation specialists concentrate dealer network control across Florida and Texas, compressing procurement leverage for independent contractors while sustaining premium pricing power through same-day quoting capabilities. This ownership pattern feeds aluminum sheet sourcing discipline and obscures component costs through labor bundling.
Pricing Analysis
Short lead-time premiums dominate contractor channel economics, with same-day installation availability commanding substantial markups over scheduled retrofit slots. Three-tier pricing structure across premium stainless steel mesh, standard perforated aluminum, and economy foam inserts separates certified EPA-compliant systems from commodity hardware. Price differentiation centers on stormwater certification tier and seamless gutter integration complexity. Cost compression in the DIY channel intensifies as big-box retail anchoring constrains professional installer rate cards.
Supply Chain Analysis
Single-source vulnerability sits with domestic aluminum rolling mills serving perforated sheet demand, while woven stainless steel mesh draws from South Korean and Taiwanese specialty metal weavers. Raw material dependencies span primary aluminum ingot, 316-grade stainless steel wire, and marine-grade alloy coatings. Tariff exposure on imported mesh components elevates landed cost volatility for coastal fabricators. Distribution runs through big-box retail for DIY consumers and captive dealer networks for professional installation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA NPDES compliance deadlines are forcing consolidation as undercapitalized regional installers lose municipal permit eligibility, creating acquisition opportunities for scaled operators with certification infrastructure.
For Market Incumbents: Deepen vertical integration into seamless gutter roll-forming equipment to capture bundled project margins and defend against standalone guard competitors. Expand 316-grade stainless steel mesh captive production capacity in Pacific Northwest markets where conifer needle loads drive specification. Prioritize Florida and California dealer density to preempt municipal stormwater ordinance enforcement windows. For New Entrants and Emerging Players: Municipal building departments in combined sewer overflow counties represent an underserved specification channel with concentrated procurement authority and limited incumbent penetration. Target bundled gutter-guard-and-drainage system approvals in California Title 24 jurisdictions where integrated compliance mandates displace standalone retrofits. Pursue direct specification relationships with county environmental offices rather than consumer marketing spend. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional installation specialists with EPA-compliant certification infrastructure in Florida and Texas coastal counties. Long-term viability hinges on stormwater regulatory enforcement durability rather than discretionary home improvement cycles. Watch FEMA floodplain mapping revision velocity as the inflection signal for insurance-premium-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Density Expansion | Same-day quoting capability in Florida metros captures EPA compliance-driven replacement cycles. |
| Seamless Gutter Integration Investment | On-site roll-forming equipment obscures component costs and elevates project bundling rates. |
| 316-Grade Stainless Steel Mesh Certification | Pacific Northwest specification for conifer needle resistance commands premium positioning. |
| Municipal Specification Relationship Development | County environmental office approvals in California embed products into Title 24 compliance pathways. |
| Rainwater Harvesting System Convergence | Cistern integration addresses Austin and Los Angeles water efficiency mandate expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews of gutter guard fabricators, roofing contractor association directors, and municipal building department officials. EPA NPDES permit documentation, Florida Department of Environmental Protection enforcement records, and California Title 24 compliance filings provided regulatory trajectory validation. Bottom-up shipment estimates from aluminum and stainless steel mesh suppliers were triangulated against top-down construction permit data.
Granularity-level modeling segmented the market by product type, material grade, installation channel, and end-user property category across state-level regulatory clusters. CAGRs were derived from installation volume trajectories correlated with housing stock age distributions and municipal ordinance adoption timelines. Forecast inputs incorporated FEMA floodplain mapping revision schedules and OSHA fall-protection compliance cost pass-through assumptions.
Revisions become necessary when EPA enforcement intensity shifts, aluminum tariff schedules change, or municipal stormwater ordinance adoption accelerates beyond baseline assumptions. Deviation in NPDES permit renewal cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
North America Particle Board Market