
 Electric Ranges Market | 2026-2036
Electric Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Ranges Market Analysis
Retail leasing and pay-per-use appliance subscription models is rewriting capital deployment for mid-tier buyers who previously deferred equipment upgrades. Whirlpool leverages its captive distribution network to sustain margin control across independent dealer channels. GE anchors its competitiveness through in-house production of induction coil assemblies. Samsung differentiates via smart-home integration that extends its electronics ecosystem into kitchen environments.
An electric range is a stationary cooking appliance comprising a cooktop with resistive coil, radiant, or induction heating elements paired with an enclosed oven cavity, typically operating on 240-volt alternating current for thermal outputs between 3,000 and 12,000 watts. The primary purpose is to provide controlled thermal energy for food preparation in residential and commercial settings where natural gas infrastructure is unavailable or prohibited. Slide-in configurations command premium positioning due to integrated cabinetry aesthetics, while induction technology captures the fastest expansion as energy efficiency regulations tighten operational cost thresholds. Freestanding units still occupy the largest volume tier, though margin pools concentrate in built-in and range-with-oven combinations targeting luxury residential and hospitality specifications.
The U.S. Department of Energy sets minimum efficiency standards that reshape product engineering cycles and disqualify lower-performing coil-element designs from new retail placement. The EPA ENERGY STAR certification program creates tiered demand segmentation that channels procurement toward induction and convection platforms. California Title 24 building codes impose all-electric readiness mandates that accelerate range electrification in new construction. Stakeholders must monitor how state-level gas-ban preemption battles reshape addressable market geography and inventory deployment priorities.
Market Dynamics
Residential kitchen electrification mandates are compressing the addressable market for gas-connected appliances while amplifying specification intensity for high-efficiency electric alternatives. This regulatory compression is forcing manufacturers to reengineer thermal management systems and recertify entire product portfolios within shortened compliance windows.
Growth Catalysts
- California Title 24 All-Electric Readiness:New construction mandates in the state require pre-wiring for electric cooking equipment, eliminating gas rough-in infrastructure and expanding the qualified buyer pool for induction and radiant ranges.
- Induction Coil Efficiency Gains:Advances in copper winding density and ferrite core materials are reducing standby power draw below 1 watt, satisfying ENERGY STAR Most Efficient thresholds that coil-element designs cannot meet.
- Sun Belt Metropolitan Housing Starts:Elevated single-family and multifamily construction across Phoenix, Austin, and Atlanta is generating concentrated demand for builder-grade electric ranges in 240-volt prewired units.
Market Restraints
- Copper and Rare Earth Magnet Volatility:Induction range production depends on neodymium-iron-boron magnets and high-conductivity copper windings, both subject to export restriction risk from Chinese processing concentration.
- 240-Volt Infrastructure Retrofit Costs:Existing residential electrical panels in pre-1990 housing stock often lack spare amperage capacity, forcing $2,000-$4,000 service upgrades that defer replacement cycles.
- Natural Gas Ban Preemption Battles:Twenty U.S. states have enacted prohibitions on municipal gas bans, fragmenting the regulatory map and complicating national inventory deployment strategies for manufacturers.
Strategic Opportunities
- Pay-Per-Use Appliance Subscriptions:Mid-tier buyers previously deferring upgrades are accessing induction ranges through monthly fee structures that bundle maintenance and end-of-life recycling.
- Smart-Home Ecosystem Convergence:Integration with voice-activated platforms and energy management systems is creating differentiation in premium segments where thermal performance alone saturates.
- Commercial Kitchen Electrification:Small-format hospitality and ghost kitchen operators in urban gas-ban jurisdictions are adopting heavy-duty electric ranges previously confined to residential specifications.
Industry Challenges
- Electromagnetic Compatibility Certification:Induction ranges must demonstrate non-interference with cardiac pacemakers and radio frequency devices, extending FCC and international testing timelines by 4-6 months.
- Legacy Housing Electrical Capacity:Field installation crews encounter fused neutral-ground bonds and aluminum branch wiring in 1970s-era stock, requiring skilled electrician dispatch that compresses margin on entry-level units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Ranges Market |
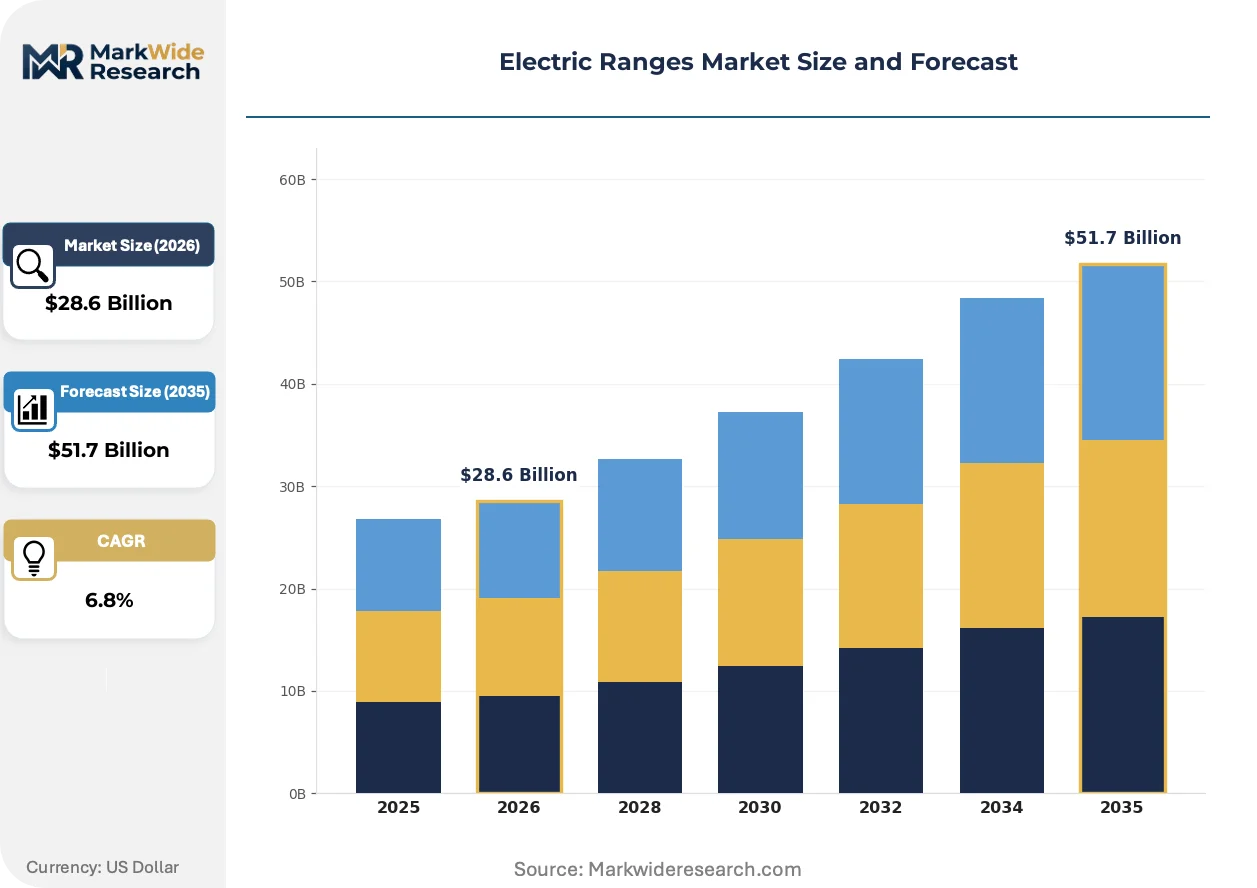
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Slide-In, Built-In, Range with Oven Technology: Induction, Radiant, Coil, Convection End User: Residential, Commercial, Industrial, Hospitality Size: Standard, Compact, Large, Extra Large |
| Companies Covered | Frigidaire, Empava, GE, Bosch, Whirlpool, LG, Kenmore, KitchenAid, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Ranges Market Emerging Trajectories
Product engineering cycles are compressing as efficiency thresholds tighten and connectivity features migrate from premium to standard equipment tiers. Manufacturers are racing to integrate thermal sensors, adaptive power modulation, and interoperability protocols before regulatory deadlines disqualify legacy platforms.
Induction heating technology is migrating from premium slide-in configurations to freestanding units priced at standard radiant-range levels. Multi-family developers in Seattle and Denver are specifying these models to meet local electrification ordinances without busting appliance allowances. The technology is migrating from niche positioning toward builder-grade default status as coil-element production volumes contract.
The EPA ENERGY STAR Most Efficient designation is disqualifying conventional radiant and coil-element designs from federal procurement and utility rebate programs. Manufacturers must redesign control systems and cavity insulation to meet the 20% efficiency premium over baseline standards. The designation is reshaping product roadmaps most aggressively in the Pacific Northwest and Northeast corridor states with aggressive decarbonization targets.
Builder procurement is consolidating around preconfigured appliance packages that bundle ranges with refrigerators and dishwashers under single-SKU logistics. National production homebuilders in Texas and Florida are negotiating direct allocation agreements that bypass independent dealer channels. This consolidation is concentrating volume with manufacturers possessing captive distribution networks and compressing shelf space for regional brands.
Electric Ranges Market Segmentation

Segmentation in electric ranges reveals how purchase decisions split across installation constraints, energy infrastructure, and operational intensity. Manufacturers must align thermal engineering, voltage compatibility, and connectivity features to distinct buyer profiles rather than pursuing uniform platform strategies.
Product Type:
Installation flexibility spans from portable plug-in units to permanent architectural integration, with each configuration demanding different supply chain and service capabilities.
- Freestanding:Self-contained chassis with finished side panels allow placement between cabinetry or as standalone units. Builders in Phoenix and Austin specify these for entry-level single-family homes where appliance allowances remain tight. The segment captures the highest unit volumes but faces margin compression from direct-to-builder procurement consolidation.
- Slide-In:Front-control designs with unfinished sides integrate flush with countertops for seamless kitchen aesthetics. Sun Belt metropolitan renovation contractors favor these for kitchen refreshes where cabinetry replacement is limited. Controls positioned at the front eliminate the need for rear panel clearance, reclaiming counter depth in compact galley layouts.
- Built-In:Wall-oven configurations separate cooktop from oven cavity for ergonomic installation at custom heights. Luxury residential specifications in California coastal markets drive demand where Title 24 all-electric mandates intersect with high-end kitchen design.
- Range with Oven:Unified cooktop-oven combinations dominate multifamily construction where space optimization outweighs customization preferences. National production homebuilders negotiate direct allocation agreements for preconfigured packages bundling these with refrigerators and dishwashers.
The dominant share belongs to Freestanding, while Slide-In is closing the gap fastest as renovation activity accelerates across North America.
Technology:
Heat transfer mechanisms differentiate products across efficiency certification tiers, electromagnetic compatibility requirements, and operational cost profiles.
- Induction:Copper coil assemblies generate oscillating magnetic fields that induce resistive heating directly in ferromagnetic cookware. EPA ENERGY STAR Most Efficient thresholds favor this technology as standby power draw falls below 1 watt with advances in ferrite core materials. California Title 24 building codes and Seattle electrification ordinances are mandating pre-wiring that accelerates induction specification in new construction.
- Radiant:Halogen or ribbon elements beneath ceramic glass surfaces provide visual feedback and compatibility with all cookware types. Hospitality operators in gas-ban jurisdictions adopt these where kitchen staff training for induction-ready cookware proves impractical.
- Coil:Exposed resistive elements represent legacy infrastructure with lowest first cost but disqualification from federal procurement and utility rebate programs. Replacement demand concentrates in pre-1990 housing stock where 240-volt panel upgrades remain uneconomical.
- Convection:Forced-air circulation within oven cavities reduces cooking time and temperature requirements through enhanced heat transfer. This feature migrates from premium to standard equipment tiers as efficiency thresholds tighten across all product configurations.
Induction commands the steepest expansion trajectory as regulatory compression eliminates coil-element eligibility from incentive programs.
End User:
Operational intensity and duty cycles separate buyers across thermal output requirements, connectivity expectations, and service response demands.
- Residential:Single-family and multifamily households drive volume with intermittent use patterns and aesthetic prioritization. Sun Belt metropolitan housing starts in Phoenix, Austin, and Atlanta concentrate demand for builder-grade electric ranges in 240-volt prewired units.
- Commercial:Small-format restaurants and ghost kitchens require heavy-duty thermal output previously confined to residential specifications. Urban gas-ban jurisdictions in California and Washington state are expanding the addressable market for commercial-grade electric platforms.
- Industrial:Food processing and institutional cafeterias demand continuous-duty thermal management with redundant control systems. These specifications prioritize mean time between failure over connectivity features or design aesthetics.
- Hospitality:Hotels and extended-stay properties balance guest-facing design with operational durability across high-turnover breakfast service. Procurement consolidates around preconfigured packages that standardize maintenance protocols across property portfolios.
Residential maintains volume leadership, though Commercial is gaining share fastest as electrification mandates penetrate foodservice operations.
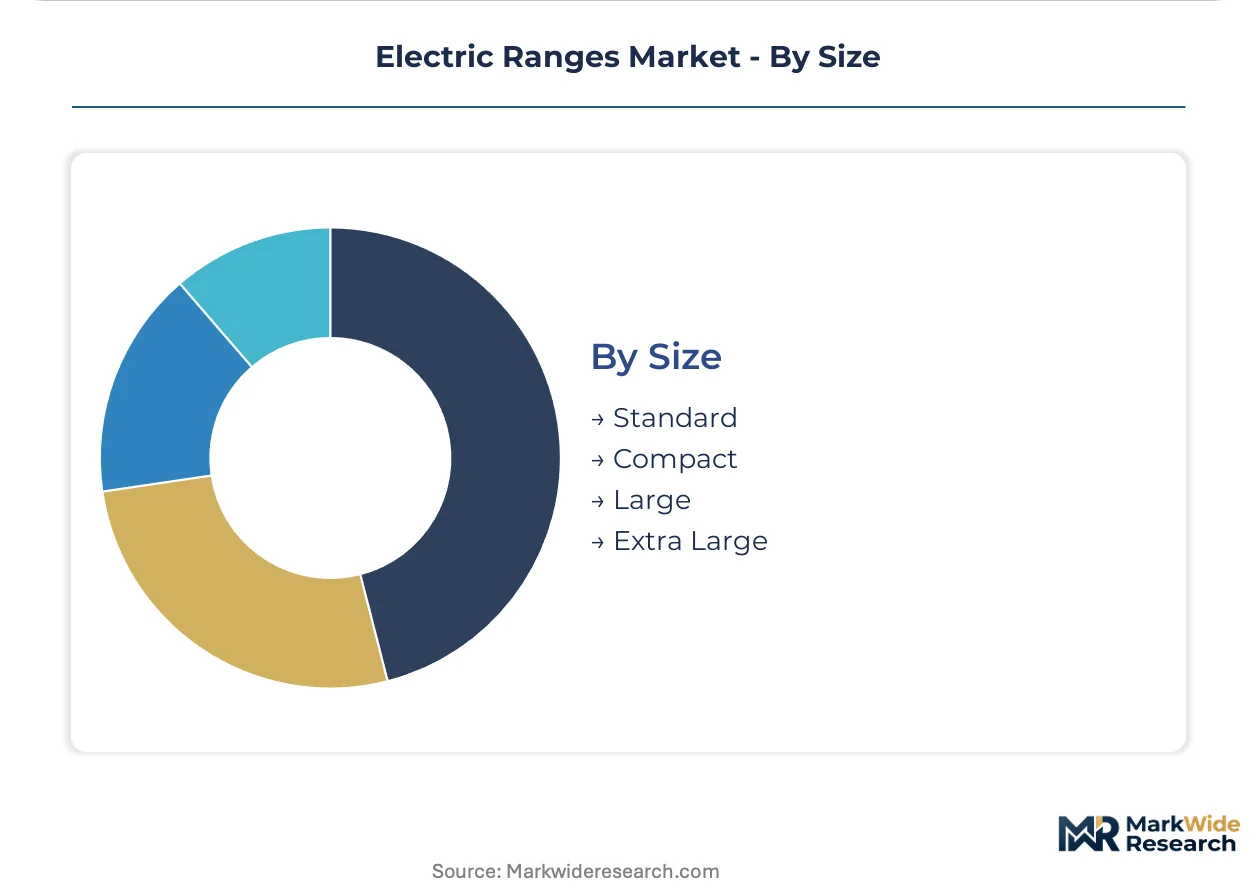
Size:
Cavity dimensions and cooktop burner count align with household composition, kitchen footprint constraints, and regional housing stock characteristics.
- Standard:30-inch width with four heating zones satisfies nuclear family cooking patterns and dominates replacement cycles. This configuration aligns with the dimensional standards of pre-2000 residential construction across the United States.
- Compact:24-inch and smaller formats address multifamily micro-units, accessory dwelling units, and urban infill construction where kitchen square footage is constrained. Seattle and Denver developers specify these to meet local electrification ordinances without busting appliance allowances.
- Large:36-inch widths with five or six burners target suburban single-family homes where kitchen islands accommodate expanded cooktops. These specifications concentrate in new construction rather than replacement demand.
- Extra Large:48-inch and 60-inch professional-style ranges with dual ovens serve luxury residential and estate properties where cooking performance signals household investment. Custom cabinetry integration requirements limit volume but sustain premium margin pools.
Standard width commands the dominant share, while Compact formats are climbing the fastest as multifamily construction intensifies in dense metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial import surplus in electric ranges, sourcing induction coil assemblies and control modules from Asian manufacturing centers while exporting premium slide-in configurations to Canadian and Mexican markets. Germany and China anchor opposite ends of the component trade, with German engineering houses supplying high-efficiency thermal management systems and Chinese fabricators dominating ferrite core and copper winding production.
United States
Residential kitchen renovation activity and Sun Belt metropolitan housing starts in Phoenix, Austin, and Atlanta are accelerating specification of 240-volt prewired units. The U.S. Department of Energy's appliance efficiency standards are tightening minimum performance thresholds and disqualifying coil-element designs from new retail placement. California Title 24 building codes impose all-electric readiness mandates that accelerate range electrification in new construction across Los Angeles, San Diego, and Bay Area metropolitan clusters.
Canada
Multi-family developers in Vancouver and Toronto are specifying compact induction ranges to meet municipal electrification bylaws without exceeding appliance allowances. Natural Resources Canada's ENERGY STAR Canada program creates tiered procurement channels that favor induction and convection platforms over radiant alternatives. British Columbia's building code amendments are accelerating adoption in Vancouver's dense condominium market while Alberta's housing stock replacement cycles concentrate demand in Calgary and Edmonton.
Germany
Industrial kitchen electrification in commercial hospitality and foodservice operations is expanding the addressable market for heavy-duty electric platforms. The EU Ecodesign Directive and national implementation through the Federal Ministry for Economic Affairs and Energy are reshaping product engineering cycles and thermal efficiency thresholds. Manufacturing concentration in Baden-Württemberg and Bavaria sustains component supply for coil assembly and control system production serving continental European markets.
China
Export-oriented production of induction coil assemblies, ferrite core materials, and copper windings supplies global OEM assembly operations. The Ministry of Industry and Information Technology's appliance efficiency standards and dual carbon goals are tightening domestic market requirements while preserving export capacity. Manufacturing clusters in Guangdong and Zhejiang provinces dominate component fabrication, with Shenzhen and Ningbo serving as primary export logistics hubs for North American and European customers.
Japan
Smart-home ecosystem integration and precision thermal control technologies are differentiating premium residential specifications in Tokyo, Osaka, and Nagoya metropolitan markets. The Ministry of Economy, Trade and Industry's Top Runner program establishes efficiency benchmarks that channel procurement toward induction and advanced convection platforms. Industrial concentration in the Chubu region around Nagoya sustains component supply for control system and sensor module production.
Electric Ranges Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling coil assembly and thermal management supply. The vendor base organizes around three strategic archetypes: diversified appliance conglomerates with captive distribution networks, electronics ecosystem extenders leveraging smart-home integration capabilities, and regional fabricators serving price-sensitive replacement cycles. Competitive positioning depends on backward integration into induction coil production and direct allocation agreements with national production homebuilders that bypass independent dealer channels.
Among diversified appliance conglomerates, Whirlpool Corporation and GE exemplify platform integrators with captive distribution networks sustaining margin control across independent dealer channels. Samsung Electronics occupies a position as an electronics ecosystem extender, differentiating through smart-home integration that extends consumer electronics platforms into kitchen environments. These three companies anchor the competitive structure, with Whirlpool and GE representing traditional appliance manufacturing archetypes and Samsung exemplifying cross-sector convergence strategies.
| Leading Market Players |
|---|
| Frigidaire |
| Empava |
| GE |
| Bosch |
| Whirlpool |
| LG |
| Kenmore |
| KitchenAid |
| Samsung |
| Others |
Supply Flow & Price Mechanics
Guangdong Province's induction coil manufacturing clusters dictate downstream pricing power for North American OEMs, with ferrite core capacity utilization directly translating into margin leverage for finished range producers. The concentration of copper winding and magnet assembly in Shenzhen-Ningbo corridors creates asymmetric cost pass-through dynamics where component volatility outpaces finished goods pricing flexibility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with ENERGY STAR Most Efficient certification and smart-home integration modules serving as primary price differentiation drivers. Cost compression in entry-level coil-element tiers is intensifying because of direct-to-builder procurement consolidation, while hospitality operators demonstrate lowest price sensitivity due to operational durability requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for induction range producers. Manufacturing draws from China, South Korea, and Germany for ferrite cores, neodymium magnets, and thermal management systems respectively, with single-source vulnerability concentrated in rare earth magnet processing. Distribution runs through captive dealer networks and direct allocation agreements with national production homebuilders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric ranges market functions as a service-attach opportunity where subscription-based maintenance and end-of-life recycling bundles expand faster than hardware replacement cycles. Pay-per-use appliance models transform capital expenditure into recurring revenue streams for mid-tier buyer segments.
For Market Incumbents: Build captive distribution moats through direct allocation agreements with Sun Belt production homebuilders that bypass independent dealer channels. Consolidate backward integration into induction coil assembly to offset rare earth magnet price volatility, while investing in FCC electromagnetic compatibility certification ahead of regulatory tightening that threatens to disqualify non-compliant platforms from new retail placement. For New Entrants and Emerging Players: Build out white-space penetration in commercial kitchen electrification for ghost kitchen operators and small-format hospitality in urban gas-ban jurisdictions. Target compact induction specifications for multifamily micro-units in Seattle and Denver where local electrification ordinances create specification pull-through without incumbent brand loyalty, leveraging pay-per-use subscription models as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with in-house ferrite core and copper winding capabilities that escape magnet supply bottlenecks. Long-term viability rests on backward integration depth rather than brand equity, with acquisition targets screening for captive coil assembly and thermal management IP. The signal to watch is state-level gas-ban preemption legislation that fragments addressable market geography and concentrates volume with regionally agile suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Assembly | In-house ferrite core production insulates margins from Chinese rare earth export restrictions. |
| Smart-Home Platform Integration | Voice-activated interoperability with Samsung and LG ecosystems differentiates premium specifications. |
| Direct-to-Builder Allocation Agreements | Bypassing independent dealer channels captures volume from Texas and Florida production homebuilders. |
| Subscription Service Model Launch | Pay-per-use structures convert deferred replacement demand into recurring revenue from mid-tier buyers. |
| Electromagnetic Compatibility Certification | FCC pacemaker-interference testing accelerates time-to-market ahead of regulatory disqualification thresholds. |
Methodological Framework
Operator-level perspectives from appliance procurement managers at national production homebuilders, independent dealer channel owners, and aftermarket service technicians anchored the qualitative base. Primary fieldwork combined with secondary validation from DOE appliance efficiency filings, EPA ENERGY STAR certification databases, and California Title 24 building code amendments. Customs records tracking ferrite core and copper winding imports, SEC 10-K disclosures from diversified appliance conglomerates, and utility rebate program enrollment data provided quantitative triangulation between bottom-up installation tracking and top-down manufacturing output analysis.
Scenario-bracketing around regulatory compression velocity and housing start volatility shaped the analytical framework across the analysis window. Segmentation dimensions modeled include installation configuration, heat transfer technology, end-use operational intensity, and regional electrification mandate adoption patterns. CAGRs were derived from unit shipment trajectories cross-referenced with average selling price movements, with induction technology penetration curves and Sun Belt metropolitan construction permits serving as industry-specific forecast inputs.
Stress conditions across rare earth magnet export restrictions, copper price volatility, and state-level gas-ban preemption outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding efficiency standard implementation timelines and housing construction permit trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Egypt Microwave Ovens Market
Appliances
Oman Dishwashers Market
Appliances
United States Washing Machine Market
Appliances
Space Heaters Market
Appliances
Electric Fan Market
Appliances
Europe Household Electric Grills Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
APAC White Goods Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Smart Ceiling Fan Market
Appliances
Triple Barrel Waver Market
Appliances
Germany Consumer Appliances Market
Appliances
Residential Space Heater Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Wall Oven Market