
 Lightwave Microwave Oven Market | 2026-2036
Lightwave Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Lightwave Microwave Oven Market Insights
Modular accessory bundling with core oven units is recalibrating how buyers evaluate total cost of ownership across residential and commercial channels. LG Electronics leverages its inverter magnetron ecosystem to anchor premium positioning in built-in installations. Samsung Electronics competes through smart-kitchen platform integration that extends software control into meal-planning workflows. Whirlpool Corporation dominates North American distribution through captive relationships with national home-improvement retailers.
A lightwave microwave oven combines conventional microwave radiation with infrared or halogen lightwave elements to achieve browning, crisping, and accelerated cooking in a single cavity, typically operating across 800–1,250 watts of microwave output supplemented by 1,000–1,500 watts of radiant heat. The countertop segment sustains the largest installed base due to lower entry pricing and rental-friendly portability, while the combination technology category captures the fastest growth as buyers trade up from solo units for expanded menu versatility. The commercial end-user segment concentrates margin pools because hospitality and institutional buyers prioritize durability ratings, NSF certification, and service-contract availability over upfront cost.
The US Department of Energy sets minimum efficiency standards that constrain standby power and cooking-energy metrics, while the FCC regulates wireless connectivity modules in smart-control feature sets. The EU Ecodesign Directive and REACH chemical-compliance requirements shape export-bound product configurations from Asian manufacturing bases. Stakeholders must monitor how tightening standby-power thresholds in multiple jurisdictions affect inverter and power-supply component sourcing, as these specifications will determine which product architectures remain commercially viable across major markets.
Market Dynamics
Kitchen labor compression across North American hospitality chains is forcing procurement toward combination-technology units that collapse cooking steps into single-cavity workflows, reshaping how buyers evaluate speed-to-plate against capital outlay.
Growth Catalysts
- US Department of Energy standby-power thresholds:Tightening efficiency mandates are accelerating inverter magnetron adoption as manufacturers redesign power-supply architectures to remain compliant across multi-jurisdictional shipments.
- Quick-service restaurant buildout cycles:Renovation waves in United States fast-casual chains are sustaining above-average replacement rates for built-in and over-the-range configurations with browning capabilities.
- Halogen-radiant convergence:Infrared lightwave elements paired with conventional microwave cavities are enabling menu expansion in compact footprints, pulling commercial buyers away from solo-function equipment.
Market Restraints
- Magnetron supply concentration:Asian manufacturing bases dominate high-frequency power component production, exposing procurement timelines to regional logistics volatility and input cost swings.
- NSF certification timelines:Commercial-grade durability validation for hospitality applications extends product development cycles, compressing margin windows before competitive obsolescence.
- Convection oven substitution:Established thermal-air systems in institutional kitchens resist displacement where capital budgets prioritize repair-over-replace strategies.
Strategic Opportunities
- EU Ecodesign Directive alignment:REACH-compliant material sourcing and standby-power optimization create export-ready product platforms for European hospitality procurement.
- Smart-kitchen platform convergence:Software-controlled meal-planning workflows integrated with cooking hardware open recurring-revenue models beyond one-time equipment sales.
- Multi-unit residential rental channels:Portable countertop configurations serve turnover-heavy apartment markets where tenant-owned appliances bypass landlord capital constraints.
Industry Challenges
- Inverter engineering talent scarcity:Power electronics specialization required for variable-frequency magnetron control outpaces vocational training pipeline output in manufacturing hubs.
- FCC wireless module recertification:Smart-control feature sets face connectivity compliance delays when hardware revisions trigger renewed electromagnetic testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightwave Microwave Oven Market |
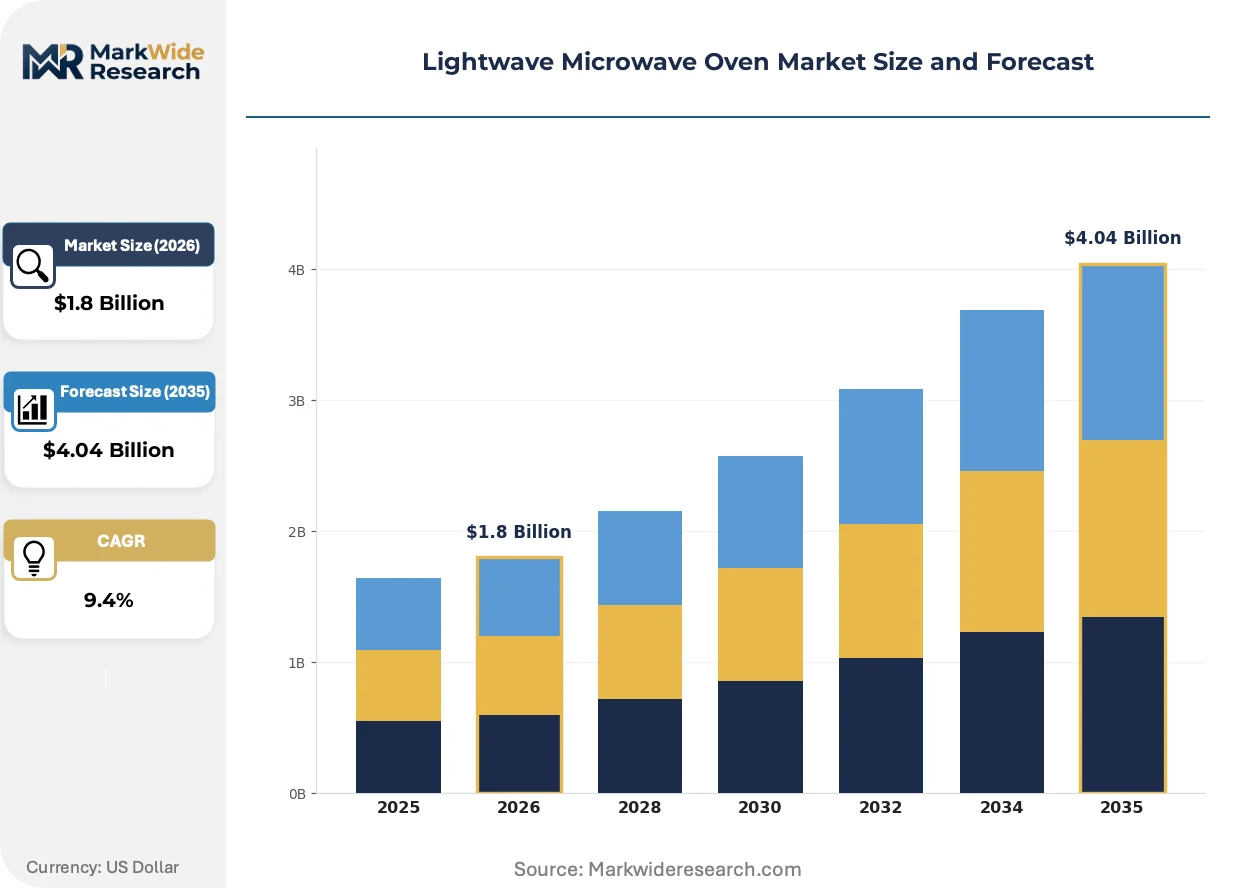
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Freestanding, Over-the-Range Technology: Convection, Grill, Solo, Combination End User: Residential, Commercial, Institutional, Hospitality Feature: Smart Control, Turbo Defrost, Auto Cook, Child Lock |
| Companies Covered | LG Electronics, Samsung Electronics, Whirlpool Corporation, Panasonic Corporation, Hitachi, Ltd., Midea, Electrolux AB, Sharp Corporation, Haier Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightwave Microwave Oven Market Trends and Innovations
Active reshaping of this market centers on hardware-software convergence, regulatory-driven component redesign, and procurement model fragmentation that separates equipment ownership from cooking outcome guarantees.
Inverter magnetron technology with variable-frequency output control is rewriting the tradeoff between browning precision and energy throughput. Commercial kitchen operators in United States hospitality chains are adopting these units at replacement-cycle velocity, collapsing the distinction between premium built-in configurations and standard over-the-range offerings.
EU Ecodesign Directive standby-power thresholds are forcing power-supply architecture redesigns across export-bound product lines. Manufacturers serving European hospitality procurement must revalidate inverter and magnetron combinations against compressing allowable idle-state consumption, with combination-technology categories absorbing the steepest compliance engineering burden.
Buyers in United States quick-service restaurant chains are fragmenting procurement decisions between equipment finance vehicles and cooking-outcome service contracts. Channel intermediaries face disintermediation pressure as national home-improvement retailers and direct manufacturer relationships capture specification influence previously held by regional distributors.
Lightwave Microwave Oven Market Segmentation
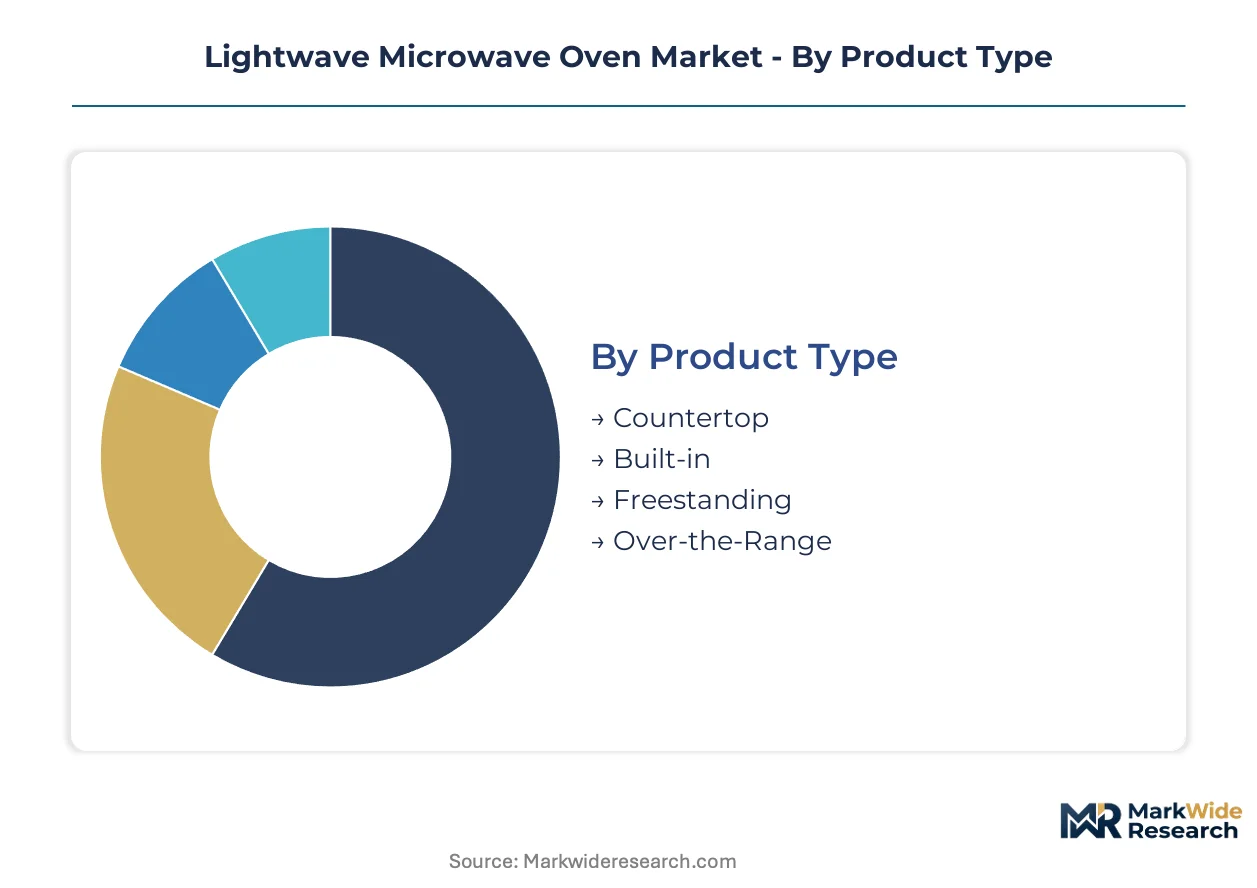
Segmentation in the lightwave microwave oven market reveals how procurement priorities diverge between cost-conscious residential buyers and durability-focused commercial operators. These splits determine where manufacturers concentrate R&D investment and which distribution channels capture margin.
Product Type:
Countertop buyers prioritize portability and entry pricing, while built-in purchasers value aesthetic integration and resale premiums in property transactions.
- Countertop:Freestanding units operating across 800–1,250 watts dominate rental markets and apartment turnover cycles. Demand concentrates in United States multi-unit residential construction where tenant-owned appliances bypass landlord capital constraints and NSF certification requirements.
- Built-in:Cabinet-integrated configurations with trim-kit finishes anchor premium kitchen renovations. United States quick-service restaurant buildouts sustain above-average replacement rates as chains refresh front-of-house appearances to compete with fast-casual rivals.
- Freestanding:Full-height units with storage drawers serve budget hospitality renovations where equipment flexibility outweighs permanent installation.
- Over-the-Range:Ventilation-combined installations capture kitchen footprint efficiency in compact commercial layouts and urban residential units.
Countertop leads volumes today; built-in is gaining share fastest.
Technology:
Technology choice determines whether buyers accept single-function limitations or pay premiums for menu versatility in constrained kitchen footprints.
- Convection:Forced-air circulation systems achieve thermal uniformity through 1,200–1,800 watt heating elements. Commercial kitchens in United States hospitality chains adopt these units to collapse baking and roasting steps into microwave-adjacent workflows as labor costs tighten.
- Combination:Integrated microwave-radiant systems pair magnetron output with 1,000–1,500 watt halogen or quartz elements for browning. United States fast-casual procurement favors these configurations for speed-to-plate advantages against conventional thermal equipment.
- Grill:Dedicated radiant elements without convection airflow serve price-sensitive buyers seeking limited browning capability.
- Solo:Pure microwave radiation without supplementary heating maintains lowest entry pricing for replacement cycles in budget residential channels.
Solo technology retains the largest installed base; combination configurations are expanding most quickly.
End User:
End-user segmentation separates buyers who prioritize upfront cost from those who weight total cost of ownership through service-contract availability.
- Commercial:Hospitality and foodservice operators demand NSF certification, stainless-steel construction, and 24-hour service response. Procurement concentrates in United States restaurant chains where renovation cycles align with franchise agreement renewals.
- Residential:Homeowners and renters evaluate warranty terms, aesthetic finish options, and smart-kitchen platform compatibility alongside wattage specifications.
- Institutional:School districts, healthcare facilities, and correctional systems prioritize repair-over-replace strategies and standardized parts availability across multi-site footprints.
- Hospitality:Hotels and extended-stay properties specify compact configurations for in-room kitchenettes with minimal training requirements for housekeeping staff.
Residential channels move the highest unit volumes; commercial segments capture steeper margin pools.
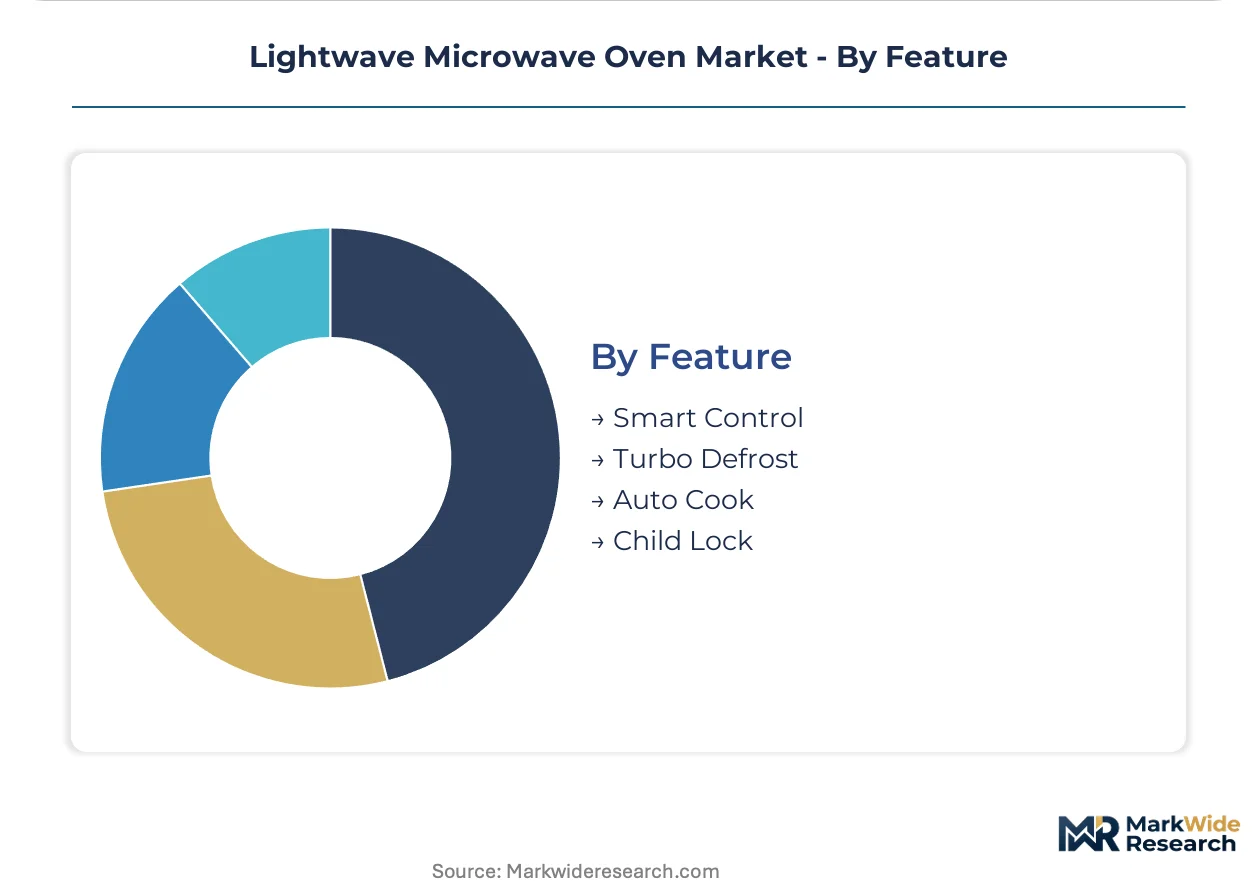
Feature:
Feature differentiation increasingly determines whether buyers perceive sufficient value to trade up from basic configurations or defer replacement.
- Smart Control:WiFi-enabled modules with app integration and voice-assistant compatibility require FCC recertification when hardware revisions trigger renewed electromagnetic testing. United States residential buyers in connected-home ecosystems show willingness to pay connectivity premiums.
- Turbo Defrost:Inverter-driven variable power delivery reduces thawing time without partial cooking at edges. Commercial kitchens value cycle-time compression during prep-hour rushes.
- Auto Cook:Preprogrammed sensor algorithms adjust time and power based on humidity detection and weight estimation.
- Child Lock:Control-panel disablement mechanisms address liability concerns in institutional settings and family residential environments.
Auto Cook functionality remains most commonly specified; smart control integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lightwave microwave oven technology first achieved commercial scale in Japan during the 1980s, with Japanese manufacturers pioneering the integration of halogen radiant elements into microwave cavities for accelerated browning and crisping functionality.
United States
Quick-service restaurant buildout cycles and multi-unit residential renovation waves sustain replacement demand for built-in and over-the-range configurations. The US Department of Energy standby-power thresholds compress allowable idle-state consumption, forcing inverter magnetron redesigns. Chicago and Dallas-Fort Worth metropolitan clusters concentrate commercial kitchen equipment procurement for hospitality chains.
Japan
Domestic demand for compact combination-technology units remains elevated in urban residential markets with constrained kitchen footprints. METI energy-efficiency benchmarks shape magnetron and power-supply architecture roadmaps for export-bound product lines. Osaka-Kobe industrial corridor hosts concentrated appliance manufacturing and component supplier networks.
Germany
Commercial hospitality procurement prioritizes EU Ecodesign Directive compliance and REACH-certified material sourcing for durability-focused installations. The country's national energy regulator enforces standby-power thresholds that exceed baseline EU requirements. Bavaria's manufacturing belt concentrates precision electronics production for inverter control systems.
South Korea
Smart-kitchen platform integration drives residential replacement cycles among connected-home ecosystem adopters. The Ministry of Trade, Industry and Energy (METI-equivalent) sets domestic efficiency standards that anticipate international regulatory convergence. Seoul Capital Area anchors both consumer demand concentration and corporate R&D headquarters for major appliance manufacturers.
China
Export manufacturing bases dominate high-frequency power component production for global OEM supply chains. GB standards and MIIT regulations govern domestic product certification while dual carbon goals accelerate inverter adoption for energy-intensity reduction. Yangtze River Delta and Pearl River Delta clusters concentrate magnetron and power electronics assembly capacity.
Lightwave Microwave Oven Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology-integration and distribution-capture dimensions, with the former commanding specification influence in commercial channels and the latter competing on entry pricing in residential replacement cycles. The vendor base organizes into three strategic archetypes: diversified electronics conglomerates with captive magnetron ecosystems, pure-play appliance manufacturers with captive retail relationships, and contract manufacturers serving private-label channels. Dominant competitive moves include smart-kitchen platform convergence for recurring-revenue capture and modular accessory bundling to recalibrate total cost of ownership calculations.
Within the diversified-electronics tier, LG Electronics and Samsung Electronics exemplify vertically integrated competitors with inverter magnetron ecosystems and software platform capabilities. Whirlpool Corporation anchors the pure-play appliance archetype through captive North American distribution relationships. Panasonic Corporation represents the precision-engineering specialist position with historical lineage in lightwave technology development.
| Leading Market Players |
|---|
| LG Electronics |
| Samsung Electronics |
| Whirlpool Corporation |
| Panasonic Corporation |
| Hitachi, Ltd. |
| Midea |
| Electrolux AB |
| Sharp Corporation |
| Haier Group |
| Others |
Pricing and Supply Chain Analysis
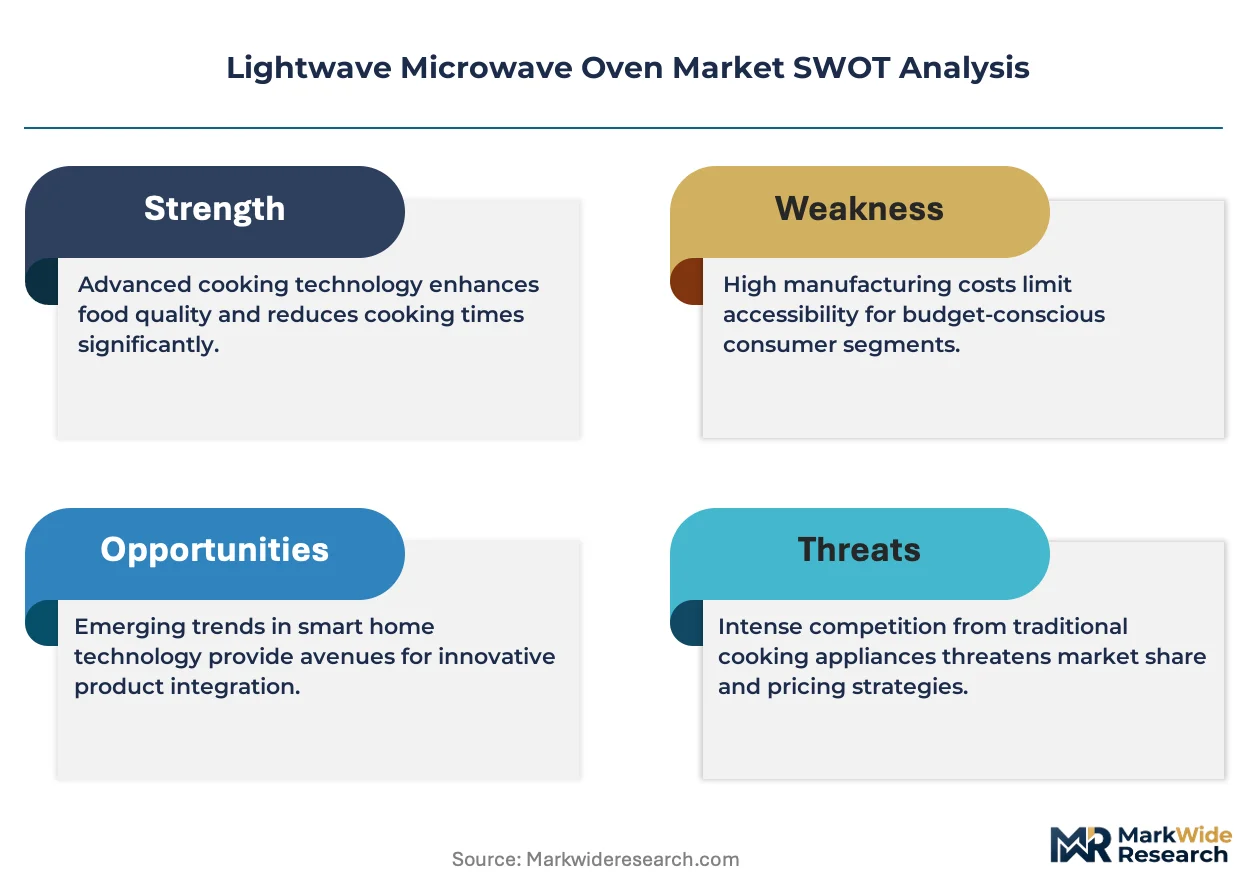
Certification-grade divergence between NSF-validated commercial units and uncertified residential imports manifests in pricing spreads exceeding three-to-one, while simultaneously concentrating magnetron sourcing in Asian manufacturing corridors and channeling distribution through distinct procurement hierarchies. This bifurcation compresses margin recovery timelines for mid-tier players caught between premium durability specifications and commodity price floors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transactions, with NSF certification and inverter magnetron precision separating commercial hospitality premiums from countertop economy tiers. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from Asian input cost volatility eroding standard-tier margins. Institutional buyers exhibit lowest price sensitivity due to repair-over-replace capital strategies, while multi-unit residential landlords face acute tenant-driven cost constraints.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing bases to North American distribution hubs has prompted regional buffer inventory expansion among hospitality procurement officers. Magnetron and power electronics assembly concentrates in China, South Korea, and Japan. Component sourcing draws from high-frequency power semiconductor foundries, halogen quartz element suppliers, and stainless-steel fabrication networks. Single-source vulnerability in magnetron supply exposes lead times to regional logistics disruption. Distribution runs through captive national home-improvement retail relationships and direct manufacturer contracts with hospitality chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through inverter magnetron cost-down curves and premium-tier displacement of solo-function units in commercial replacement cycles.
For Market Incumbents: To counter halogen-radiant convergence from diversified electronics conglomerates, pure-play appliance manufacturers should deepen backward integration into magnetron ecosystems and secure exclusive NSF certification pathways for combination-technology configurations. Channel control through captive national retailer relationships remains essential for specification influence in renovation-driven procurement. For New Entrants and Emerging Players: Launch via private-label contract manufacturing for multi-unit residential rental channels, where tenant-owned appliance turnover bypasses landlord capital constraints and NSF requirements. The countertop segment in United States apartment markets presents the most penetrable white-space, with smart-kitchen platform compatibility as the distinguishing go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where inverter engineering talent scarcity outpaces vocational training pipeline output in manufacturing hubs. Long-term viability favors precision-engineering specialists with historical lightwave technology lineage and established component supplier networks. The signal to watch is FCC wireless module recertification delays disrupting smart-control feature rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Magnetron Ecosystem Development | Captive supply of variable-frequency power components anchors premium positioning against commodity competitors. |
| Smart-Kitchen Platform Integration | Software-controlled meal-planning workflows with LG and Samsung ecosystems open recurring-revenue models. |
| NSF Certification Fast-Track Investment | Accelerated durability validation compresses margin windows before competitive obsolescence in hospitality channels. |
| EU Ecodesign Directive Alignment | REACH-compliant sourcing and standby-power optimization create export-ready platforms for European procurement. |
| Multi-Unit Residential Channel Penetration | Portable countertop configurations serve turnover-heavy apartment markets with minimal landlord capital deployment. |
Research Methodology
Direct dialogue with commercial kitchen equipment procurement officers, inverter power electronics engineers, national home-improvement retail category managers, and hospitality chain facility directors grounded qualitative insights. Secondary validation drew from US Department of Energy efficiency filings, FCC equipment authorization databases, EU Ecodesign Directive implementing measures, and customs trade records for magnetron component flows. Bottom-up unit shipment modeling and top-down value aggregation were cross-referenced for triangulation.
Bottom-up demand modeling by product type, technology category, end-user segment, and feature configuration was reconciled against top-down macroeconomic indicators across the analysis window. CAGRs were derived from regression analysis of historical replacement cycles and projected renovation velocity. Industry-specific forecast inputs included quick-service restaurant buildout pipelines and multi-unit residential construction permits.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to standby-power thresholds, geopolitical disruptions to Asian component supply corridors, and technological substitution by air-fryer convection systems. Forecasts reflect documented assumptions about replacement cycle timing and certification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Asia-Pacific Washing Machine Market
Appliances
North America Compact Dishwasher Market
Appliances
GCC Dishwashers Market
Appliances
United States Multi-Functional Oven Market
Appliances
Electric Kettle Market
Appliances
Egypt Dishwashers Market
Appliances
Smart Microwave Oven Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Small Electric Kettles Market
Appliances
Europe Induction Hobs Market
Appliances
Electric Hand Dryer Market
Appliances
Kuwait Microwave Ovens Market
Appliances
Vacuum Cleaner Market
Appliances
Refrigerated Cabinet Market
Appliances
Europe Garment Steamers Market
Appliances
Consumer Appliances Market