
 United States Contract Manufacturing Services Market | 2026-2036
United States Contract Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Contract Manufacturing Services Market Analytics
Digital thread integration across design-to-manufacturing workflows is fragmenting traditional monolithic production models into distributed, data-linked supplier networks. Jabil Inc. leverages its electronics assembly scale across multiple US sites to anchor high-volume consumer and automotive programs. Thermo Fisher Scientific Inc. sustains biopharma contract development dominance through integrated analytical and clinical supply services. Flex Ltd. competes on advanced manufacturing platforms that merge automation with real-time supply chain orchestration.
Contract manufacturing services encompass third-party production execution where external firms assume fabrication, assembly, testing, or packaging functions under client specifications, typically governed by ISO 13485 quality systems for medical applications or IPC-A-610 standards for electronics. The primary purpose is to convert fixed production costs into variable operating expenditures while accessing specialized process capabilities without capital deployment. Pharmaceutical product types command premium margin pools due to validation complexity and regulatory audit intensity, while electronic components represent the highest volume throughput segment driven by consumer electronics refresh cycles. On-demand manufacturing delivery models are expanding fastest among mid-tier OEMs seeking to compress inventory exposure, though lean manufacturing retains structural dominance in automotive and industrial equipment verticals where just-in-time coordination remains mandatory.
FDA cGMP enforcement and ISO 13485 certification requirements shape medical device and pharmaceutical contract access, while NHTSA safety standards and EPA environmental compliance constrain automotive supplier qualification. OSHA workplace regulations and SEC disclosure obligations for public contract manufacturers add layered operational accountability across the sector. Stakeholders must monitor how IRA domestic content thresholds and reshoring tax credits reshape site economics against established Mexican and Asian supply alternatives.
Market Dynamics
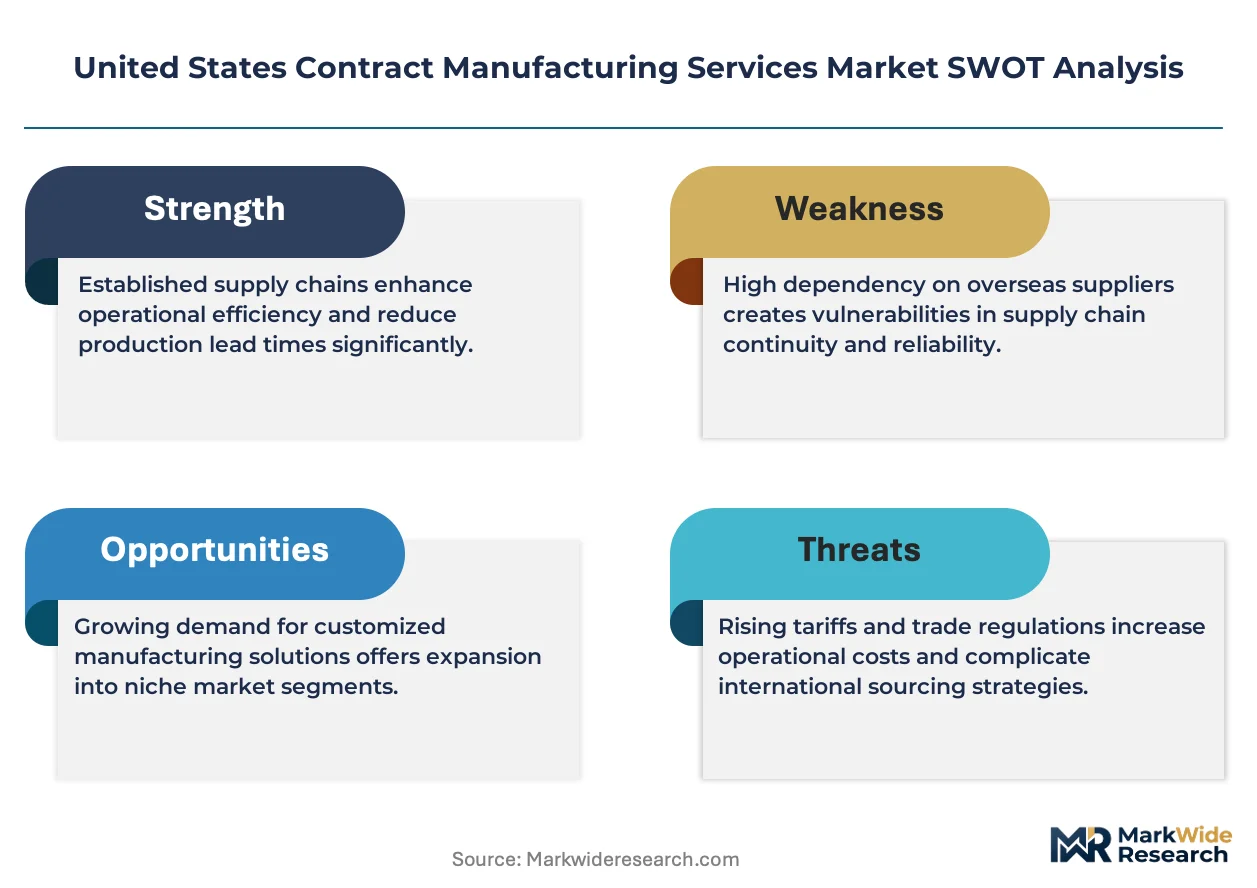
IRA domestic manufacturing incentives are redirecting pharmaceutical and electronics production capacity toward Michigan, Ohio, and Illinois, while FDA quality system regulations compress site qualification timelines for new contract entrants.
Growth Catalysts
- Biologics pipeline expansion:CDMOs capture rising outsourced demand for cell therapy and monoclonal antibody production as biopharma firms shed fixed manufacturing assets.
- Automotive electrification:Battery pack assembly contracts concentrate in the Great Lakes corridor where Tier 1 electronics assembly infrastructure overlaps with OEM final assembly proximity.
- Reshoring tax credits:IRA Section 45X advanced manufacturing credits reduce effective production costs for domestic pharmaceutical and semiconductor packaging operations.
Market Restraints
- Specialized labor scarcity:FDA cGMP-qualified technicians and IPC-A-610 certified electronics assemblers command wage premiums exceeding 40% above general manufacturing rates in Midwest industrial zones.
- Single-source API dependency:Active pharmaceutical ingredient supply concentrates among Indian and Chinese bulk manufacturers, exposing US-based formulation contractors to tariff and shipping disruption risk.
- Validation timeline compression:ISO 13485 medical device certification cycles extend 18-24 months, locking contract manufacturers into committed capacity before revenue recognition.
Strategic Opportunities
- Cell and gene therapy CDMO capacity:Viral vector manufacturing and plasmid DNA production remain undersupplied relative to clinical trial demand, creating first-mover margin pools.
- Texas and Arizona industrial corridors:Lower energy costs and right-to-work labor frameworks attract electronics and medical device assembly migration from legacy Midwest concentrations.
- Digital thread integration:Real-time production data exchange between OEM design systems and contract manufacturing execution systems enables on-demand lot sizing for mid-tier device makers.
Industry Challenges
- Automation retrofit capex burdens:Legacy automotive electronics assembly lines require $15-25 million per facility to achieve IPC-CFX connectivity standards for smart factory integration.
- Multi-site quality harmonization:FDA inspectional observations spike when contract manufacturers operate distributed production networks without unified electronic batch record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Contract Manufacturing Services Market |
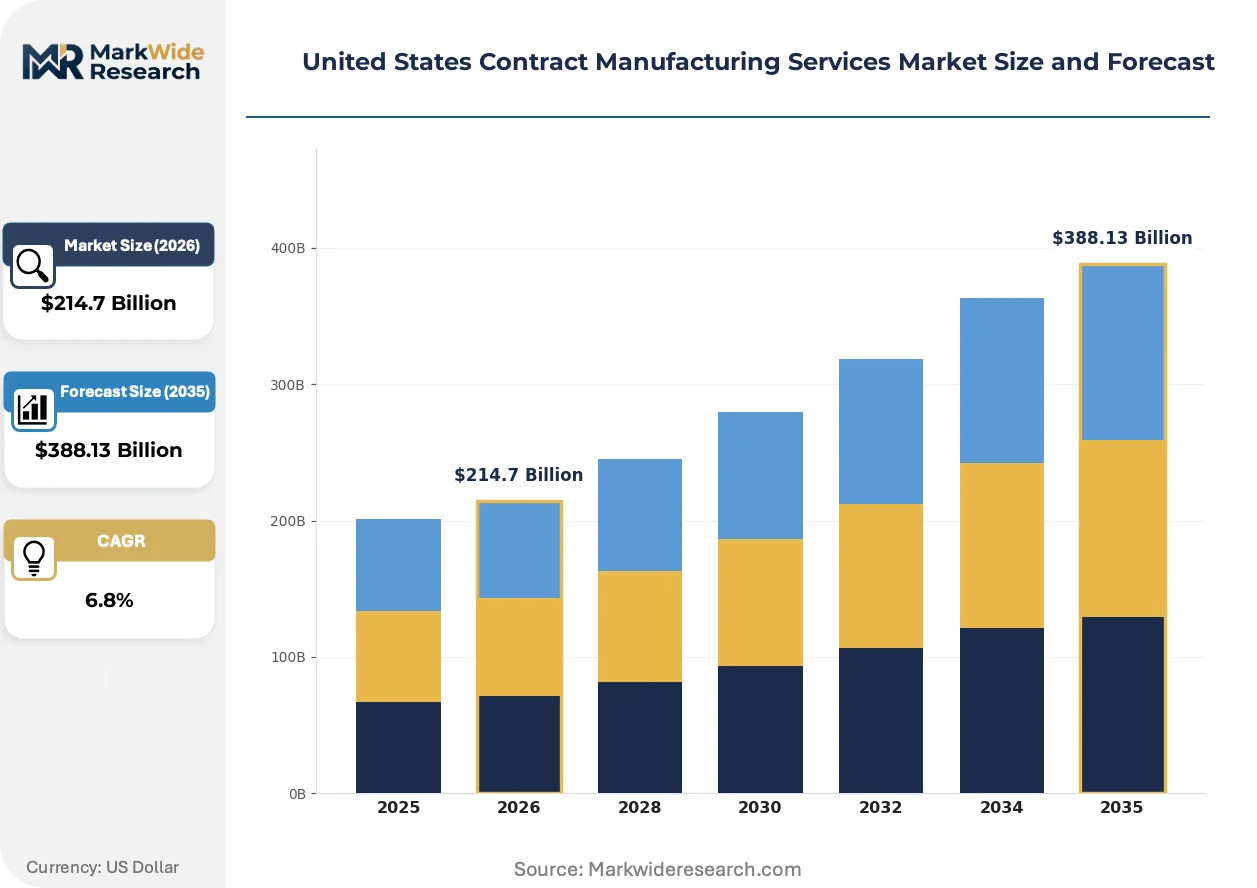
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Assembly Services, Packaging Services, Testing Services, Logistics Services Industry Vertical: Aerospace, Consumer Electronics, Healthcare, Automotive Product Type: Electronic Components, Medical Devices, Industrial Equipment, Pharmaceuticals Delivery Model: On-Demand Manufacturing, Lean Manufacturing, Batch Production, Prototype Services |
| Companies Covered | Catalent Pharma Solutions Inc., Lonza Group AG, Thermo Fisher Scientific Inc., Jabil Inc., Flex Ltd., Celestica Inc., Benchmark Electronics Inc., Proto Labs, Xometry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Contract Manufacturing Services Market Evolving Landscape
Production workflows are fragmenting into distributed, data-linked supplier networks as digital thread architectures replace monolithic manufacturing models. Three forces are actively reshaping competitive positioning in US contract manufacturing.
Digital twin simulation is hybridizing physical and virtual production environments for pharmaceutical process validation. Biopharma CDMOs deploy computational fluid dynamics modeling to predict mixing performance in single-use bioreactors before physical installation. FDA reviewers accept virtual evidence packages for prior-approval supplement filings, compressing technology transfer timelines from 12 months to 6 months for qualified facilities.
IRA domestic content thresholds are restructuring site economics for pharmaceutical and clean energy component manufacturing. Treasury Department guidance requires 40% North American content for full credit eligibility, pushing contract manufacturers toward US-based API finishing and packaging operations. Electronics assemblers in Michigan and Ohio requalify Mexican component suppliers to maintain cost position while satisfying origin documentation requirements.
OEM procurement organizations are consolidating supplier panels to reduce qualification overhead and audit burden. Medical device makers shrink active contract manufacturing relationships from 15-20 suppliers to 5-7 strategic partners per product category. Automotive electronics programs favor multi-year sole-source arrangements with Jabil and Flex over fragmented bidding across regional machine shops.
United States Contract Manufacturing Services Market Segmentation
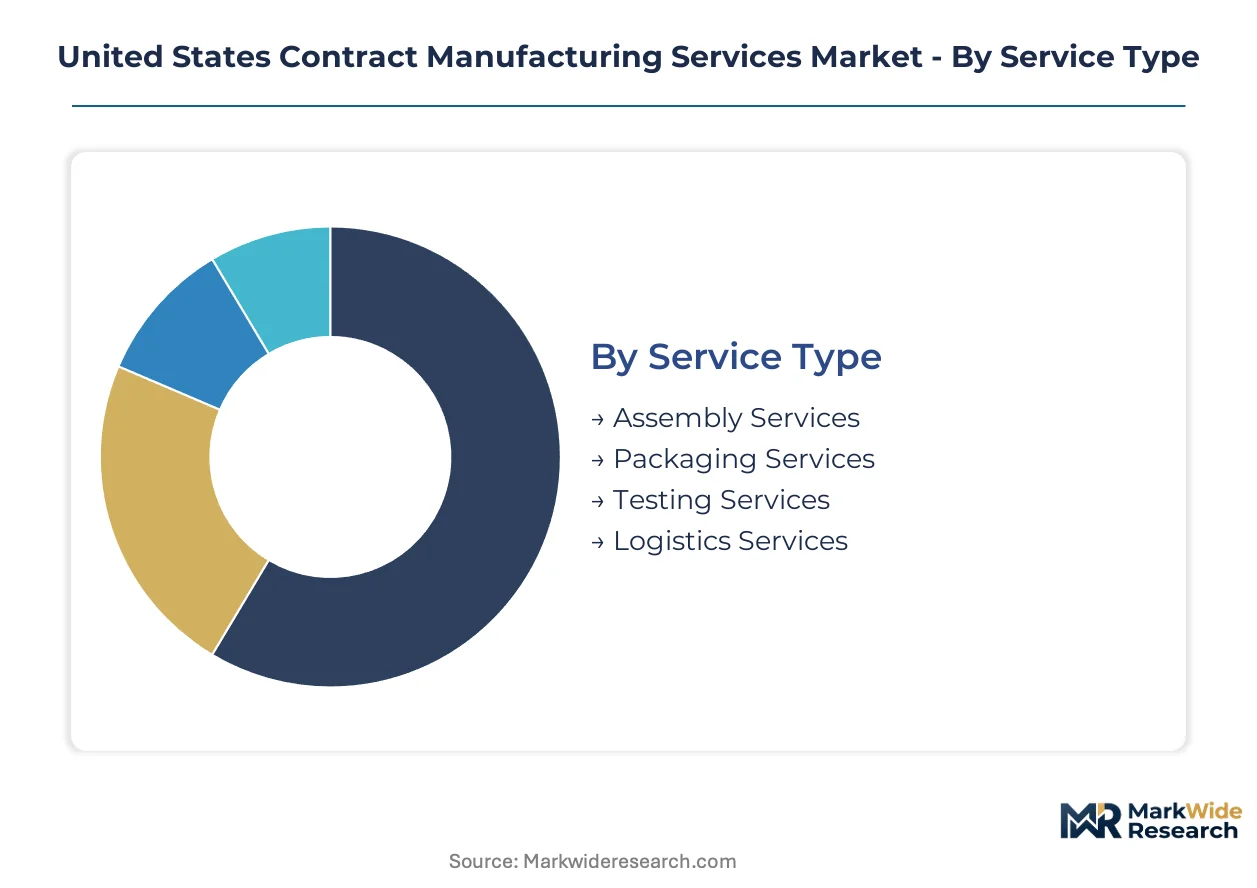
Segmentation reveals how contract manufacturing value pools concentrate across service capabilities and regulatory intensity. Each dimension exposes distinct margin structures, qualification barriers, and capital requirements that shape supplier selection criteria for OEM procurement teams.
Service Type:
Mature assembly and packaging operations anchor volume throughput, while testing and logistics services represent emerging margin expansion zones as quality assurance and supply chain orchestration complexity intensify.
- Assembly Services:Surface-mount and through-hole electronics assembly dominates contract manufacturing revenue, driven by automotive electrification programs in Michigan and Ohio industrial corridors. IPC-A-610 certification requirements filter out mid-tier competitors from high-reliability aerospace and medical device contracts.
- Packaging Services:Primary and secondary packaging for pharmaceuticals commands premium pricing due to FDA serialization mandates and cold-chain validation protocols. Demand concentrates among CDMOs serving biologics pipelines where container closure integrity directly impacts shelf-life claims.
- Testing Services:In-circuit and functional testing for automotive electronics.
- Logistics Services:Kitting and vendor-managed inventory programs for industrial OEMs.
Assembly Services retains volume leadership; Testing Services holds the steepest expansion curve.
Industry Vertical:
Cost tier differentiation separates capital-heavy automotive and aerospace programs from consumer electronics volume plays, with healthcare occupying the premium certification tier that commands 40-60% margin premiums over industrial benchmarks.
- Aerospace:AS9100-certified precision machining and avionics assembly for defense and commercial aircraft programs. FAA production approval requirements extend qualification cycles to 24-36 months, locking incumbent suppliers into long-term sole-source positions.
- Healthcare:ISO 13485 medical device manufacturing and pharmaceutical formulation services. FDA inspectional intensity and MDR compliance for European market access create defensive moats around established Great Lakes and New England contract manufacturers.
- Automotive:Battery pack assembly and power electronics integration for EV platforms.
- Consumer Electronics:High-volume smartphone and wearable assembly with compressed product lifecycles.
Healthcare commands the steepest pricing tier; Automotive shows the most aggressive capacity expansion.
Product Type:
Supply concentration patterns differentiate commodity electronic components from validated medical and pharmaceutical products where regulatory audit trails determine market access.
- Pharmaceuticals:Small-molecule formulation and biologics manufacturing under FDA cGMP. IRA domestic manufacturing incentives redirect sterile injectable and oral solid dose capacity toward Illinois and North Carolina facilities to capture Section 45X tax credits.
- Medical Devices:Class II and III device assembly requiring ISO 13485 quality systems and FDA establishment registration. Demand clusters in Minnesota and Massachusetts where OEM engineering proximity accelerates design transfer timelines.
- Electronic Components:Printed circuit board assembly and semiconductor packaging.
- Industrial Equipment:Motor drives, sensors, and automation hardware.
Electronic Components retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
Delivery Model:
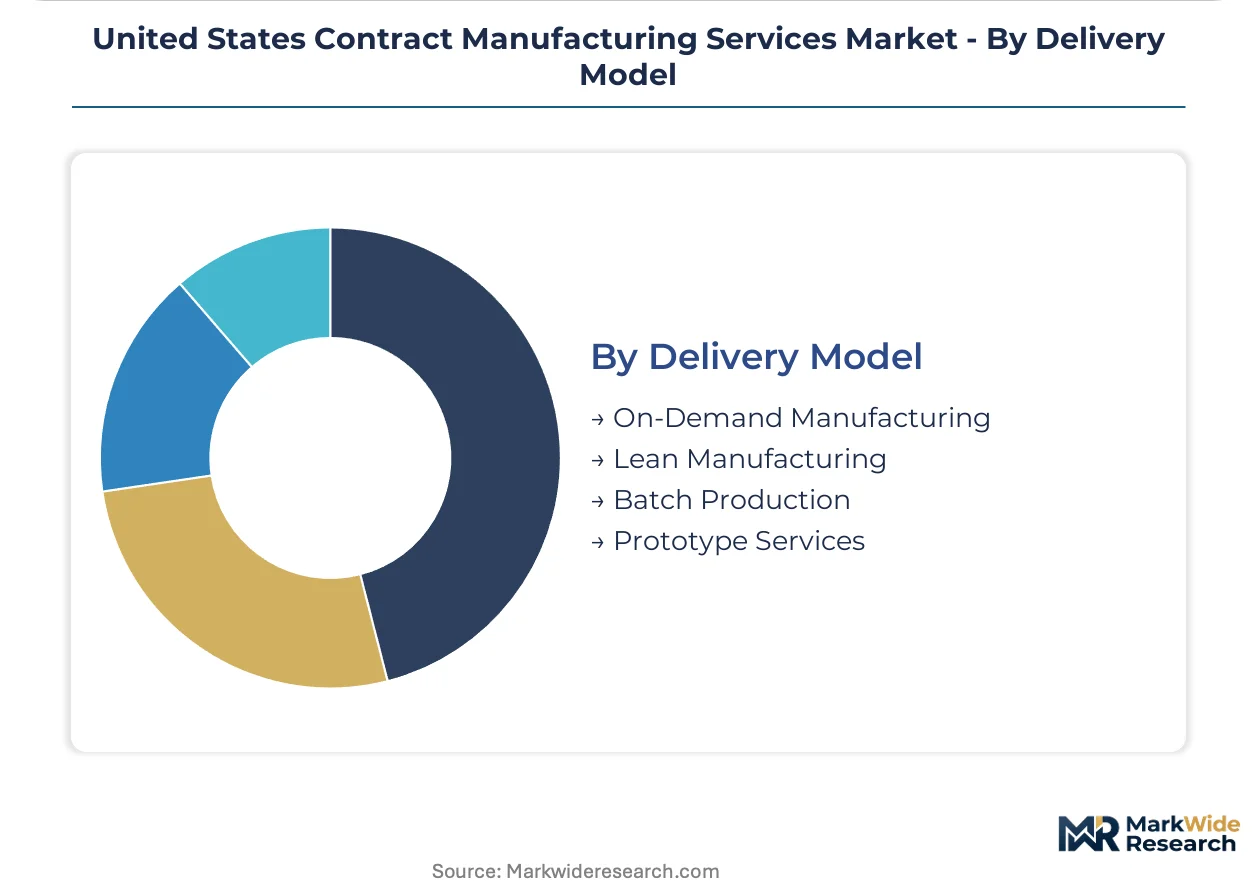
Customer type stratification separates enterprise OEMs demanding lean manufacturing partnerships from mid-tier device makers adopting on-demand models to minimize inventory exposure.
- Lean Manufacturing:Just-in-time production coordination with automotive and industrial OEMs requiring daily milk-run delivery schedules. Jabil and Flex anchor multi-year agreements with Tier 1 suppliers where kanban inventory systems mandate geographic proximity to final assembly plants.
- On-Demand Manufacturing:Digital thread-enabled lot sizing for medical device startups and industrial IoT hardware companies. Real-time quoting platforms compress procurement cycles from weeks to days, though FDA validation requirements limit adoption in pharmaceutical applications.
- Batch Production:Campaign-based pharmaceutical and specialty chemical manufacturing.
- Prototype Services:NPI acceleration for consumer electronics and medical device development programs.
Lean Manufacturing retains volume leadership; On-Demand Manufacturing shows the most rapid adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive and biopharma OEM procurement teams concentrate contract manufacturing demand across distinct industrial corridors, with site selection driven by IRA tax credit eligibility, FDA inspection proximity, and Tier 1 supplier density.
Great Lakes Corridor
Michigan, Ohio, and Illinois anchor battery pack assembly and power electronics integration for Detroit Three electrification programs. IRA Section 45X credits reduce effective production costs for domestic pharmaceutical packaging operations. Cleveland and Detroit suburbs concentrate FDA-registered medical device contract manufacturers serving Midwestern OEM engineering centers.
Southeast Industrial Belt
North Carolina and Georgia attract sterile injectable formulation capacity as CDMOs chase IRA domestic content thresholds for biologics finishing. FDA's Research Triangle Park inspection office accelerates site qualification timelines for new entrants. RTP-Durham clusters viral vector manufacturing startups alongside established pharmaceutical contract development networks.
Texas and Arizona Corridors
Right-to-work labor frameworks and lower industrial electricity rates draw electronics assembly migration from legacy Midwest concentrations. Mexican maquiladora component suppliers requalify under USMCA origin rules to maintain cost position for border-adjacent contract manufacturers. Phoenix and Austin suburbs host semiconductor packaging operations serving defense and aerospace prime contractors.
New England Medical Device Cluster
Massachusetts and Minnesota concentrate ISO 13485-certified assembly for Class II and III devices where OEM engineering proximity compresses design transfer cycles. FDA's Boston district office maintains elevated inspectional intensity that reinforces defensive moats around established contract manufacturers. Minneapolis-St. Paul and Greater Boston anchor precision machining and catheter assembly for cardiovascular and orthopedic device pipelines.
Pacific Northwest Technology Corridor
Washington and Oregon host high-mix, low-volume electronics assembly for aerospace and industrial automation OEMs. IPC-A-610 certification requirements filter mid-tier competitors from avionics contracts serving Boeing's Puget Sound engineering base. Portland suburbs concentrate automated test equipment integration for semiconductor capital equipment manufacturers.
United States Contract Manufacturing Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata where scale economies, regulatory certification depth, and geographic proximity to OEM final assembly plants determine contract awards. Consolidation pressures intensify as medical device makers shrink supplier panels from fifteen to seven active relationships per product category. Three archetypes dominate: diversified electronics assemblers with multi-site North American footprints, integrated biopharma CDMOs combining analytical and clinical supply services, and digital-native on-demand platforms serving mid-tier hardware startups. Capacity expansion and M&A activity concentrate among Great Lakes and Southeast corridors where IRA incentives reshape site economics.
Within the integrated biopharma CDMO tier, Thermo Fisher Scientific Inc. and Catalent Pharma Solutions Inc. exemplify the regulatory-scale archetype. Among diversified electronics assemblers, Jabil Inc. and Flex Ltd. occupy positions where automotive electrification programs demand IPC-CFX connectivity standards and real-time supply chain orchestration. Lonza Group AG represents the Swiss-headquartered specialist model with US-based cell therapy manufacturing assets.
| Leading Market Players |
|---|
| Catalent Pharma Solutions Inc. |
| Lonza Group AG |
| Thermo Fisher Scientific Inc. |
| Jabil Inc. |
| Flex Ltd. |
| Celestica Inc. |
| Benchmark Electronics Inc. |
| Proto Labs |
| Xometry |
| Others |
Value Network & Pricing Analysis
Cleveland's FDA-registered medical device manufacturing cluster concentrates sterile injectable formulation capacity, translating into asymmetric pricing power for ISO 13485-certified contractors serving Midwestern OEM engineering centers. Battery pack assembly lines in Michigan and Ohio command cost-plus premiums indexed to copper and lithium carbonate spot markets, while electronics assemblers face margin compression from Mexican maquiladora competition under USMCA rules.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate pharmaceutical and automotive electronics segments, linking final pricing to copper, lithium carbonate, and active pharmaceutical ingredient benchmarks. Price differentiation rests on FDA cGMP certification tier and IPC-A-610 quality grade, with medical device contracts commanding 40-60% premiums over industrial assembly benchmarks. Pricing pressure stems from IRA domestic content thresholds forcing US-based API finishing despite higher labor costs. Mid-tier OEMs exhibit highest price sensitivity, while biopharma firms prioritize validation speed over unit economics.
Supply Chain Analysis
Upstream active pharmaceutical ingredient feedstock draws from Indian and Chinese bulk manufacturers, exposing US-based formulation contractors to tariff and shipping disruption risk. Electronic components rest on Taiwanese semiconductor packaging and Mexican cable harness assembly. Single-source API dependency creates structural vulnerability when FDA import alerts trigger supply interruptions. Distribution runs through Tier 1 supplier milk-run networks anchored to Detroit Three final assembly plants and RTP-Durham biopharma clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technician scarcity across FDA cGMP and IPC-A-610 certification tiers is compressing site qualification timelines and inflating wage premiums beyond 40% above general manufacturing rates in Midwest industrial zones. This capability gap rewards first-movers who secure certified labor pipelines before competitors.
For Market Incumbents: Build regulatory-scale moats through unified electronic batch record systems across distributed production networks. Consolidate supplier panels from fifteen to seven active relationships per product category to reduce audit burden and capture sole-source premiums. Defend against digital-native on-demand platforms by embedding real-time production data exchange into multi-year automotive and medical device agreements. For New Entrants and Emerging Players: Pursue viral vector manufacturing and plasmid DNA production capacity in the Southeast Industrial Belt where FDA's Research Triangle Park inspection office accelerates site qualification. Target Texas and Arizona electronics assembly corridors where right-to-work frameworks and lower energy costs undercut legacy Midwest concentrations. Lead with digital thread-enabled on-demand quoting platforms to compress procurement cycles for mid-tier industrial IoT hardware companies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated biopharma CDMOs combining analytical and clinical supply services over pure-play assembly operations. Long-term viability hinges on IRA tax credit eligibility and domestic content threshold compliance across the projection horizon. Acquire cell and gene therapy manufacturing assets with viral vector capabilities. Watch FDA inspectional observation trends as inflection indicator for multi-site quality harmonization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Thread Integration | Real-time data exchange between OEM design systems and contract manufacturing execution systems compresses technology transfer timelines for qualified facilities. |
| IRA Domestic Content Compliance | Treasury Department 40% North American content thresholds reshape site economics toward US-based API finishing and packaging operations. |
| Cell Therapy CDMO Capacity Buildout | Viral vector manufacturing and plasmid DNA production remain undersupplied relative to clinical trial demand, creating first-mover margin pools. |
| Multi-Site Quality Harmonization | Unified electronic batch record systems reduce FDA inspectional observations in distributed production networks. |
| IPC-CFX Smart Factory Retrofit | Legacy automotive electronics assembly lines require connectivity standards investment to anchor high-volume electrification programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biopharma outsourcing executives, FDA regulatory affairs leads, Tier 1 automotive procurement managers, and contract manufacturing site directors. Secondary validation drew from FDA establishment registration databases, SEC 10-K filings, IRA Treasury guidance documents, and IPC industry certification records. Bottom-up capacity assessments across Great Lakes and Southeast corridors were triangulated against top-down OEM spend analysis.
Calibration against historical capacity expansion patterns and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service capability tier, regulatory intensity grade, industry vertical, and geographic production cluster proximity to OEM final assembly. CAGRs were derived from supply-demand balance analysis incorporating IRA incentive phase-in schedules and FDA inspection resource constraints.
Sensitivities concentrate around IRA domestic content threshold enforcement, FDA cGMP inspection backlogs, and single-source API supply interruptions. Forecasts reflect documented assumptions regarding labor certification pipeline expansion and battery pack assembly capacity ramp rates. Cross-checking against Customs and Border Protection import volume data and FDA warning letter issuance trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Interactive Projector Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Chile ICT Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Global Mesh App and Service Architecture Market